
 Global Cardiovascular Ultrasound System Market | 2026-2036
Global Cardiovascular Ultrasound System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiovascular Ultrasound System Market Foresight
Software-defined imaging analytics is pivoting how cardiovascular ultrasound value gets captured, shifting revenue from hardware transactions toward recurring diagnostic intelligence subscriptions. GE Healthcare leverages its Edison platform to anchor AI-augmented echocardiography workflows across integrated delivery networks. Koninklijke Philips N.V. sustains R&D intensity in autonomous cardiac quantification, while Siemens Healthineers AG competes through its digital twin integration for real-time hemodynamic modeling.
A cardiovascular ultrasound system employs high-frequency sound waves, typically 2-15 MHz, to generate real-time images of cardiac structures, valve motion, and blood flow dynamics for non-invasive diagnosis of structural and functional heart disease. Cart-based systems dominate installed base revenue due to premium transducer arrays and full diagnostic suites, yet handheld ultrasound represents the fastest-expanding segment as emergency departments and rural clinics prioritize mobility over comprehensive feature sets. Doppler imaging technology occupies the largest share of procedure volume, though 3D and 4D imaging modalities command superior reimbursement tiers in complex congenital defect screening and surgical planning workflows.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and clinical evidence burdens for manufacturers seeking market access in the United States and European Union, while China's NMPA accelerates review timelines for AI-assisted diagnostic features under its innovative medical device fast-track program. ISO 13485 quality management standards and IEC 60601-2-24 safety specifications govern manufacturing consistency across all major supply jurisdictions. Stakeholders must monitor how divergent regulatory post-market surveillance obligations in the United States, Germany, and China reshape service attach rates and software update deployment economics.
Market Dynamics
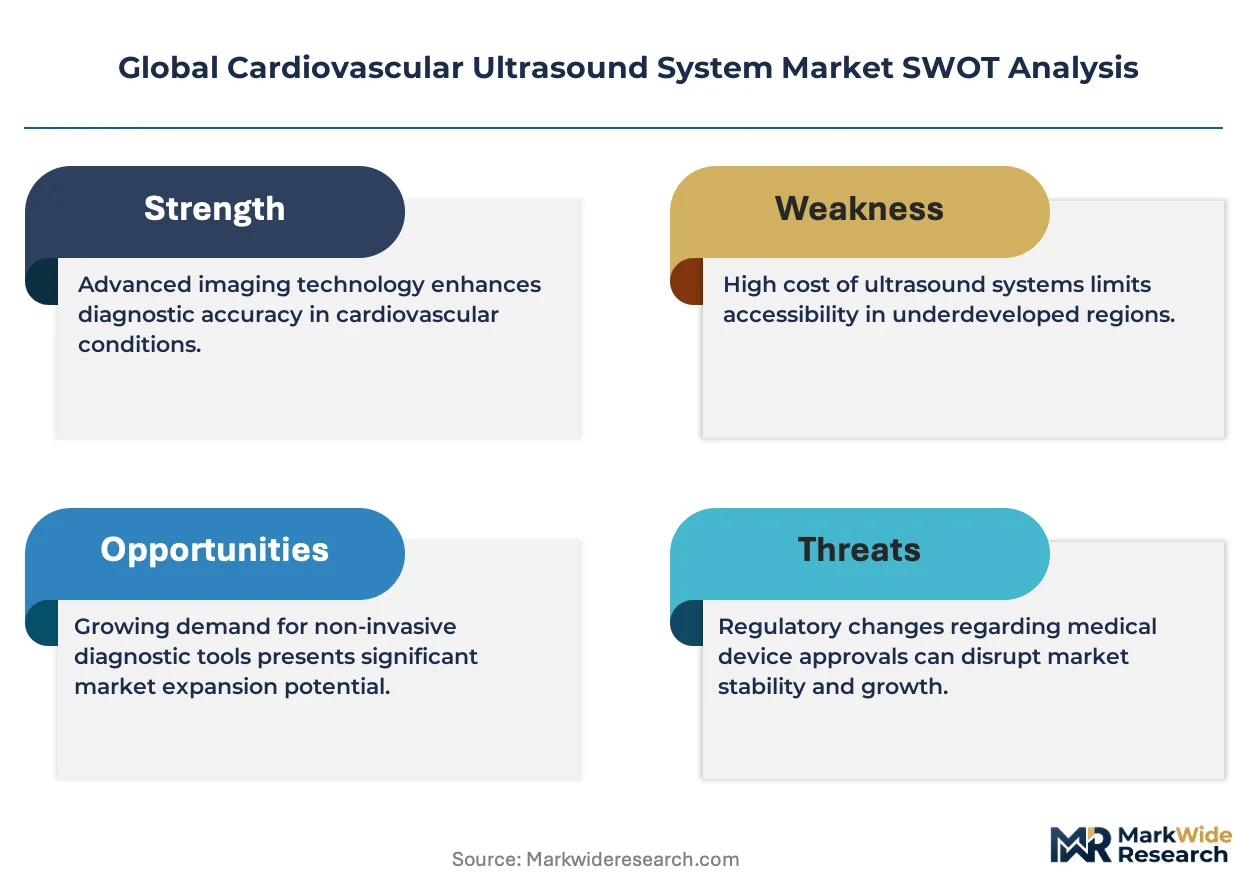
Software-defined imaging architectures are compressing hardware refresh cycles while elevating recurring revenue from AI-augmented diagnostic workflows, fundamentally restructuring how value accrues across the cardiovascular ultrasound value chain.
Growth Catalysts
- China NMPA Fast-Track:Accelerated review timelines for AI-assisted diagnostic features under the innovative medical device program compress time-to-revenue for algorithm-enabled systems.
- Point-of-Care Expansion:Emergency departments and rural clinics prioritize handheld mobility over comprehensive cart-based suites, expanding addressable procedure volume beyond traditional cardiology suites.
- Cloud-Based Platforms:Integrated delivery networks deploy remote image interpretation and centralized quality assurance, reducing specialist travel burden and enabling asynchronous diagnostic workflows.
Market Restraints
- EU MDR Conformity Burden:Enhanced clinical evidence requirements and notified body capacity constraints extend product development timelines and elevate regulatory compliance costs for European market access.
- Premium Transducer Supply Concentration:Piezoelectric crystal fabrication and advanced array manufacturing concentrate among specialized component suppliers, creating input bottlenecks for high-end system production.
- Optical Coherence Tomography Substitution:Intravascular imaging alternatives capture share in coronary plaque characterization applications where acoustic resolution limits diagnostic certainty.
Strategic Opportunities
- India Tier-II/Tier-III Penetration:Underpenetrated secondary cities and district hospitals present whitespace for portable system deployment as cardiac care infrastructure expands beyond metropolitan centers.
- 3D/4D Reimbursement Tiers:Complex congenital defect screening and surgical planning workflows command superior reimbursement codes, creating margin expansion opportunity for advanced modality vendors.
- ISO 13485 + IEC 60601 Harmonization:Converging quality management and safety standards across United States, European Union, and Asia-Pacific jurisdictions enable single-source manufacturing for multi-regional distribution.
Industry Challenges
- Sonographer Workforce Scarcity:Specialized echocardiography training programs produce insufficient certified operators to match system deployment rates, constraining effective utilization of installed base capacity.
- Legacy PACS Integration Friction:Hospital information systems and departmental archives built on disparate data standards impede seamless AI workflow embedding and cloud connectivity deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiovascular Ultrasound System Market |
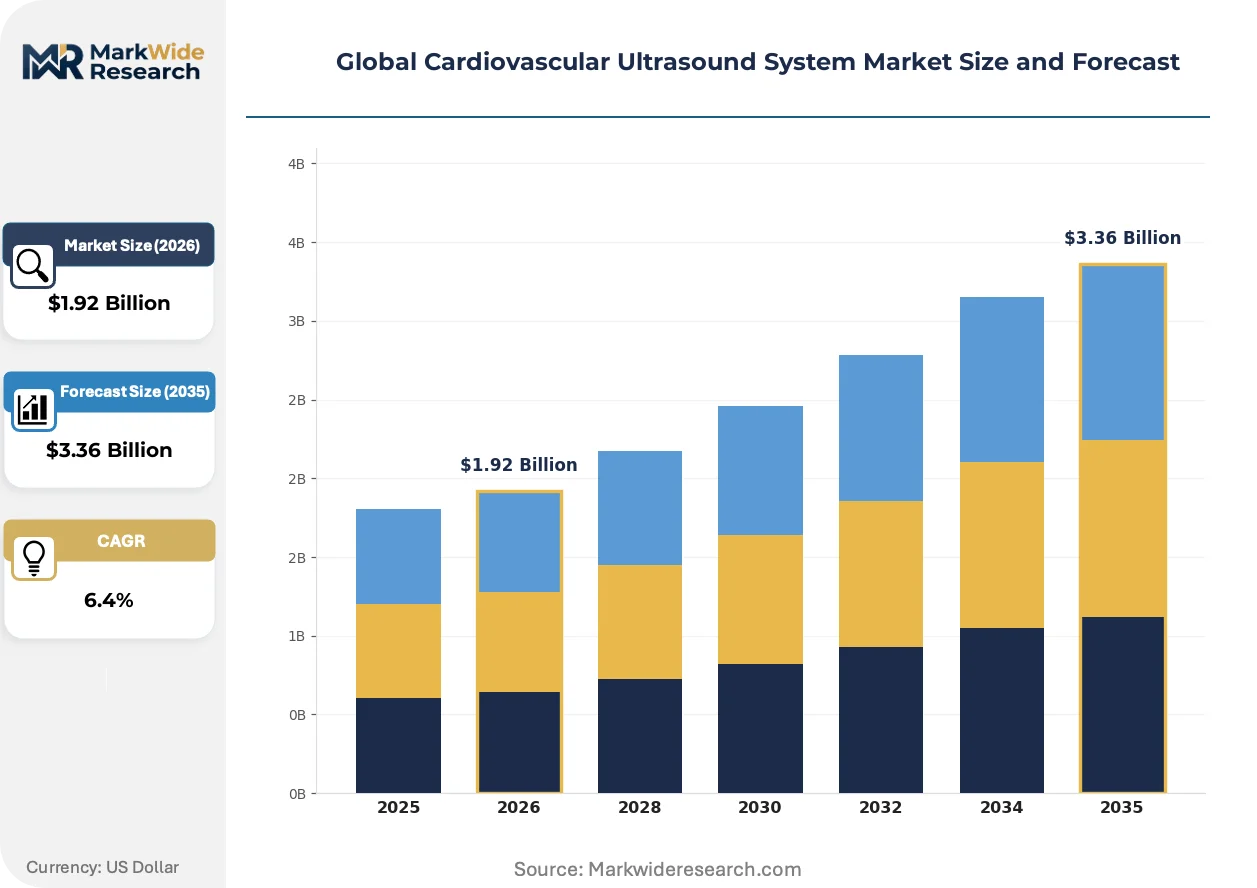
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Cart-Based Ultrasound, Handheld Ultrasound, Laptop-Based Ultrasound Technology: Doppler Imaging, 2D Imaging, 3D Imaging, 4D Imaging, Speckle Tracking Application: Cardiac Assessment, Vascular Diagnostics, Pericardial Evaluation, Congenital Defect Screening, Cardiac Stress Testing End User: Cardiology Clinics, Diagnostic Centers, Ambulatory Surgery Centers, Research Institutes, Universities |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers AG, Canon Medical Systems, FUJIFILM Holdings Corporation, Mindray Medical International Limited, Samsung Medison Co., Ltd., Hitachi Medical Corporation, Esaote SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiovascular Ultrasound System Market Shifts & Advancements
Artificial intelligence is embedding directly into image acquisition and interpretation pipelines, compressing the gap between raw ultrasound data and diagnostic decision support while enabling less specialized operators to perform complex cardiac assessments.
Autonomous cardiac quantification algorithms are integrating real-time chamber segmentation and ejection fraction calculation into standard imaging protocols. Community hospitals and ambulatory surgical centers adopt these capabilities to reduce dependence on subspecialist interpretation. The technology is integrating previously discrete analysis steps into continuous acquisition workflows, collapsing the time between image capture and structured report generation.
EU MDR post-market surveillance obligations are intensifying clinical follow-up requirements and periodic safety reporting for active implantable and diagnostic devices. Manufacturers must maintain robust vigilance systems and risk management documentation throughout product lifecycles. High-risk device categories face expanded notified body audit frequency, compressing margin structures for vendors with legacy quality management architectures.
Subscription-based diagnostic intelligence is displacing perpetual software licenses and bundled service contracts across integrated delivery networks. Health systems in Germany and the United States prioritize per-procedure or per-patient analytics pricing over capital-intensive upfront commitments. This consumption-pattern shift aligns vendor incentives with clinical outcome metrics and system utilization rates rather than hardware shipment volume.
Global Cardiovascular Ultrasound System Market Segmentation
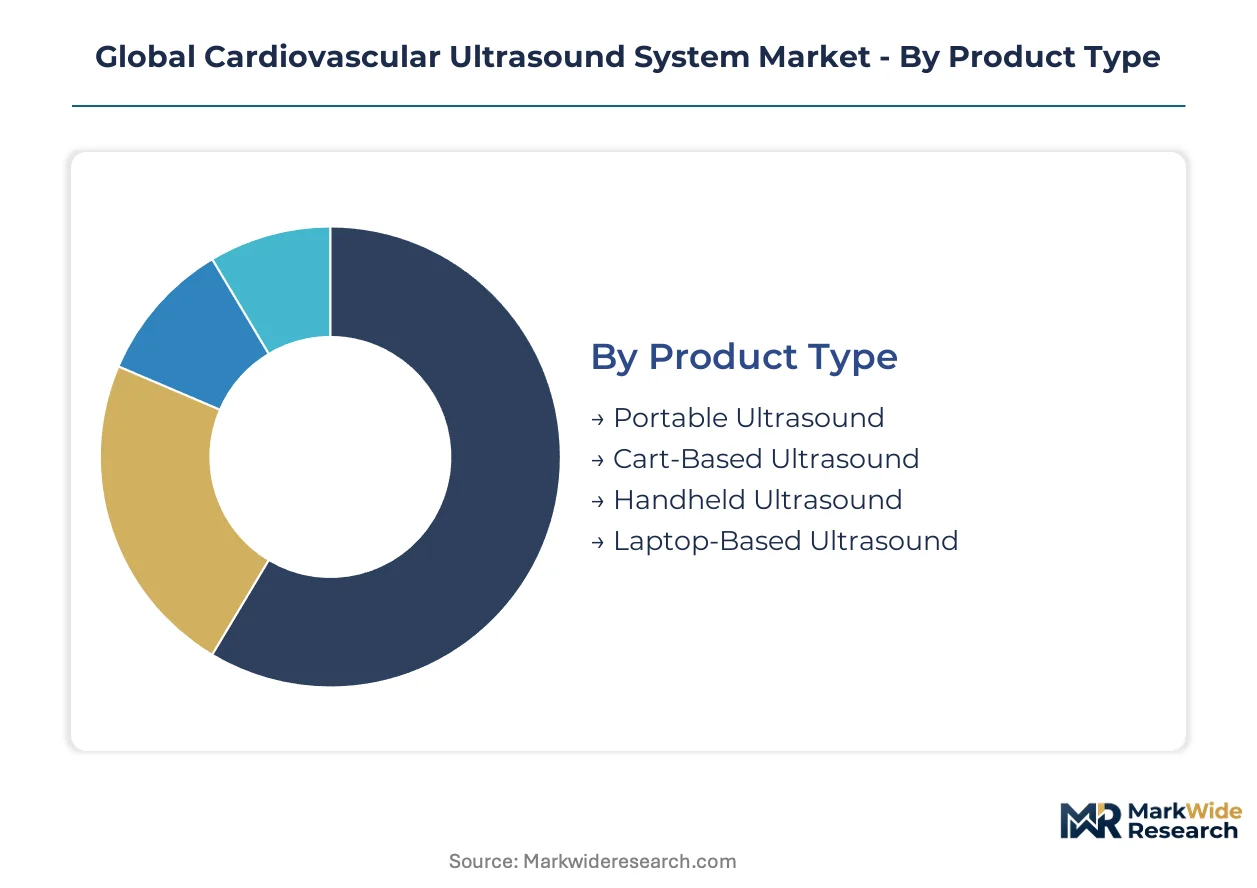
Cardiovascular ultrasound systems fragment across four interlocking dimensions that determine procurement workflows and margin capture. Product form factors dictate capital deployment patterns, while imaging modalities shape reimbursement eligibility and clinical utility across care settings.
Product Type:
Standardization dominates at the high end, with customization emerging at the portable periphery where battery life and wireless protocols vary by deployment context.
- Cart-Based Ultrasound:Full diagnostic suites with premium transducer arrays and comprehensive measurement packages anchor hospital cardiology departments. Demand concentrates in the United States and Germany where integrated delivery networks prioritize workflow efficiency and AI-augmented quantification over acquisition cost.
- Handheld Ultrasound:Smartphone-connected probes and pocket-sized units deliver point-of-care cardiac assessment without dedicated exam rooms. Emergency departments in China and rural clinics across India drive volume as physician extenders perform bedside triage previously requiring specialist referral.
- Portable Ultrasound:Mid-tier systems balance mobility with diagnostic depth for ambulatory and outreach applications.
- Laptop-Based Ultrasound:Compact compute-integrated units serve traveling cardiologists and temporary clinical setups.
Leading the category by volume: Cart-Based Ultrasound. Growing fastest: Handheld Ultrasound.
Technology:
Cost tiers stratify sharply, with basic 2D modalities commoditizing while 3D/4D capabilities command premium positioning through surgical planning applications.
- Doppler Imaging:Spectral and color flow mapping constitutes the procedural backbone for valvular assessment and hemodynamic quantification. Cardiac stress testing protocols across diagnostic centers in the United States and Germany generate sustained procedure volume where reimbursement frameworks reward functional measurement precision.
- 3D Imaging:Real-time volumetric reconstruction enables en-face valve visualization and automated chamber quantification. Congenital defect screening programs in China and pediatric cardiology units across France adopt these capabilities for surgical planning workflows that justify superior reimbursement tiers.
- 4D Imaging:Spatiotemporal volumetric capture with cine playback supports interventional guidance and intraoperative monitoring.
- Speckle Tracking:Deformation analysis algorithms quantify myocardial strain for early dysfunction detection in oncology cardiology.
- 2D Imaging:Fundamental grayscale anatomical visualization remains the entry-level standard for resource-constrained settings.
Doppler Imaging commands the largest installed base. Speckle Tracking climbs the fastest as strain analysis enters routine surveillance protocols.
Application:
Customer type determines specification intensity, with hospital-based cardiologists demanding comprehensive measurement packages while primary care adopters prioritize interpretive assistance.
- Cardiac Assessment:Comprehensive structural and functional evaluation including chamber quantification, wall motion analysis, and ejection fraction calculation. Cardiology clinics across the United States and Germany deploy these capabilities as standard-of-care for heart failure monitoring and post-infarction surveillance.
- Congenital Defect Screening:Fetal and pediatric echocardiography for septal defects, valve anomalies, and complex cyanotic lesions. Tertiary centers in China and specialized children's hospitals across France invest in 3D/4D modalities where surgical planning accuracy justifies capital intensity.
- Vascular Diagnostics:Carotid, peripheral, and cerebrovascular flow assessment extending beyond cardiac applications.
- Pericardial Evaluation:Effusion characterization and tamponade detection in emergency and critical care contexts.
- Cardiac Stress Testing:Exercise or pharmacologic provocation with continuous imaging for ischemia detection.
Cardiac Assessment generates the highest procedure volume. Congenital Defect Screening expands most quickly through pediatric subspecialization.
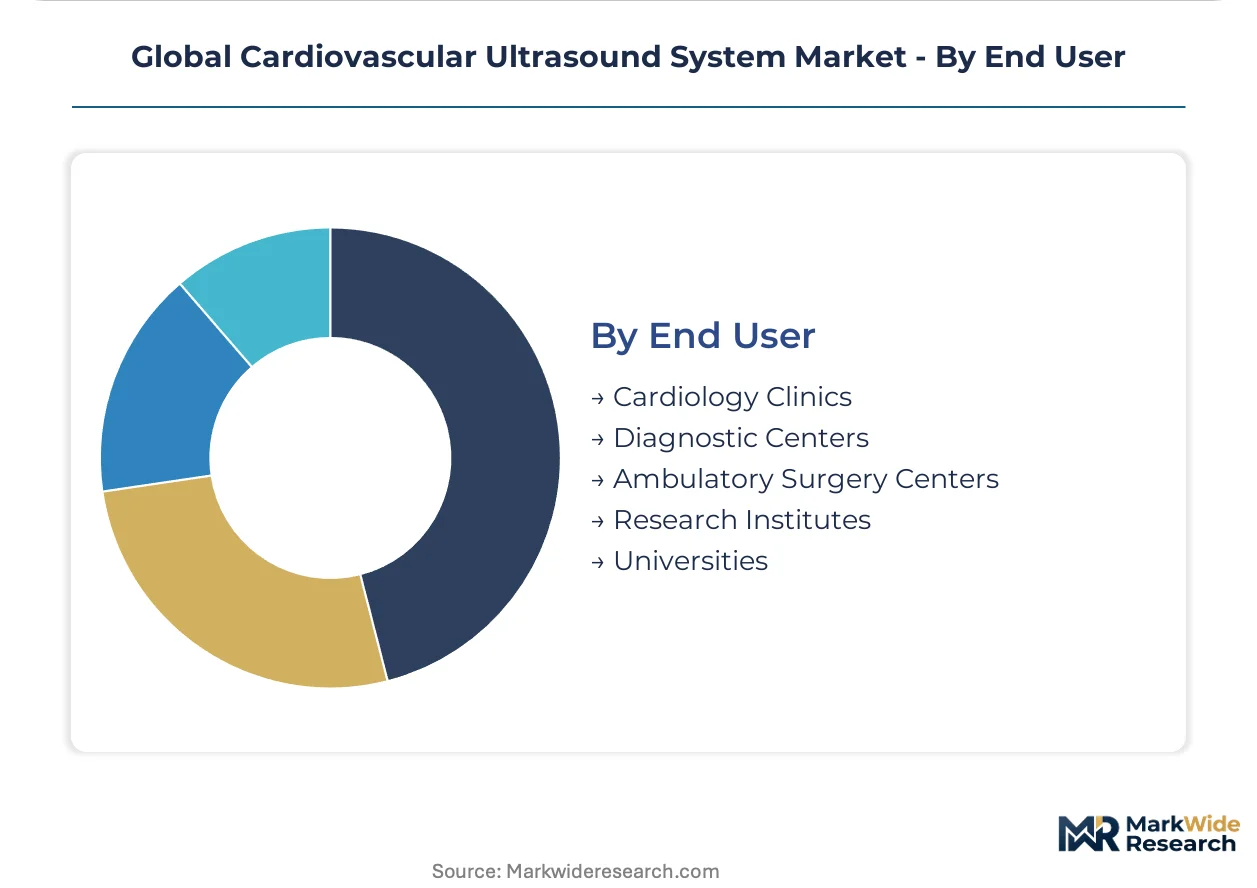
End User:
Geography shapes procurement authority, with urban academic centers driving premium adoption while distributed networks prioritize interoperability and remote interpretation capabilities.
- Cardiology Clinics:Dedicated cardiac diagnostic facilities with subspecialist interpretation and comprehensive measurement protocols. Germany's office-based cardiologist practices and China's metropolitan specialty clinics sustain demand for full-featured systems with autonomous quantification.
- Diagnostic Centers:High-volume imaging facilities processing referred patients across multiple modalities. India's tier-II city networks and United States outpatient imaging chains prioritize throughput optimization and PACS integration for centralized reading workflows.
- Ambulatory Surgery Centers:Preoperative cardiac clearance and procedural monitoring in same-day surgical settings.
- Research Institutes:Protocol development and clinical trial imaging with custom analysis requirements.
- Universities:Training programs and academic medical centers balancing education with patient care missions.
Cardiology Clinics anchor category revenue. Diagnostic Centers gain share fastest through referral consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors cardiovascular ultrasound R&D density, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical validation protocols for AI-augmented echocardiography systems.
United States
Integrated delivery networks in Texas and Florida prioritize portable system deployment for rural outreach programs. FDA 510(k) clearance pathways compress time-to-market for algorithm-enabled devices. The Research Triangle in North Carolina concentrates manufacturing operations for high-frequency transducer arrays serving academic medical centers.
Germany
Office-based cardiologist practices in Bavaria and Baden-Württemberg sustain demand for full-featured cart-based systems with autonomous quantification. EU MDR conformity requirements elevate clinical evidence burdens for notified body certification. Berlin-Brandenburg hosts digital health clusters integrating cloud-based diagnostic platforms into hospital information systems.
China
Metropolitan specialty clinics in Shanghai and Beijing deploy handheld units for bedside triage in overcrowded emergency departments. NMPA fast-track programs accelerate review timelines for AI-assisted diagnostic features. The Yangtze River Delta concentrates domestic manufacturing capacity for mid-tier portable systems targeting tier-II city expansion.
India
District hospitals in Maharashtra and Karnataka adopt smartphone-connected probes as physician extenders perform cardiac assessments without specialist referral. CDSCO medical device regulations govern import licensing for foreign manufacturers. Tamil Nadu's medical device manufacturing corridor develops localized assembly operations for cost-optimized portable units.
Japan
Geriatric cardiology units in Tokyo and Osaka invest in 3D/4D modalities for complex congenital defect screening among aging populations. PMDA pharmaceutical and medical device agency maintains stringent post-market surveillance for high-risk diagnostic equipment. The Kansai region hosts precision manufacturing clusters for piezoelectric crystal fabrication in premium transducer production.
Global Cardiovascular Ultrasound System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent value capture models. The vendor base stratifies between integrated imaging conglomerates owning full-stack manufacturing and specialized algorithm developers licensing diagnostic intelligence. Three archetypes dominate: diversified healthcare technology conglomerates with installed base leverage, mid-scale regional equipment fabricators with cost-optimized portfolios, and AI-native software vendors embedding into existing hardware ecosystems. Competitive moves concentrate on strategic partnerships bridging hardware and algorithm capabilities, plus geographic licensing arrangements penetrating underpenetrated secondary markets.
Within the diversified healthcare technology tier, GE Healthcare exemplifies integrated delivery network anchoring through platform-based workflow integration. Koninklijke Philips N.V. occupies a position emphasizing autonomous cardiac quantification capabilities. Siemens Healthineers AG represents digital twin integration for real-time hemodynamic modeling. These three conglomerates situate their competitive positioning around software-defined value migration rather than hardware shipment volume, reflecting industry-wide subscription economics displacement of perpetual licensing.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Canon Medical Systems |
| FUJIFILM Holdings Corporation |
| Mindray Medical International Limited |
| Samsung Medison Co., Ltd. |
| Hitachi Medical Corporation |
| Esaote SpA |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing eligibility for cardiovascular ultrasound manufacturers, compressing margins for vendors lacking robust vigilance architectures while elevating reimbursement-adjacent system tiers in Germany and France.
Pricing Analysis
Per-procedure diagnostic intelligence subscriptions anchor value-based pricing across integrated delivery networks in the United States and Germany, displacing perpetual software licenses. Three-tier pricing structure across premium, standard, and economy levels separates AI-augmented cart-based systems with autonomous quantification from handheld probes and basic 2D modalities. Pricing pressure stems from EU MDR conformity cost absorption and sonographer workforce scarcity constraining effective utilization. Emergency departments and rural clinics in India exhibit highest price sensitivity, while academic medical centers in Japan and Germany demonstrate lowest sensitivity due to surgical planning reimbursement premiums.
Supply Chain Analysis
Freight cost volatility from precision transducer component sourcing elevates landed cost uncertainty for manufacturers dependent on Japanese and German piezoelectric crystal fabrication. Advanced array manufacturing concentrates in the Kansai region and Bavaria, drawing from specialized ceramic substrate suppliers and semiconductor-grade signal processing chips. Single-source vulnerability in premium transducer supply creates bottleneck risk for high-end system production. Distribution runs through hospital GPO contracts in the United States, direct procurement by Germany's office-based cardiologists, and government tender channels in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined value migration positions this market as a consolidation play where AI-native algorithm developers and legacy hardware vendors lacking platform integration face forced exit.
For Market Incumbents: Deepen backward integration into piezoelectric crystal supply through captive manufacturing partnerships in Japan or Germany, insulating against transducer input bottlenecks. Fortify platform stickiness by embedding cloud-based diagnostic workflows into hospital information systems, defending against handheld disruptors capturing point-of-care volume in China and India. For New Entrants and Emerging Players: District hospital physician extenders in India's tier-II cities represent the most penetrable buyer archetype, underserved by specialist-dependent cart-based workflows. Deploy smartphone-connected probes with embedded AI interpretation to bypass sonographer scarcity constraints. Pursue CDSCO import licensing pathways and localized Tamil Nadu assembly to compress cost structures below multinational portable offerings. For Investors and Strategic Acquirers: NMPA fast-track approval for AI-assisted diagnostic features is the leading indicator that algorithm-enabled cardiovascular ultrasound vendors will capture disproportionate China revenue share. Position acquisition targets around mid-scale regional fabricators with ISO 13485 certification and existing distribution in underpenetrated Asian markets, monitoring EU MDR notified body audit frequency as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Workflow Integration | Edison platform and autonomous quantification capabilities anchor integrated delivery network contracts in the United States. |
| Handheld System Certification Pathway | FDA 510(k) clearance for smartphone-connected probes unlocks emergency department procurement in Texas and Florida. |
| Cloud-Based Diagnostic Platform Deployment | Remote interpretation capabilities reduce specialist travel burden across Germany's Berlin-Brandenburg hospital clusters. |
| Premium Transducer Supply Securement | Backward integration into Kansai-region piezoelectric fabrication insulates against array manufacturing bottlenecks. |
| Tier-II City Distribution Partnership | Localized assembly in Tamil Nadu positions cost-optimized portable units for Maharashtra district hospital expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and echocardiography sonographers. FDA 510(k) clearance databases, EU MDR notified body certifications, NMPA registration records, and hospital procurement databases supplied quantitative anchors. Bottom-up system shipment estimates triangulated against top-down diagnostic procedure volume projections across the analysis window.
Segment-level modeling captured product type differentiation between cart-based, handheld, portable, and laptop-based form factors; technology tiers spanning Doppler, 3D/4D, and speckle tracking modalities; application splits across cardiac assessment, congenital defect screening, and stress testing; and end-user variation between cardiology clinics, diagnostic centers, and ambulatory surgery centers. CAGRs derived from procedure volume growth trajectories, reimbursement code stability, and AI adoption curve assumptions. Forecast inputs incorporated NMPA fast-track approval velocity, EU MDR post-market surveillance cost absorption, and sonographer workforce expansion rates.
Revisions become necessary when NMPA regulatory timelines extend, EU MDR notified body capacity constraints intensify, or optical coherence tomography substitution accelerates in coronary plaque applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Stent Grafts Market