
 North America Methyl Acrylate Market | 2026-2036
North America Methyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Methyl Acrylate Market Analytics
Specialized polymer chemist availability is bifurcating the competitive landscape between integrated producers and formulation specialists. Dow Chemical Company leverages its Gulf Coast ethylene-to-acrylate chain to sustain cost-advantaged supply for waterborne adhesive makers. DuPont anchors its position through R&D intensity in high-performance coating resins, while Arkema S.A. differentiates via specialty acrylate grades for electronics-grade applications.
Methyl acrylate is an ester of acrylic acid with the formula CH₂=CHCOOCH₃, typically produced through acid-catalyzed esterification of acrylic acid with methanol; it polymerizes readily to form homopolymers and copolymers with glass transition temperatures around 10°C, serving primarily as a building block for pressure-sensitive adhesives, textile finishes, and UV-curable coatings. Liquid methyl acrylate dominates volume flows due to its ease of handling in bulk chemical logistics, while polyacrylate derivatives capture expanding margin pools in high-clarity optical and medical-grade films. The adhesives application segment leads absolute consumption, though coatings demand grows fastest as architectural and automotive OEM formulators shift from solvent-borne to waterborne acrylic systems.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain conventional solvent-based methyl acrylate processes, while OSHA permissible exposure limits shape workplace handling protocols and capital allocation toward enclosed reactor systems. Health Canada's Chemicals Management Plan and corresponding PMRA assessments for polymer intermediates create additional compliance layers for cross-border suppliers. Stakeholders must monitor the trajectory of state-level low-VOC product rules in California and New York, as these jurisdictions typically prefigure broader federal adoption timelines.
Market Dynamics
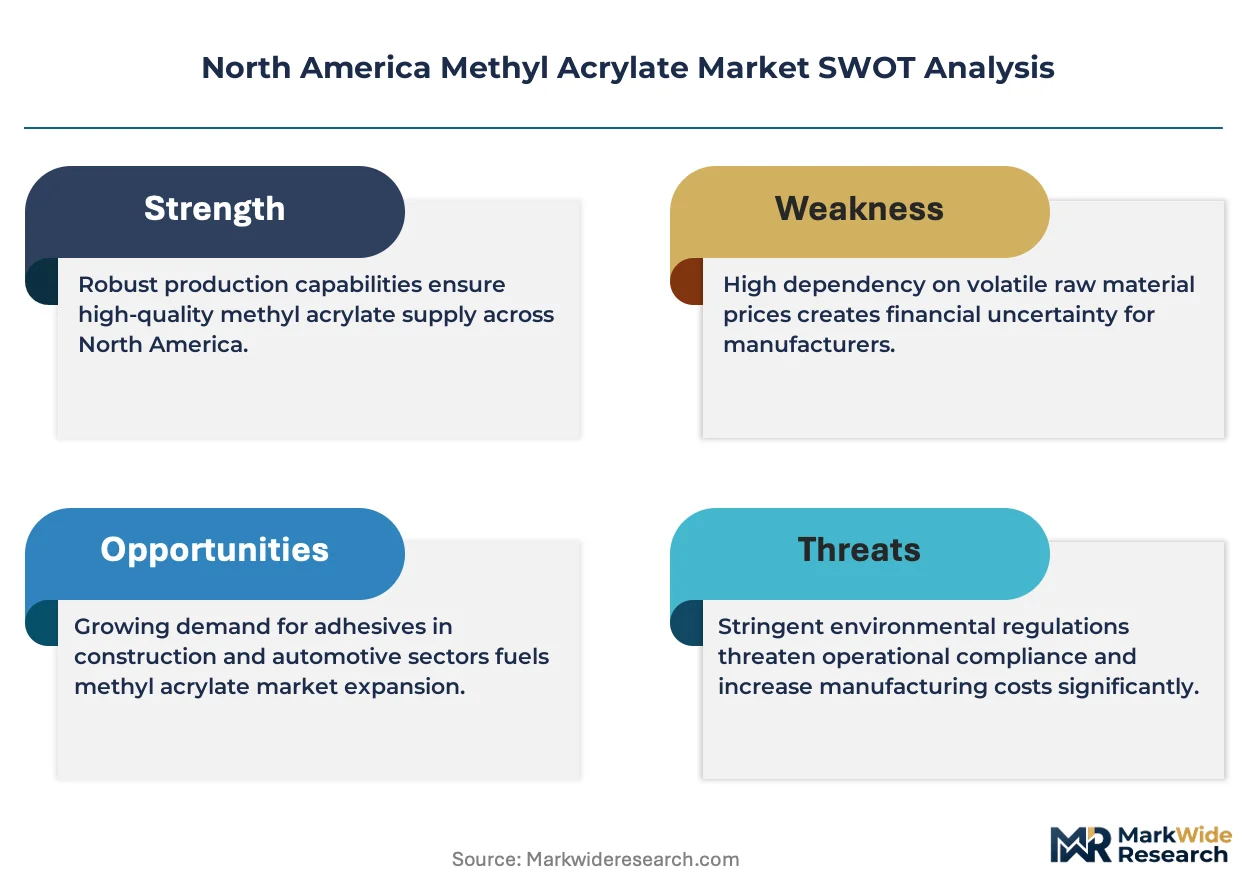
EPA's tightened National Emission Standards for Hazardous Air Pollutants are compressing solvent-borne coating margins while accelerating waterborne acrylic system adoption across automotive refinishing and architectural applications. This regulatory pivot is redrawing competitive boundaries between integrated Gulf Coast producers and specialty formulation houses.
Growth Catalysts
- Clean Air Act VOC mandates:EPA emission ceilings are forcing automotive OEM and refinish formulators toward low-solvent acrylic binders, expanding methyl acrylate consumption in waterborne coating platforms.
- Pressure-sensitive adhesive demand:E-commerce logistics growth is driving tape and label consumption, with methyl acrylate copolymers serving as critical tackifier and peel-strength modifiers in hot-melt and emulsion systems.
- Texas-Louisiana production clustering:Integrated acrylic acid-methyl acrylate units along the Gulf Coast petrochemical corridor are capturing feedstock cost advantages from proximate ethylene and propylene supply.
Market Restraints
- Acrylic acid feedstock volatility:Propylene price swings and unplanned cracker outages transmit directly to methyl acrylate cost structures, compressing margin predictability for non-integrated buyers.
- Gulf Coast supply concentration:Over 70% of North American capacity sits within hurricane-exposed Texas and Louisiana corridors, creating weather-related production interruption risk.
- Regulatory compliance capital intensity:OSHA permissible exposure limits and EPA leak detection mandates are requiring enclosed reactor investments that disadvantage smaller batch producers.
Strategic Opportunities
- Canadian cross-border expansion:Health Canada's Chemicals Management Plan is harmonizing with EPA frameworks, reducing regulatory friction for US producers seeking Alberta and Ontario adhesive and coatings markets.
- UV-curable electronics films:Methyl acrylate oligomers are penetrating optical-grade display laminates and semiconductor encapsulants as device miniaturization demands tighter cure control.
- California low-VOC product rules:The state's South Coast Air Quality Management District is prefiguring federal timelines, creating first-mover positioning for compliant waterborne system suppliers.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise in acrylate ester reactivity ratios and glass transition temperature tuning is concentrating at integrated producers, constraining mid-scale compounder R&D bandwidth.
- Legacy solvent-borne asset stranding:Coatings manufacturers face write-down risk on conventional spray booth and drying oven infrastructure as waterborne system conversions accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Methyl Acrylate Market |
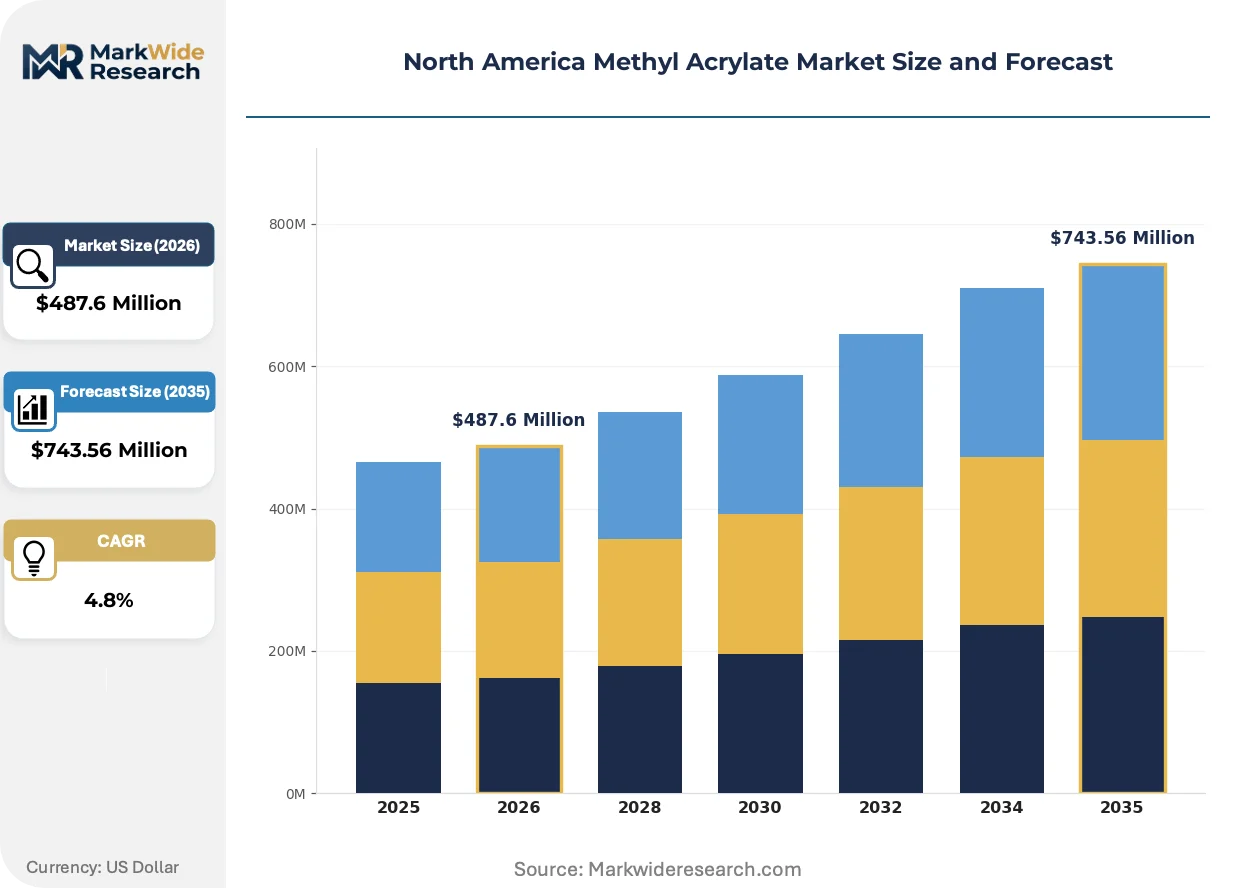
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Methyl Acrylate, Solid Methyl Acrylate, Aqueous Methyl Acrylate, Polyacrylate Application: Adhesives, Coatings, Paints, Textiles End User: Construction, Automotive, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Dow Chemical Company, DuPont, BASF, Arkema S.A., Evonik Industries AG, Mitsubishi Chemical America, Inc., Sumitomo Chemical America, Inc., H.B. Fuller Company, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Methyl Acrylate Market Evolving Landscape
Waterborne acrylic polymerization chemistry is advancing rapidly as formulators seek to match solvent-borne performance benchmarks without volatile organic compound penalties. Three developments are reshaping technical and commercial trajectories.
Bio-based acrylic acid feedstocks derived from glycerol and lignocellulosic sugars are supplanting petroleum-derived propylene in pilot-scale methyl acrylate production. Automotive OEM sustainability scorecards are accelerating qualification timelines for partially renewable content binders. This feedstock diversification is compressing petrochemical price linkage and opening margin structures previously unavailable to specialty producers.
The EPA's National Emission Standards for Hazardous Air Pollutants and corresponding state-level MACT rules are mandating enclosed reactor systems and vapor recovery units for methyl acrylate handling. Capital expenditure requirements are favoring large integrated producers with balance sheet capacity for compliance infrastructure. Smaller batch compounders are responding through toll manufacturing arrangements and shared reactor access models.
Specification-driven procurement is consolidating purchasing authority among tier-one automotive and electronics OEMs, displacing fragmented distributor-based buying patterns. Direct supplier relationships are enabling collaborative formulation development and locked-in volume commitments. This shift is most visible in Michigan automotive clusters and California electronics manufacturing corridors where OEM technical teams are embedding directly at adhesive and coating supplier facilities.
North America Methyl Acrylate Market Segmentation
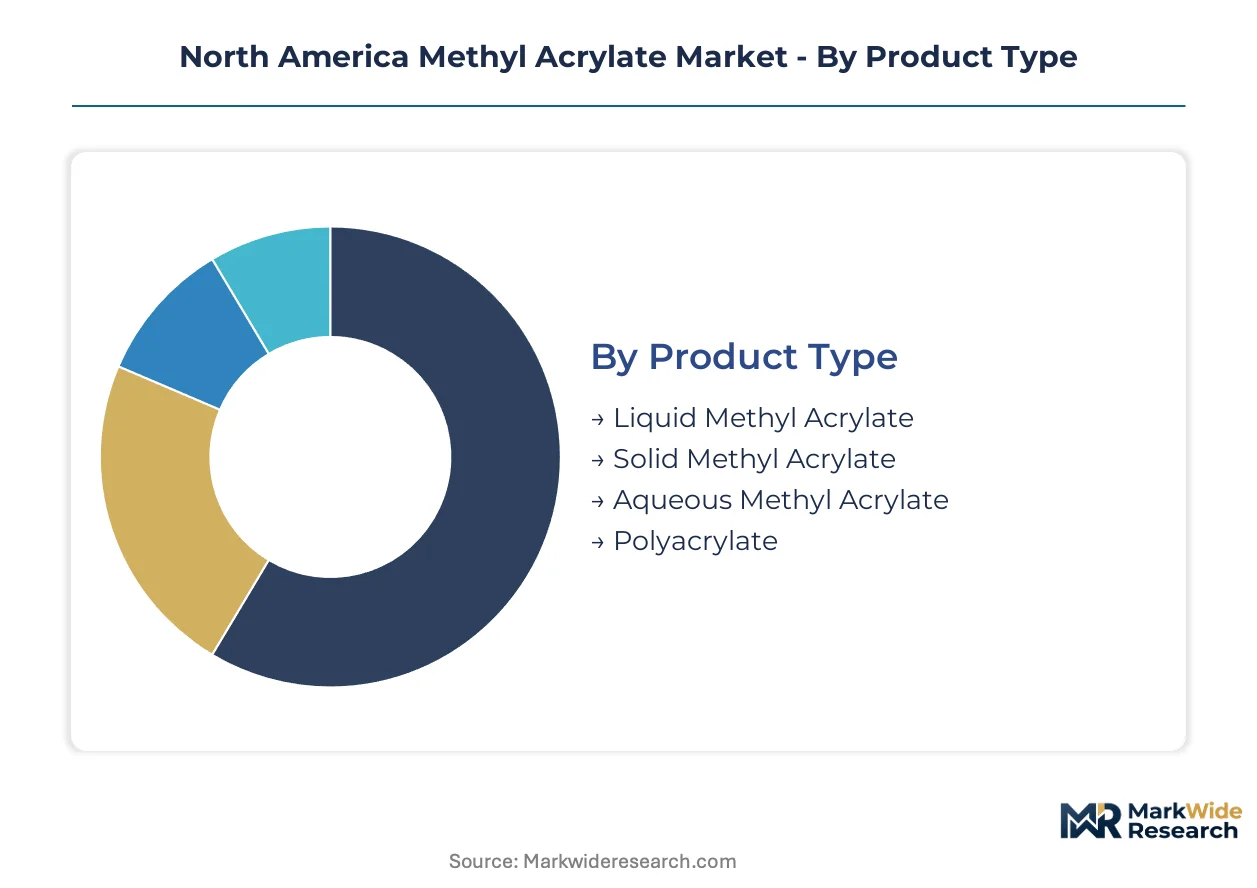
Segmentation in the North America methyl acrylate market reveals distinct procurement patterns across product forms and end-use verticals. Product type determines logistics infrastructure requirements, while application mix governs regulatory exposure and margin structure.
Product Type:
Liquid methyl acrylate dominates domestic bulk movements through Gulf Coast terminals, while polyacrylate derivatives command premium positioning in cross-border specialty chemical trade.
- Liquid Methyl Acrylate:Standard industrial grade with 99% minimum purity serves railcar and tanker-truck logistics networks. Demand concentrates in Texas and Louisiana adhesive manufacturing corridors where Dow and Arkema maintain integrated acrylic acid-to-ester production. EPA National Emission Standards for Hazardous Air Pollutants compliance costs favor large-volume handlers with enclosed loading systems.
- Polyacrylate:Polymerized derivatives including sodium and ammonium salts function as superabsorbent polymers and rheology modifiers. California electronics manufacturers and Michigan automotive OEMs drive specification-grade consumption for optical films and pressure-sensitive adhesives. Health Canada PMRA assessments for polymer intermediates create additional qualification layers for Canadian medical device applications.
- Solid Methyl Acrylate:Powder and flake forms enable precise dosing in batch compounding operations across Ontario construction sealant plants.
- Aqueous Methyl Acrylate:Pre-emulsified dispersions reduce VOC handling requirements for New York and California architectural coating formulators facing South Coast Air Quality Management District limits.
Liquid methyl acrylate commands the established base. The steepest expansion runs through polyacrylate.
Application:
Application mix reflects divergent growth velocities, with coatings demand accelerating fastest under regulatory pressure while adhesives maintain volume dominance.
- Adhesives:Pressure-sensitive tapes, hot-melt formulations, and structural bonding systems consume the largest volume share. E-commerce logistics growth across US distribution hubs and Canadian cross-border fulfillment centers drives tape and label substrate demand. Methyl acrylate copolymers deliver tunable tack and peel strength in emulsion and solvent-borne platforms.
- Coatings:Waterborne acrylic binders for automotive refinish and architectural applications are displacing solvent systems under Clean Air Act mandates. California and New York state-level low-VOC product rules prefigure federal adoption, concentrating specification development in West Coast and Northeast formulation laboratories.
- Paints:Decorative and industrial finishes incorporate methyl acrylate as a comonomer for gloss retention and exterior durability in Gulf Coast humidity exposure.
- Textiles:Sizing agents and fabric finishing treatments utilize acrylate esters for hand modification and wrinkle resistance in North Carolina and South Carolina mill operations.
Adhesives anchor current procurement volumes. Coatings deliver the fastest margin expansion trajectory.
End User:
End user concentration varies by sector maturity, with automotive and electronics driving technical specification intensity while construction maintains commodity-scale absorption.
- Automotive:OEM and refinish coating formulators in Michigan, Ohio, and Ontario specify methyl acrylate-rich binders for chip resistance and metallic flake orientation. Tier-one suppliers embed technical teams at adhesive compounders to co-develop waterborne systems meeting EPA emission ceilings.
- Electronics:Display laminates, semiconductor encapsulants, and optical-grade films demand ultra-low residual monomer content. California and Texas electronics manufacturing corridors source specialty acrylate grades through direct supplier relationships rather than distributor channels.
- Construction:Sealants, caulks, and waterproofing membranes absorb commodity-grade liquid methyl acrylate through bulk distribution networks serving Florida, Texas, and Arizona building booms.
- Consumer Goods:Packaging adhesives and personal care thickeners utilize polyacrylate derivatives in mid-volume batch production across Midwest contract manufacturers.
Construction underpins steady offtake. Electronics generates the steepest specification premium capture.
Distribution Channel:
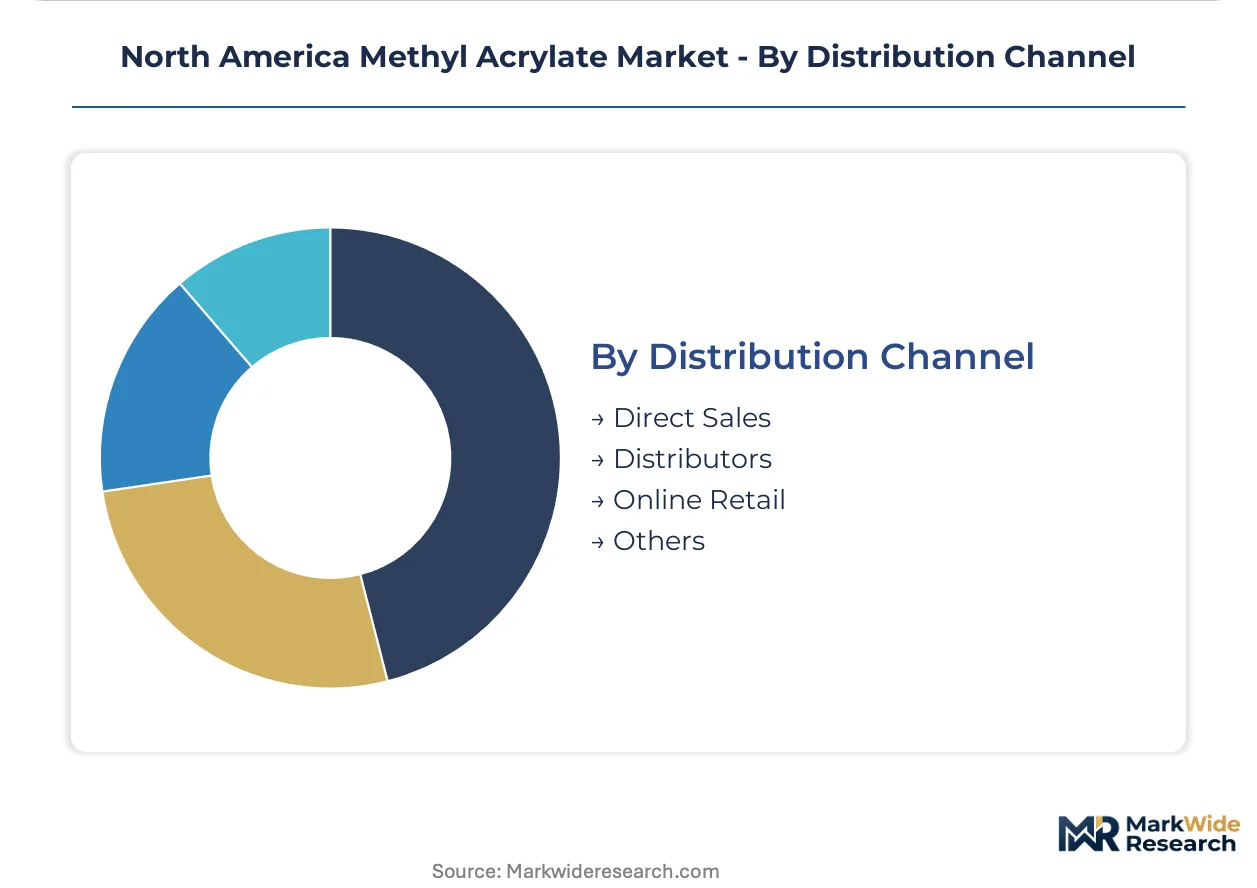
Channel structure bifurcates between bulk commodity flows and specialty technical sales, with direct relationships displacing traditional distribution in specification-driven segments.
- Direct Sales:Integrated producers Dow and Arkema supply automotive and electronics OEMs through dedicated account management and technical service agreements. Locked-in volume commitments and collaborative formulation development characterize Michigan and California procurement patterns.
- Distributors:Univar Solutions and Brenntag maintain regional stocking positions for mid-scale adhesive compounders and coating manufacturers lacking rail siding infrastructure.
- Online Retail:Laboratory-scale quantities and specialty grades reach R&D facilities through digital procurement platforms with expedited delivery.
- Others:Toll manufacturing arrangements and shared reactor access models enable smaller batch producers to circumvent capital-intensive enclosed system investments.
Direct sales channels command the highest value concentration. Distributor relationships deliver the broadest geographic coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission ceilings under the Clean Air Act are compressing solvent-borne coating margins across the United States while accelerating waterborne acrylic system adoption. This regulatory pivot is redrawing procurement patterns and production clustering across North American geographies.
United States
Automotive OEM and refinish formulators in Michigan and Ohio specify methyl acrylate-rich binders for chip resistance and metallic flake orientation. The EPA's National Emission Standards for Hazardous Air Pollutants mandate enclosed reactor systems and vapor recovery units for methyl acrylate handling. The Texas-Louisiana Gulf Coast petrochemical corridor concentrates over 70 percent of North American capacity, where integrated acrylic acid-methyl acrylate units capture feedstock cost advantages from proximate ethylene supply.
Canada
Cross-border adhesive and coatings demand concentrates in Ontario and Alberta manufacturing corridors. Health Canada's Chemicals Management Plan and corresponding PMRA assessments for polymer intermediates create qualification layers for medical device applications. Toronto-area formulation laboratories are embedding technical teams at US supplier facilities to co-develop compliant waterborne systems.
Mexico
Automotive assembly growth in Nuevo León and Mexico City Metro is driving pressure-sensitive adhesive consumption for interior trim and exterior badge bonding. Mexico's environmental regulator SEMARNAT is harmonizing VOC emission frameworks with EPA benchmarks, reducing regulatory friction for US Gulf Coast producers. Querétaro and Guanajuato electronics manufacturing corridors are sourcing specialty acrylate grades for display laminates.
California
The South Coast Air Quality Management District's low-VOC product rules prefigure federal adoption timelines, concentrating specification development in West Coast formulation laboratories. Electronics manufacturers in Silicon Valley demand ultra-low residual monomer content for semiconductor encapsulants. Los Angeles-area architectural coating formulators are converting solvent-borne spray booths to waterborne acrylic systems under state-level mandates.
North America Methyl Acrylate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American methyl acrylate market. Integrated Gulf Coast producers command feedstock-advantaged positions through captive ethylene-to-acrylate chains, while specialty formulation houses compete on R&D intensity and specification-grade customization. The competitive landscape bifurcates between scale-driven commodity suppliers and application-specific solution providers. Dominant competitive moves include capacity expansion along hurricane-exposed corridors and collaborative formulation partnerships with tier-one automotive OEMs.
Among integrated petrochemical producers, Dow Chemical Company and Arkema S.A. occupy positions exemplifying the cost-leadership archetype through Gulf Coast production clustering. DuPont represents the technology-intensity vector, anchoring competitive positioning through high-performance coating resin development. These three companies illustrate the market's structural division between feedstock-integrated scale players and specification-driven specialty houses.
| Leading Market Players |
|---|
| Dow Chemical Company |
| DuPont |
| BASF |
| Arkema S.A. |
| Evonik Industries AG |
| Mitsubishi Chemical America, Inc. |
| Sumitomo Chemical America, Inc. |
| H.B. Fuller Company |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Integrated acrylic acid-methyl acrylate units along the Texas-Louisiana Gulf Coast corridor capture scale economies that compress unit costs and establish regional price floors for non-integrated compounders. This concentration of captive ethylene-to-ester production creates asymmetric pricing power where hurricane-exposed capacity tightness periodically resets contract benchmarks for downstream adhesive and coating manufacturers.
Pricing Analysis
Gulf Coast contract prices for liquid methyl acrylate trade at spreads below delivered costs to Ontario and California formulators facing rail and trucking surcharges. Three-tier pricing structure across premium specification-grade, standard industrial-grade, and economy bulk-grade levels reflects residual monomer content and certification intensity. Cost compression in standard grades is intensifying because propylene feedstock volatility transmits directly through integrated producer cost structures. Mid-scale adhesive compounders exhibit highest price sensitivity, while electronics OEMs purchasing ultra-low residual monomer grades demonstrate inelastic demand.
Supply Chain Analysis
Strategic stockpiling of liquid methyl acrylate prevails among Michigan automotive OEMs and California electronics manufacturers seeking insulation from Gulf Coast weather disruptions, whereas Ontario construction sealant plants operate on just-in-time railcar schedules. Supply concentrates in the United States, Canada, and Mexico through cross-border petrochemical corridors. Production draws from propylene, methanol, and sulfuric acid catalyst inputs. Single-source vulnerability runs through the hurricane-exposed Texas-Louisiana production cluster where over two-thirds of North American capacity resides. Distribution runs through direct producer-to-OEM relationships for specification grades and regional chemical distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EPA emission mandates and state-level low-VOC product rules bifurcate demand between compliant waterborne system specialists and legacy solvent-borne asset holders. This regulatory-driven demand-side shift creates defendable niches for formulation expertise and certification-capable producers.
For Market Incumbents: Shield margin structures through backward integration into captive acrylic acid production and enclosed reactor infrastructure investments that smaller batch compounders cannot replicate. The OSHA permissible exposure limit tightening and EPA leak detection mandates threaten non-compliant producers with stranded asset risk. Priority levers include Gulf Coast capacity expansion with vapor recovery systems and collaborative formulation partnerships with tier-one automotive OEMs embedding technical teams at supplier facilities. For New Entrants and Emerging Players: Anchor in Canadian cross-border expansion where Health Canada's Chemicals Management Plan harmonization reduces regulatory friction for US-qualified waterborne systems. The most penetrable white-space target sits in Alberta and Ontario adhesive manufacturing corridors underserved by integrated producer direct sales. UV-curable electronics films for semiconductor encapsulants offer specification-grade entry with lower volume scale requirements. Go-to-market angle should emphasize toll manufacturing arrangements that circumvent capital-intensive enclosed reactor investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty formulation houses with locked-in volume commitments from automotive and electronics OEMs through collaborative development agreements. Long-term viability across the analysis window favors acquisition targets with demonstrated EPA compliance infrastructure and specification-grade certification pathways. The target archetype combines mid-scale batch compounding capability with direct OEM relationships in Michigan or California manufacturing clusters. Watch for inflection when California South Coast Air Quality Management District rules achieve federal adoption traction.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast additions with vapor recovery units capture EPA compliance advantages. |
| Backward Integration | Captive acrylic acid production insulates margin from propylene volatility. |
| Long-term Supply Agreement | Locked-in volumes with Michigan automotive OEMs reduce demand uncertainty. |
| Joint Venture | Shared reactor access models enable smaller compounders to meet OSHA enclosed system mandates. |
| Green Manufacturing Transition | Bio-based acrylic acid feedstocks from glycerol qualify for automotive OEM sustainability scorecards. |
Research Methodology
Desk research of customs and trade flow databases, ACC industry reports, and SEC chemical sector filings preceded structured interviews with plant managers at integrated Gulf Coast producers, procurement leads at Michigan automotive OEMs, distribution channel partners, and technical R&D directors at specialty formulation houses. Primary fieldwork combined with secondary validation through EPA enforcement records and Health Canada PMRA assessments enabled bottom-up and top-down triangulation of volume and value estimates.
Variance decomposition across feedstock cost, regulatory compliance capital, and end-use demand elasticity shaped the analytical framework. Segmentation dimensions modeled include product form grade tier, end-use industry vertical, regional production hub clustering, and specification intensity level. CAGRs were derived through iterative convergence of demand-side uptake curves and supply-side capacity addition schedules. Industry-specific forecast inputs incorporated propylene price trajectory assumptions and state-level low-VOC adoption timelines.
Material uncertainties — unplanned cracker outages, hurricane-related production interruptions, and accelerated federal adoption of California emission benchmarks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization continuity and automotive OEM waterborne conversion rates. Revision becomes warranted when propylene feedstock volatility or EPA enforcement intensity crosses thresholds that alter integrated producer cost advantage calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market