
 India Chlorine Market | 2026-2036
India Chlorine Market Size, Share, and Industry Trends Forecast 2026-2036
India Chlorine Market Foresight
Food-grade and pharmaceutical-grade chlorine specifications is bifurcating the India Chlorine Market into premium and industrial tiers. Chemplast Sanmar Limited leverages its chlor-alkali integration to command the high-purity segment. Grasim Industries Limited anchors western India supply through its Gujarat manufacturing base. Tata Chemicals Limited differentiates via specialty chlorine derivatives for regulated end-uses.
Chlorine is a yellow-green diatomic gas produced primarily through membrane cell electrolysis of brine, with minimum purity thresholds of 99.5% for industrial applications and higher grades for pharmaceutical and potable water uses. The gas serves as a foundational oxidizing agent across PVC synthesis, water disinfection, and intermediate chemical manufacturing. Caustic soda co-production dominates volume economics, while sodium hypochlorite captures expanding water treatment demand from municipal utilities. Pharmaceutical-grade chlorine commands premium pricing due to stringent CDSCO impurity limits, whereas chlorinated solvents face substitution pressure from environmental regulations.
BIS standards govern chlorine purity grades and packaging protocols, while CDSCO regulates pharmaceutical-grade specifications for active ingredient manufacturing. The Central Pollution Control Board enforces emissions thresholds that favor membrane cell technology over mercury-cell legacy capacity. State-level pollution control boards in Gujarat and Maharashtra implement site-specific discharge norms that shape plant location decisions. Stakeholders must monitor the trajectory of India's PLI scheme for chemical manufacturing and evolving state-level environmental compliance timelines.
Market Dynamics
Membrane cell electrolysis is displacing mercury-cell capacity across Gujarat and Maharashtra as state pollution control boards enforce stricter discharge norms, compressing legacy chlorine production economics while elevating capital requirements for compliant greenfield installations.
Growth Catalysts
- Municipal Water Treatment Expansion:Water utilities in Maharashtra and Gujarat are scaling chlorine procurement for urban purification systems, with BIS certification mandates tightening product specifications nationwide.
- PLI Scheme for Chemical Manufacturing:India's production-linked incentive scheme is channeling investment toward chlor-alkali integration, reducing import dependency for high-purity industrial grades.
- Dahej-Mundra Chemical Corridor:Concentrated demand from PVC synthesis and intermediate chemical manufacturing in Gujarat's industrial zones anchors volume offtake for regional producers.
Market Restraints
- Caustic Soda Co-Production Economics:Chlorine volume viability depends on caustic soda offtake pricing, creating margin compression when alkali markets soften.
- Mercury-Cell Legacy Liabilities:Central Pollution Control Board emissions thresholds force costly retrofit or closure of aging capacity, stranding capital in non-compliant assets.
- Chlorinated Solvent Substitution:Environmental regulations are displacing chlorinated solvent applications with aqueous and hydrocarbon alternatives, eroding a traditional chlorine demand pillar.
Strategic Opportunities
- Pharmaceutical-Grade Certification:CDSCO impurity limits for active ingredient manufacturing create premium pricing tiers for producers achieving pharmaceutical-grade chlorine specifications.
- Sodium Hypochlorite Direct Supply:Municipal utilities are bypassing merchant chlorine gas in favor of pre-formulated sodium hypochlorite, opening packaged chemical distribution channels.
- Membrane Technology Upgrades:Ion-exchange membrane efficiency gains enable energy cost reductions that improve competitiveness against imported material from Middle Eastern producers.
Industry Challenges
- BIS Certification Timelines:Bureau of Indian Standards purity testing and packaging protocol approvals extend product launch cycles, delaying market entry for new grades.
- Specialized Chlor-Alkali Engineering Talent:Shortage of process engineers experienced in membrane cell optimization limits operational efficiency gains at expanded capacity.
- Legacy System Integration:Retrofitting mercury-cell plants with membrane technology requires extended shutdown periods, disrupting supply commitments during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Chlorine Market |
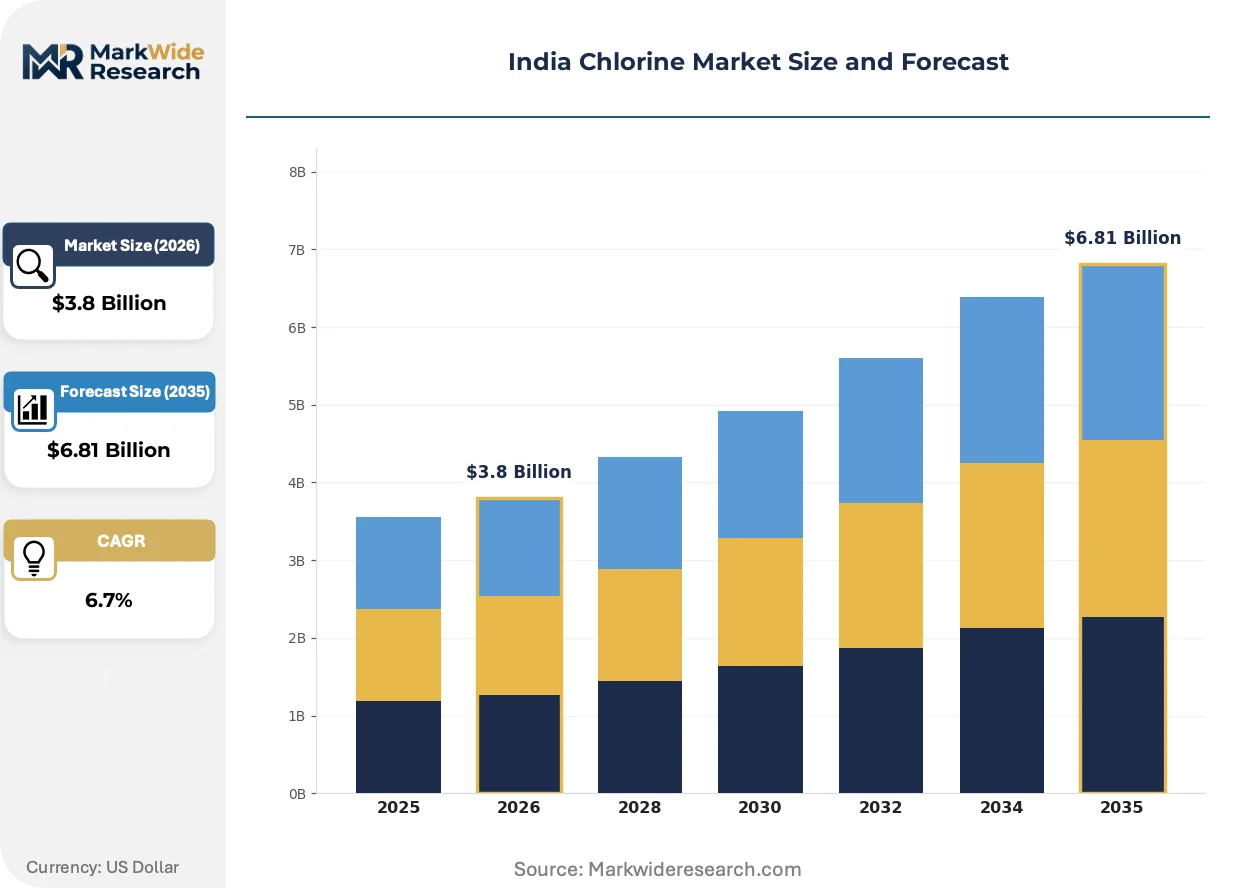
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hypochlorite, Caustic Soda, Chlorinated Solvents, Hydrochloric Acid Application: Water Treatment, PVC Production, Pharmaceuticals, Bleaching Agents End User: Chemical Industry, Water Utilities, Pharmaceutical Companies, Textile Manufacturers Distribution Channel: Direct Sales, Online Sales, Wholesale Distributors, Retail Outlets |
| Companies Covered | Chemplast Sanmar Limited, Reliance Industries Limited, Grasim Industries Limited, Gujarat Fluorochemicals Ltd., Tata Chemicals Limited, Gujarat Alkalies and Chemicals Limited, Nirma Limited, Meghmani Finechem Limited, DCM Shriram, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Chlorine Market Shifts & Advancements
Electrochemical process intensification and regulatory emissions compression are fragmenting traditional chlorine production economics, creating divergent technology pathways across India's western chemical corridor.
Membrane cell electrolysis with advanced ion-exchange materials is fragmenting the competitive landscape between energy-efficient producers and legacy mercury-cell operators. Dahej and Mundra industrial zone installations are adopting third-generation membrane stacks that reduce power consumption per ton of chlorine output. This technology diffusion is compressing margins for non-compliant capacity while elevating barriers to entry for new market participants.
BIS certification requirements for chemical purity and packaging protocols are tightening product differentiation thresholds across industrial and potable water grades. The Bureau of Indian Standards mandates now distinguish food-grade specifications from pharmaceutical-grade chlorine, forcing producers to maintain parallel production streams. Maharashtra and Gujarat state pollution control boards are layering site-specific discharge norms atop central requirements, multiplying compliance complexity for multi-state operators.
Direct sodium hypochlorite procurement is displacing merchant chlorine gas contracts among municipal water utilities seeking operational simplification. Urban water treatment authorities in western India are consolidating purchases through state-level tendering platforms, compressing supplier margins while demanding technical support services. This channel shift favors producers with integrated hypochlorite formulation capacity over pure chlorine gas merchants.
India Chlorine Market Segmentation
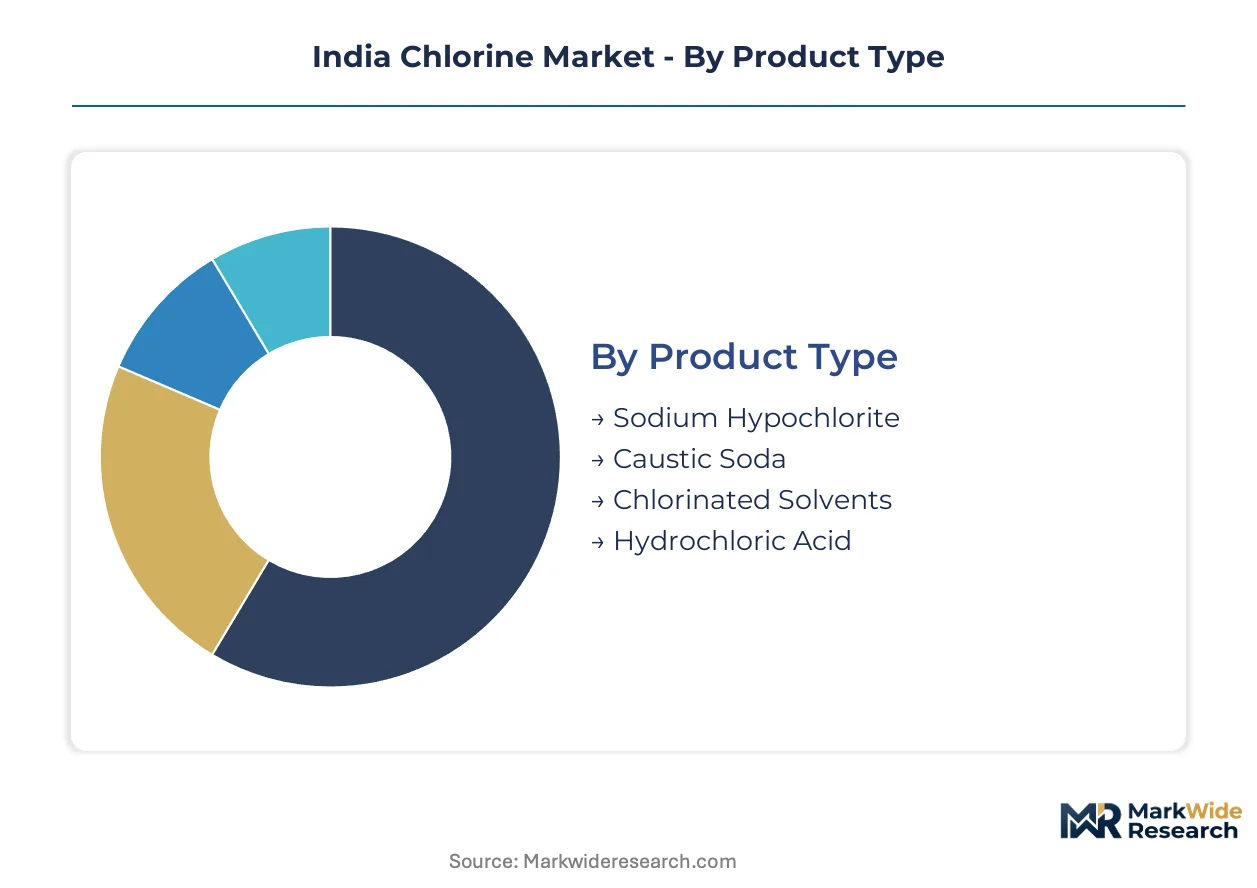
Chlorine derivative markets in India fragment across co-product economics, regulatory purity tiers, and utility procurement modernization. Segment boundaries reflect membrane cell technology diffusion, BIS certification stratification, and the shift from merchant gas to formulated chemical delivery.
Product Type:
Domestic production concentrates on co-product chemicals from membrane cell electrolysis, while chlorinated solvent output faces export market headwinds from environmental substitution pressures abroad.
- Sodium Hypochlorite:Aqueous solution containing 10-15% available chlorine serves municipal water utilities seeking operational simplification. Maharashtra and Gujarat urban water authorities are consolidating procurement through state tendering platforms, bypassing merchant chlorine gas entirely.
- Caustic Soda:Co-produced sodium hydroxide dominates volume economics for chlor-alkali operators. Dahej and Mundra corridor producers anchor western India supply, with pricing interdependence forcing integrated margin management across both outputs.
- Chlorinated Solvents:Perchloroethylene and trichloroethylene face displacement from aqueous cleaning alternatives in export markets.
- Hydrochloric Acid:Captive consumption by PVC synthesis and pharmaceutical intermediates limits merchant market depth.
Caustic Soda holds the largest share; momentum sits with Sodium Hypochlorite.
Application:
Cost tiers separate commodity water treatment from premium pharmaceutical grades, with BIS and CDSCO specifications creating pricing stratification.
- Water Treatment:Municipal purification systems across Maharashtra and Gujarat drive baseline chlorine offtake. BIS certification mandates for potable water grades tighten purity thresholds, forcing producers to maintain parallel production streams.
- Pharmaceuticals:CDSCO impurity limits for active ingredient manufacturing command premium pricing. Membrane cell producers achieving pharmaceutical-grade certification capture margin expansion unavailable to industrial-grade merchants.
- PVC Production:Dahej chemical corridor anchors concentrated demand for vinyl chloride monomer synthesis.
- Bleaching Agents:Textile and paper applications face substitution from peroxide-based alternatives in environmental compliance scenarios.
Water Treatment commands volume leadership; Pharmaceuticals delivers the steepest margin expansion trajectory.
End User:
Customer type determines delivery format, with bulk chemical offtake from integrated manufacturers contrasting packaged distribution to fragmented utility buyers.
- Water Utilities:State-level urban water boards in western India are shifting from cylinder chlorine gas to pre-formulated sodium hypochlorite. This procurement pattern favors producers with integrated formulation and technical service capabilities.
- Chemical Industry:PVC and intermediate manufacturers in Gujarat's Dahej-Mundra zone absorb merchant chlorine through pipeline and bulk tanker delivery. Volume concentration enables long-term contract structures with price pass-through mechanisms.
- Pharmaceutical Companies:CDSCO-regulated manufacturers require certificate-of-analysis documentation for every lot.
- Textile Manufacturers:Bleaching applications in Surat and Tiruppur clusters face environmental discharge compliance pressures.
Chemical Industry represents the largest offtake volume; Water Utilities are gaining share fastest.
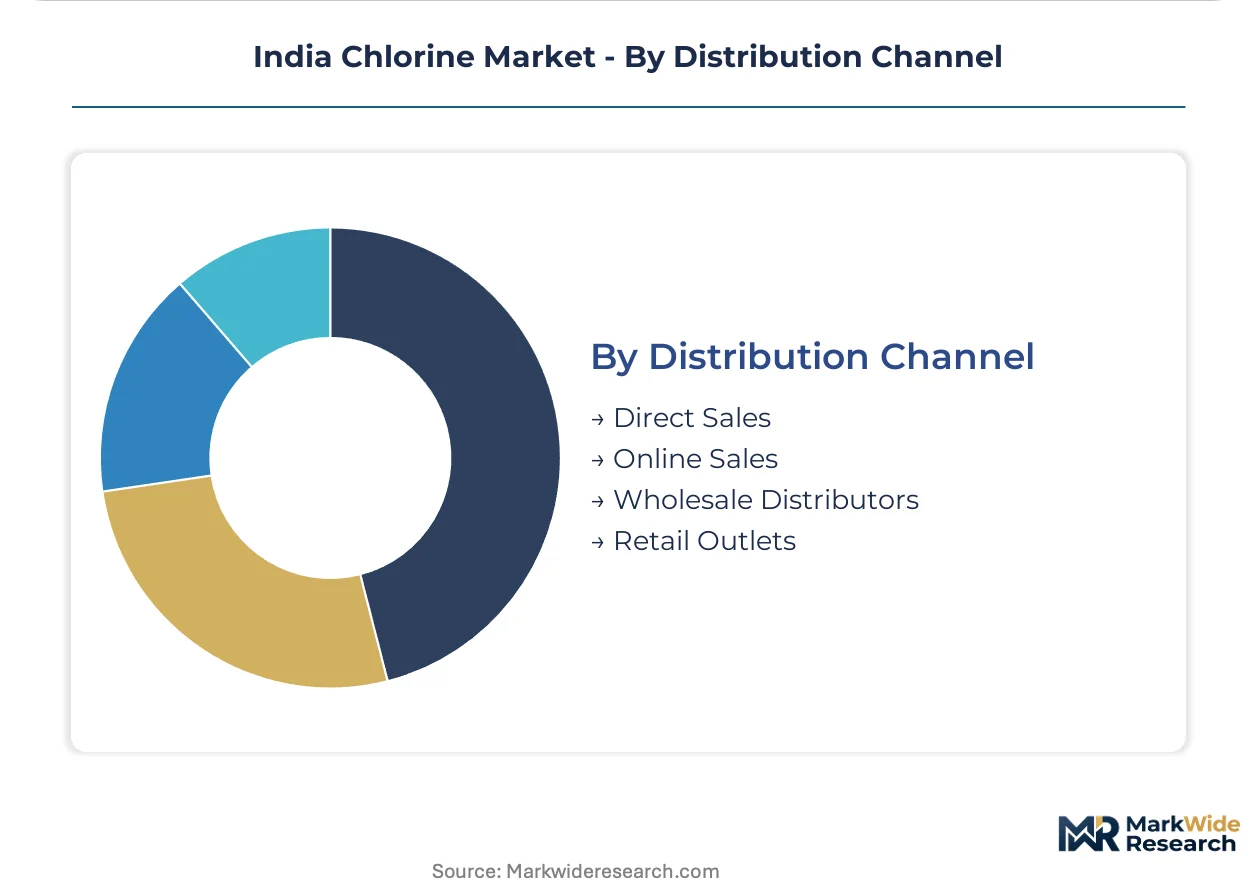
Distribution Channel:
Supply chain configuration separates bulk pipeline delivery to integrated manufacturers from packaged chemical logistics to fragmented municipal buyers.
- Direct Sales:Pipeline and dedicated tanker delivery serves Dahej-Mundra chemical corridor manufacturers. Long-term offtake agreements with price escalation clauses dominate this channel, reducing spot market exposure for membrane cell operators.
- Wholesale Distributors:Regional chemical distributors manage cylinder gas and drum packaging for smaller industrial consumers. Inventory holding and BIS compliance documentation responsibilities shift to distributor balance sheets.
- Online Sales:Laboratory-grade and small-volume industrial chemicals move through B2B platforms with certificate-of-analysis verification.
- Retail Outlets:Limited to consumer bleach formulations with minimal industrial relevance.
Direct Sales holds the largest share; Wholesale Distributors capture expanding municipal utility volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's chlorine trade balance tilts toward domestic self-sufficiency as membrane cell capacity expands across western industrial corridors. Import dependency concentrates on pharmaceutical-grade specifications where CDSCO certification barriers limit foreign supplier participation.
Maharashtra
Mumbai and Pune municipal corporations are expanding sodium hypochlorite procurement for urban water treatment networks. The Maharashtra Pollution Control Board enforces discharge norms that accelerate mercury-cell plant retirements in the Thane-Belapur chemical belt. Dahej pipeline connectivity enables chlorine transfer from Gujarat-based membrane cell operators to Maharashtra PVC manufacturers.
Gujarat
Dahej and Mundra industrial zones anchor concentrated demand from vinyl chloride monomer synthesis and intermediate chemical manufacturing. The Gujarat Pollution Control Board layers site-specific effluent standards atop Central Pollution Control Board baselines, multiplying compliance complexity for multi-state operators. Ankleshwar and Vapi chemical estates host legacy chlor-alkali capacity facing costly membrane technology retrofits.
Tamil Nadu
Chennai Metropolitan Water Supply and Sewerage Board tenders consolidate sodium hypochlorite purchases through state-level procurement platforms. The Tamil Nadu Pollution Control Board mandates zero-liquid discharge for chlor-alkali expansions in the Cuddalore chemical cluster. Manali and Ennore industrial zones absorb merchant chlorine for dye intermediate and textile bleaching applications.
Andhra Pradesh
Visakhapatnam Steel Plant and nearby fertilizer complexes drive bulk chlorine offtake through dedicated tanker arrangements. The Andhra Pradesh Pollution Control Board enforces coastal zone regulations that constrain greenfield chlor-alkali siting near Visakhapatnam port. Kakinada and Vijayawada municipal utilities are transitioning from cylinder gas to pre-formulated hypochlorite delivery.
West Bengal
Haldia Petrochemicals and Durgapur industrial belt sustain chlorine demand for captive PVC and chemical intermediate production. The West Bengal Pollution Control Board administers legacy mercury-cell phase-out timelines that lag western state schedules. Asansol and Kalyani manufacturing zones rely on rail-tanker chlorine supply from Gujarat and Maharashtra membrane cell operators.
India Chlorine Market Competitive Landscape
Concentration sits with integrated chlor-alkali operators commanding pipeline delivery networks across the Dahej-Mundra corridor. The competitive structure fragments between membrane cell specialists achieving pharmaceutical-grade certification and legacy mercury-cell merchants facing regulatory extinction. Three archetypes dominate: integrated chemical conglomerates with captive caustic soda offtake, standalone chlor-alkali specialists serving merchant markets, and diversified industrial groups leveraging power cost advantages. Capacity expansion and backward integration into salt and power inputs constitute the primary competitive moves.
Within the integrated chemical conglomerate tier, Chemplast Sanmar Limited and Grasim Industries Limited exemplify scale-driven positioning through western India manufacturing concentration. Tata Chemicals Limited occupies a specialty-grade position targeting CDSCO-regulated pharmaceutical applications. These three entities represent divergent strategic pathways—chlor-alkali integration, regional supply anchoring, and premium certification pursuit—without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Chemplast Sanmar Limited |
| Reliance Industries Limited |
| Grasim Industries Limited |
| Gujarat Fluorochemicals Ltd. |
| Tata Chemicals Limited |
| Gujarat Alkalies and Chemicals Limited |
| Nirma Limited |
| Meghmani Finechem Limited |
| DCM Shriram |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with price escalation clauses dominate chlorine procurement across Gujarat's Dahej-Mundra corridor, locking in supply access for PVC manufacturers while embedding caustic soda co-product pricing into chlorine cost visibility. These contract structures insulate membrane cell operators from spot market volatility while forcing legacy mercury-cell merchants into margin compression.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across western India, with pricing stratifying across pharmaceutical-grade, food-grade, and industrial-grade tiers based on BIS certification levels and CDSCO impurity documentation. Cost compression in industrial-grade segments is intensifying because municipal utilities are consolidating sodium hypochlorite procurement through state tendering platforms. Water utilities exhibit the highest price sensitivity due to budget-constrained public procurement, while pharmaceutical manufacturers demonstrate lowest sensitivity given CDSCO compliance requirements.
Supply Chain Analysis
India and select Middle Eastern producers anchor merchant chlorine supply to South Asian markets, with Dahej and Mundra industrial zones feeding pipeline networks across Gujarat and Maharashtra. Domestic membrane cell capacity draws from captive salt sourcing and grid power arrangements, with ion-exchange membrane imports resting on limited supplier bases in Japan and Germany. Single-source vulnerability concentrates in specialized membrane stack procurement. Distribution runs through dedicated tanker and pipeline networks to integrated chemical manufacturers, with packaged cylinder gas and drum formulations reaching fragmented municipal utilities via regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane cell engineering expertise and pharmaceutical-grade certification capabilities represent the critical scarcity layer in this market, with qualified process engineers commanding premium compensation and extended recruitment timelines.
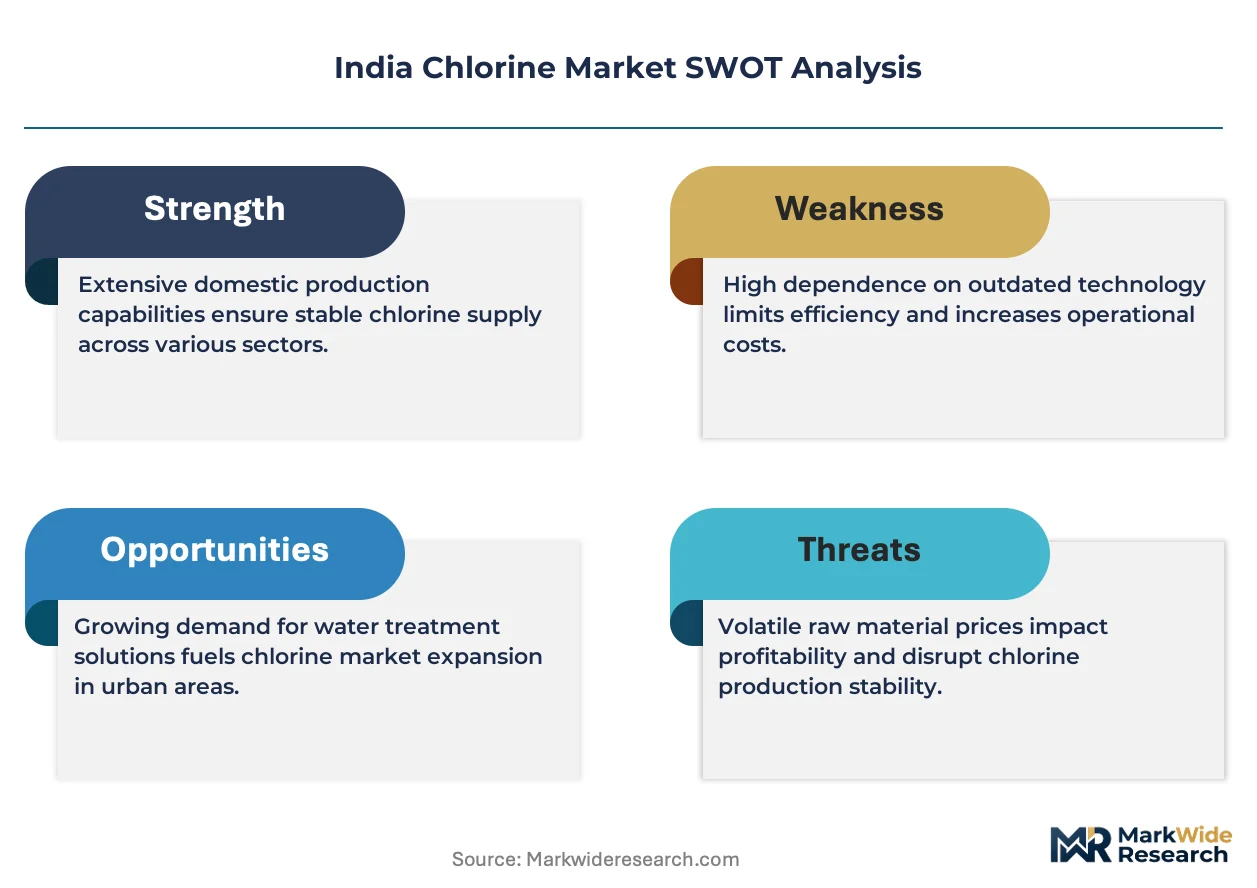
For Market Incumbents: Compound membrane technology leadership through third-generation ion-exchange stack upgrades at Dahej and Mundra installations, while securing pharmaceutical-grade CDSCO certification to capture premium pricing tiers unavailable to industrial-grade competitors. Mercury-cell legacy liabilities from Central Pollution Control Board enforcement threaten stranded capital for non-compliant operators. For New Entrants and Emerging Players: Anchor in sodium hypochlorite formulation and technical service capabilities for Maharashtra and Gujarat municipal utilities bypassing merchant chlorine gas entirely. Direct hypochlorite supply to state water boards represents the most penetrable segment, with packaged chemical distribution offering lower capital barriers than integrated chlor-alkali construction. For Investors and Strategic Acquirers: Capital is best deployed toward membrane cell specialists with existing pharmaceutical-grade certification and pipeline connectivity to western India chemical corridors. Long-term viability hinges on regulatory compliance trajectory rather than commodity pricing cycles. The signal to watch is Gujarat Pollution Control Board acceleration of mercury-cell phase-out timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Upgrade | Third-generation ion-exchange stacks reduce power consumption per ton of chlorine output at Dahej installations. |
| Pharmaceutical-Grade Certification | CDSCO impurity documentation unlocks premium pricing tiers for active ingredient manufacturing supply. |
| Backward Integration into Salt | Captive brine sourcing insulates membrane cell operators from imported salt price volatility. |
| Sodium Hypochlorite Formulation Capacity | Pre-formulated delivery meets Maharashtra and Gujarat municipal utility procurement consolidation. |
| Pipeline Network Expansion | Dedicated chlorine transfer infrastructure connects Gujarat production to Maharashtra PVC manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across chlor-alkali plant managers, procurement leads at PVC and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors at membrane technology suppliers. Secondary validation incorporated customs and trade data, BIS certification registries, CDSCO pharmaceutical filings, and state pollution control board discharge compliance records. Bottom-up capacity modeling and top-down demand estimation were triangulated to reconcile production economics with end-use offtake patterns.
Across the projection horizon, the analytical framework modeled segmentation across grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from installed capacity expansion timelines, technology diffusion curves for membrane cell adoption, and regulatory enforcement schedules for mercury-cell phase-out. Industry-specific forecast inputs included caustic soda co-product pricing interdependence and municipal utility procurement modernization trajectories.
Underlying assumptions cover membrane technology cost reduction trajectories and state-level environmental compliance timelines, with deviation risk concentrated in Central Pollution Control Board enforcement acceleration and caustic soda market pricing volatility. Recalibration cycles align with material shifts in PLI scheme disbursement patterns and mercury-cell plant closure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Meta Tartaric Acid Market