
 Carbamide Market | 2026-2036
Carbamide Market Size, Share, and Industry Trends Forecast 2026-2036
Carbamide Market Analysis
REACH compliance is decoupling European production economics from legacy cost structures, forcing capital-intensive upgrades at older ammonia-urea complexes. CF Industries Holdings, Inc. leverages its Gulf Coast feedstock access to sustain export competitiveness into premium-regulation markets. Yara International ASA anchors its position through integrated ammonia-carbamide operations on three continents. Nutrien Ltd. controls extensive North American distribution infrastructure that extends its farmer-direct reach beyond commodity pricing cycles.
Carbamide, chemically urea (CO(NH₂)₂), is a nitrogen-rich organic compound synthesized via the Bosch-Haber reaction of ammonia and carbon dioxide under high pressure, typically containing 46% nitrogen by weight and serving as the world's most concentrated solid nitrogen fertilizer. The granular and prilled product types dominate volume trade, with coated variants commanding premium positioning where controlled-release agronomy justifies higher input costs. Agricultural application absorbs the majority of offtake, though pharmaceutical-grade purification requirements create concentrated margin pools for laboratory and chemical manufacturer end users. Wholesale and direct sales channels handle bulk fertilizer movements, while online distribution is gaining traction among horticulturists managing smaller plot sizes.
The EPA regulates carbamide emissions under Clean Air Act ammonia provisions, while India's FSSAI and BIS enforce fertilizer-grade quality thresholds that determine market access for domestic and imported supply. ECHA's REACH framework restricts certain anti-caking additives, redirecting formulation R&D toward compliant coating chemistries. Stakeholders must monitor evolving carbon border adjustment mechanisms and low-carbon ammonia certification schemes that will resegment supplier competitiveness regardless of feedstock geography.
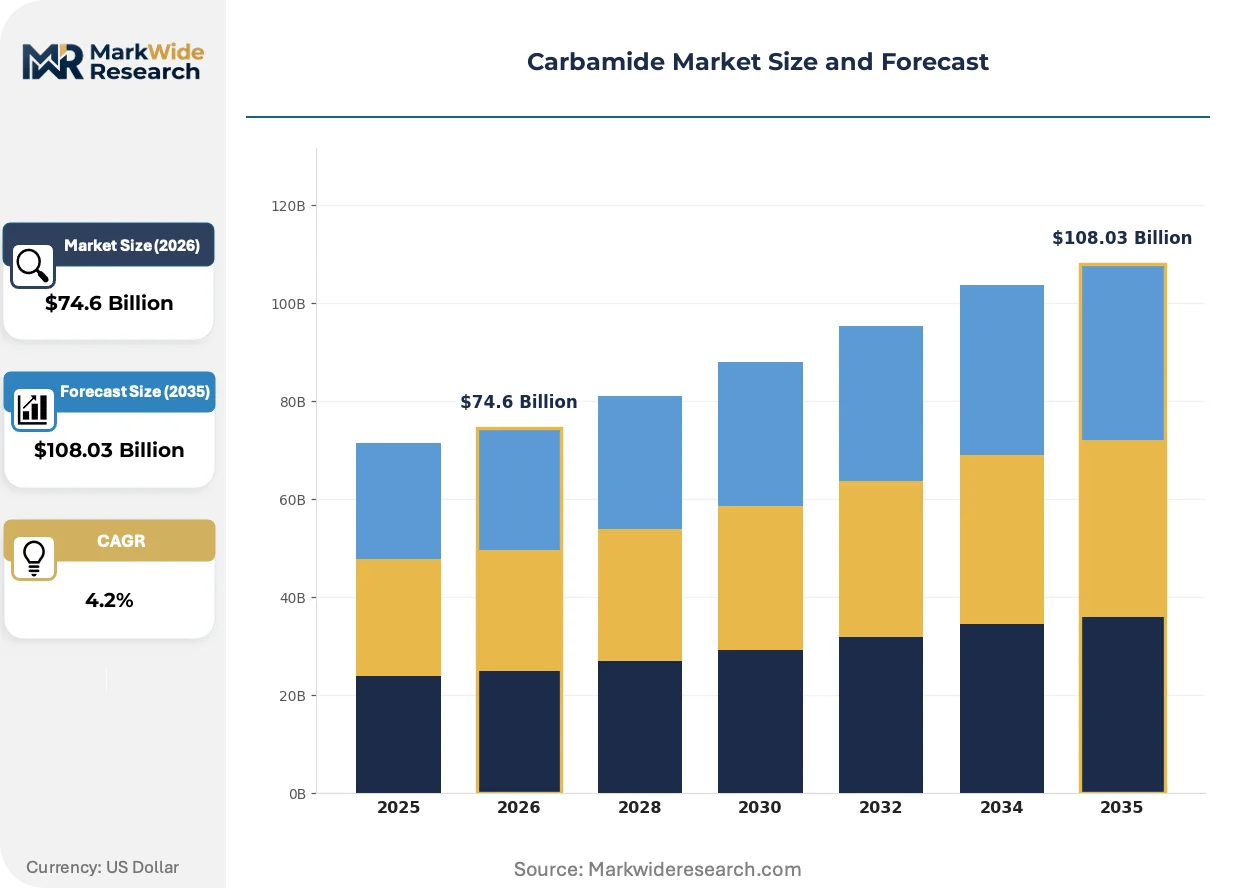
Market Dynamics
Low-carbon ammonia certification schemes and carbon border adjustment mechanisms are fragmenting supplier competitiveness by feedstock geography, forcing capital reallocation toward renewable hydrogen integration at existing carbamide complexes.
Growth Catalysts
- EU F-Gas Regulation:Tightening production benchmarks across European jurisdictions accelerate facility upgrades that improve process efficiency and yield recovery rates at legacy ammonia-urea plants.
- Precision farming adoption:Brazilian agricultural operations expand fertilizer-grade carbamide consumption through variable-rate application technologies that optimize nitrogen use efficiency per hectare.
- Subsidized irrigation expansion:India's agricultural heartland sustains bulk procurement volumes through government-supported water infrastructure that enables intensive cropping cycles demanding sustained nitrogen input.
Market Restraints
- Natural gas cost volatility:Feedstock price swings compress margins at non-integrated producers lacking captive ammonia supply or long-term supply agreements with indexed pricing.
- REACH compliance costs:ECHA restrictions on anti-caking additives redirect formulation R&D expenditure toward compliant coating chemistries without immediate volume recovery.
- Controlled-release substitutes:Polymer-coated fertilizers and nitrification inhibitors capture premium agronomy segments where application labor costs justify higher input expenditure.
Strategic Opportunities
- Pharmaceutical-grade purification:Laboratory and chemical manufacturer end users create concentrated margin pools through specification-grade production that commands pricing multiples above commodity fertilizer grades.
- Online distribution channels:Horticulturists managing smaller plot sizes bypass wholesale bulk movements through direct-to-grower platforms that aggregate fragmented demand.
- India's PLI scheme alignment:Domestic production incentives for green hydrogen and ammonia feedstock integration position local manufacturers for export competitiveness into carbon-regulated markets.
Industry Challenges
- Process engineer scarcity:Specialized talent for high-pressure synthesis unit optimization and catalyst management concentrates at integrated petrochemical complexes, constraining independent facility expansion.
- Carbon certification timeline:Low-carbon ammonia verification protocols lack harmonized standards across EU, Japan, and South Korean import regimes, complicating multi-jurisdiction market access planning.
- Legacy asset retrofit complexity:Steam reformer integration with electrolytic hydrogen supply requires extended outage windows that disrupt contracted offtake schedules during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbamide Market |
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $108.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Prilled, Liquid, Coated Application: Agriculture, Fertilizers, Pharmaceuticals, Industrial Distribution Channel: Online, Retail, Wholesale, Direct Sales End User: Chemical Manufacturers, Farmers, Laboratories, Horticulturists |
| Companies Covered | CF Industries Holdings, Inc., Yara International ASA, Nutrien Ltd., OCI N.V., SABIC Agri-Nutrients Company, Pupuk Indonesia (Persero), Chambal Fertilisers and Chemicals Limited, Acron Group, EuroChem Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbamide Market Emerging Trajectories
Electrolytic hydrogen feedstock substitution and carbon capture retrofitting are compressing the cost differential between conventional and low-carbon carbamide production pathways.
Electrolytic ammonia synthesis is electrifying the front end of carbamide production by replacing steam methane reformers with polymer electrolyte membrane stacks powered by renewable electricity. Nordic and Iberian producers pilot 20 MW demonstration units that match Haber-Bosch pressure specifications. This technology is electrifying capital deployment patterns as project finance shifts from gas-linked offtake structures to power purchase agreement-backed green hydrogen supply contracts.
REACH framework evolution restricts specific anti-caking additive chemistries previously standard in granular and prilled formulations. ECHA substance evaluation redirects coating R&D toward bio-based alternatives including modified starches and lignin derivatives. European formulators absorb compliance costs through specification-grade product lines while Asian exporters face border testing protocols that delay customs clearance.
Farmer-direct procurement platforms disintermediate traditional wholesale distribution for horticultural and specialty crop segments. Digital marketplaces aggregate small-lot demand from greenhouse operators and organic certification holders who require traceable supply chains. This channel compression concentrates in the Netherlands, Spain, and California where high-value crop density supports logistics cost absorption.
Carbamide Market Segmentation
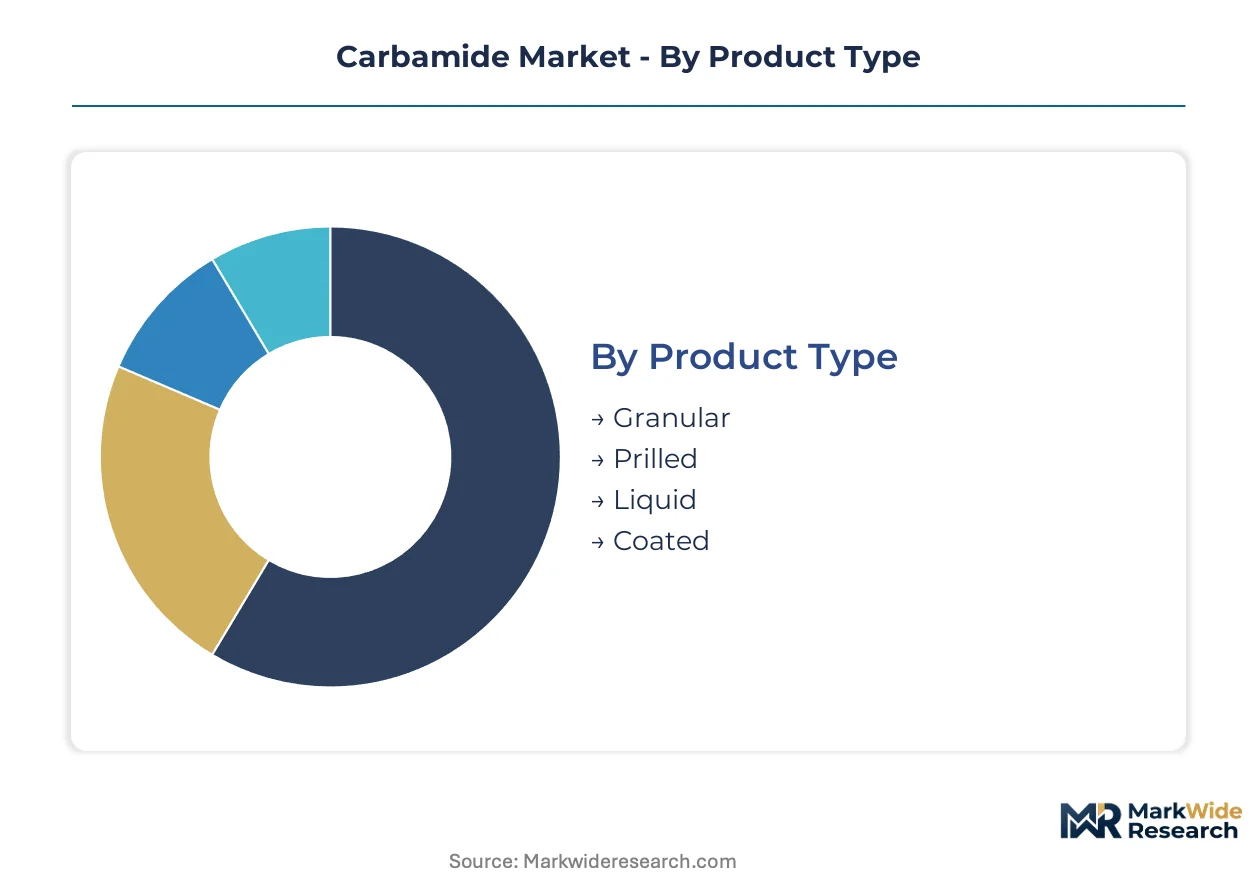
Carbamide segmentation reflects divergent purity requirements and logistics economics across commodity fertilizer flows versus specification-grade industrial offtake. Physical form and coating technology determine handling characteristics, nitrogen release profiles, and applicable regulatory frameworks from farm gate to pharmaceutical cleanroom.
Product Type:
Physical specification dictates storage stability, application equipment compatibility, and premium capture potential through controlled-release engineering.
- Granular:Spherical particles manufactured through fluidized-bed processing achieve superior crush strength for bulk handling and pneumatic spreading equipment. Brazilian precision farming operations favor this format for variable-rate application systems that calibrate nitrogen delivery by soil zone. Granular leads on scale; Coated leads on momentum.
- Prilled:Molten carbamide droplets solidify into uniform spheres through tower cooling, offering lower production energy intensity than granular alternatives. Indian subsidized procurement programs absorb substantial prilled volumes for flood-irrigated rice cultivation where rapid nitrogen dissolution matches crop uptake timing.
- Liquid:Aqueous solutions containing dissolved carbamide enable foliar feeding and fertigation integration with drip irrigation infrastructure. Greenhouse operators in the Netherlands and Spain leverage liquid formulations for precision nutrient dosing in substrate-grown high-value crops.
- Coated:Polymer or sulfur encapsulation layers regulate nitrogen release kinetics across extended crop growth cycles. ECHA REACH restrictions on legacy coating chemistries redirect R&D toward bio-based alternatives including modified starches and lignin derivatives.
Granular dominates volume throughput; Coated commands the steepest expansion trajectory through premium agronomy adoption.
Application:
End-use concentration separates bulk commodity flows from specification-grade margin pools with divergent certification and purity thresholds.
- Agriculture:Soil-incorporated nitrogen supplementation for cereal, oilseed, and fiber crops consumes the majority of global carbamide production. Indian irrigation expansion and Brazilian no-till farming sustain bulk procurement volumes through government price support and carbon-sequestration-linked agronomy.
- Fertilizers:Formulated blends incorporating carbamide with phosphate and potassium sources address balanced nutrition requirements. Specialty fertilizer manufacturers in Germany and China compound controlled-release variants for export into premium-regulation markets.
- Pharmaceuticals:United States Pharmacopeia and European Pharmacopoeia compliance mandates multi-stage crystallization and heavy-metal testing for excipient and active pharmaceutical ingredient applications. Laboratory and chemical manufacturer demand concentrates margin in this segment despite fractional volume share.
- Industrial:Urea-formaldehyde resin feedstock, diesel exhaust fluid, and chemical synthesis applications require technical-grade purity without agricultural certification overhead. AdBlue manufacturing for EU heavy-duty vehicle emission compliance sustains dedicated industrial-grade supply chains.
Agriculture anchors absolute volume; Pharmaceuticals generates the highest margin per ton through specification-grade purification requirements.
Distribution Channel:
Channel selection reflects lot size economics and traceability requirements from bulk commodity movements to direct-to-grower platforms.
- Online:Digital marketplaces aggregate fragmented horticultural demand from greenhouse operators and organic certification holders requiring documented supply chain provenance. California and Spanish platforms bypass traditional wholesale tiers for specialty crop inputs.
- Retail:Farm supply cooperatives and garden centers handle bagged quantities for smallholder and consumer horticulture segments. Nutrien's North American retail network exemplifies farmer-direct infrastructure extending beyond commodity pricing cycles.
- Wholesale:Bulk terminal and barge movements dominate intercontinental fertilizer-grade flows from Gulf Coast and Middle Eastern production hubs. Long-term offtake agreements with indexed natural gas pricing protect margin at integrated producers.
- Direct Sales:Large-scale farming cooperatives and industrial consumers negotiate volume contracts bypassing distributor markups. CF Industries leverages Gulf Coast feedstock access to sustain export competitiveness through direct supply relationships.
Wholesale commands intercontinental volume; Online is gaining share fastest among horticultural and specialty crop segments.
End User:
Customer type determines purity specifications, procurement scale, and regulatory documentation requirements from commodity farm gate to pharmaceutical cleanroom.
- Chemical Manufacturers:Technical-grade carbamide serves as feedstock for melamine, urea-formaldehyde resins, and diesel exhaust fluid production. Process integration with captive ammonia supply characterizes competitive positioning in this segment.
- Farmers:Subsidized procurement programs in India and precision agriculture adoption in Brazil concentrate demand among large-scale commercial operations. Variable-rate application technologies optimize nitrogen use efficiency per hectare.
- Laboratories:Analytical reagent and cell culture applications require pharmaceutical-grade purity with comprehensive certificate of analysis documentation. Concentrated margin pools reward specification-grade production despite limited volume.
- Horticulturists:Greenhouse operators and specialty crop producers prioritize soluble and coated formulations for substrate and hydroponic systems. Direct procurement platforms disintermediate wholesale distribution in high-value crop clusters.
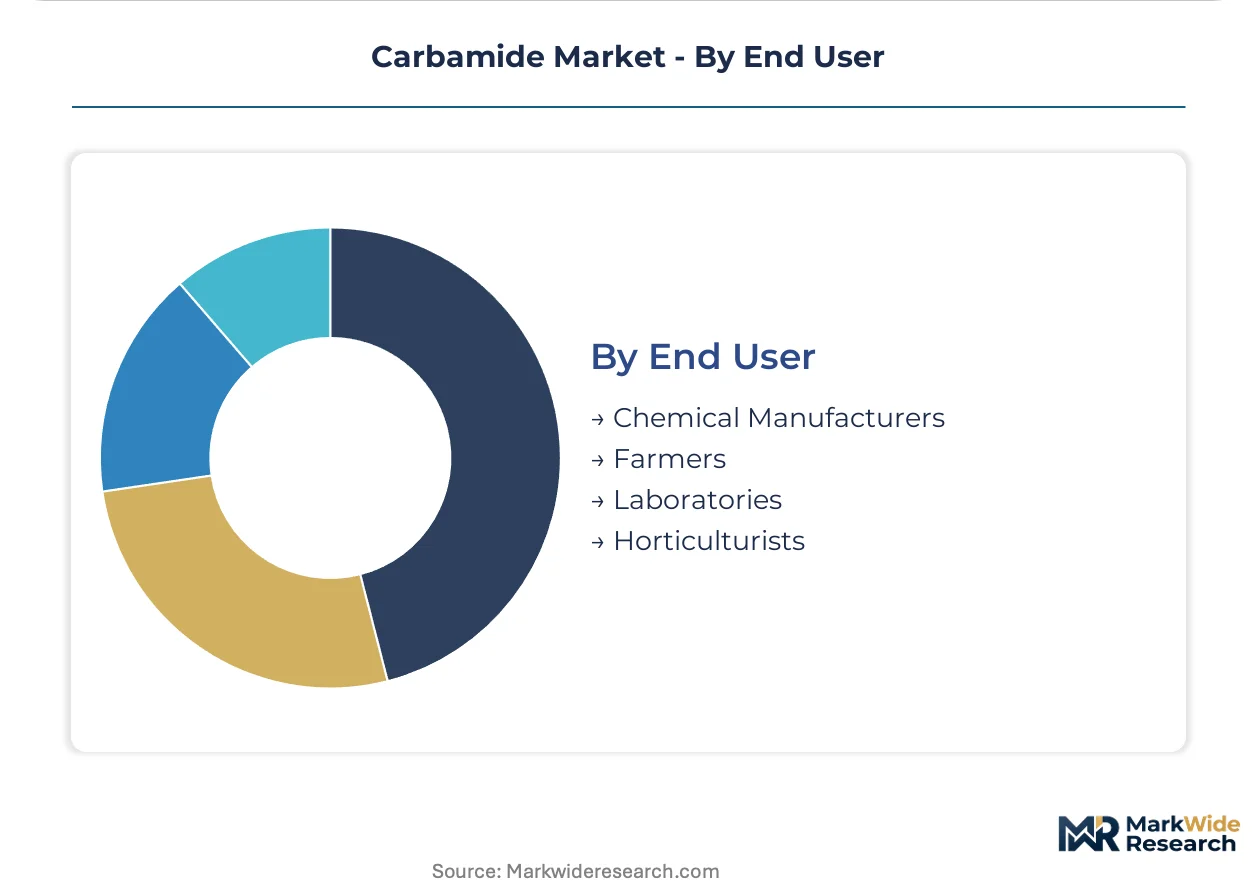
Farmers represent the largest addressable base; Laboratories extract the highest value per kilogram through certification-intensive supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineering talent for high-pressure ammonia synthesis concentrates in the US Gulf Coast, Rotterdam-Antwerp corridor, and Mumbai-Pune industrial belt, anchoring competitive production economics in these geographies.
United States
Shale gas feedstock access sustains cost-competitive ammonia production along the Gulf Coast, with Louisiana and Texas complexes serving export markets. EPA Clean Air Act ammonia provisions regulate stack emissions and storage facility design standards. The Houston Ship Channel corridor hosts integrated ammonia-carbamide operations that leverage pipeline natural gas pricing indexed to Henry Hub.
India
Subsidized urea procurement under the New Urea Policy sustains bulk consumption across Uttar Pradesh, Punjab, and Haryana agricultural belts. FSSAI and BIS enforce fertilizer-grade quality thresholds that determine import eligibility and domestic manufacturing licensing. The Gujarat industrial corridor hosts coal-gasification based ammonia complexes that supply western state fertilizer demand.
Brazil
Precision farming adoption in Mato Grosso and Paraná expands variable-rate carbamide application for soybean and corn cultivation. ANVISA regulates agricultural chemical formulations while MAPA oversees fertilizer registration and import quotas. The Santos port complex handles bulk urea imports from Middle Eastern suppliers for redistribution to interior farming cooperatives.
Germany
REACH compliance mandates redirect coating formulation R&D toward bio-based anti-caking alternatives at legacy ammonia-urea complexes. ECHA substance evaluation protocols restrict specific additive chemistries previously standard in granular products. The Ludwigshafen chemical cluster maintains technical expertise for pharmaceutical-grade carbamide purification serving European laboratory demand.
China
Coal-based ammonia production dominates feedstock economics in Inner Mongolia and Shanxi provinces, though dual carbon goals accelerate renewable hydrogen pilot integration. MIIT and MEE enforce industrial emissions standards and carbon intensity benchmarks for chemical sector operations. The Yangtze River Delta concentrates urea-formaldehyde resin manufacturing for wood panel and adhesive applications.
Carbamide Market Vendor Landscape
The competitive structure tilts toward integrated ammonia-carbamide operators with captive feedstock supply. Gulf Coast and Middle Eastern producers leverage indexed natural gas contracts to sustain export competitiveness into premium-regulation markets. Three archetypes dominate: vertically integrated petrochemical conglomerates, regional fertilizer cooperatives with government-backed procurement access, and specialty chemical purifiers serving pharmaceutical-grade specification tiers. Capacity expansion and backward integration into ammonia synthesis represent the dominant competitive vectors.
Among North American integrated producers, CF Industries Holdings, Inc. exemplifies Gulf Coast feedstock positioning, while Nutrien Ltd. anchors farmer-direct distribution infrastructure across the continent. Yara International ASA represents the multi-continental integrated archetype with ammonia-carbamide operations spanning European, American, and Asian production hubs.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Yara International ASA |
| Nutrien Ltd. |
| OCI N.V. |
| SABIC Agri-Nutrients Company |
| Pupuk Indonesia (Persero) |
| Chambal Fertilisers and Chemicals Limited |
| Acron Group |
| EuroChem Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmaceutical and fertilizer tiers fragments both pricing power and sourcing networks, with USP-grade purification commanding premium multiples while commodity urea flows through indexed natural gas contracts and bulk terminal economics. This bifurcation concentrates margin recovery in specification-grade channels while compressing returns at spot-market exposed producers lacking captive ammonia supply.
Pricing Analysis
Bundled long-term offtake agreements with indexed Henry Hub pricing dominate Gulf Coast export economics, while unbundled spot purchases expose Indian and Brazilian importers to volatile Middle Eastern ammonia benchmarks. Price differentiation hinges on nitrogen purity certification and controlled-release coating technology, with polymer-encapsulated variants capturing agronomy premiums. Cost compression in prilled commodity grades intensifies as coal-gasification supply from China floods Asian procurement tenders. Smallholder cooperatives in India's subsidized procurement system exhibit acute price sensitivity, while European pharmaceutical laboratories absorb specification-grade premiums without volume elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Santos anchor hub-and-spoke patterns for intercontinental fertilizer movements, with coastal ammonia terminals feeding inland blending facilities. Production concentrates in the United States, China, and India, with Middle Eastern exporters maintaining swing capacity for Atlantic and Pacific basin arbitrage. The network draws from natural gas, coal, and emerging electrolytic hydrogen feedstocks, exposing margin structures to energy commodity volatility. Single-source vulnerability concentrates in catalyst supply for high-pressure synthesis units, predominantly sourced from German and Japanese specialty chemical manufacturers. Distribution runs through wholesale cooperatives for bulk farm procurement, while direct-to-grower platforms disintermediate horticultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbamide functions as a stable compounder anchored by non-discretionary agricultural demand, with nitrogen input intensity proving inelastic to commodity cycles across subsidized procurement regimes.
For Market Incumbents: Cement feedstock security through backward integration into ammonia synthesis or long-term indexed supply agreements, defending against margin compression from renewable hydrogen entrants. Prioritize REACH-compliant coating R&D investment to preserve European market access as ECHA restrictions harden. Capacity consolidation in the US Gulf Coast and Middle East reinforces export competitiveness into carbon-regulated jurisdictions. For New Entrants and Emerging Players: The premium-economy price-point gap in controlled-release fertilizers opens white-space targeting for horticultural and specialty crop segments bypassing wholesale distribution. India's PLI-aligned green hydrogen ammonia production offers penetrable domestic manufacturing positioning for export into EU carbon border adjustment mechanisms. Direct-to-grower digital platforms provide the most accessible go-to-market channel for fragmented greenhouse operator demand. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy ammonia-urea complexes face stranded asset risk from low-carbon certification mandates and electrolytic hydrogen retrofit requirements. Long-term viability favors integrated operators with captive feedstock and multi-continental production footprints. Target acquisition archetypes include regional fertilizer cooperatives with government procurement access and specialty chemical purifiers with pharmaceutical-grade certification infrastructure. The signal to watch is harmonization progress across EU, Japanese, and South Korean low-carbon ammonia verification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolytic Hydrogen Integration | Renewable ammonia synthesis reconfigures feedstock economics at Gulf Coast and Nordic demonstration facilities. |
| REACH-Compliant Coating Development | Bio-based anti-caking alternatives preserve European market access under evolving ECHA substance evaluations. |
| Farmer-Direct Platform Expansion | Digital marketplaces aggregate fragmented horticultural demand in California and Dutch greenhouse clusters. |
| Pharmaceutical-Grade Purification Investment | USP and EP certification unlocks concentrated margin pools from laboratory and excipient manufacturers. |
| Indexed Long-Term Offtake Structuring | Henry Hub-linked contracts protect margin at integrated producers against spot natural gas volatility. |
Methodological Framework
Bottom-up agricultural consumption modeling reconciled against top-down ammonia production tracking forms the analytical core, combining primary interviews with plant managers at integrated urea complexes, procurement leads at downstream fertilizer blenders, distribution channel partners in Indian cooperatives, and technical R&D directors at European coating formulators. Secondary validation draws from customs and trade flow databases, SEC 10-K filings of listed nitrogen producers, Fertilizer Association of India consumption statistics, and ECHA substance evaluation registers. Cross-referencing facility-level capacity data against national procurement program disclosures enables supply-demand reconciliation.
Historical trendline analysis across nitrogen fertilizer intensity per hectare, natural gas price volatility bands, and regulatory compliance cost trajectories informs projection parameters. Segmentation modeling incorporates grade tier (fertilizer versus pharmaceutical), physical form (granular, prilled, liquid, coated), end-use industry concentration, and regional production hub configuration. CAGRs derive from fitted trend extrapolation moderated by policy scenario weighting, with electrolytic hydrogen adoption curves and carbon border adjustment implementation timelines serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for renewable hydrogen integration at scale would alter the outlook through accelerated asset obsolescence at steam-reformer-dependent facilities. Forecasts reflect stated assumptions regarding subsidy continuity, regulatory enforcement intensity, and feedstock price correlation structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Barium Sulphate Market