
 Fixed Tilt Solar PV Market | 2026-2036
Fixed Tilt Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Tilt Solar PV Market Analysis
Utility buyer concentration is broadening as independent power producers and municipal co-ops diversify procurement beyond traditional vertically integrated developers. Nextracker leverages its tracking-adjacent engineering expertise to compete in fixed-tilt adjacent bids, while RBI Solar anchors its position through heavy-gauge steel fabrication capabilities for utility-scale ground mounts. Unirac sustains rooftop share through modular rail systems that reduce labor hours on commercial installations.
Fixed Tilt Solar PV denotes stationary photovoltaic mounting structures set at a predetermined angle, typically constructed from galvanized steel or aluminum with corrosion-resistant coatings, designed to maximize annual energy yield without motorized tracking. The primary purpose is to minimize capital expenditure and operational complexity while delivering predictable performance across 25-30 year asset lifetimes. Mono-crystalline modules command premium positioning in utility-grade fixed-tilt deployments where energy density per hectare drives returns. Ground-mounted installations dominate volume, though carport configurations extract incremental value from parking infrastructure without land-use competition.
FERC interconnection standards and state renewable portfolio obligations in California, Texas, and Arizona shape utility procurement timelines and racking specification requirements. India's CEA mandates stringent structural load certifications for cyclone-prone regions, filtering import-dependent suppliers from project bids. Stakeholders must monitor evolving domestic content thresholds under the US IRA and India's PLI scheme, as tariff and incentive eligibility increasingly hinges on country-of-origin documentation for steel and aluminum structural components.
Market Dynamics
Interconnection queue congestion across US ISO territories is compressing project development timelines and forcing developers toward standardized, rapidly deployable racking configurations that minimize engineering variability and accelerate permitting.
Growth Catalysts
- Domestic Content Incentives:The US IRA's domestic manufacturing tax credits are redirecting procurement toward North American steel and aluminum fabrication, accelerating localized supply chain development for structural components.
- Utility-Scale Procurement Expansion:Independent power producers and municipal cooperatives are diversifying procurement portfolios, creating volume opportunities for fixed-tilt systems in Texas and Arizona interconnection clusters.
- High-Irradiance Site Development:Concentrated solar resource development in the American Southwest reduces balance-of-system costs per megawatt, improving project returns on flat terrain without tracking complexity.
Market Restraints
- Steel Price Volatility:Galvanized steel coil pricing fluctuations directly impact racking system costs, compressing margins for fabricators locked into fixed-price EPC contracts.
- Import Supply Concentration:Reliance on Southeast Asian aluminum extrusion creates tariff exposure and delivery uncertainty under evolving US trade remedy frameworks.
- Tracking Technology Substitution:Single-axis trackers capture incremental energy yield in high-DNI environments, displacing fixed-tilt configurations where land constraints permit motorization.
Strategic Opportunities
- Carport Infrastructure Integration:Parking canopy deployments extract value from commercial real estate without land-use competition, opening municipal and retail verticals.
- India PLI Scheme Alignment:India's production-linked incentive scheme for solar manufacturing is creating domestic racking supply chain capacity for cyclone-certified structural systems.
- Bifacial Module Pairing:Elevated fixed-tilt configurations optimized for bifacial gain are capturing utility interest where ground albedo conditions support rear-side generation.
Industry Challenges
- Structural Engineering Talent Scarcity:Qualified geotechnical and wind-load specialists are concentrated among incumbent EPCs, constraining rapid project scaling.
- CEA Certification Timelines:India's Central Electricity Authority mandates extended testing protocols for cyclone-prone coastal zones, delaying equipment qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Tilt Solar PV Market |
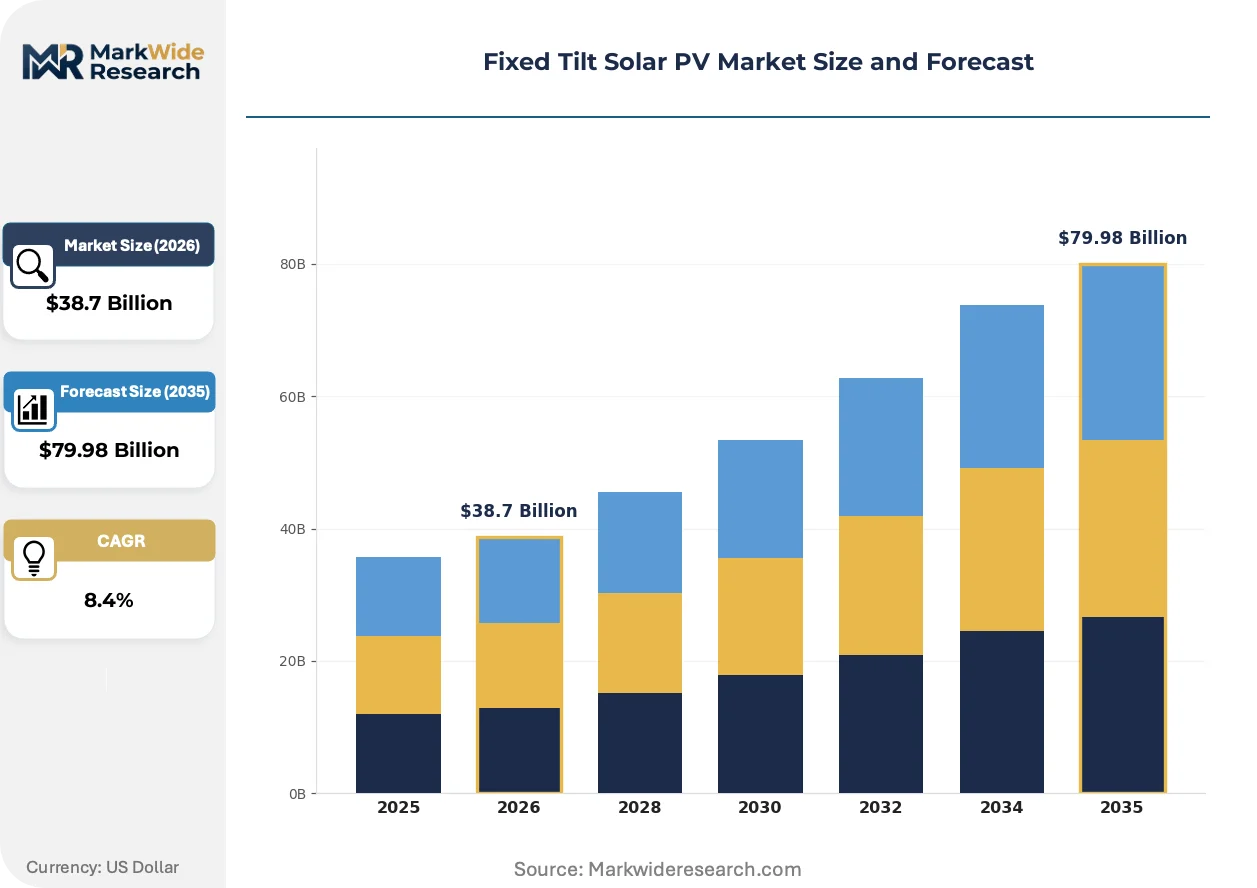
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-crystalline, Poly-crystalline, Thin-film, Bifacial Installation Type: Ground-mounted, Rooftop, Carport, Building-integrated End User: Residential, Commercial, Industrial, Utilities Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Nextracker, Inc., RBI Solar, LLC, Unirac, Inc., PV Hardware Manufacturing Co., Ltd., GameChange Solar, Inc., Mounting Systems GmbH, Schletter Group GmbH, SunLink Corporation, Clenergy Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Tilt Solar PV Market Emerging Trajectories
Racking system architecture is converging with module form factor evolution and installation robotics, compressing labor hours and standardizing field assembly sequences across utility-scale deployments.
Pre-assembled torque tube and pile cap systems are modularizing field installation workflows. EPC contractors in Texas and Arizona are adopting these configurations to reduce crew sizing and accelerate mechanical completion timelines. Standardized connection geometries are modularizing procurement, enabling multi-project volume aggregation and reducing per-watt installation costs.
The US Inflation Reduction Act's domestic content bonus credit is restructuring supply chain geography. Steel and aluminum structural components must demonstrate North American provenance to qualify for incremental tax credits. Utility-scale developers are responding by qualifying domestic fabricators and documenting mill certificates through project financial close.
Buyer procurement patterns are consolidating around multi-year master service agreements with integrated EPC-racking providers. Traditional component bidding is yielding to turnkey contracting in California and Texas utility markets. This consolidation is compressing vendor margins while locking in volume commitments through 2028-2030 construction windows.
Fixed Tilt Solar PV Market Segmentation
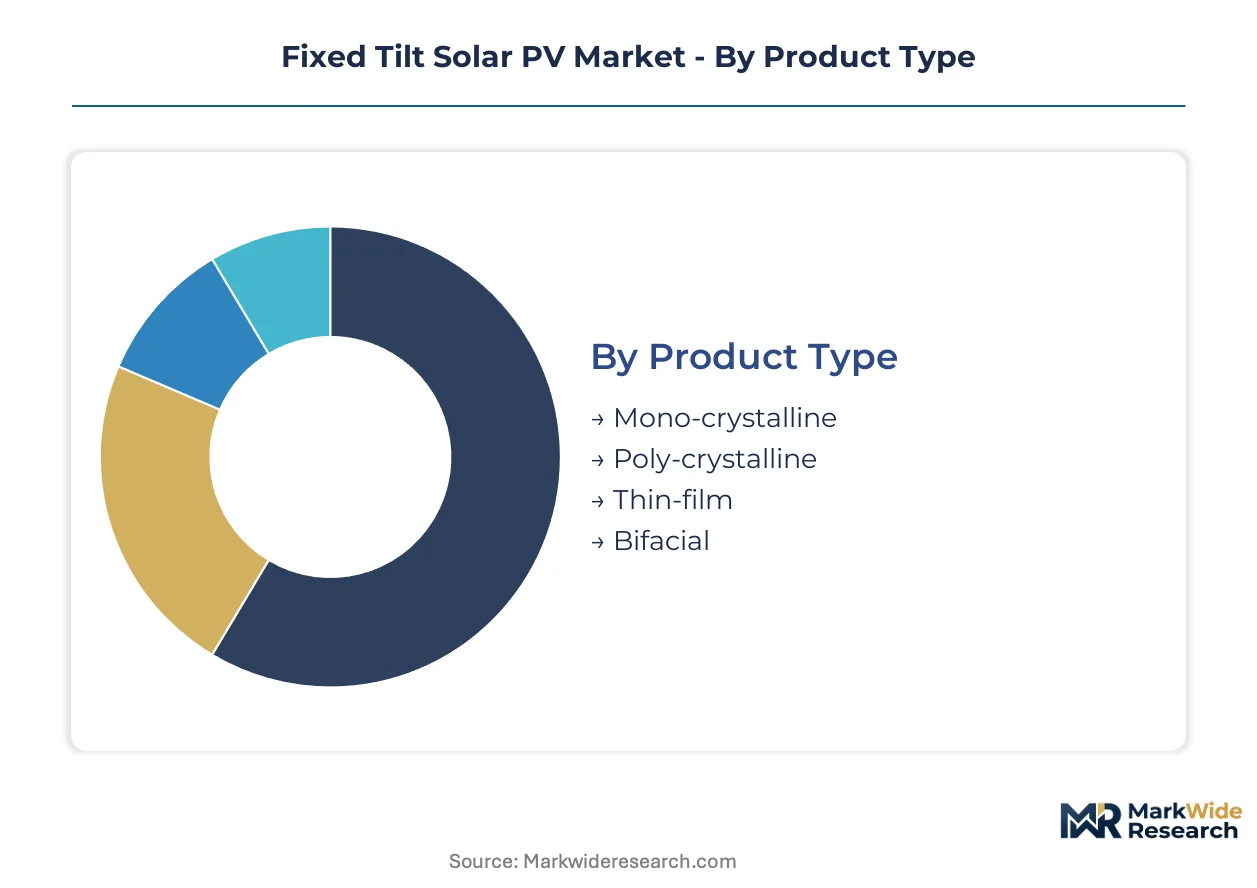
Segmentation in fixed-tilt solar PV reveals how technology choices cascade through procurement economics and installation logistics. Module efficiency tiers, mounting configurations, and buyer sophistication levels each create distinct margin structures and competitive dynamics for racking suppliers.
Product Type:
Mono-crystalline and bifacial segments command integration depth through utility-scale standalone deployments, while poly-crystalline and thin-film increasingly embed into distributed commercial systems where space constraints matter less.
- Mono-crystalline:Silicon ingots sliced from single-crystal boules deliver conversion efficiencies exceeding 21% in standard test conditions. Utility developers in Arizona and Texas specify mono-crystalline modules for fixed-tilt arrays where energy density per hectare drives project returns, though cell cracking during field handling elevates installation labor costs.
- Bifacial:Dual-sided cell architecture captures albedo-reflected irradiance from ground surfaces, boosting yield 5-20% depending on terrain reflectivity. Elevated fixed-tilt configurations in the American Southwest optimize rear-side gain on high-albedo desert soils, creating differentiated procurement specifications for racking height and row spacing.
- Poly-crystalline:Multi-crystalline silicon wafers trade efficiency for lower manufacturing energy intensity, finding residual demand in price-sensitive commercial rooftop segments.
- Thin-film:Cadmium-telluride and CIGS deposition on glass substrates offers temperature coefficient advantages in hot climates, though module area requirements limit utility-scale penetration.
Mono-crystalline leads volumes today; bifacial is gaining share fastest.
Installation Type:
Ground-mounted systems dominate capital deployment scale, while carport and building-integrated configurations extract value from otherwise unproductive real estate with higher structural engineering complexity.
- Ground-mounted:Steel-driven pile or ballasted foundations anchor arrays on open terrain with standardized torque-tube assemblies. Texas and Arizona utility clusters specify ground-mounted fixed-tilt for interconnection queue acceleration, compressing mechanical completion timelines through pre-assembled module-table configurations.
- Carport:Elevated canopy structures spanning parking infrastructure combine solar generation with vehicle shading, commanding structural steel premiums for column and beam spans. Municipal procurement in California targets carport deployments for school and transit authority sites where land availability constrains ground-mounted alternatives.
- Rooftop:Low-profile fixed-tilt rails attach to commercial membrane or metal roofing through penetrating or ballasted connections, with wind-uplift certification driving fastener specification.
- Building-integrated:PV modules substitute for conventional building envelope materials in facade or skylight applications, requiring architectural-grade framing integration and fire-rating compliance.
Ground-mounted leads volumes today; carport is expanding most quickly.
End User:
Utility buyers concentrate procurement scale through multi-year master service agreements, while commercial and industrial segments fragment across regional EPC relationships with shorter contracting horizons.
- Utilities:Vertically integrated power producers and independent generators procure fixed-tilt systems through integrated EPC-racking contracts spanning hundreds of megawatts. FERC interconnection standards and state renewable portfolio obligations in California, Texas, and Arizona shape specification requirements and equipment qualification timelines.
- Commercial:Retail chains, logistics facilities, and office portfolios deploy rooftop and carport configurations under power-purchase agreements with third-party owners, prioritizing rapid installation to minimize operational disruption.
- Industrial:Manufacturing facilities and data centers specify high-capacity fixed-tilt arrays for behind-the-meter consumption, with load-matching requirements driving DC-AC ratio optimization.
- Residential:Single-family and multi-family installations represent marginal volume for fixed-tilt systems, as rooftop constraints typically favor flush-mount or tracking alternatives.
Utilities lead volumes today; commercial is climbing the fastest.
Service Type:
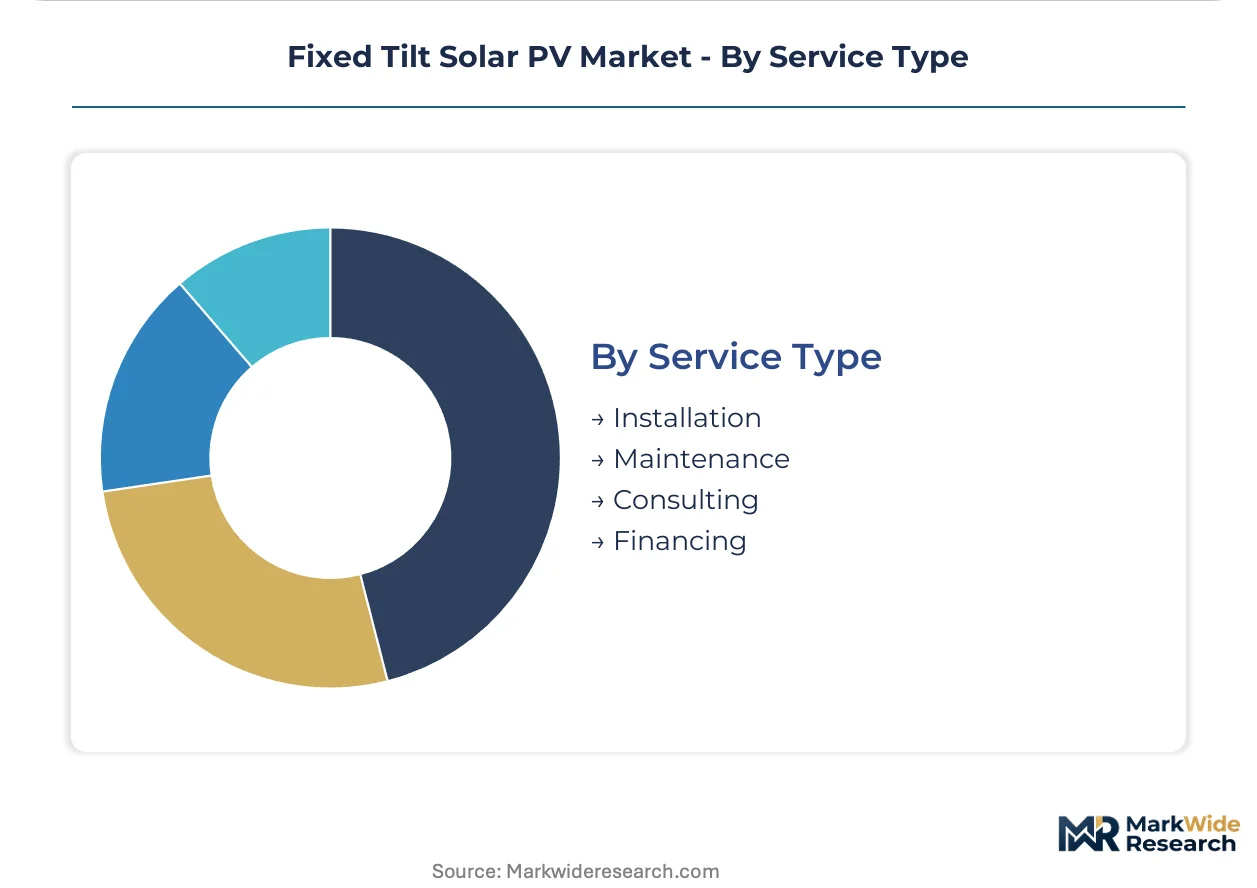
Installation services capture the dominant share of lifecycle value, while financing and consulting margins concentrate among specialized intermediaries with tax equity structuring expertise.
- Installation:Mechanical assembly of racking, module mounting, and DC electrical termination consumes 40-60% of total project labor hours. Pre-assembled torque-tube systems adopted by Arizona and Texas EPCs reduce crew sizing and accelerate field completion.
- Financing:Tax equity partnerships, green bonds, and construction debt structuring determine project economic viability under the US IRA's domestic content and energy community bonus credit regimes.
- Maintenance:Vegetation management, module cleaning, and structural inspection contracts extend across 25-30 year asset lifetimes, with drone-based thermal imaging reducing O&M labor intensity.
- Consulting:Geotechnical assessment, wind-load engineering, and permitting strategy support early-stage development, with qualified specialists concentrated among incumbent EPCs.
Installation leads volumes today; financing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural engineering talent concentrates in Arizona and Texas utility corridors, where interconnection queue acceleration demands rapid deployment expertise. Project developers in these clusters prioritize standardized racking configurations that compress permitting timelines. Regulatory navigation capabilities now determine market access across jurisdictions.
United States
Utility-scale procurement in California, Texas, and Arizona drives fixed-tilt deployment as FERC interconnection standards compress development windows. The IRA's domestic content bonus credit redirects steel and aluminum sourcing toward North American fabricators. Phoenix and Dallas-Fort Worth clusters anchor engineering talent for rapid mechanical completion.
India
Domestic manufacturing incentives under the PLI scheme redirect capital toward cyclone-certified racking supply chains. CEA mandates stringent structural load certifications for coastal zones, filtering import-dependent suppliers from project bids. Gujarat and Tamil Nadu industrial corridors concentrate fabrication capacity for utility-scale ground mounts.
Germany
Commercial rooftop and carport configurations dominate procurement as distributed generation targets reshape municipal infrastructure planning. EU Green Deal implementation tightens embodied carbon documentation requirements for steel structural components. Bavaria and North Rhine-Westphalia anchor engineering consultancies specializing in wind-load optimization.
Australia
High-irradiance site development in Queensland and Western Australia reduces balance-of-system costs for fixed-tilt configurations on flat terrain. Grid connection standards administered by the Australian Energy Market Operator shape equipment qualification timelines. Perth and Brisbane clusters concentrate EPC contractors with desert soil geotechnical expertise.
Brazil
Utility auction mechanisms concentrate procurement scale in Minas Gerais and Bahia solar corridors where land availability permits ground-mounted configurations. ANEEL regulatory frameworks govern interconnection timelines and equipment certification requirements. São Paulo-based engineering firms supply structural assessment capabilities for expanding northeast deployment.
Fixed Tilt Solar PV Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale advantages and engineering depth represent alternative paths to margin retention. The vendor base organizes around three strategic archetypes: tracking-adjacent diversifiers leveraging shared manufacturing infrastructure, heavy-gauge steel fabricators commanding utility-scale ground mount positions, and modular system specialists capturing commercial rooftop share through labor-hour reduction. Competitive intensity concentrates in M&A activity targeting regional engineering capabilities and strategic partnerships that lock multi-year volume commitments through integrated EPC-racking contracts.
Among tracking-adjacent diversifiers, Nextracker, Inc. exemplifies engineering expertise migration into fixed-tilt adjacent bids, while RBI Solar, LLC anchors the heavy-gauge steel fabrication tier for utility-scale deployments. Unirac, Inc. occupies the modular specialist position, representing labor-optimized rail system approaches that sustain commercial installation share. These three entities collectively illustrate the competitive positioning spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Nextracker, Inc. |
| RBI Solar, LLC |
| Unirac, Inc. |
| PV Hardware Manufacturing Co., Ltd. |
| GameChange Solar, Inc. |
| Mounting Systems GmbH |
| Schletter Group GmbH |
| SunLink Corporation |
| Clenergy Pty Ltd. |
| Others |
Supply Flow & Price Mechanics
Galvanized steel coil pricing cascades from mill certificates through fixed-tilt racking tiers, with North American provenance commanding premiums under IRA domestic content bonus structures while Southeast Asian aluminum extrusions face tariff exposure that compresses margins for import-dependent fabricators locked into fixed-price EPC contracts.
Pricing Analysis
Bundled EPC-racking contracts dominate utility-scale procurement, separating turnkey providers from component vendors. Price differentiation hinges on domestic content certification grade and volume scale commitments through multi-year master service agreements. Cost compression in standard ground-mount configurations intensifies as pre-assembled torque-tube systems reduce labor hours. Municipal cooperatives exhibit highest price sensitivity; vertically integrated IPPs prioritize schedule certainty over per-watt savings.
Supply Chain Analysis
Freight cost volatility from Southeast Asian aluminum extruders reshapes procurement geography toward domestic mill sourcing. Heavy-gauge steel fabrication concentrates in the United States, India, and Germany; aluminum structural components draw from Chinese and Vietnamese extrusion capacity. Supply chain risk centers on tariff exposure under evolving US trade remedy frameworks. Distribution runs through integrated EPC contractors with multi-project volume aggregation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fixed Tilt Solar PV Market functions as a regulatory compounder where FERC interconnection standards and the US IRA's domestic content bonus credit mechanically expand addressable demand for compliant racking systems.
For Market Incumbents: Deepen backward integration into North American steel and aluminum fabrication to secure IRA bonus credit eligibility and defend against tracking technology substitution in high-DNI environments. Anchor market position through captive supply of cyclone-certified structural systems for India's CEA-mandated coastal zones. For New Entrants and Emerging Players: Premium-to-economy tier price gaps in commercial carport configurations present accessible entry points for modular system specialists. Target municipal procurement in California school and transit authority sites where land constraints eliminate ground-mounted alternatives. Pursue labor-hour reduction through pre-assembled canopy structures as the primary go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering talent scarcity constrains rapid project scaling in Arizona and Texas utility corridors. Long-term viability favors acquirers of regional geotechnical and wind-load specialists with FERC qualification track records. Watch CEA certification timeline compression in India as the inflection signal for supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Supply Chain Qualification | IRA bonus credit eligibility hinges on North American mill certificate documentation through financial close. |
| Pre-Assembled Torque-Tube System Deployment | Texas and Arizona EPCs compress mechanical completion timelines through standardized module-table configurations. |
| Cyclone-Certified Structural System Investment | CEA mandates filter import-dependent suppliers from Gujarat and Tamil Nadu utility-scale project bids. |
| Carport Infrastructure Integration | California municipal procurement extracts value from parking real estate without land-use competition. |
| Bifacial Module Pairing Optimization | Elevated fixed-tilt configurations capture rear-side gain on high-albedo American Southwest desert soils. |
Methodological Framework
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded the qualitative assessment, cross-referenced against FERC filings, EIA project databases, IEA renewable energy reports, and customs trade records for steel and aluminum structural components. Bottom-up installation volume estimates triangulated with top-down capacity deployment forecasts across the analysis window.
Segment-level projections incorporate module efficiency tier, mounting configuration, buyer sophistication level, and regional regulatory framework as core dimensions. CAGRs derive from iterative reconciliation of historical deployment trajectories with policy incentive phase-out schedules and interconnection queue velocity assumptions. Bifacial penetration rates and domestic content compliance thresholds serve as critical sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for single-axis tracking substitution would alter the outlook for fixed-tilt share in high-irradiance utility corridors. Forecasts reflect assumptions about IRA bonus credit continuity and CEA certification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Backsheet Market