
 Middle-East and Africa Distributed Solar Power Generation Market | 2026-2036
Middle-East and Africa Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Distributed Solar Power Generation Market Foresight
Aftermarket service revenue from operations and maintenance contracts is rewriting margin distribution across the value chain. ACWA Power leverages its utility-scale experience to anchor distributed portfolios across Saudi Arabia and Egypt. SirajPower competes through fully financed commercial rooftop models that eliminate capital barriers for mid-size enterprises. Yellow Door Energy differentiates by controlling end-to-end asset performance through proprietary monitoring platforms.
Distributed solar power generation encompasses small-scale photovoltaic, concentrated solar power, and hybrid systems installed at or near the point of consumption, typically ranging from kilowatt-scale residential arrays to multi-megawatt commercial plants with DC-to-AC conversion efficiencies of 20-22% for monocrystalline modules. These installations serve industrial facilities, commercial buildings, and agricultural operations seeking to reduce grid dependence and stabilize energy expenditures against volatile fossil fuel tariffs. Photovoltaic technology dominates deployment volumes across residential and commercial applications, while off-grid installations in sub-Saharan Africa represent the fastest-expanding addressable base as rural electrification programs accelerate. Rooftop systems command premium margins in dense urban corridors where land scarcity precludes ground-mounted alternatives.
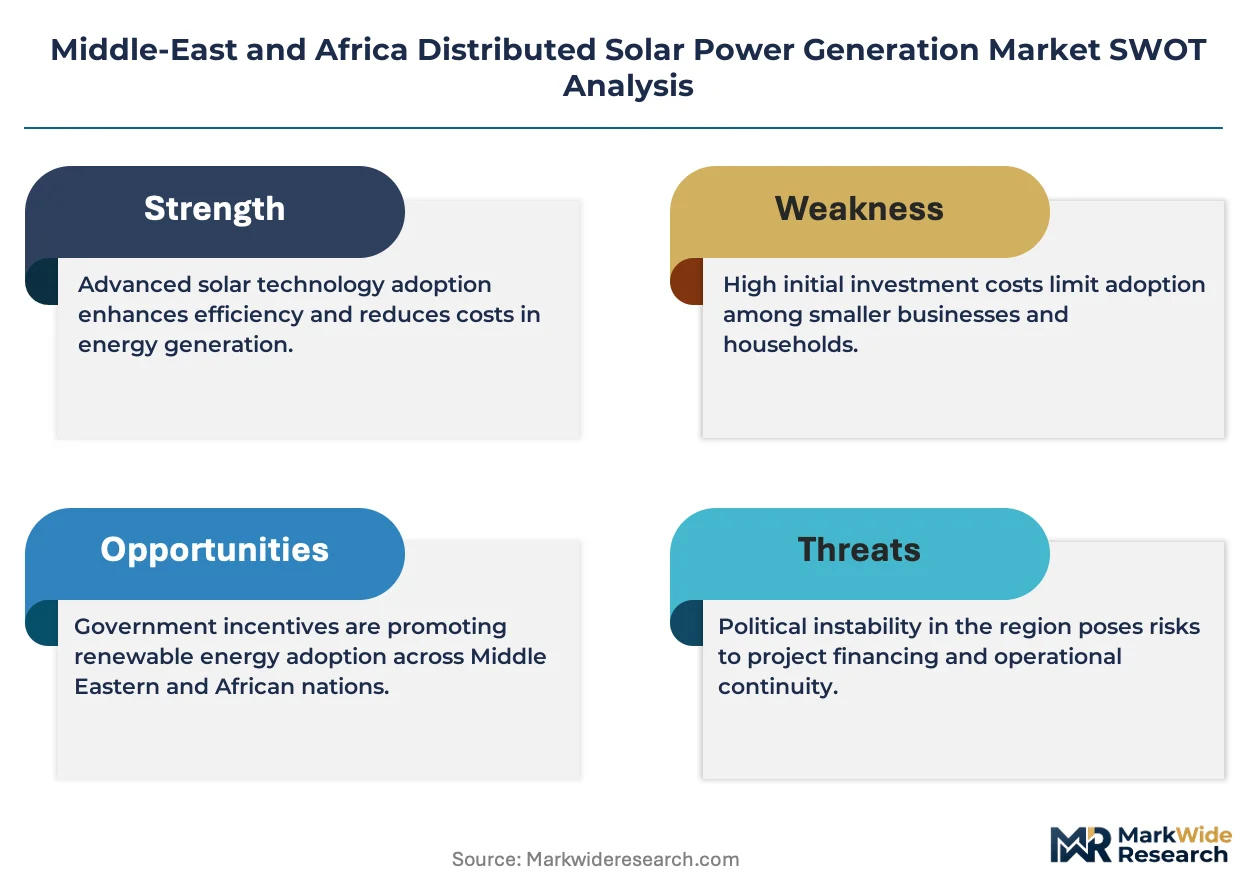
Saudi Arabia's Electricity and Cogeneration Regulatory Authority, the UAE's Emirates Authority for Standardization and Metrology, and South Africa's National Energy Regulator collectively mandate grid interconnection standards and net metering eligibility that determine project bankability and developer market access. Compliance with IEC 61215 module certification and regional fire safety codes shapes procurement specifications for property developers and utility offtakers. Stakeholders must monitor evolving tariff degression schedules and storage mandate proposals that will determine whether captive generation or grid-export models yield superior returns.
Market Dynamics
The UAE's net metering framework and Saudi Arabia's Electricity and Cogeneration Regulatory Authority mandates are compressing payback periods for commercial rooftop installations, while lithium-ion storage cost curves are hybridizing project economics across the Gulf Cooperation Council corridor.
Growth Catalysts
- Net Metering Frameworks:The UAE's interconnection standards allow commercial facilities to export surplus generation to the grid, improving project bankability for mid-size enterprises.
- Industrial Load Centers:Petrochemical and desalination facilities across Saudi Arabia's Eastern Province are deploying captive solar to hedge against volatile natural gas tariffs.
- Monocrystalline Efficiency Gains:DC-to-AC conversion efficiencies reaching 20-22% are reducing land and rooftop requirements for equivalent output in dense urban corridors.
Market Restraints
- Polysilicon Supply Concentration:Upstream ingot and wafer production concentrates in East Asian manufacturing hubs, exposing developers to input cost volatility and logistics bottlenecks.
- Grid Interconnection Queues:South Africa's National Energy Regulator processing timelines for distributed generator registration create deployment delays exceeding 18 months in Gauteng and Western Cape provinces.
- Diesel Generator Substitution:Off-grid installations in sub-Saharan Africa face competition from established diesel backup systems with lower upfront capital requirements and familiar maintenance protocols.
Strategic Opportunities
- Agricultural Irrigation Loads:Egypt's Nile Delta farming cooperatives represent an underpenetrated addressable base for solar-powered pumping systems replacing subsidized diesel units.
- Green Hydrogen offtake:Saudi Arabia's NEOM project is creating anchor demand for hybrid solar-plus-storage configurations serving electrolyzer loads.
- Digital Procurement Platforms:Developer aggregators are bypassing traditional EPC channels to connect commercial rooftops directly with financing and installation services.
Industry Challenges
- Certification Bottlenecks:IEC 61215 module testing and Emirates Authority for Standardization and Metrology approval timelines add 4-6 months to procurement cycles for UAE projects.
- Technical Workforce Scarcity:Certified solar electricians and grid interconnection engineers remain concentrated in Dubai and Riyadh, constraining deployment velocity in secondary Saudi cities and Egyptian provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Distributed Solar Power Generation Market |
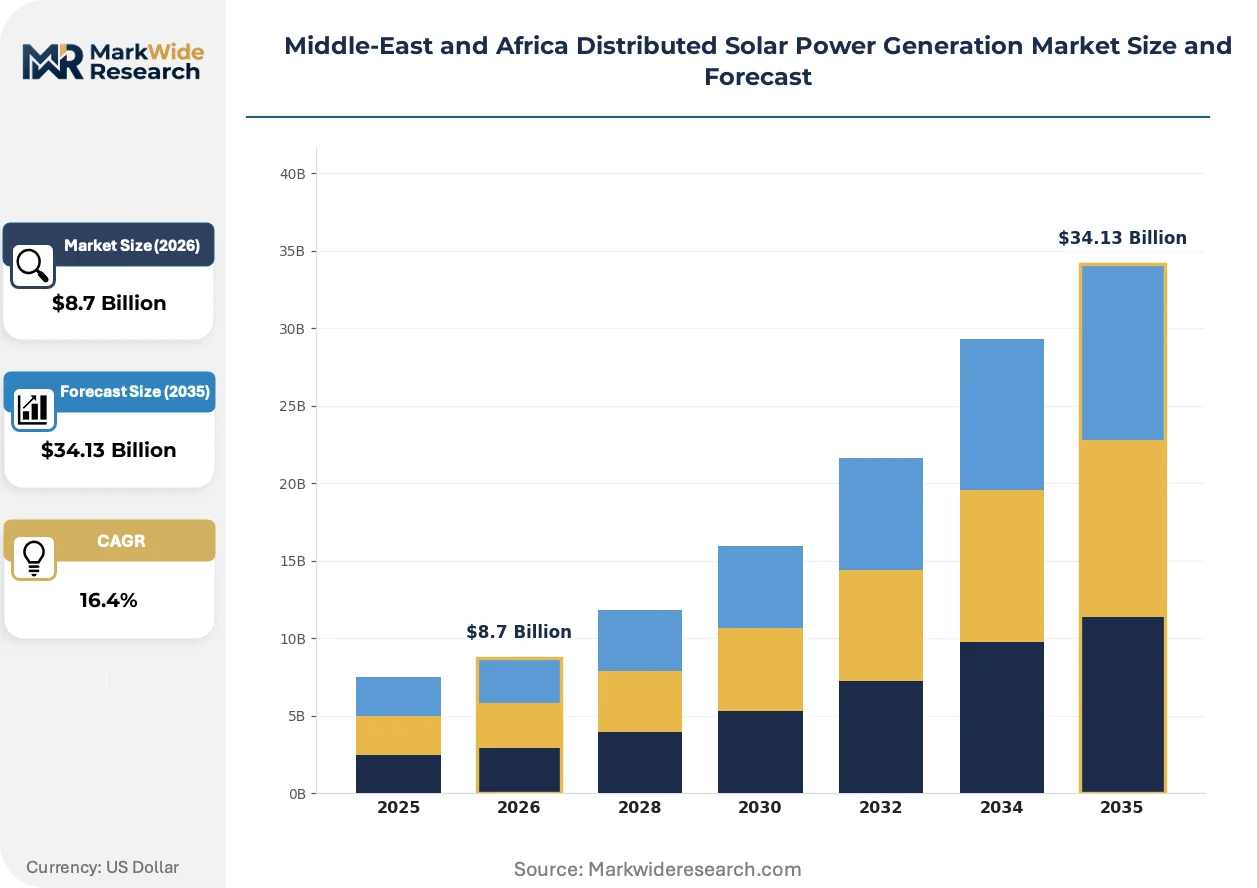
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Building-Integrated PV Application: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-mounted, Floating, Off-grid End User: Utility Providers, Property Developers, Homeowners, Small Businesses |
| Companies Covered | Masdar, ACWA Power, Juwi Solar Inc., Yellow Door Energy, Enerwhere Sustainable Energy DMCC, AMEA Power, SirajPower, Dubai Electricity and Water Authority, EDF Renewables, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Distributed Solar Power Generation Market Shifts & Advancements
Bifacial module architectures and containerized battery integration are compressing levelized cost trajectories for commercial installations, while regulatory mandates across the Middle-East and Africa are hardening grid code requirements that favor intelligent inverter platforms.
DC-coupled solar-plus-storage architectures are hybridizing commercial project designs by eliminating AC conversion losses between photovoltaic arrays and lithium-ion battery systems. Large-format property developers in Dubai's logistics and industrial free zones are specifying these configurations to maximize self-consumption ratios. The structural consequence is a compression of EPC margins as storage integration becomes a standard rather than premium offering.
Saudi Arabia's Electricity and Cogeneration Regulatory Authority is mandating smart inverter capabilities and grid-support functions for all new distributed generation above 1 MW capacity. Industrial facilities in Jubail and Yanbu are retrofitting existing installations to comply with revised interconnection standards. The regulation most affects cement and steel producers with captive power plants, forcing procurement shifts toward European and East Asian inverter suppliers with certified grid-forming capabilities.
Commercial offtakers are unbundling operations and maintenance contracts from initial EPC agreements, creating standalone revenue streams for specialized asset managers. Mid-size enterprises in Riyadh and Jeddah are procuring monitoring and performance guarantees separately from installation services. This pattern is most visible among retail and hospitality chains seeking standardized reporting across multi-site portfolios.
Middle-East and Africa Distributed Solar Power Generation Market Segmentation
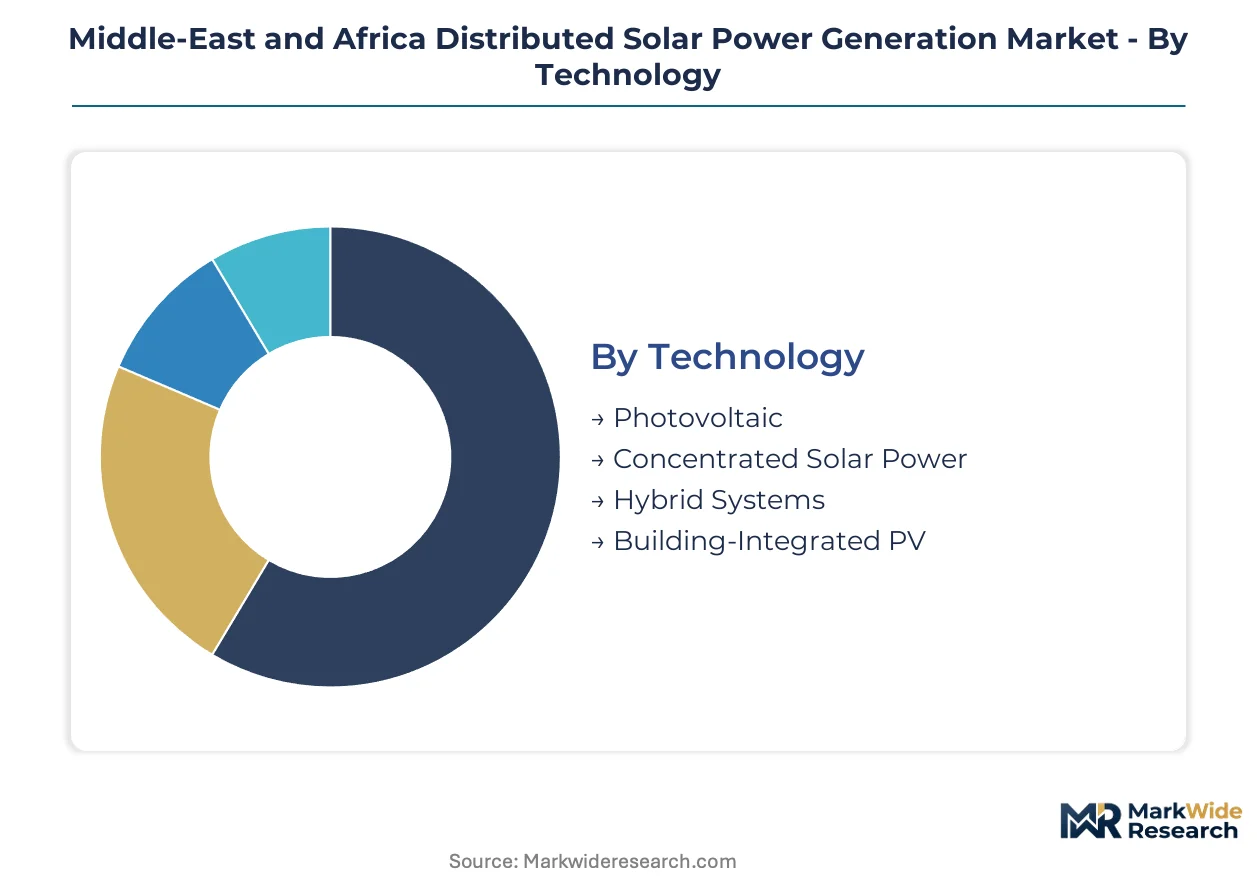
Segmentation reveals how technology choices and installation constraints fragment addressable demand across the Middle-East and Africa corridor. Deployment economics vary sharply between Gulf commercial rooftops and sub-Saharan off-grid installations. Understanding these fractures illuminates where capital allocation and regulatory attention concentrate.
Technology:
Mature photovoltaic systems anchor current deployment volumes while emerging hybrid configurations reshape project economics through storage integration.
- Photovoltaic:Monocrystalline silicon modules with 20-22% DC-to-AC conversion efficiency dominate commercial and residential installations. Demand concentrates in Dubai and Riyadh logistics free zones where landlords seek to stabilize energy expenditures against volatile fossil fuel tariffs.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt thermal storage suit industrial process heat applications. Deployment remains limited to Saudi Arabia's petrochemical corridor where ACWA Power anchors utility-scale pilots with captive industrial offtake.
- Hybrid Systems:DC-coupled solar-plus-storage architectures eliminate conversion losses between arrays and lithium-ion batteries.
- Building-Integrated PV:Facade-embedded modules serve aesthetic constraints in high-end commercial developments.
Photovoltaic retains volume leadership; hybrid systems hold the steepest expansion curve.
Application:
Cost tiers separate premium commercial deployments from capital-constrained residential and agricultural segments.
- Commercial:Mid-size enterprises in UAE free zones and Saudi logistics parks deploy rooftop systems under net metering frameworks. SirajPower's fully financed models eliminate upfront capital barriers, accelerating adoption among retail and hospitality chains seeking standardized reporting across multi-site portfolios.
- Industrial:Captive power plants at Jubail and Yanbu cement and steel facilities retrofit to comply with Electricity and Cogeneration Regulatory Authority smart inverter mandates. Petrochemical and desalination operators in Saudi Arabia's Eastern Province hedge against natural gas price volatility through behind-the-meter generation.
- Residential:Grid-tied rooftop systems serve high-income homeowners in Dubai and Riyadh.
- Agricultural:Solar-powered pumping systems target Egypt's Nile Delta farming cooperatives replacing subsidized diesel units.
Commercial applications command premium margins through financing innovation; agricultural deployment climbs fastest as diesel substitution economics improve.
Installation Type:
Geography dictates feasibility, with land scarcity in dense urban corridors favoring elevated and floating alternatives over ground-mounted arrays.
- Rooftop:Commercial and industrial property developers across the UAE and Saudi Arabia accelerate adoption where land scarcity precludes ground alternatives. Premium margins reflect structural reinforcement requirements and Emirates Authority for Standardization and Metrology fire safety compliance.
- Off-grid:Standalone systems with battery storage serve rural electrification programs across sub-Saharan Africa. Yellow Door Energy's proprietary monitoring platforms target this segment through end-to-end asset performance control.
- Ground-mounted:Utility-scale adjacent deployments serve industrial parks with available land.
- Floating:Reservoir and canal installations address land constraints in Egypt and South Africa.
Rooftop commands revenue concentration; off-grid gains share fastest as rural electrification programs accelerate.
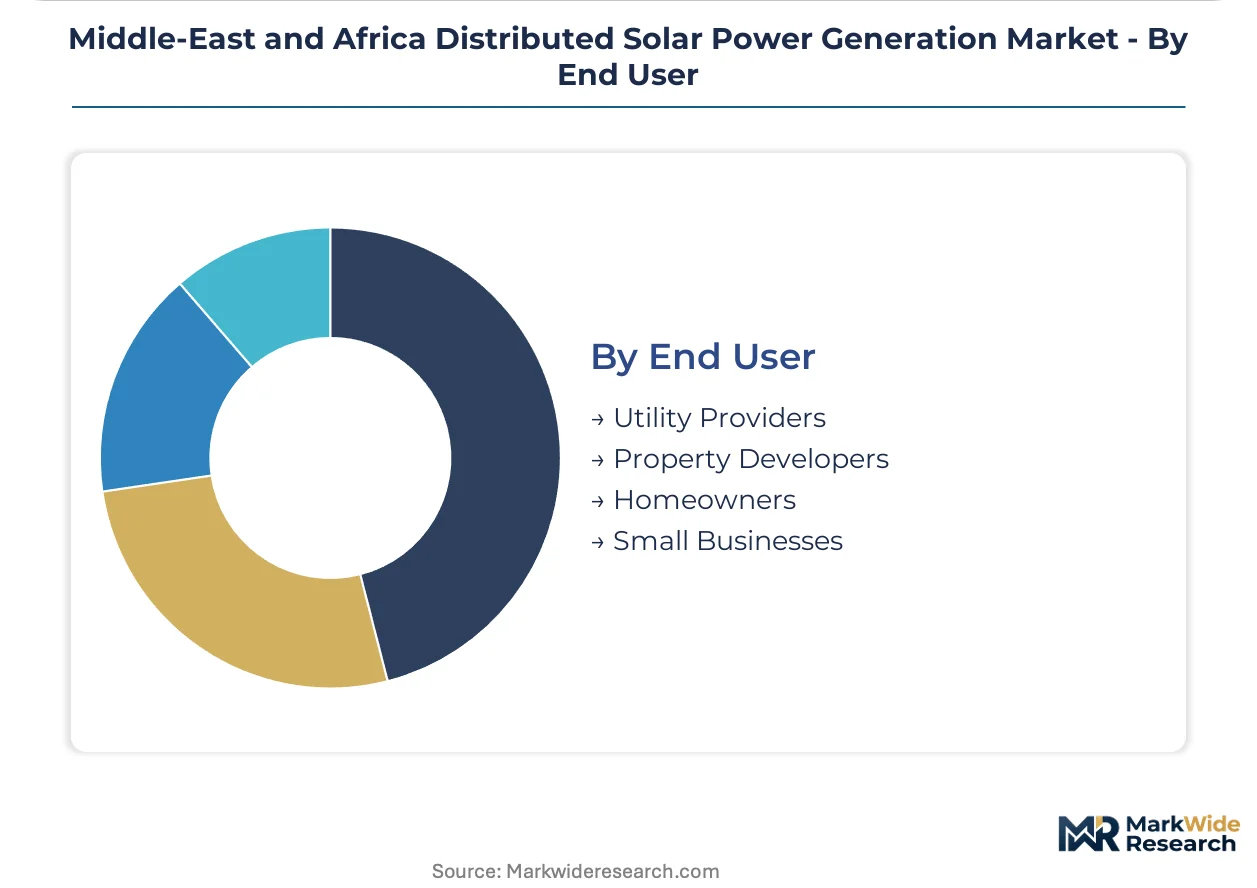
End User:
Customer type determines procurement sophistication, from standardized utility tenders to fragmented homeowner decisions.
- Property Developers:Large-format logistics and industrial free zone operators in Dubai specify DC-coupled solar-plus-storage configurations to maximize self-consumption ratios. Unbundled operations and maintenance contracts create standalone revenue streams for specialized asset managers.
- Utility Providers:Grid interconnection standards and net metering eligibility frameworks from South Africa's National Energy Regulator determine project bankability. Processing timelines exceeding 18 months in Gauteng and Western Cape provinces constrain deployment velocity.
- Small Businesses:Mid-size enterprises procure monitoring and performance guarantees separately from installation services.
- Homeowners:High-net-worth individuals in Gulf urban centers drive residential adoption.
Property developers retain procurement volume leadership; small businesses represent the fastest-expanding addressable base as financing models democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the corridor. Gulf commercial buyers prioritize financing flexibility over unit economics, while sub-Saharan agricultural offtakers remain acutely price-sensitive to upfront capital requirements.
United Arab Emirates
Dubai's logistics free zones and Abu Dhabi's industrial parks anchor commercial rooftop deployment. The Emirates Authority for Standardization and Metrology mandates IEC 61215 module certification and fire safety compliance that shape procurement specifications. Dubai Electricity and Water Authority's net metering framework permits grid export, improving project bankability for mid-size enterprises in Jebel Ali and Dubai South.
Saudi Arabia
Petrochemical and desalination facilities across the Eastern Province deploy captive solar to hedge natural gas price volatility. The Electricity and Cogeneration Regulatory Authority mandates smart inverter capabilities above 1 MW capacity. Jubail and Yanbu industrial clusters retrofit cement and steel plants to comply with revised interconnection standards.
South Africa
Gauteng and Western Cape provinces concentrate distributed generation demand from mining and manufacturing facilities. The National Energy Regulator's registration processing timelines exceed 18 months, constraining deployment velocity. Cape Town's commercial property sector accelerates rooftop adoption despite bureaucratic friction.
Egypt
Nile Delta farming cooperatives represent underpenetrated demand for solar-powered irrigation pumping. The country's renewable energy regulator oversees grid interconnection standards that determine project feasibility. Alexandria and Suez Canal industrial zones attract captive power investments from textile and food processing operators.
Israel
High electricity tariffs drive commercial and industrial rooftop economics in Tel Aviv and Haifa corridors. The national electricity regulator governs net metering eligibility and grid export compensation structures. Kibbutzim and moshavim agricultural collectives deploy distributed arrays to offset irrigation and cold storage loads.
Middle-East and Africa Distributed Solar Power Generation Market Competitive Landscape
Capability concentration sits with utility-scale veterans who leverage project finance expertise; scale advantage sits with specialized distributed developers who control customer acquisition costs. The market structures around three archetypes: state-affiliated energy champions with sovereign balance sheet access, independent power producers with distributed financing platforms, and engineering-procurement-construction contractors with installation velocity. Competitive moves center on unbundling operations and maintenance contracts from initial construction agreements, and on securing anchor offtake relationships with large-format property developers.
Within the state-affiliated tier, Masdar and ACWA Power exemplify players leveraging utility-scale experience to anchor distributed portfolios across the Gulf Cooperation Council corridor. Among specialized distributed developers, SirajPower and Yellow Door Energy occupy positions defined by financing innovation and end-to-end asset control. EDF Renewables represents the European utility-backed archetype applying developed-market technical standards to emerging-market deployment.
| Leading Market Players |
|---|
| Masdar |
| ACWA Power |
| Juwi Solar Inc. |
| Yellow Door Energy |
| Enerwhere Sustainable Energy DMCC |
| AMEA Power |
| SirajPower |
| Dubai Electricity and Water Authority |
| EDF Renewables |
| Others |
Supply & Pricing Matrix
East Asian polysilicon ingot and wafer production anchors upstream supply, concentrating margin capture with module manufacturers while EPC contractors and project developers compete for downstream margin pools through financing innovation and O&M unbundling.
Pricing Analysis
Aftermarket service revenue from multi-year operations and maintenance contracts drives lifetime project value, with unbundled O&M agreements commanding premium pricing over bundled EPC-plus-service packages. Three-tier pricing structure across premium, standard, and economy levels separates bankable utility-grade installations with full certification from commercial rooftop systems and basic off-grid configurations. Cost compression in module procurement is intensifying because polysilicon spot volatility feeds directly into developer margins. Agricultural cooperatives in Egypt's Nile Delta exhibit the highest price sensitivity due to capital constraints, while UAE logistics free zone operators prioritize financing flexibility over unit economics.
Supply Chain Analysis
Export-control regimes restricting semiconductor-grade polysilicon processing equipment to Chinese manufacturers limit alternative supply base development for ingot and wafer production. Module assembly draws from China, Vietnam, and Malaysia, with lithium-ion battery cell production centering on China, South Korea, and Japan. Raw material dependencies span metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames. Single-source vulnerability concentrates in high-purity quartz crucibles for monocrystalline ingot pulling. Distribution runs through developer-aggregator platforms that bypass traditional EPC channels to connect commercial rooftops directly with financing and installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa distributed solar market represents a high-growth disruption as net metering frameworks and lithium-ion cost curves simultaneously reshape project economics across the Gulf Cooperation Council corridor.
For Market Incumbents: Pre-empt margin erosion in EPC services by securing captive O&M contract portfolios across multi-site commercial deployments before specialized asset managers consolidate this revenue tier. Deepen backward integration into module procurement through direct partnerships with tier-one Chinese manufacturers to hedge polysilicon price volatility. The Electricity and Cogeneration Regulatory Authority's smart inverter mandates above 1 MW capacity threaten retrofit obsolescence for existing captive power installations at Jubail and Yanbu industrial clusters. For New Entrants and Emerging Players: Mid-market commercial buildings in Saudi Arabia's secondary cities—Jeddah, Dammam, and Khobar—represent the most penetrable entry point given technical workforce scarcity constraining incumbent deployment velocity there. Solar-powered irrigation pumping for Egypt's Nile Delta farming cooperatives offers a second white-space target with diesel substitution economics improving as equipment financing models mature. A fully financed zero-upfront-capital go-to-market angle eliminates the primary barrier for price-sensitive agricultural offtakers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed distributed developers who have scaled customer acquisition platforms but lack utility-scale project finance expertise for hybrid solar-plus-storage configurations. Long-term viability over a five-to-ten year window rests on developer ability to anchor recurring O&M revenue streams that stabilize cash flows against module price volatility. The signal to watch is regulatory movement toward storage mandates that would force technology capability upgrades across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-term offtake contracts with Dubai Electricity and Water Authority improve project bankability for commercial rooftops. |
| Vertical Integration into Storage | DC-coupled solar-plus-storage configurations eliminate AC conversion losses and compress competitor EPC margins. |
| Technology Licensing | Proprietary monitoring platforms from specialized asset managers create switching costs across multi-site portfolios. |
| Green Certification Program | Emirates Authority for Standardization and Metrology compliance opens access to UAE net metering frameworks. |
| Capacity Buildout | Installation velocity in secondary Saudi cities requires certified solar electrician training programs. |
Research Methodology
Cross-validation between primary interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators anchors the qualitative findings against secondary data from IEA reports, EIA data, FERC filings, and project development databases. Bottom-up segmentation modeling triangulates with top-down macroeconomic overlays to ensure consistency across capacity deployment estimates and revenue projections.
Calibration against historical deployment trajectories and announced project pipelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include generation capacity tier, project scale, regulatory framework, regional grid type, and technology configuration. CAGRs derive from fitted growth curves applied to base-year market sizing, with lithium-ion battery cost curves and net metering policy evolution serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon price trajectories, currency volatility in Egyptian pound and South African rand, and sovereign debt capacity would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and technology cost reduction rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market