
 On-Site Photovoltaic Solar Power for Data Centers Market | 2026-2036
On-Site Photovoltaic Solar Power for Data Centers Market Size, Share, and Industry Trends Forecast 2026-2036
On-Site Photovoltaic Solar Power for Data Centers Market Analytics
EPA emissions guidelines for stationary power sources is recalibrating the cost-of-entry calculus for data center operators evaluating on-site generation. First Solar leverages its thin-film cadmium telluride technology to sustain cost advantages in utility-scale deployments adjacent to hyperscale campuses. Jinko Solar anchors global manufacturing scale, while SunPower differentiates through high-efficiency interdigitated back-contact cells designed for constrained rooftop footprints.
On-site photovoltaic solar power for data centers denotes electricity generation systems installed directly at data center premises, typically comprising crystalline silicon or thin-film modules with DC-to-AC inversion and net metering interconnection at voltages from 480V to 34.5kV, designed to offset facility baseload or provide resilient behind-the-meter supply. Bifacial modules capture reflected albedo from white membrane roofs and gravel surfaces, delivering elevated energy yield per installed watt in data center applications. Grid-tied systems dominate current deployments by capacity, though hybrid configurations with lithium-ion storage are expanding fastest as operators seek to shift solar generation into evening peak pricing windows.
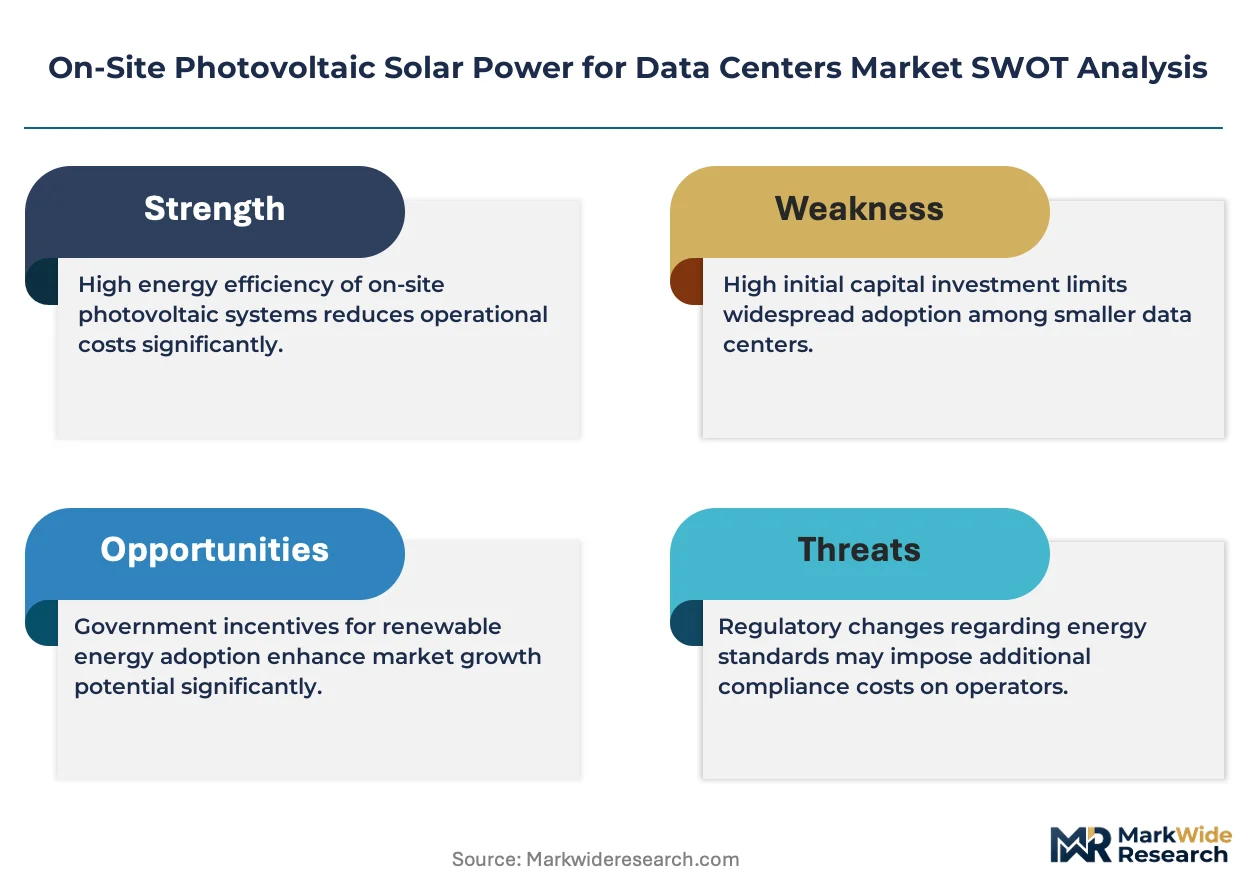
FERC interconnection standards, IEEE 1547 grid integration protocols, and OSHA workplace safety requirements collectively shape equipment specifications, installation practices, and market access timelines for on-site solar at data center facilities. The EU AI Act and national renewable portfolio standards in multiple jurisdictions are tightening disclosure requirements for data center energy sourcing. Stakeholders must monitor evolving carbon accounting rules and interconnection queue reforms to determine optimal timing between captive solar investment and third-party green tariff procurement.
Market Dynamics
Bifacial photovoltaic modules are compressing levelized cost thresholds for data center operators by harvesting albedo from white membrane roofing, while IEEE 1547 grid integration protocols are tightening inverter synchronization requirements that reshape equipment procurement timelines.
Growth Catalysts
- EU Green Deal building codes:Mandatory renewable energy quotas for new hyperscale facilities in Germany and the Netherlands are accelerating rooftop and carport solar specifications into standard RFP templates.
- Cloud service provider procurement:Hyperscale operators are embedding solar generation into campus master plans to offset baseload consumption and meet internal carbon neutrality commitments.
- FERC interconnection standardization:Streamlined behind-the-meter approval processes in the United States are compressing project development cycles from permitting to energization.
Market Restraints
- Polysilicon supply concentration:Refining and ingot production gravity in specific Asian manufacturing clusters creates input cost volatility and logistics vulnerability for module procurement.
- Interconnection queue congestion:Utility study backlogs and transformer lead times in high-growth data center markets are extending project commissioning schedules beyond operator planning horizons.
- Lithium-ion storage cost structure:Battery system pricing remains a prohibitive adder for hybrid solar-plus-storage configurations that would enable peak-shifting into evening pricing windows.
Strategic Opportunities
- India data center cluster expansion:Greenfield hyperscale developments in Mumbai and Chennai are incorporating captive solar generation from project inception under national renewable purchase obligation frameworks.
- Agrivoltaic dual-use applications:Ground-mount solar arrays on data center buffer lands are emerging as a land-use efficiency play that satisfies local zoning while expanding generation capacity.
- EU AI Act disclosure mandates:Tightening energy sourcing transparency requirements are creating competitive differentiation for operators with verified on-site renewable generation.
Industry Challenges
- Electrical engineering talent scarcity:Specialized expertise in medium-voltage interconnection design and power quality management is concentrating among a limited pool of qualified EPC contractors.
- OSHA workplace safety compliance:Fall protection and energized work protocols for rooftop installations are extending labor hours and subcontractor coordination complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Site Photovoltaic Solar Power for Data Centers Market |
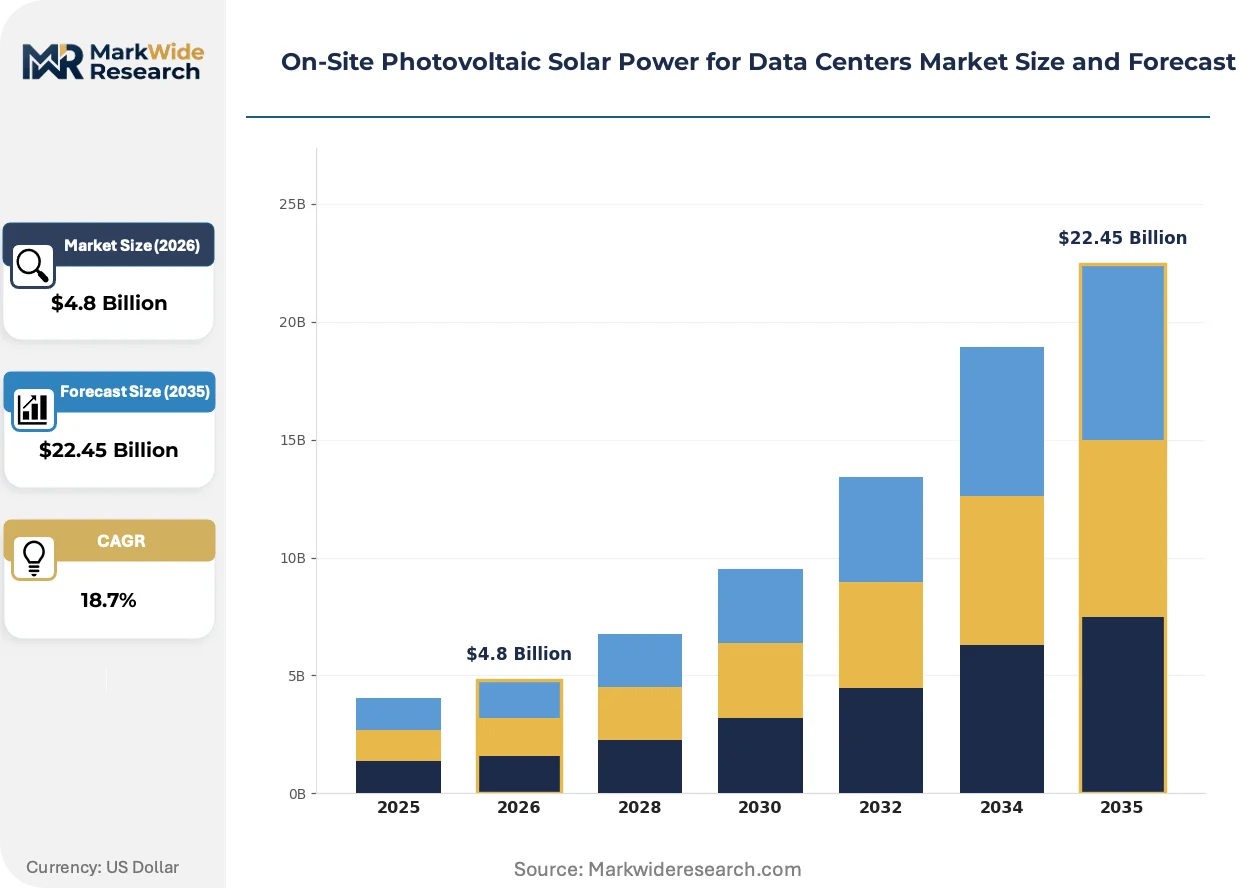
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline Panels, Polycrystalline Panels, Bifacial Modules, Thin-Film Panels Technology: Grid-Tied Systems, Off-Grid Systems, Hybrid Systems, Energy Storage Solutions End User: Telecommunication Companies, Cloud Service Providers, Financial Institutions, Government Agencies Capacity: Below 100 kW, 100 kW to 500 kW, 500 kW to 1 MW, Above 1 MW |
| Companies Covered | First Solar, Jinko Solar, Trina Solar, Yingli Solar, Hanwha Q CELLS, JA Solar, Canadian Solar, Vikram Solar, SunPower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Site Photovoltaic Solar Power for Data Centers Market Evolving Landscape
Thin-film cadmium telluride technology is compressing module manufacturing energy intensity while elevating temperature coefficient performance, reshaping technology selection criteria for utility-scale deployments adjacent to hyperscale campuses.
Bifacial glass-glass module architecture is absorbing reflected irradiance from gravel ballast and white TPO roofing to deliver energy yield premiums of fifteen to twenty percent over monofacial equivalents in data center applications. Operators in Arizona and Nevada are specifying these configurations for carport and ground-mount installations where albedo conditions are favorable. The technology is absorbing market share from traditional monofacial crystalline silicon in new-build projects where space constraints and yield optimization drive procurement decisions.
The EU AI Act's energy disclosure requirements are forcing hyperscale operators to document renewable energy sourcing with granular hourly matching rather than annualized certificates. This regulatory pressure is accelerating investment in behind-the-meter solar with battery storage to demonstrate temporal correlation between generation and consumption. German and French data center developments are responding by oversizing solar arrays relative to immediate load to build generation surpluses for evening dispatch.
Power purchase agreement structures are fragmenting as operators seek to decouple solar asset ownership from operational risk. Third-party ownership models with fixed escalators are displacing traditional capex-heavy self-build approaches among mid-sized colocation providers. This behavioral shift is most visible in the United States, where investment tax credit monetization through tax equity partnerships has become the dominant procurement pathway for facilities below fifty megawatts of critical IT load.
On-Site Photovoltaic Solar Power for Data Centers Market Segmentation
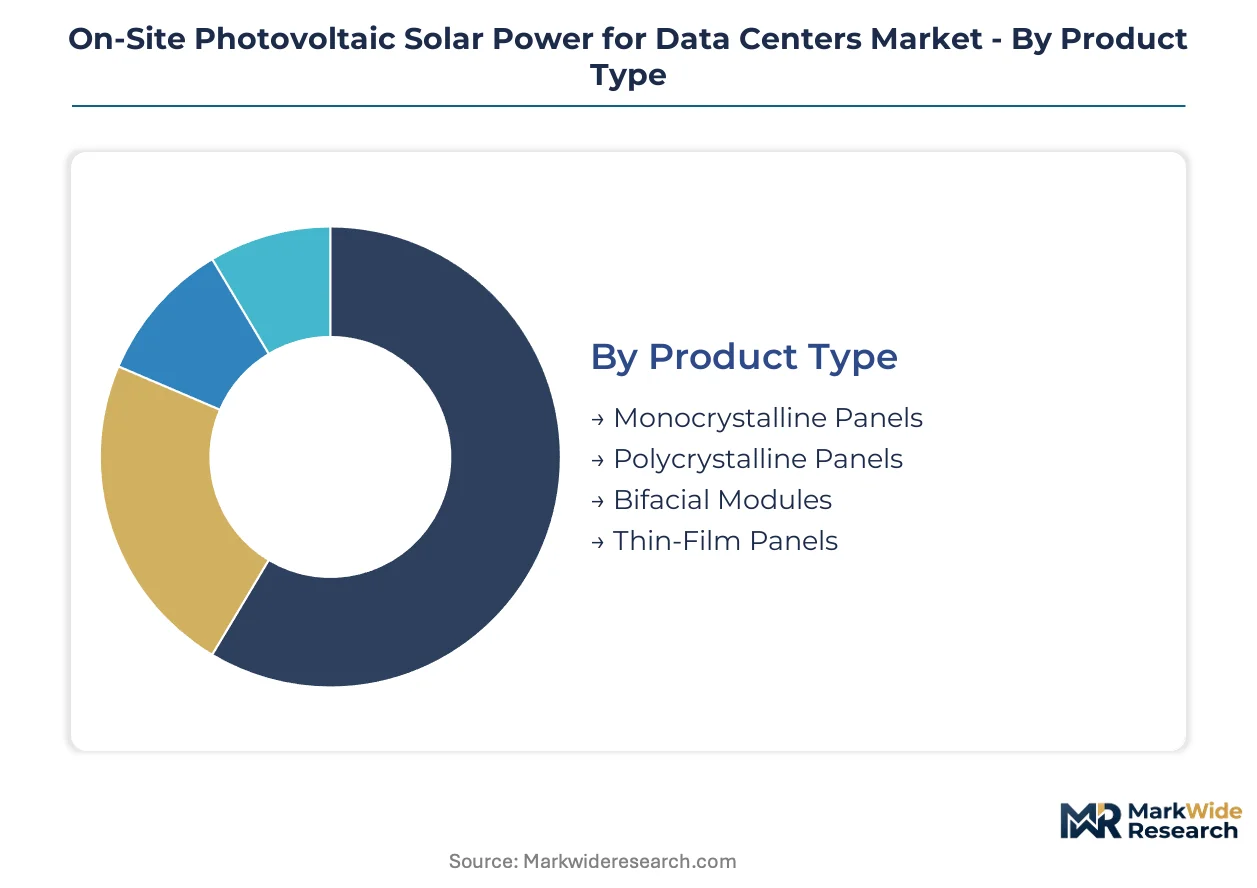
Technology selection in data center solar deployments hinges on rooftop constraints, grid interconnection protocols, and hourly load-matching requirements. Procurement patterns bifurcate between hyperscale operators optimizing for levelized cost and colocation providers prioritizing rapid deployment timelines.
Product Type:
Module efficiency directly determines land-use intensity and structural load requirements for rooftop installations.
- Bifacial Modules:Dual-sided glass architecture harvests albedo from white TPO membrane roofing and gravel ballast, delivering yield premiums in data center applications. German and Dutch hyperscale facilities specify these configurations to maximize generation per square meter under EU Green Deal mandates.
- Monocrystalline Panels:Single-crystal silicon wafers deliver the highest commercial efficiencies, making them the default specification for space-constrained urban rooftops where structural load limits apply. Cloud service providers in India deploy these for captive generation under renewable purchase obligation frameworks.
- Polycrystalline Panels:Multi-crystal ingot production yields lower efficiency at reduced manufacturing energy intensity, occupying cost-sensitive procurement portfolios.
- Thin-Film Panels:Cadmium telluride deposition tolerates high-temperature operating conditions with superior spectral response, suiting utility-scale ground-mount arrays adjacent to Arizona and Nevada campuses.
Volume sits with monocrystalline panels; growth tilts toward bifacial modules.
Technology:
System architecture choices reflect grid reliability, tariff structures, and resilience requirements.
- Hybrid Systems:DC-coupled solar-plus-storage configurations enable peak-shifting into evening pricing windows and provide ride-through capability during utility disturbances. United States colocation providers favor these for FERC Order 2222 participation and demand charge management.
- Energy Storage Solutions:Lithium-ion battery systems paired with photovoltaic generation address temporal mismatch between solar production and data center baseload consumption. German operators oversize arrays to build dispatchable surpluses for evening correlation under EU AI Act disclosure rules.
- Grid-Tied Systems:Net-metered configurations without storage dominate current installed capacity by virtue of lower capital requirements and simplified interconnection.
- Off-Grid Systems:Islanded microgrids serve remote facilities and edge computing nodes where utility infrastructure is unavailable or prohibitively expensive.
Grid-tied systems anchor current deployments; hybrid configurations are climbing the fastest as battery costs compress.
End User:
Customer scale and sustainability disclosure obligations drive divergent procurement strategies.
- Cloud Service Providers:Hyperscale operators embed solar generation into campus master plans with multi-hundred-megawatt procurement programs to offset baseload and satisfy internal carbon neutrality commitments. Amazon Web Services and Microsoft specify rooftop, carport, and adjacent utility-scale arrays across United States, Germany, and India clusters.
- Telecommunication Companies:Tower operators and network facilities prioritize rapid-deployment solar for remote cell sites and edge data centers where grid extension is uneconomical.
- Financial Institutions:Banking and trading data centers emphasize resilience and ESG reporting transparency, favoring behind-the-meter generation with hourly matching certificates.
- Government Agencies:Federal and state facilities follow mandated renewable procurement targets with standardized contracting vehicles and extended payback horizons.
Cloud service providers concentrate procurement volume; financial institutions are gaining share fastest on disclosure compliance urgency.
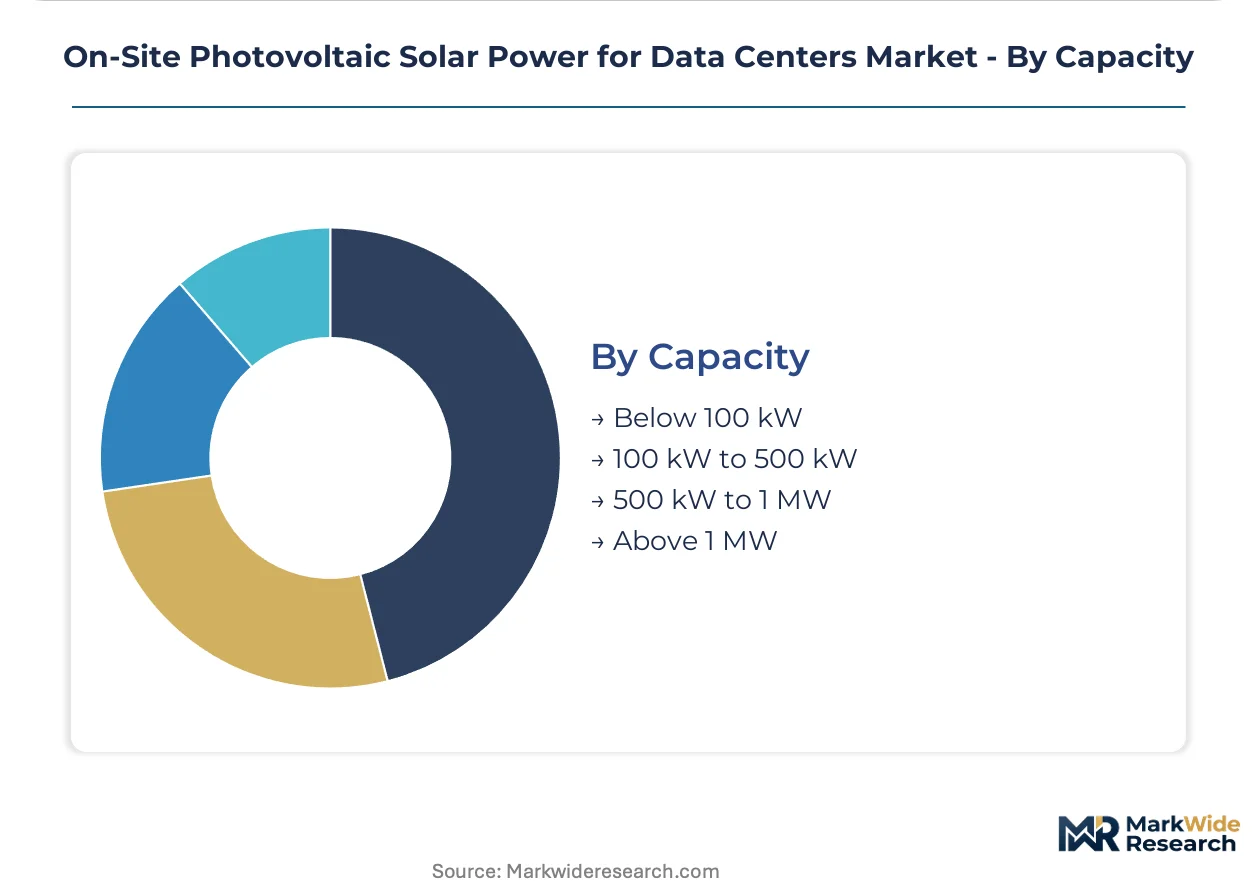
Capacity:
Scale thresholds determine interconnection voltage, regulatory jurisdiction, and ownership structure.
- Above 1 MW:Medium-voltage interconnection at 12.47kV to 34.5kV serves hyperscale data center campuses with dedicated substations and utility-scale equipment. These projects trigger FERC interconnection study requirements and tax equity partnership structures in the United States.
- 500 kW to 1 MW:Commercial-scale rooftop and carport installations occupy the sweet spot for behind-the-meter net metering and accelerated depreciation schedules.
- 100 kW to 500 kW:Distributed generation for colocation facilities and enterprise data centers leverages simplified permitting and standardized inverter packages.
- Below 100 kW:Small commercial and edge computing installations rely on plug-and-play solar kits with string inverters and minimal engineering overhead.
Above-1 MW deployments dominate installed capacity; sub-500 kW segments are expanding most quickly among colocation providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center solar deployment concentrates in jurisdictions where hyperscale operators face binding renewable mandates and favorable interconnection economics. Germany, the United States, India, the Netherlands, and Australia anchor procurement volume through distinct regulatory and market mechanisms.
United States
Hyperscale campuses in Virginia, Texas, and Arizona drive rooftop and adjacent utility-scale solar procurement to offset baseload consumption. FERC interconnection standardization and IRA tax credit monetization compress project development cycles. Northern Virginia's data center corridor integrates solar generation into campus master plans with dedicated substations at medium voltage.
Germany
EU Green Deal building codes mandate renewable energy quotas for new hyperscale facilities in Frankfurt and Berlin metro areas. Operators oversize solar arrays relative to immediate load to build dispatchable surpluses for evening correlation under EU AI Act disclosure rules. Bavarian and Hesse data center clusters incorporate bifacial modules on white membrane roofing to maximize yield per square meter.
India
Greenfield hyperscale developments in Mumbai and Chennai embed captive solar generation from project inception under national renewable purchase obligation frameworks. Ministry of Power regulations and state-level solar policies accelerate behind-the-meter installations. Telangana and Karnataka data center parks specify monocrystalline panels for space-constrained urban rooftops.
Netherlands
Amsterdam metro area data center operators face tightening municipal renewable energy requirements and spatial planning constraints. Bifacial carport and rooftop configurations dominate new specifications to satisfy EU Green Deal mandates. Eindhoven and Rotterdam clusters leverage streamlined permitting for distributed generation below 1 MW threshold.
Australia
New South Wales and Victoria data center developments integrate solar generation to meet corporate renewable targets and grid reliability concerns. Australian Energy Market Operator protocols and state-based feed-in tariffs shape hybrid system economics. Sydney and Melbourne hyperscale campuses specify lithium-ion paired solar for peak-shifting into evening pricing windows.
On-Site Photovoltaic Solar Power for Data Centers Market Competitive Landscape
Chinese producers anchor the scale-driven tier; American and South Korean specialists hold technology-differentiated positions. The vendor base organizes around three archetypes: integrated cell-to-module manufacturers optimizing for cost, thin-film technology specialists capturing high-temperature performance premiums, and high-efficiency crystalline silicon players serving constrained rooftop footprints. Competitive moves concentrate on backward integration into polysilicon refining and strategic partnerships with data center EPC contractors to secure offtake pipelines.
Among thin-film technology specialists, First Solar occupies a position exemplifying cadmium telluride deposition for utility-scale deployments adjacent to hyperscale campuses. Jinko Solar and Trina Solar represent the integrated manufacturing archetype, anchoring global module supply through crystalline silicon scale. SunPower sits within the high-efficiency tier, targeting space-constrained data center rooftops with interdigitated back-contact cell architecture.
| Leading Market Players |
|---|
| First Solar |
| Jinko Solar |
| Trina Solar |
| Yingli Solar |
| Hanwha Q CELLS |
| JA Solar |
| Canadian Solar |
| Vikram Solar |
| SunPower |
| Others |
Value Network & Pricing Analysis
Thin-film cadmium telluride deposition is compressing module manufacturing energy intensity while simultaneously concentrating production among a handful of integrated manufacturers, creating asymmetric pricing power for those controlling captive tellurium supply. This technology shift rewards operators with backward integration into semiconductor refining while squeezing margins for crystalline silicon assemblers exposed to polysilicon spot volatility.
Pricing Analysis
Volume procurement by hyperscale cloud service providers captures standard-tier pricing through multi-hundred-megawatt offtake agreements, while colocation providers with sub-fifty-megawatt loads absorb premium markups for rapid-deployment rooftop configurations. Price differentiation hinges on module efficiency certification and FERC interconnection study bundling. Cost compression in standard monocrystalline panels is intensifying because Chinese ingot producers are expanding polysilicon refining capacity. Mid-sized colocation providers exhibit the highest price sensitivity, whereas financial institutions with ESG disclosure mandates accept premium pricing for hourly-matched renewable certificates.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-origin polysilicon, where ingot production gravity creates input cost volatility for crystalline silicon module procurement. Manufacturing concentrates in China, Vietnam, and Malaysia for cell assembly and module framing. Raw material dependencies encompass high-purity silicon metal, silver paste for cell metallization, and aluminum frames. Tariff exposure on Southeast Asian module imports threatens landed cost structures for United States data center developers. Distribution runs through authorized EPC contractor networks with direct-from-factory volume pricing for hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's hourly energy disclosure mandates erect a compliance moat that rewards operators with verified behind-the-meter generation while penalizing those reliant on annualized renewable certificates. This regulatory barrier-to-entry favors incumbents with capitalized solar assets and certified tracking infrastructure.
For Market Incumbents: To counter lithium-ion storage cost inflation eroding hybrid system margins, hyperscale operators should deepen backward integration into battery cell supply through long-term offtake partnerships with South Korean manufacturers. Incumbents must also secure IEEE 1547-certified inverter inventory ahead of grid integration protocol tightening in Germany and the United States. For New Entrants and Emerging Players: Edge computing nodes in India's Telangana and Karnataka data center parks represent an underserved buyer archetype with limited captive generation penetration and simplified interconnection thresholds below 500 kW. New entrants should target rapid-deployment monocrystalline rooftop kits with plug-and-play string inverters, leveraging state-level solar policies for accelerated permitting. For Investors and Strategic Acquirers: Exit pathways concentrate in tax equity partnership monetization for United States projects and operational asset sales to infrastructure funds seeking contracted cash flows. The five-to-ten-year viability window favors developers with interconnection queue positions in Northern Virginia and Frankfurt. Watch FERC interconnection study backlog clearance rates as the inflection signal for project commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Captive silicon supply insulates module costs from Xinjiang logistics disruptions and tariff exposure. |
| Power Purchase Agreement Structuring | Third-party ownership with fixed escalators transfers operational risk while preserving ITC monetization. |
| Hybrid Solar-Plus-Storage Deployment | DC-coupled configurations enable FERC Order 2222 participation and evening peak-shifting revenue. |
| Bifacial Module Specification | Albedo harvesting from white TPO roofing delivers yield premiums under EU Green Deal mandates. |
| EPC Contractor Partnership Lockups | Exclusive installation agreements secure qualified electrical engineering talent for medium-voltage interconnection. |
Research Methodology
Independent corroboration across data center EPC contractors, utility interconnection planners, and module procurement officers underwrites the qualitative findings in this study. Primary interviews with hyperscale sustainability directors, colocation facility managers, and thin-film technology specialists combined with secondary validation from FERC filings, EIA generation databases, IEA renewable energy reports, and EU regulatory transparency portals. Bottom-up project pipeline aggregation and top-down market sizing triangulate volume estimates across technology and capacity segments.
Comparable-period anchoring to historical deployment data from 2020 through 2025 established baseline coefficients for capacity expansion modeling across the projection horizon. The analytical framework segments by module technology, system architecture, end-user scale, and interconnection voltage tier, with CAGRs derived from regression against hyperscale capex disclosures and national renewable purchase obligation trajectories. Forecast inputs incorporate polysilicon price elasticity curves and lithium-ion battery cost compression schedules from supplier disclosure patterns.
Revisions become necessary when FERC interconnection queue reforms, EU carbon border adjustment implementation, or polysilicon trade policy shifts materialize beyond current baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Solar Metal Roof Market