
 US Smart Air Purifier Market | 2026-2036
US Smart Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Air Purifier Market Analytics
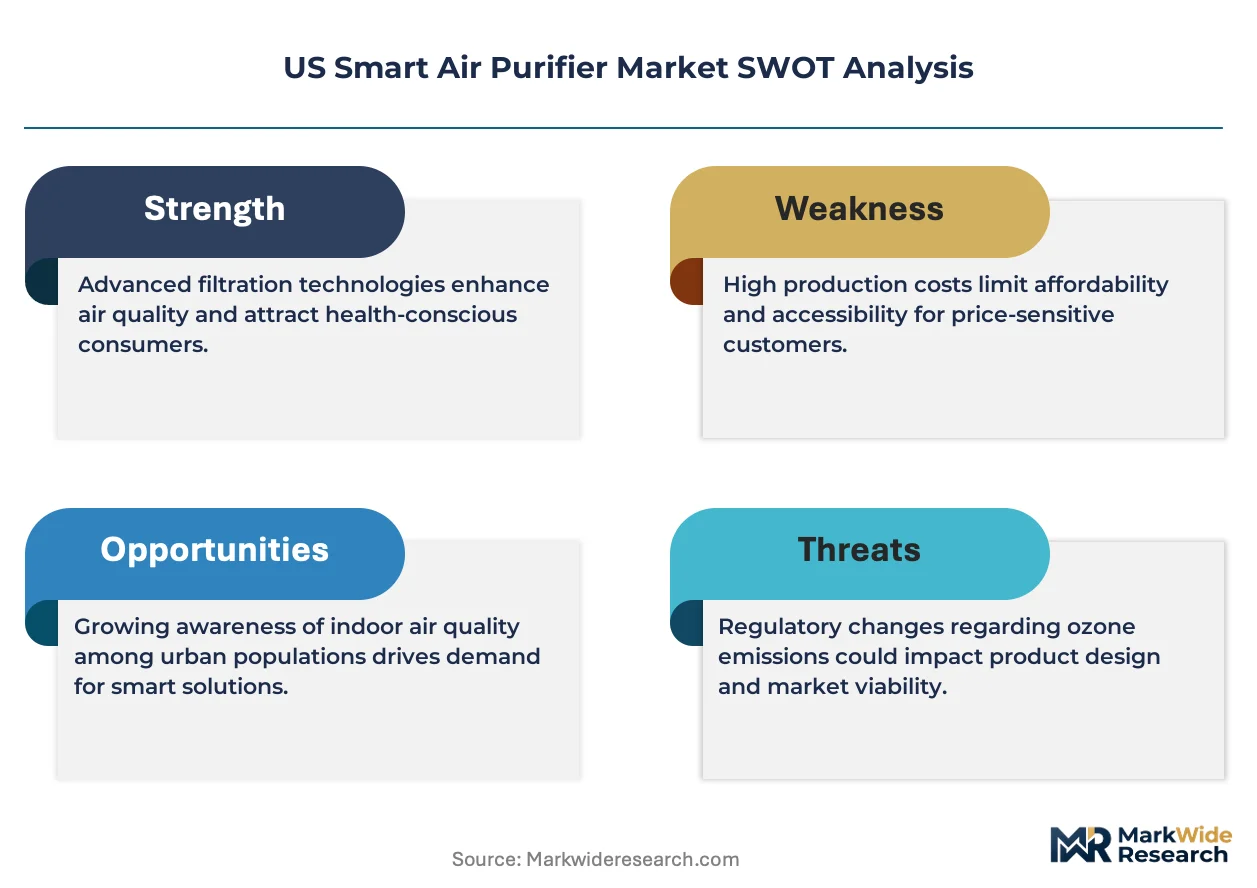
Embedded systems engineering talent scarcity is unwinding manufacturing timelines for connected filtration hardware. Honeywell International leverages its building automation heritage to sustain commercial channel dominance. Dyson Limited differentiates through proprietary air multiplier mechanics and direct-to-consumer positioning. Levoit anchors the mid-market residential tier through aggressive online retail pricing and compact form factors.
A smart air purifier integrates particulate sensors, wireless communication modules, and automated filter management to remove airborne contaminants including PM2.5, volatile organic compounds, and biological allergens from enclosed spaces. HEPA filtration remains the structural backbone of unit composition, though UV-C modules gain traction in hospital and school procurement specifications. Smart sensors and Wi-Fi connectivity represent the fastest-expanding technology layer, while voice control integration matures as a standard feature rather than premium differentiator. Online retail channels capture the dominant volume share, with specialty stores retaining relevance for commercial specification sales.
EPA indoor air quality standards and California Air Resources Board certification requirements shape product compliance pathways and filter efficiency claims. FCC oversight of wireless connectivity modules adds a secondary regulatory gate for smart feature deployment. OSHA workplace air quality guidelines further extend demand into office and institutional segments. Stakeholders must monitor evolving filter disposal regulations and interoperability standards that could reshape hardware architecture and recurring revenue models.
Market Dynamics
Embedded systems engineering scarcity compresses manufacturing timelines for connected filtration hardware, forcing OEMs to redesign around available chipsets and sensor modules. This talent gap concentrates production among vertically integrated suppliers with captive firmware development capabilities.
Growth Catalysts
- EPA Indoor Air Quality Standards:Tighter particulate exposure limits in residential and commercial buildings mandate automated filtration systems with real-time monitoring capabilities.
- Wildfire smoke penetration:Persistent particulate loads across California and Texas metro corridors accelerate replacement cycles and drive multi-unit household adoption.
- UV-C module integration:Hospital and school procurement specifications now require pathogen inactivation layers beyond standard HEPA capture, expanding unit bill-of-materials.
Market Restraints
- Semiconductor input volatility:Wi-Fi and Bluetooth module lead times extend firmware certification schedules, delaying smart feature rollouts.
- Filter supply concentration:HEPA media production clusters in East Asian manufacturing zones expose brands to freight cost fluctuations and tariff exposure.
- FCC certification friction:Wireless connectivity module approval adds secondary regulatory gates that compress margin on sub-$200 retail units.
Strategic Opportunities
- Underpenetrated institutional verticals:OSHA workplace air quality guidelines extend demand into small and mid-size office segments currently served by consumer-grade hardware.
- Voice control convergence:Integration with Alexa and Google Home ecosystems transforms smart air purifiers from standalone appliances to connected home infrastructure nodes.
- Filter subscription models:Automated filter replacement programs via Amazon Subscribe and Save and direct brand channels capture recurring revenue from installed base expansion.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent shortages force brands to outsource IoT stack development, creating IP leakage risks and update latency.
- Interoperability standardization delays:Fragmented Matter protocol adoption across HVAC and home automation vendors complicates cross-platform integration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Air Purifier Market |
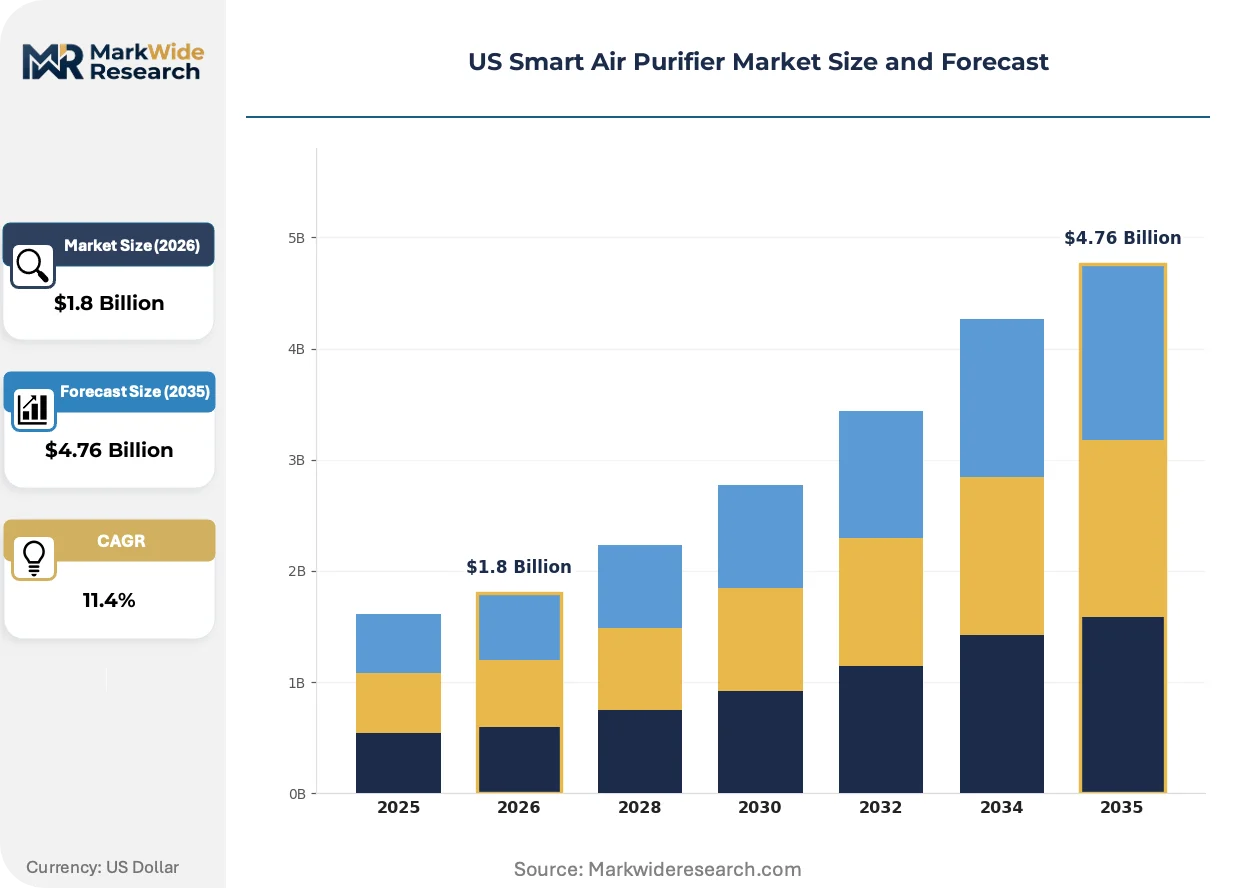
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, UV-C, Ionizer End User: Residential, Offices, Schools, Hospitals Technology: Smart Sensors, Wi-Fi Connectivity, Mobile App Integration, Voice Control Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Koninklijke Philips N.V., Whirlpool, Honeywell International, SharkNinja, Daikin Industries, Dyson Limited, Levoit, Blueair, Coway Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Air Purifier Market Evolving Landscape
Sensor fusion and edge computing architectures are compressing the latency between particulate detection and filtration response. These advances reshape competitive differentiation away from static CADR ratings toward dynamic air quality management.
Photocatalytic oxidation modules paired with activated carbon layers is supplanting standalone HEPA configurations in premium residential and commercial specifications. Hospitality chains and luxury multifamily developers specify these systems for VOC and odor control beyond particulate capture. This dual-stage architecture is supplanting single-filter designs in projects above $400 per unit, compressing addressable market for basic HEPA-only SKUs.
California Air Resources Board certification requirements now mandate ozone emission testing for all electronic air cleaning devices sold in the state. This creates a compliance moat that filters out unbranded imports and white-label suppliers lacking testing infrastructure. Products lacking CARB certification face channel exclusion from major retailers with California footprint, forcing portfolio rationalization among mid-tier competitors.
Facility managers in healthcare and education verticals now specify outcome-based performance contracts rather than capital equipment purchases. This procurement evolution transfers filter maintenance burden and air quality accountability to equipment vendors or third-party service integrators. Texas and Florida school districts pilot these arrangements most aggressively, driven by state-level indoor environmental quality mandates and liability exposure concerns.
US Smart Air Purifier Market Segmentation
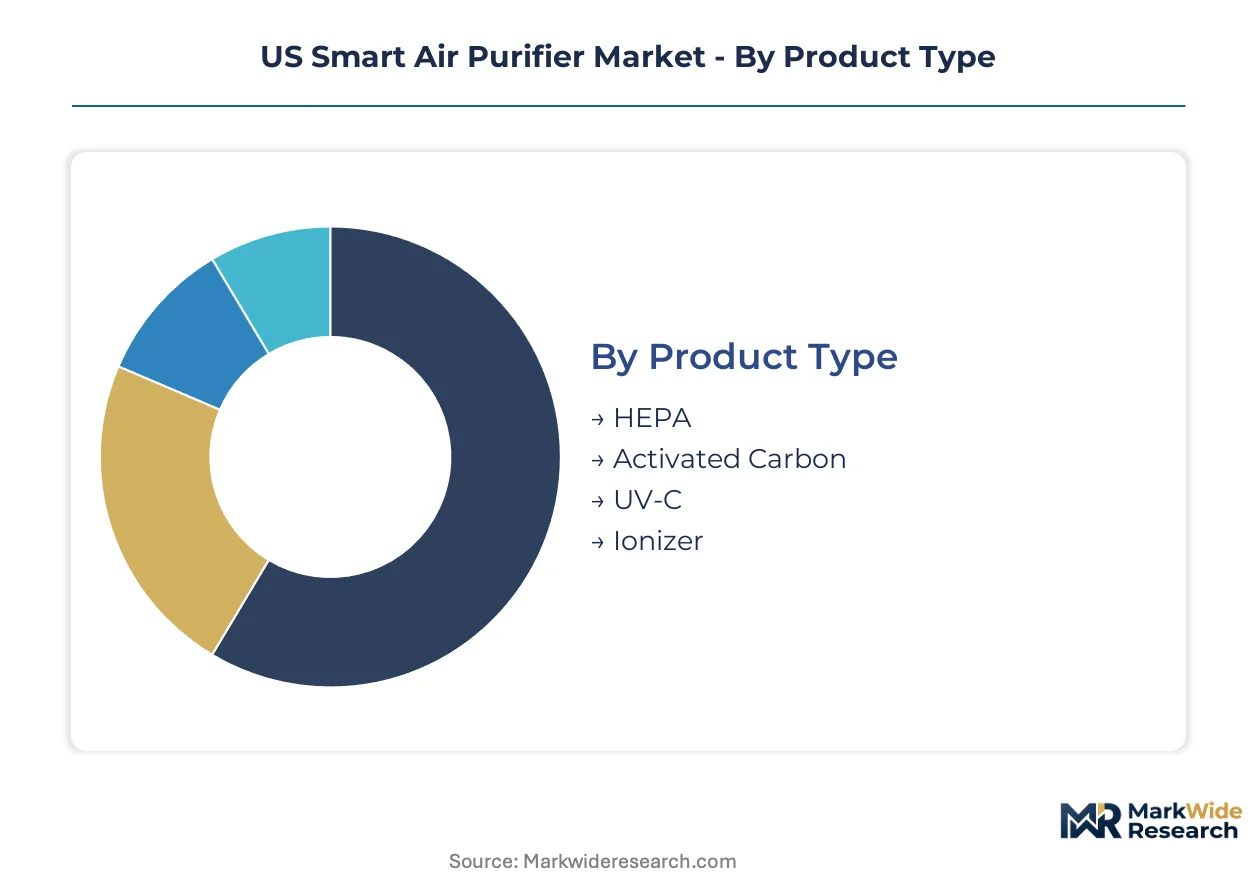
Product architecture in the US smart air purifier market fragments across filtration physics, connectivity layers, and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor positioning.
Product Type:
HEPA variants dominate domestic manufacturing footprints, while UV-C and ionizer segments rely more heavily on imported module assemblies.
- HEPA:High-efficiency particulate air media constructed from interlaced glass fibers captures 99.97% of particles at 0.3 microns. Demand concentrates in California and Texas residential corridors where wildfire smoke and allergen loads persist, with replacement cycles accelerating under tighter EPA indoor air quality guidelines.
- Activated Carbon:Porous carbon structures adsorb volatile organic compounds and odor molecules through physisorption mechanisms. Hospitality chains and luxury multifamily developers in Florida and Arizona specify these layers for VOC control beyond particulate capture, expanding unit bill-of-materials in premium residential specifications.
- UV-C:Ultraviolet germicidal irradiation modules inactivate pathogens through DNA disruption at 254 nanometers.
- Ionizer:Electrostatic precipitation systems charge airborne particles for collection on oppositely charged plates.
HEPA commands the established base. The steepest expansion runs through UV-C as hospital and school procurement specifications mandate pathogen inactivation layers.
End User:
Cost tier stratification separates capital-intensive institutional deployments from volume-driven residential replacement cycles.
- Residential:Single-family and multifamily households purchase compact units through online retail channels with automated filter subscription attachments. Urban centers in California and Texas metro corridors drive multi-unit household adoption amid persistent particulate loads.
- Hospitals:Acute care facilities specify outcome-based performance contracts transferring filter maintenance burden to equipment vendors. Texas and Florida school districts pilot these arrangements aggressively, driven by state-level indoor environmental quality mandates.
- Offices:OSHA workplace air quality guidelines extend demand into small and mid-size office segments.
- Schools:K-12 procurement specifications now require CARB-certified ozone emission testing for all electronic air cleaning devices.
Residential volume anchors manufacturer revenue. Hospitals deliver the fastest margin expansion through service-integrated procurement models.
Technology:
Maturity gradients separate baseline connectivity from emerging edge computing architectures reshaping competitive differentiation.
- Smart Sensors:Particulate matter and VOC detection modules enable real-time air quality indexing and automated filtration response. Sensor fusion architectures compress latency between detection and activation, displacing static CADR ratings as the primary competitive metric.
- Wi-Fi Connectivity:Wireless communication modules integrate units with home automation ecosystems. FCC certification adds secondary regulatory gates that compress margin on sub-$200 retail units, concentrating smart feature deployment in premium price tiers.
- Mobile App Integration:Proprietary smartphone interfaces deliver filter status monitoring and remote control functionality.
- Voice Control:Alexa and Google Home ecosystem integration transforms standalone appliances into connected home infrastructure nodes.
Smart sensors anchor the technology stack. Voice control integration is climbing the fastest as standard feature maturation erodes premium differentiation.
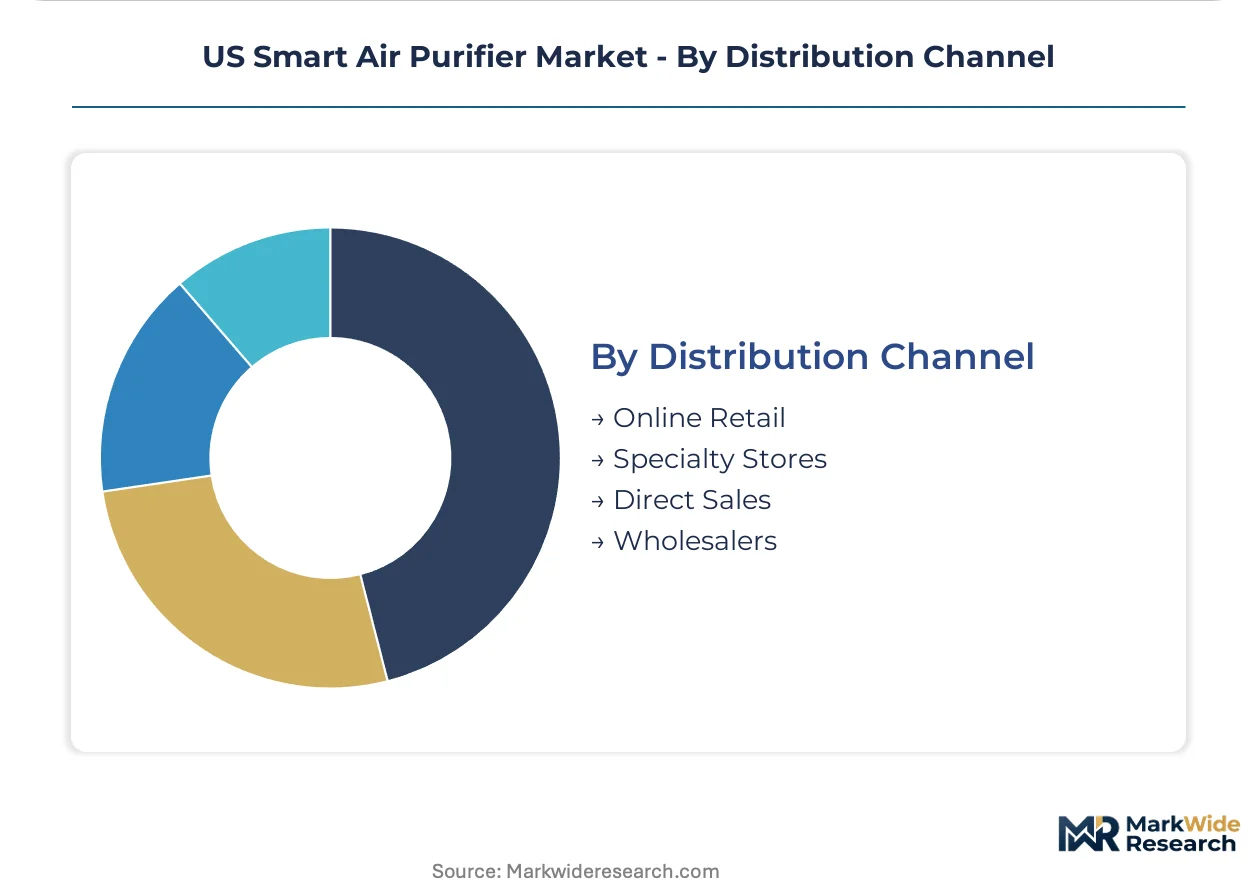
Distribution Channel:
Volume concentration versus margin capture defines channel strategy tradeoffs for brand portfolios.
- Online Retail:Amazon and direct-to-consumer platforms capture dominant volume share through aggressive pricing and automated filter subscription programs. Levoit anchors this channel through compact form factors and algorithmic retail placement.
- Specialty Stores:HVAC and home improvement retailers retain relevance for commercial specification sales requiring technical consultation. Honeywell leverages building automation heritage to sustain commercial channel dominance through this route.
- Direct Sales:Manufacturer-owned channels capture full margin on premium SKUs with extended warranty attachments.
- Wholesalers:Institutional procurement aggregators serve facility management and government contract vehicles.
Online retail commands volume leadership. Specialty stores deliver the steepest margin trajectory through specification consulting fees and service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas metro corridors where wildfire smoke and allergen loads persist, while the Midwest and Southeast trade on volume throughput at compressed margins. This geographic asymmetry shapes manufacturer channel strategy and inventory deployment.
California
Wildfire smoke penetration drives multi-unit household adoption across Los Angeles, San Francisco, and Sacramento metro areas. California Air Resources Board certification requirements mandate ozone emission testing for all electronic air cleaning devices sold in the state. The Bay Area and Southern California corridor anchors premium product demand where CARB compliance creates a regulatory moat filtering out unbranded imports.
Texas
Persistent particulate loads and allergen concentrations accelerate replacement cycles in Dallas-Fort Worth, Houston, and Austin. State-level indoor environmental quality mandates in K-12 procurement specifications require pathogen inactivation layers beyond standard HEPA capture. The Dallas-Fort Worth metroplex concentrates hospital and school district pilot programs for outcome-based performance contracts.
New York Metro
Urban residential density and aging building stock drive demand for compact units with automated filter management. EPA indoor air quality standards tighten particulate exposure limits in multifamily buildings. The five-borough area and adjacent New Jersey counties sustain specialty store relevance for commercial specification sales requiring technical consultation.
Pacific Northwest
Seasonal wildfire smoke events from British Columbia and Oregon penetrate the Seattle and Portland metro areas with increasing frequency. OSHA workplace air quality guidelines extend demand into small and mid-size office segments. The Seattle-Tacoma-Bellevue cluster concentrates smart home ecosystem integration demand as voice control matures as a standard feature.
Florida
Hospitality chains and luxury multifamily developers specify activated carbon layers for VOC and odor control beyond particulate capture. Humidity-driven biological allergen loads persist year-round in Miami, Orlando, and Tampa corridors. The Orlando metro area anchors procurement from theme park and resort operators upgrading indoor air quality infrastructure.
US Smart Air Purifier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with building automation heritage separating commercial channel dominance from direct-to-consumer scale. The vendor base concentrates among vertically integrated suppliers with captive firmware development capabilities and algorithmic retail placement. Three strategic archetypes define positioning: diversified industrial conglomerates with HVAC legacy, direct-to-consumer specialists with compact form factor expertise, and Asian manufacturing platforms with cost-optimized module assembly. Competitive moves center on filter subscription model deployment and voice control ecosystem integration as standard feature maturation erodes premium differentiation.
Within the diversified industrial tier, Honeywell International and Whirlpool exemplify building automation heritage sustaining commercial channel dominance through specification consulting and service bundling. Dyson Limited and Levoit occupy contrasting positions on the premium-direct versus mid-market-online spectrum, with the former leveraging proprietary mechanics and the latter anchoring algorithmic retail placement. Koninklijke Philips N.V. represents the European multinational archetype with healthcare-adjacent brand equity. Daikin Industries and Coway Co. exemplify Asia-Pacific manufacturing platforms with module assembly scale and cost-optimized supply chains. SharkNinja and Blueair sit within the specialty appliance segment, with the former leveraging small appliance distribution velocity and the latter representing Nordic design-positioned filtration specialists.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Whirlpool |
| Honeywell International |
| SharkNinja |
| Daikin Industries |
| Dyson Limited |
| Levoit |
| Blueair |
| Coway Co. |
| Others |
Value Network & Pricing Analysis
California Air Resources Board certification requirements gate both supply qualification and price differentiation simultaneously, filtering unbranded imports from major retailer channels while compressing margin on sub-$200 units that lack testing infrastructure. EPA indoor air quality standards and FCC wireless module oversight add secondary regulatory layers that reshape cost structures across the pricing spectrum.
Pricing Analysis
California and Texas metro corridors command 15-25% price premiums over Midwest markets where volume throughput runs at compressed margins. Pricing stratifies across premium, standard, and economy tiers with CARB certification and voice control integration as primary differentiation drivers. Cost compression in the sub-$200 tier is intensifying because FCC certification friction erodes residual margin. Residential online buyers exhibit highest price sensitivity while hospital procurement committees prioritize outcome-based performance contracts over unit economics.
Supply Chain Analysis
East Asian manufacturing chokepoints for HEPA media production expose brands to freight cost fluctuations and tariff exposure. HEPA filter media draws from China, South Korea, and Japan while Wi-Fi and Bluetooth modules source from Taiwan and mainland China facilities. Single-source vulnerability concentrates in specialized sensor fusion chipsets and UV-C lamp assemblies. Distribution runs through Amazon and direct-to-consumer platforms for volume capture, with HVAC specialty retailers retaining commercial specification relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter subscription programs via Amazon Subscribe and Save and direct brand channels expand faster than hardware unit sales, transforming one-time transactions into recurring revenue streams with superior lifetime value economics.
For Market Incumbents: Shield commercial channel dominance by deepening firmware development capabilities in-house rather than outsourcing IoT stack development to contract partners. Invest in CARB certification infrastructure to maintain retailer access moats against emerging white-label competitors. Capacity addition in Texas and Florida school district corridors captures outcome-based performance contract pilots before procurement patterns solidify. For New Entrants and Emerging Players: Filter subscription management services represent a service-layer gap where incumbents under-serve small and mid-size office segments. Target OSHA workplace air quality guideline compliance in underpenetrated institutional verticals currently served by consumer-grade hardware. A direct-to-Consumer launch with automated replacement scheduling software bypasses established brand recognition barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across UV-C module assembly as manufacturing scales and component costs compress. Long-term viability favors vertically integrated suppliers with captive firmware development capabilities and algorithmic retail placement rather than pure hardware assemblers. The signal to watch is Matter protocol adoption velocity across HVAC and home automation vendor ecosystems as interoperability standardization reshapes competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Subscription Model Deployment | Amazon Subscribe and Save integration transforms unit sales into recurring revenue with superior customer lifetime value. |
| Voice Control Ecosystem Integration | Alexa and Google Home compatibility matures smart air purifiers into connected home infrastructure nodes. |
| UV-C Module Manufacturing Scale-Up | Hospital and school procurement specifications mandate pathogen inactivation layers beyond standard HEPA capture. |
| CARB Certification Infrastructure Investment | Ozone emission testing compliance creates channel exclusion moats against unbranded imports in California. |
| Outcome-Based Performance Contracting | Texas and Florida school districts pilot service-integrated procurement transferring maintenance burden to vendors. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Conversations with embedded systems engineers, HVAC specification consultants, Amazon category managers, hospital procurement directors, and school district facilities managers informed supply chain and channel dynamics. Secondary validation drew from EPA indoor air quality guidance documents, FCC equipment authorization databases, California Air Resources Board certification listings, and OSHA workplace exposure guidelines. Bottom-up unit economics modeling triangulated against top-down market sizing from trade flow and retail audit data.
Sensitivity analysis around semiconductor input cost volatility and filter media freight rates stress-tested projection robustness across the analysis window. The analytical framework segments by filtration physics, connectivity layer maturity, procurement channel, and end-user vertical with geographic price-spread differentials. CAGRs derive from installed base expansion rates, replacement cycle compression, and technology layer adoption curves. Wildfire smoke penetration frequency and EPA guideline tightening velocity served as demand-side scenario inputs.
Forecasts assume regulatory continuity in EPA indoor air quality standards, FCC wireless certification requirements, and California Air Resources Board ozone emission testing; material policy shifts would require re-modeling demand trajectories and compliance cost structures. Semiconductor lead time normalization, tariff regime changes, and Matter protocol adoption velocity represent specific risk factors that could revise hardware shipment and margin assumptions. Practitioners should keep alternative scenarios live as wildfire season intensity and K-12 indoor environmental quality mandate expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
MEMS Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Middle East and Africa Touch Sensor Market