
 MEMS Market | 2026-2036
MEMS Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Market Outlook
Multi-source procurement from foundry partners is broadening supply security for fabless MEMS designers. Texas Instruments sustains captive wafer fabrication for analog-integrated MEMS, while STMicroelectronics leverages 300mm pilot lines to reduce die costs for consumer gyroscopes. Robert Bosch GmbH anchors European supply through in-house production of automotive pressure and inertial sensors.
Microelectromechanical systems are micron-scale mechanical structures fabricated on silicon wafers using surface or bulk micromachining, typically integrating suspended proof masses, comb drives, or piezoelectric thin films with CMOS readout circuitry to transduce physical signals into electrical outputs. Pressure sensors and accelerometers occupy mature, high-volume positions in automotive tire monitoring and smartphone motion tracking, while microphones compete on array density for noise-canceling earwear. Gyroscopes lead in navigation-grade precision for defense and autonomous platforms, where margin pools concentrate on temperature-stable, high-g devices.
FDA 21 CFR Part 820 quality system requirements shape medical MEMS development timelines for implantable pressure monitors, while REACH and RoHS restrict substrate and packaging material choices across European-bound shipments. FAA airworthiness directives and DO-160G environmental standards govern aerospace qualification paths for inertial measurement units. Stakeholders must weigh certification overhead against the premium pricing available in regulated verticals when allocating R&D capacity across consumer and industrial product lines.
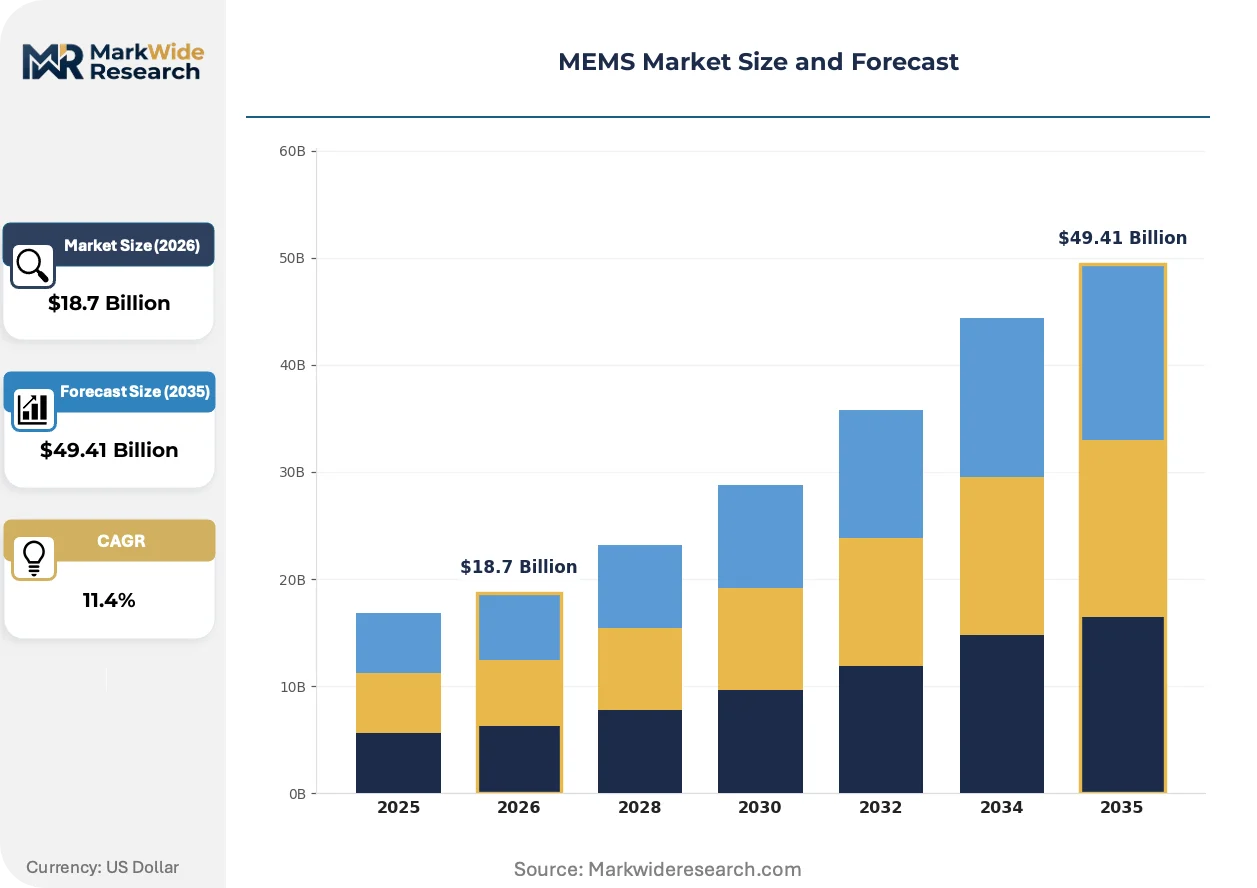
Market Dynamics
Automotive electrification and autonomous driving architectures are forcing a sensor density inflection, with each vehicle platform now specifying 40-100 discrete MEMS elements for powertrain, chassis, and cabin monitoring functions.
Growth Catalysts
- Euro NCAP safety mandates:Five-star rating protocols now require pedestrian detection and automatic emergency braking, mandating radar-accelerometer fusion modules in every new vehicle platform sold across the European Union.
- India's PLI scheme for electronics manufacturing:Subsidized capital expenditure for semiconductor packaging is drawing MEMS assembly capacity toward Gujarat and Tamil Nadu, diversifying supply away from traditional East Asian hubs.
- Silicon photonics convergence:Foundries are integrating MEMS tunable filters with photonic integrated circuits, opening optical switching applications in data center interconnects previously served by discrete components.
Market Restraints
- Specialized wafer supply concentration:Silicon-on-insulator substrates for high-performance inertial sensors source predominantly from French and Japanese suppliers, creating single-point vulnerability for fabless designers.
- REACH substance restrictions:ECHA's candidate list expansion for SVHCs is forcing reformulation of lead-based piezoelectric materials in ultrasonic transducers, extending qualification timelines by 18-24 months.
- Optical encoders:Magnetic and capacitive MEMS position sensors face displacement in precision robotics by photonic encoder modules offering sub-arc-second accuracy without temperature drift compensation.
Strategic Opportunities
- Indonesia's nickel-processing corridor:Battery-grade nickel refining in Sulawesi is creating localized demand for high-temperature pressure sensors in hydrometallurgical reactors, an application segment with limited incumbent presence.
- FDA breakthrough device designation:Expedited review pathways for implantable MEMS-based continuous glucose monitors are compressing time-to-revenue for neuromodulation and cardiovascular pressure monitoring platforms.
- Edge AI sensor fusion:Integration of MEMS accelerometers with neuromorphic compute dies is enabling always-on vibration classification for predictive maintenance without cloud connectivity, opening industrial IoT deployments in bandwidth-constrained environments.
Industry Challenges
- Multi-physics simulation expertise:Coupled electro-mechanical-thermal modeling for MEMS design requires rare cross-disciplinary talent combining finite element analysis with CMOS circuit design, constraining R&D throughput at mid-size firms.
- DO-160G environmental qualification:Aerospace inertial measurement units must demonstrate operational integrity across temperature shock, humidity, and vibration profiles that extend development cycles to 4-7 years before first revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Pressure Sensors, Microphones Application: Automotive, Consumer Electronics, Industrial Automation, Medical Devices Technology: Surface Micromachining, Bulk Micromachining, High-Temperature Co-Fired Ceramics, Piezoelectric End User: Aerospace, Telecommunications, Healthcare, Defense |
| Companies Covered | Texas Instruments, Murata Manufacturing, Robert Bosch GmbH, Infineon Technologies, Knowles Electronics, STMicroelectronics, TDK InvenSense, NXP Semiconductors, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Market Strategic Shifts
Process migration toward 300mm wafer platforms is compressing die economics while enabling monolithic integration with advanced CMOS nodes, fundamentally restructuring competitive positioning between captive and fabless supply models.
Monolithic integration of piezoelectric aluminum nitride thin films with 22nm CMOS readout circuitry is automating self-test and calibration routines previously requiring external ASICs. Automotive tier-one suppliers are adopting these smart sensor platforms for chassis control modules, reducing bill-of-materials complexity by 30-40%. The technology is automating the displacement of discrete multi-chip module architectures that dominated prior vehicle generations.
The EU AI Act's risk classification framework is mandating conformity assessments for safety-critical sensor systems deployed in autonomous mobility applications. MEMS inertial units now require documented algorithmic transparency and fail-operational performance validation before CE marking. German automotive manufacturers are responding by pre-qualifying dual-redundant sensor configurations that satisfy both functional safety ISO 26262 and emerging AI governance requirements.
Direct foundry relationships are displacing traditional component distribution for high-volume consumer electronics OEMs. Apple and Samsung now contract MEMS die supply through multi-year capacity reservations with TSMC and GlobalFoundries, bypassing established sensor module distributors. This channel compression is most visible in smartphone microphone and accelerometer procurement, where spot-market purchasing has declined to sub-10% of volume.
MEMS Market Segmentation
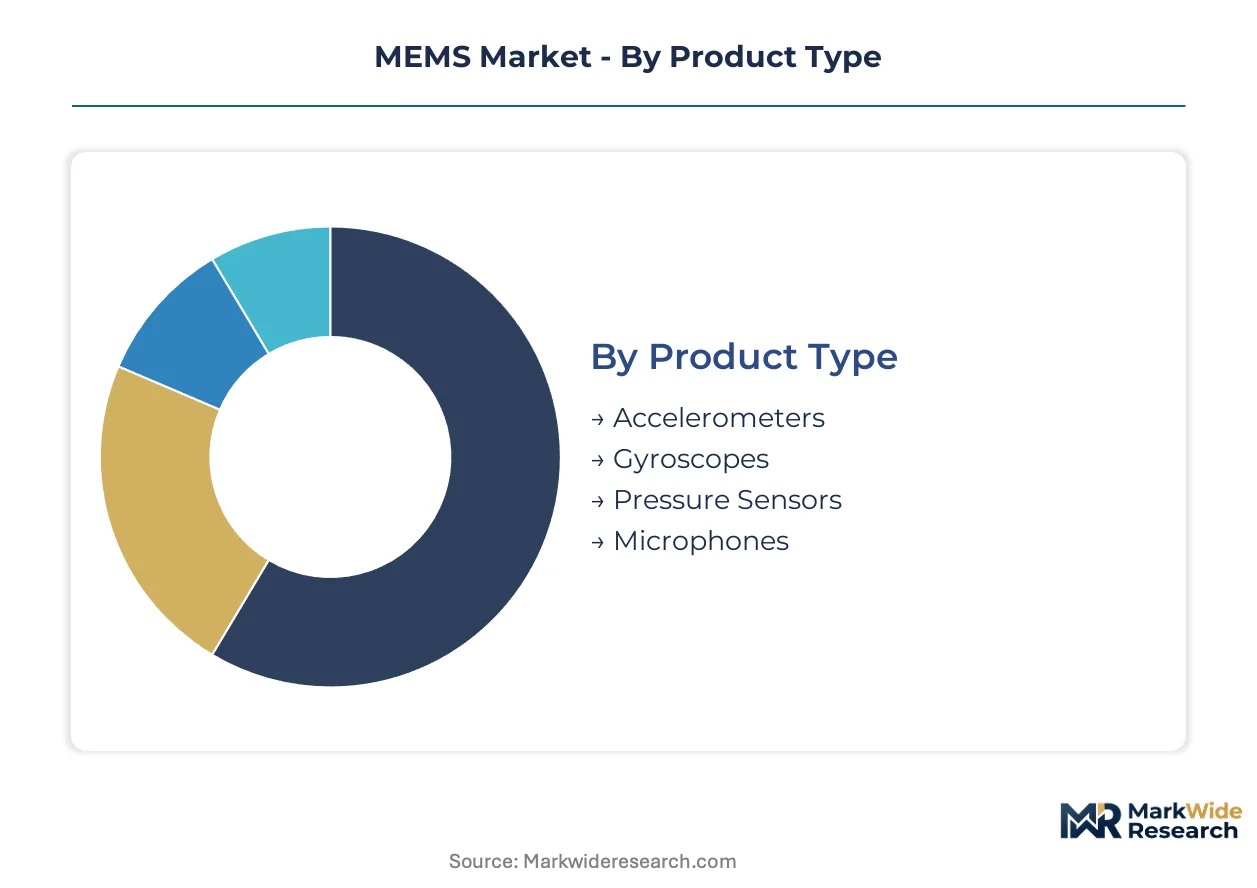
MEMS market segmentation reveals distinct margin architectures across product physics and qualification regimes. Buyer procurement decisions diverge sharply between cost-optimized consumer specifications and safety-certified automotive tiers.
Product Type:
Selection criteria center on measurement axis count, noise floor, and temperature stability requirements.
- Accelerometers:Capacitive sensing structures detect linear acceleration across single to tri-axial configurations. Automotive chassis control modules in Germany specify these for electronic stability programs under Euro NCAP mandates. Volume concentrates in smartphone motion tracking, though margin pools favor automotive grades.
- Gyroscopes:Coriolis-effect resonating structures measure angular velocity with precision ranging from consumer-grade 10°/hour drift to navigation-grade 0.01°/hour specifications. Defense platforms and autonomous vehicles in the United States demand temperature-compensated designs for GPS-denied navigation.
- Pressure Sensors:Piezoresistive diaphragms transduce pneumatic and hydraulic pressures for tire monitoring systems.
- Microphones:Capacitive backplate-diaphragm assemblies capture acoustic signals with signal-to-noise ratios exceeding 70dB for noise-canceling earwear.
Volume sits with Accelerometers; growth tilts toward Gyroscopes.
Application:
End-use environments dictate packaging hermeticity, calibration protocols, and supply chain qualification depth.
- Automotive:Powertrain, chassis, and cabin monitoring functions each specify distinct MEMS specifications. NHTSA mandates in the United States and Euro NCAP protocols in Germany drive 40-100 discrete sensors per electrified vehicle platform. Functional safety ISO 26262 certification separates qualified suppliers from commodity entrants.
- Consumer Electronics:Smartphone and wearable OEMs prioritize die size and unit economics over precision. Motion tracking and voice interfaces absorb high volumes at compressed margins, with procurement consolidating through direct foundry contracts.
- Industrial Automation:Predictive maintenance applications require vibration sensors with 10-year reliability guarantees.
- Medical Devices:FDA 21 CFR Part 820 quality systems govern implantable pressure monitors and continuous glucose measurement platforms.
Revenue concentrates in Automotive; expansion accelerates most steeply in Medical Devices.
Technology:
Fabrication method determines integration feasibility with CMOS readout circuitry and unit economics at scale.
- Surface Micromachining:Sacrificial layer etching builds suspended mechanical structures on standard silicon substrates. Consumer gyroscopes and accelerometers leverage this for monolithic integration with 22nm CMOS at STMicroelectronics' 300mm pilot lines.
- Bulk Micromachining:Deep reactive-ion etching sculpts mechanical features directly into silicon wafers. High-aspect-ratio structures serve automotive pressure sensors requiring robust diaphragm geometries.
- High-Temperature Co-Fired Ceramics:Multilayer ceramic substrates package sensors for extreme thermal environments.
- Piezoelectric:Aluminum nitride thin films enable self-test and calibration automation in smart sensor platforms.
Deployment favors Surface Micromachining; qualification momentum builds behind Piezoelectric integration.
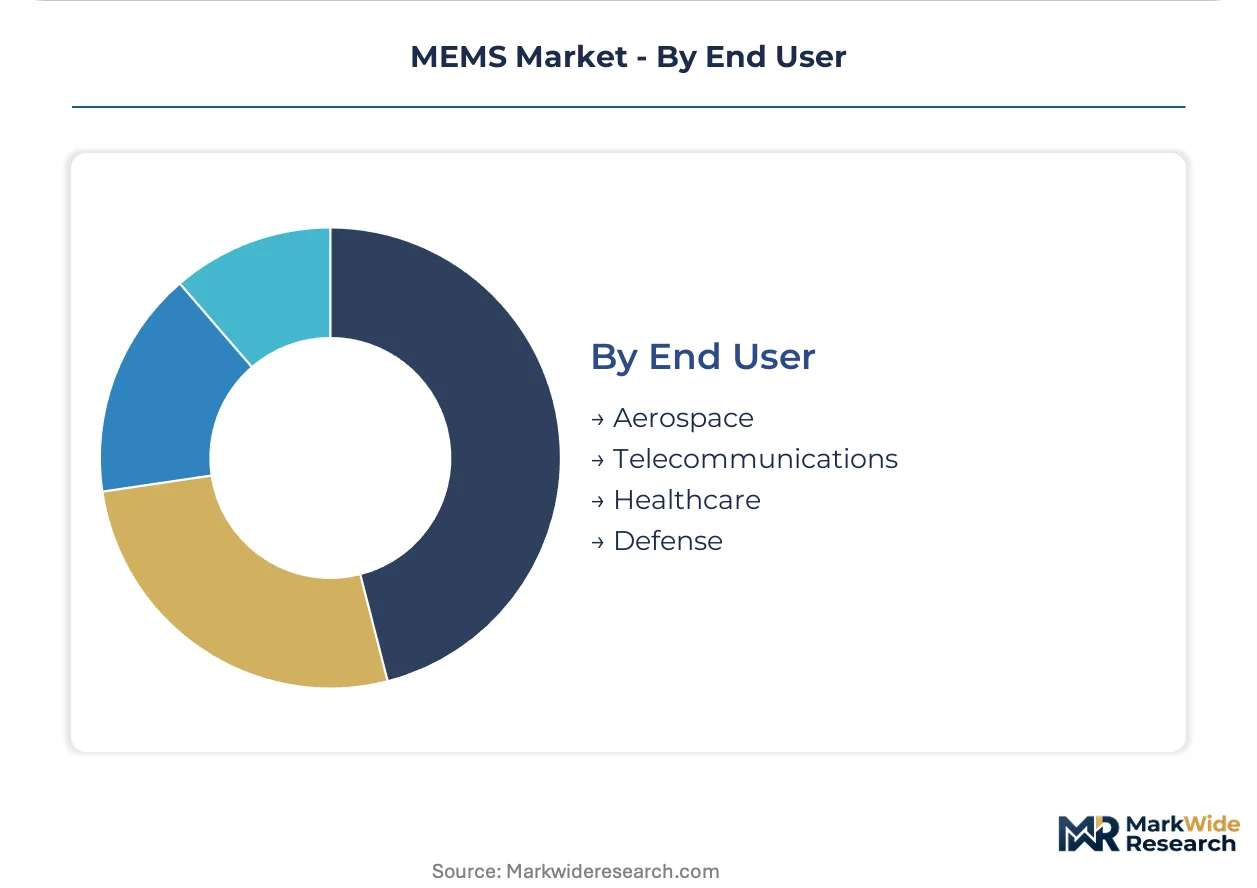
End User:
Certification burden and procurement cycle length segment the addressable market by organizational risk tolerance.
- Aerospace:FAA airworthiness directives and DO-160G environmental standards impose 4-7 year development cycles before first revenue. Inertial measurement units for commercial aviation command premium pricing contingent on temperature shock and vibration qualification.
- Telecommunications:Optical switching infrastructure absorbs MEMS-tunable filters integrated with silicon photonics. Data center interconnect demand in the United States drives foundry capacity allocation for these hybrid devices.
- Healthcare:Implantable and diagnostic applications require biocompatibility validation and sterilization stability.
- Defense:Navigation-grade inertial systems for weapons platforms specify radiation-hardened electronics and secure supply chains.
Contract value peaks in Aerospace; procurement velocity runs highest in Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon-on-insulator wafer supply from French and Japanese substrate specialists anchors the geographic distribution of high-performance MEMS fabrication. Foundry capacity concentrates where automotive electrification and consumer electronics OEMs cluster.
United States
NHTSA mandates for automatic emergency braking and pedestrian detection drive sensor deployment across Detroit and Austin automotive design centers. FDA 21 CFR Part 820 governs medical MEMS development timelines for implantable pressure monitors in Minnesota and California. Defense navigation-grade gyroscopes for GPS-denied applications concentrate in Boston and Los Angeles aerospace corridors.
Germany
Euro NCAP five-star safety protocols mandate radar-accelerometer fusion modules for every new vehicle platform. REACH and RoHS substance restrictions from ECHA force reformulation of lead-based piezoelectric materials. Bosch and Infineon anchor production clusters in Stuttgart and Dresden for automotive pressure and inertial sensing modules.
China
MIIT industrial policy accelerates domestic MEMS foundry capacity for smartphone motion tracking and tire pressure monitoring. GB standards and dual carbon goals shape substrate material choices for consumer electronics OEMs in Shenzhen and Shanghai. Yangtze River Delta packaging houses scale assembly for noise-canceling earwear microphones.
Japan
METI technology roadmaps prioritize silicon photonics convergence for data center optical switching applications. JIS standards govern quality systems for automotive gyroscopes supplied to Toyota and Honda platforms in Nagoya and Tokyo. Bulk micromachining expertise for high-aspect-ratio pressure sensors concentrates in Kyoto-Osaka precision manufacturing belts.
India
PLI scheme subsidies for semiconductor packaging draw MEMS assembly capacity toward Gujarat and Tamil Nadu. BIS certification requirements shape import substitution strategies for automotive tier-one suppliers. Chennai and Bengaluru clusters diversify supply away from traditional East Asian hubs for consumer accelerometer modules.
MEMS Market Competitive Environment
Capacity reservation agreements dominate the current landscape as high-volume consumer electronics OEMs secure multi-year foundry allocations. The vendor base stratifies across captive fabrication, fabless design, and hybrid model archetypes. Texas Instruments sustains in-house wafer production while STMicroelectronics leverages 300mm pilot lines. Strategic moves center on direct foundry contracting and geographic diversification of assembly capacity.
Among European-anchored suppliers, Robert Bosch GmbH and Infineon Technologies exemplify the captive fabrication archetype through in-house production of automotive-grade sensing modules. STMicroelectronics occupies a position bridging fabless design with pilot-line scale advantages for consumer gyroscopes. These three entities represent distinct competitive postures: Bosch anchors safety-critical automotive supply, Infineon concentrates on powertrain and chassis applications, and STMicroelectronics targets die cost compression through 300mm process migration.
| Leading Market Players |
|---|
| Texas Instruments |
| Murata Manufacturing |
| Robert Bosch GmbH |
| Infineon Technologies |
| Knowles Electronics |
| STMicroelectronics |
| TDK InvenSense |
| NXP Semiconductors |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Automotive ISO 26262 certification tiers bifurcate MEMS pricing into safety-qualified premiums and consumer-grade commodities, with the divergence manifesting in both unit economics and supply chain depth. Fabless designers serving smartphone OEMs compete on die cost through foundry spot markets, while Tier 1 automotive suppliers lock in multi-year capacity reservations with captive wafer fabrication at Bosch and Infineon.
Pricing Analysis
Warranty and calibration service bundling separates navigation-grade gyroscope contracts from unbundled consumer accelerometer spot purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, with FDA 21 CFR Part 820 compliance adding substantial overhead to implantable pressure monitors. Cost compression in consumer microphones is intensifying because direct foundry contracting by Apple and Samsung has collapsed distributor margins. Automotive tier-one buyers exhibit lowest price sensitivity due to liability exposure, while smartphone OEMs drive hardest bargain on per-die economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for smartphone accelerometers, while specialized distributors serve aerospace and medical device qualification pathways. Silicon-on-insulator wafer supply concentrates in France and Japan, with bulk micromachining expertise anchored in German precision manufacturing belts. Aluminum nitride thin films and deep reactive-ion etching equipment constitute critical input dependencies. Single-source vulnerability for high-performance inertial substrates creates structural risk. Distribution runs through foundry-direct contracts for consumer volumes and authorized distributors for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized wafer supply constraints prop MEMS pricing power, with silicon-on-insulator substrate bottlenecks limiting fabless competitor entry into navigation-grade segments.
For Market Incumbents: Deepen captive fabrication capacity in automotive-grade pressure sensing to defend against silicon photonics displacement in precision positioning. Lock in multi-year silicon-on-insulator supply agreements with French and Japanese substrate specialists before capacity tightens further. Prioritize dual-redundant sensor architectures that satisfy emerging EU AI Act conformity assessments. For New Entrants and Emerging Players: Capture Indonesia's nickel-processing corridor demand for high-temperature pressure sensors in hydrometallurgical reactors, a segment with limited incumbent presence. Target FDA breakthrough device designation pathways for implantable continuous glucose monitors to compress qualification timelines. Pursue foundry partnerships for piezoelectric aluminum nitride integration rather than building captive fabrication. For Investors and Strategic Acquirers: Re-rating potential sits with fabless designers possessing direct foundry relationships given channel compression accelerating in consumer electronics. Multi-year capacity reservation agreements with TSMC or GlobalFoundries signal durable revenue visibility. Watch for silicon photonics convergence announcements as inflection indicator for optical switching segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| 300mm Process Migration | STMicroelectronics' pilot lines compress die costs for consumer gyroscopes against 200mm legacy competitors. |
| Dual-Redundant Sensor Certification | German automotive OEMs pre-qualify configurations satisfying both ISO 26262 and EU AI Act requirements. |
| Silicon Photonics Convergence | MEMS tunable filter integration with photonic circuits opens data center interconnect applications. |
| Direct Foundry Contracting | Apple and Samsung bypass distributors through multi-year capacity reservations with TSMC. |
| Geographic Assembly Diversification | India's PLI scheme draws packaging capacity toward Gujarat and Tamil Nadu from East Asian hubs. |
Study Parameters
Multi-period observation of foundry capacity utilization, certification timeline durations, and automotive platform sensor counts anchored the trend analysis, supplemented by interviews with MEMS design engineers, Tier 1 automotive procurement managers, FDA regulatory consultants, and silicon photonics integration specialists. Secondary validation drew from SEC semiconductor filings, ECHA REACH substance restriction updates, NHTSA safety mandate documentation, and IHS vehicle production databases. Bottom-up die shipment modeling triangulated against top-down automotive electronics value chain estimates.
Segment-weighting across product type, application, technology, and end-user dimensions structured the analytical framework, with automotive electrification sensor density curves and consumer electronics direct procurement patterns informing growth allocation throughout the forecast period. CAGRs derived from regression against historical foundry capacity expansion and qualification timeline compression. Forecast inputs incorporated Euro NCAP protocol evolution and FDA breakthrough device designation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon-on-insulator substrate supply disruptions and REACH substance restriction expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market