
 Ultrasonic Sensors Market | 2026-2036
Ultrasonic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Sensors Market Analysis
Project finance for smart factory retrofits is reconfiguring competitive entry barriers in ultrasonic sensing. Keyence Corporation leverages its direct sales force to sustain premium positioning across Asian manufacturing hubs. Pepperl+Fuchs anchors European industrial automation with intrinsically safe sensor designs. Honeywell International Inc. competes through backward integration into piezoelectric ceramic production.
Ultrasonic sensors emit high-frequency acoustic pulses—typically 40 kHz to 400 kHz—and measure time-of-flight echoes to detect object presence, distance, or liquid level without physical contact. Piezoelectric transducers dominate industrial-grade units due to their electromechanical efficiency and temperature resilience. Distance sensors lead revenue contribution from automotive parking assistance and logistics pallet detection, while flow measurement applications in water management are gaining fastest. Analog sensors retain share in cost-sensitive machinery retrofits, though digital variants with IO-Link connectivity capture margin pools in new smart-factory installations.
The EPA enforces emissions and material standards affecting sensor housings in US automotive and industrial deployments. REACH and RoHS in Europe restrict hazardous substances in piezoelectric ceramics and solder joints, compelling reformulation of transducer stacks. Japan's METI promotes factory automation standards that integrate ultrasonic devices into Industry 4.0 architectures. Stakeholders must weigh certification breadth against regional production footprint decisions as compliance fragmentation intensifies.
Market Dynamics
Project finance for smart factory retrofits is reconfiguring competitive entry barriers in ultrasonic sensing, as capital deployment shifts from greenfield automation to brownfield sensor integration requiring backward compatibility with legacy PLC architectures.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is compelling HVAC and cold-chain operators to adopt sealed, refrigerant-free ultrasonic flow sensors for leak detection and thermal management.
- ADAS mandate acceleration:Parking assistance and blind-spot monitoring regulations in Germany and Japan are embedding ultrasonic arrays into vehicle bumpers and side mirrors as standard equipment.
- Shenzhen-Shanghai automation corridor:Industrial robot density targets in China's Pearl River and Yangtze River Delta regions are pulling demand for high-frequency distance sensors in pallet detection and collision avoidance.
Market Restraints
- Piezoelectric ceramic supply concentration:Sintering capacity for lead zirconate titanate transducers clusters in Japanese and Chinese material suppliers, exposing buyers to allocation risk during semiconductor-capacitor demand spikes.
- REACH substance restrictions:European chemical regulations on lead content in piezoelectric stacks are forcing reformulation of transducer compositions, extending qualification timelines for industrial-grade units.
- LiDAR cost compression:Solid-state optical ranging modules are displacing ultrasonic arrays in premium autonomous vehicle perception stacks above Level 2 autonomy.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for component manufacturing are attracting sensor assembly investments to Gujarat and Tamil Nadu corridors for domestic industrial automation supply.
- IO-Link protocol convergence:The unification of digital sensor interfaces with Ethernet-APL networks is opening retrofit markets in process industries previously locked into analog 4-20 mA infrastructures.
- Water utility digitization:Non-invasive ultrasonic flow measurement is capturing share from mechanical meters in smart city deployments across Southeast Asian megacities facing non-revenue water reduction mandates.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers skilled in time-of-flight algorithm optimization and acoustic beamforming is constraining product development cycles for multi-transducer arrays.
- Cross-border certification fragmentation:Divergent EMC and safety standards between FCC Part 15, CE marking, and GB/T compliance are multiplying test burden for sensor platforms targeting multiple industrial automation markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Sensors Market |
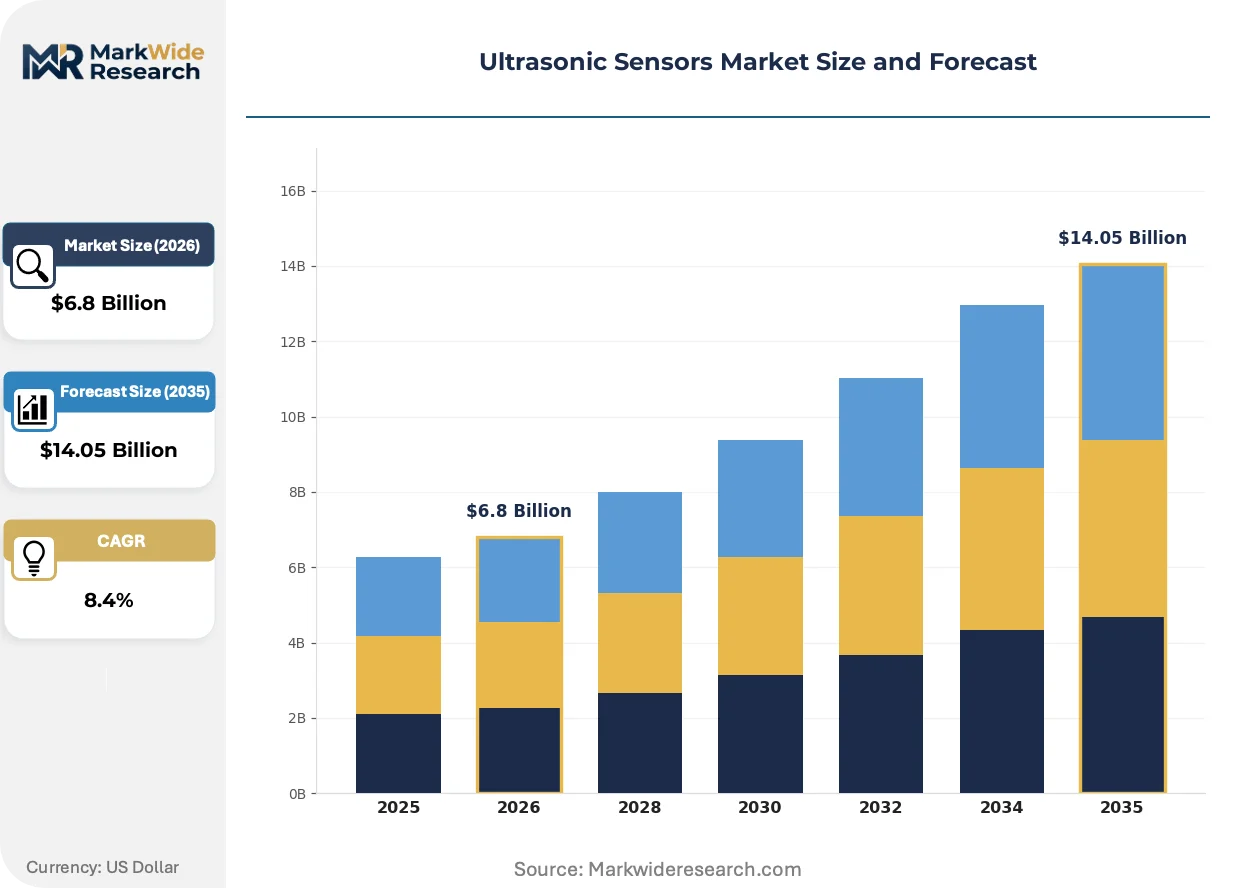
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Pressure Sensors, Distance Sensors Technology: Piezoelectric, Capacitive, Optical, Magnetic End User: Automotive, Industrial Automation, Healthcare, Consumer Electronics Application: Level Measurement, Flow Measurement, Object Detection, Parking Assistance |
| Companies Covered | Keyence Corporation, Pepperl+Fuchs, Honeywell International Inc., SICK AG, Omron Corporation, Rockwell Automation, Balluff Inc., Banner Engineering Corp., Murata Manufacturing Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Sensors Market Emerging Trajectories
Acoustic sensing architectures are pivoting from analog signal chains to software-defined measurement systems, compressing hardware differentiation and elevating firmware and edge-analytics capabilities as primary value drivers.
Time-of-flight sensor modules with integrated digital signal processors are digitizing distance measurement workflows in automotive and logistics applications. Tier 1 suppliers in Germany are specifying these units for parking assistance systems requiring sub-centimeter resolution. The shift is digitizing margin capture toward semiconductor and software suppliers, compressing value for discrete transducer vendors.
REACH and RoHS substance restrictions in Europe are mandating lead-free piezoelectric ceramic formulations and halogen-free solder joints in transducer stacks. Industrial sensor manufacturers are redesigning housing assemblies and bonding processes to maintain electromechanical coupling efficiency under these constraints. Water management and food processing segments in the EU are prioritizing certified compliant units, creating procurement preference divergence from cost-optimized Asian industrial markets.
After-sales calibration and maintenance contracts are unbundling from hardware sales in process industry deployments. Chemical and pharmaceutical operators in the US Gulf Coast are purchasing sensor performance guarantees rather than capital equipment, shifting vendor relationships toward service-level agreements. This model is most visible in Texas and Louisiana refineries where EPA emissions monitoring mandates require continuous flow measurement uptime commitments.
Ultrasonic Sensors Market Segmentation
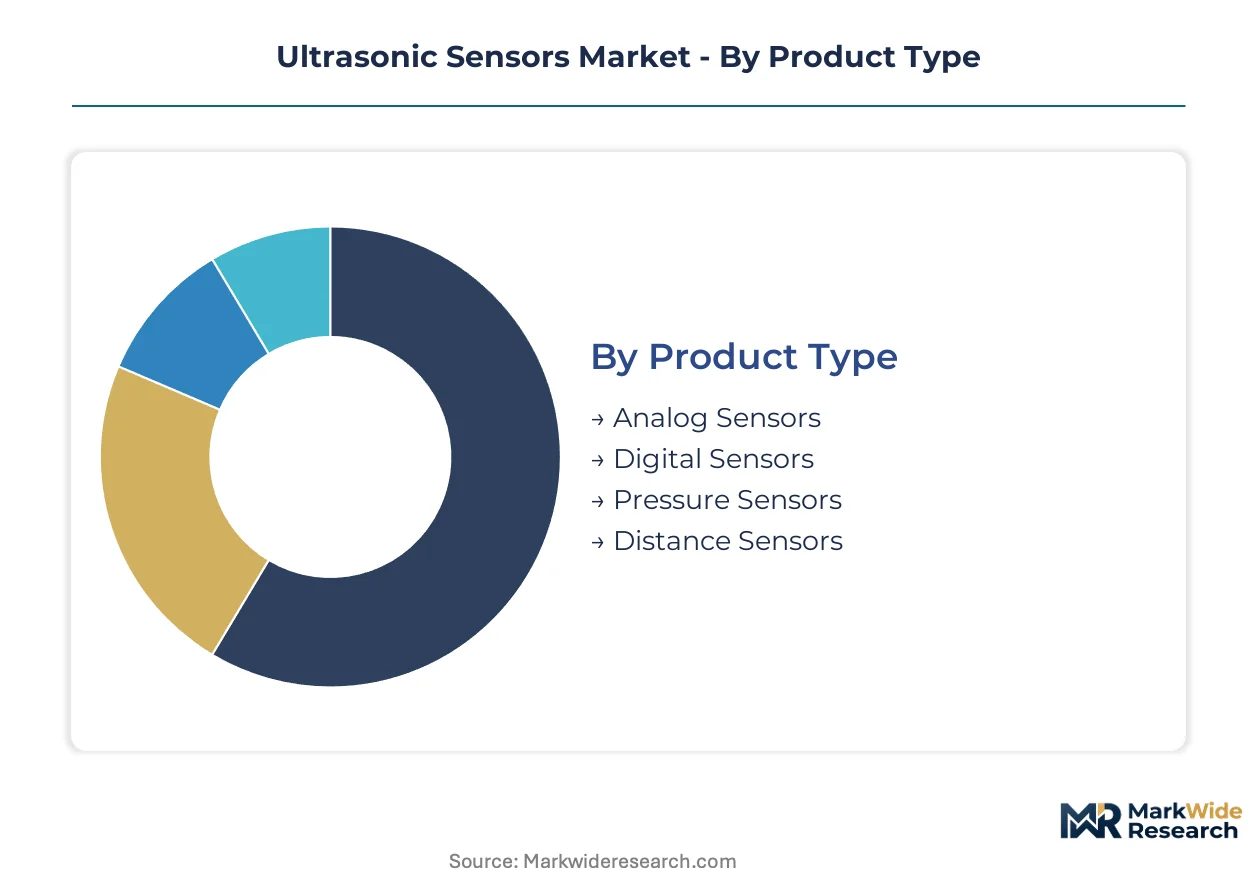
Ultrasonic sensor procurement patterns diverge sharply across product architectures and signal processing methods. Technical specifications in one segment rarely translate to adjacent categories, forcing vendors to maintain parallel development tracks.
Product Type:
Replacement cycles stretch from 5-7 years for analog units in legacy machinery to 2-3 years for digital variants in smart-factory retrofits. Distance sensors turn over fastest as automotive platforms refresh bumper electronics each model cycle.
- Distance Sensors:Time-of-flight modules measure object proximity through 40-400 kHz acoustic pulse emission and echo detection. Parking assistance mandates from Germany's KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism are embedding these arrays into vehicle bumpers as standard equipment, with sub-centimeter resolution now specified by Tier 1 suppliers.
- Digital Sensors:Integrated DSP architectures with IO-Link connectivity enable direct Ethernet-APL integration without analog signal conditioning. Shenzhen and Shanghai automation corridors are pulling these units for pallet detection in high-density warehousing where backward compatibility with legacy PLCs matters less than data throughput.
- Analog Sensors:4-20 mA output circuits dominate cost-sensitive machinery retrofits where PLC architectures predate digital fieldbus adoption.
- Pressure Sensors:Sealed transducer designs serve HVAC and refrigeration leak detection under EU F-Gas Regulation phasedown requirements.
Distance Sensors dominate installed base. Digital Sensors are where expansion concentrates.
Technology:
Cost tiers separate electromechanical designs from solid-state alternatives, with piezoelectric stacks commanding premium positioning due to material and sintering complexity.
- Piezoelectric:Lead zirconate titanate transducers convert electrical energy to mechanical vibration with high electromechanical coupling efficiency. REACH substance restrictions on lead content are forcing reformulation of transducer compositions, extending qualification timelines for industrial-grade units destined for EU water management and food processing installations.
- Capacitive:MEMS-fabricated diaphragm structures enable batch manufacturing at lower unit costs for consumer electronics proximity detection.
- Optical:Solid-state LiDAR modules are displacing ultrasonic arrays in premium autonomous vehicle perception stacks above Level 2 autonomy.
- Magnetic:Inductive sensing alternatives serve explosive atmosphere applications where acoustic emission poses ignition risks.
Piezoelectric anchors revenue contribution. Capacitive is climbing the fastest as smartphone and wearable integration scales.
End User:
Customer procurement sophistication ranges from automotive Tier 1 technical specifications to healthcare device OEMs prioritizing EMC compliance documentation.
- Automotive:ADAS mandate acceleration in Germany and Japan embeds ultrasonic arrays into parking assistance and blind-spot monitoring systems as standard equipment.
- Industrial Automation:Robot density targets in China's Pearl River and Yangtze River Delta regions pull demand for high-frequency distance sensors in collision avoidance and pallet detection.
- Healthcare:Diagnostic imaging and fluid level monitoring applications require FDA and CE marked units with extensive electromagnetic compatibility documentation.
- Consumer Electronics:Smartphone proximity detection and wearable gesture recognition drive volume at compressed margins.
Industrial Automation dominates installed base. Automotive is gaining share fastest as bumper electronics content rises.
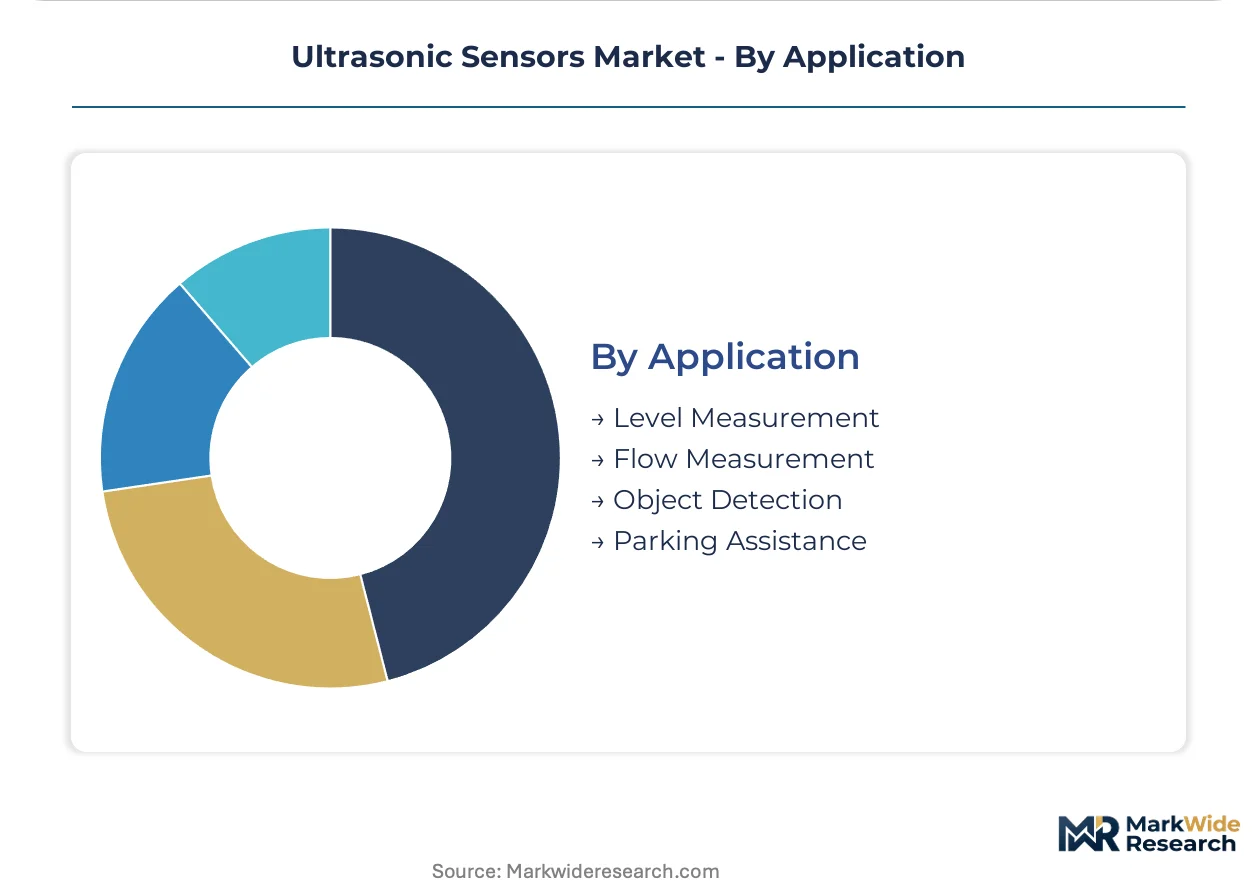
Application:
Functional requirements separate continuous measurement tasks from discrete presence detection, with flow applications demanding highest calibration precision.
- Flow Measurement:Transit-time and Doppler ultrasonic methods measure liquid velocity without pipe intrusion. Southeast Asian megacity water utilities facing non-revenue water reduction mandates are capturing share from mechanical meters, with after-sales calibration contracts unbundling from hardware sales in US Gulf Coast refinery deployments.
- Parking Assistance:Multi-transducer arrays in vehicle bumpers provide obstacle proximity alerts with audible and haptic feedback.
- Level Measurement:Tank and silo content monitoring serves chemical, pharmaceutical, and food processing operators with continuous uptime requirements.
- Object Detection:Presence sensing for conveyor systems and packaging machinery enables collision avoidance in high-speed material handling.
Object Detection dominates installed base. Flow Measurement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive Tier 1 suppliers and industrial automation integrators concentrate procurement decisions in manufacturing corridors where regulatory mandates and production density intersect. Buyer archetypes split between German and Japanese automotive engineering centers, Chinese smart-factory deployment zones, and US process industry hubs.
Germany
KBA parking assistance mandates and ADAS regulations embed ultrasonic arrays into vehicle bumpers as standard equipment. The EU F-Gas Regulation accelerates sealed transducer adoption for HVAC leak detection. Stuttgart and Munich engineering corridors host Tier 1 supplier technical specification centers driving sub-centimeter resolution requirements.
China
Industrial robot density targets in the Pearl River and Yangtze River Delta regions pull demand for high-frequency distance sensors. MIIT factory automation standards integrate ultrasonic devices into Industry 4.0 architectures. Shenzhen and Shanghai automation corridors prioritize pallet detection sensors with IO-Link connectivity over backward-compatible analog units.
Japan
METI promotes factory automation standards that embed ultrasonic sensors into smart-manufacturing architectures. Lead zirconate titanate sintering capacity concentrates among domestic material suppliers, exposing buyers to allocation risk. Nagoya and Osaka industrial clusters anchor automotive sensor production for domestic and export markets.
United States
EPA emissions monitoring mandates require continuous flow measurement uptime in Gulf Coast refineries. After-sales calibration contracts unbundle from hardware sales as chemical operators purchase performance guarantees. Texas and Louisiana process industry hubs drive service-level agreement models over capital equipment transactions.
India
PLI scheme production-linked incentives attract sensor assembly investments for domestic industrial automation supply. Central electricity authority standards shape utility digitization procurement for non-revenue water reduction. Gujarat and Tamil Nadu manufacturing corridors concentrate electronics component fabrication capacity.
Ultrasonic Sensors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. Direct sales forces sustain premium positioning in Asian manufacturing hubs while distribution partnerships penetrate cost-sensitive retrofit markets. Three archetypes dominate: integrated automation conglomerates with captive sensor divisions, piezoelectric material specialists with backward integration into transducer production, and software-defined measurement platform vendors. Competitive moves concentrate on M&A for sensor fusion capabilities and capacity expansion in lead-free ceramic sintering to satisfy REACH compliance timelines.
Among Japanese precision equipment manufacturers, Keyence Corporation and Omron Corporation exemplify the direct-sales archetype with premium positioning across factory automation deployments. German industrial sensor specialists including Pepperl+Fuchs and SICK AG anchor European intrinsically safe design standards. Honeywell International Inc. represents the diversified conglomerate model with upstream control over piezoelectric ceramic production. Murata Manufacturing Co. Ltd. occupies a position within the electronic component specialist tier serving consumer electronics proximity detection at compressed margins.
| Leading Market Players |
|---|
| Keyence Corporation |
| Pepperl+Fuchs |
| Honeywell International Inc. |
| SICK AG |
| Omron Corporation |
| Rockwell Automation |
| Balluff Inc. |
| Banner Engineering Corp. |
| Murata Manufacturing Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Shanghai-Nagoya container freight corridors transmit lead zirconate titanate ceramic cost volatility directly into transducer pricing tiers, with EU REACH compliance premiums widening spreads between certified and uncertified sensor assemblies.
Pricing Analysis
Cost-plus contracts with lead oxide price indexation dominate piezoelectric transducer procurement, binding sensor assemblers to Japanese and Chinese ceramic suppliers. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels separates KBA-compliant bumper arrays from analog retrofit units. Pricing pressure stems from solid-state LiDAR cost compression in premium ADAS stacks. Automotive Tier 1 suppliers exhibit lowest price sensitivity; machinery retrofitters in China's inland provinces show highest.
Supply Chain Analysis
Lead zirconate titanate powder sintering concentrates in Japan, China, and South Korea, with electromechanical coupling efficiency resting on proprietary dopant formulations. DSP chip sourcing draws from Taiwan semiconductor foundries; halogen-free solder alloys hinge on Malaysian smelter output. Single-source vulnerability in high-purity titanate precursors threatens allocation during semiconductor demand spikes. Distribution runs through direct sales forces for premium factory automation, authorized distributors for cost-sensitive retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the automotive production cycle, with ADAS mandate waves in Germany and Japan providing the current expansionary impulse.
For Market Incumbents: Entrench lead-free ceramic sintering capabilities ahead of REACH substance restriction deadlines. Secure captive piezoelectric material supply through backward integration or long-term offtake with Japanese suppliers. Defend against LiDAR substitution by embedding ultrasonic arrays into bumper electronics as standard rather than optional content. For New Entrants and Emerging Players: India's underpenetrated industrial automation corridors offer white-space expansion beneath incumbent pricing floors. Target water utility digitization in Southeast Asian megacities where mechanical meter replacement creates service-level agreement opportunities. Pursue IO-Link protocol certification as the fastest path to smart-factory qualification. For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown reshapes the acquisition landscape toward sealed transducer specialists with HVAC leak detection track records. Five-to-ten year viability favors platform vendors with software-defined measurement architectures over discrete hardware assemblers. Watch MEMS capacitive sensor cost curves as the inflection signal for consumer electronics proximity detection margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Ceramic Sintering Scale-Up | REACH compliance timelines force reformulation investments ahead of competitor qualification delays. |
| IO-Link Protocol Certification | Ethernet-APL convergence opens brownfield retrofit markets previously locked in analog infrastructures. |
| Direct Sales Force Expansion | Keyence's Asian manufacturing hub penetration demonstrates premium positioning through channel control. |
| After-Sales Service Unbundling | US Gulf Coast refineries now purchase flow measurement uptime guarantees rather than capital equipment. |
| Sensor Fusion Capability Acquisition | Multi-modal perception stacks in Level 2+ autonomy require acoustic-optical integration expertise. |
Methodological Framework
Desk research of trade flow databases, ceramic materials patents, and automotive platform specifications preceded structured interviews with Tier 1 supplier procurement managers, industrial automation plant engineers, water utility metering directors, and piezoelectric materials R&D leads. Secondary triangulation drew from EPA emissions filings, EU ECHA substance restriction updates, MIIT factory automation standards, and SEC 10-K disclosures from listed sensor manufacturers. Bottom-up segment sizing and top-down macro validation converged on volume and value estimates.
Assumptions held fixed include current regulatory enforcement intensity and no disruptive substitution below Level 3 autonomy, while automotive ADAS penetration rates and industrial robot density targets varied across sensitivity scenarios. The analytical framework modeled product type, technology architecture, end-user industry, and application function dimensions throughout the forecast period. CAGRs derived from segment-level growth rate blending, with automotive bumper electronics content and smart-city water meter replacement schedules as primary demand inputs.
Practitioners should monitor REACH substance restriction implementation pace and LiDAR cost compression curves for early signals of forecast revision. Cross-checking against IHS Markit vehicle production databases and MIIT industrial robot installation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
North America Water Detection Sensors Market