
 Automotive Image Sensors Market | 2026-2036
Automotive Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Image Sensors Market Analytics
Aftermarket sensor calibration revenue is tilting toward OEM-captive service networks as vehicle electronics architectures grow more proprietary. Sony Semiconductor Solutions Corporation leverages its stacked CMOS expertise to anchor premium ADAS camera supply contracts. Onsemi competes through its Hayabusa platform, while Samsung extends fabrication scale across its Pyeongtaek complex to serve tier-1 module integrators.
Automotive image sensors are solid-state photodetectors that convert optical signals into electrical outputs, typically fabricated on silicon wafers with pixel pitches below three micrometers for high-resolution surround-view applications. These devices enable machine vision for collision avoidance, lane-keeping, and occupant monitoring by delivering real-time image data to vehicle compute platforms. CMOS technology dominates production economics due to lower power draw and on-chip integration capacity, while 3D time-of-flight variants capture fastest-growing demand from cabin monitoring and autonomous driving stacks. Color sensors retain the largest volume pool across parking assistance and rear-view camera modules where cost sensitivity shapes procurement.
NHTSA mandates in the United States and Euro NCAP protocols in Europe are forcing rear-view and surround-view camera adoption across vehicle classes, directly expanding sensor unit requirements per platform. China's MIIT issues GB standards for intelligent connected vehicles that specify minimum image resolution and latency thresholds for homologation. Stakeholders must monitor how software-defined vehicle architectures redistribute value between discrete sensor suppliers and domain controller integrators.
Market Dynamics
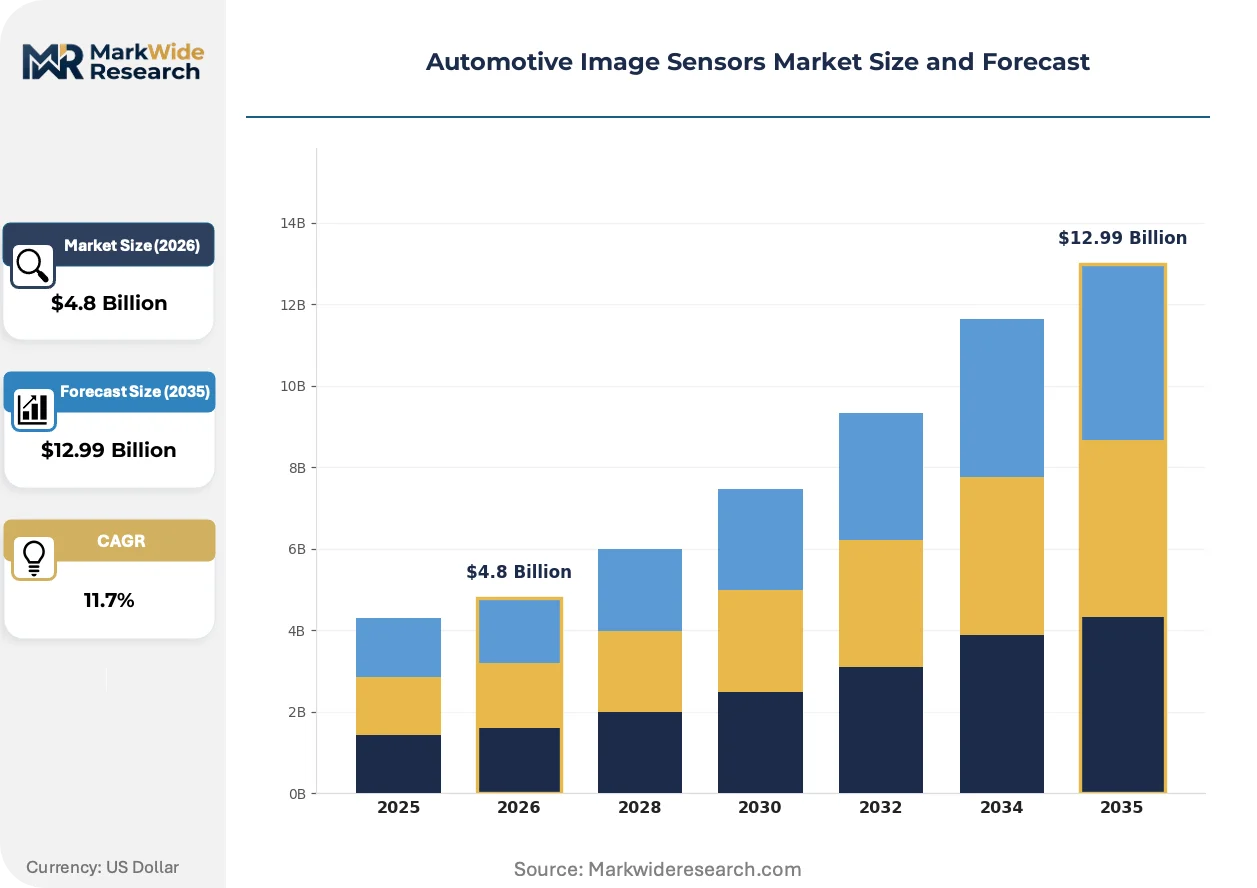
The Automotive Image Sensors Market is experiencing a fundamental restructuring as software-defined vehicle architectures dissolve traditional boundaries between discrete sensor suppliers and centralized compute platforms. This shift is redistributing value capture toward domain controller integrators while compressing margins for standalone component vendors.
Growth Catalysts
- Euro NCAP Safety Mandates:European protocols now require rear-view and surround-view cameras across all vehicle classes, directly expanding sensor unit requirements per platform and eliminating compliance opt-outs for entry-level segments.
- China's GB Standards:MIIT regulations for intelligent connected vehicles specify minimum image resolution and latency thresholds for homologation, forcing domestic and foreign OEMs to upgrade sensor specifications simultaneously.
- 3D Time-of-Flight Adoption:Cabin monitoring and autonomous driving stacks are driving fastest-growing demand for depth-sensing variants, creating new application layers beyond traditional exterior vision systems.
Market Restraints
- Silicon Wafer Supply Concentration:Advanced CMOS fabrication depends on concentrated 300mm wafer supply from East Asian foundry clusters, exposing sensor vendors to geopolitical disruption and capacity allocation conflicts.
- Proprietary Vehicle Electronics Architectures:OEM-captive service networks are capturing aftermarket calibration revenue as vehicle systems grow more closed, restricting independent repair channel participation.
- Color Sensor Commoditization:Parking assistance and rear-view camera modules face severe cost compression where color sensors dominate volume, limiting R&D recovery for suppliers focused on these segments.
Strategic Opportunities
- Underpenetrated Commercial Vehicle Segment:Heavy-duty trucking and logistics fleets in Germany and the United States remain below passenger vehicle ADAS penetration rates, presenting volume expansion potential as fleet operators face insurance-driven safety mandates.
- Sensor Fusion Convergence:Integration of image sensors with LiDAR and radar data streams in next-generation autonomous stacks creates demand for higher-bandwidth, lower-latency CMOS variants with specialized interface protocols.
- NHTSA Camera-Based Requirements:Pending US mandates for pedestrian automatic emergency braking will force front-facing camera deployment across light truck and SUV segments previously exempt from stringent car standards.
Industry Challenges
- Embedded Vision Software Talent Scarcity:The shortage of engineers capable of optimizing neural network inference on edge compute platforms limits sensor vendors' ability to deliver complete perception subsystems.
- Functional Safety Certification Burden:ISO 26262 ASIL-D qualification timelines for automotive image sensors now extend 18-24 months, compressing product refresh cycles and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Image Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome Sensors, Color Sensors, 3D Sensors, Infrared Sensors Technology: CMOS, CCD, Hyperfocal, Time-of-Flight Application: Advanced Driver Assistance Systems, Autonomous Driving, Collision Avoidance, Parking Assistance End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | STMicroelectronics, GalaxyCore, Sony Semiconductor Solutions Corporation, Canon, SK Hynix, Samsung, Onsemi, SmartSens Technology, OMNIVISION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Image Sensors Market Evolving Landscape
Stacked CMOS architectures are compressing the physical footprint and power envelope of automotive image sensors while multiplying on-chip processing capabilities. This technological trajectory is enabling new sensor placements and fusion topologies that were physically impossible with planar designs.
Pixel-level analog-to-digital conversion is collapsing the noise floor and dynamic range limitations that previously forced multi-sensor redundancy in high-contrast driving scenarios. Tier-1 module integrators are adopting these devices for single-camera surround-view replacements. The structural consequence is collapsing bill-of-materials counts for premium ADAS suites while raising performance expectations for mid-tier configurations.
REACH substance restrictions and RoHS recast directives in Europe are forcing reformulation of sensor packaging materials and solder compositions. German KBA type-approval processes now incorporate extended chemical compliance documentation. Suppliers serving Volkswagen Group and BMW procurement channels have reconfigured supply chains to eliminate restricted substances ahead of enforcement deadlines.
Fleet operators in the United States are consolidating sensor procurement through telematics platform providers rather than direct tier-1 relationships. Samsara and Geotab are bundling camera hardware with subscription-based video intelligence services. This channel compression is most visible in long-haul trucking where owner-operators previously purchased aftermarket safety equipment through independent distributors.
Automotive Image Sensors Market Segmentation
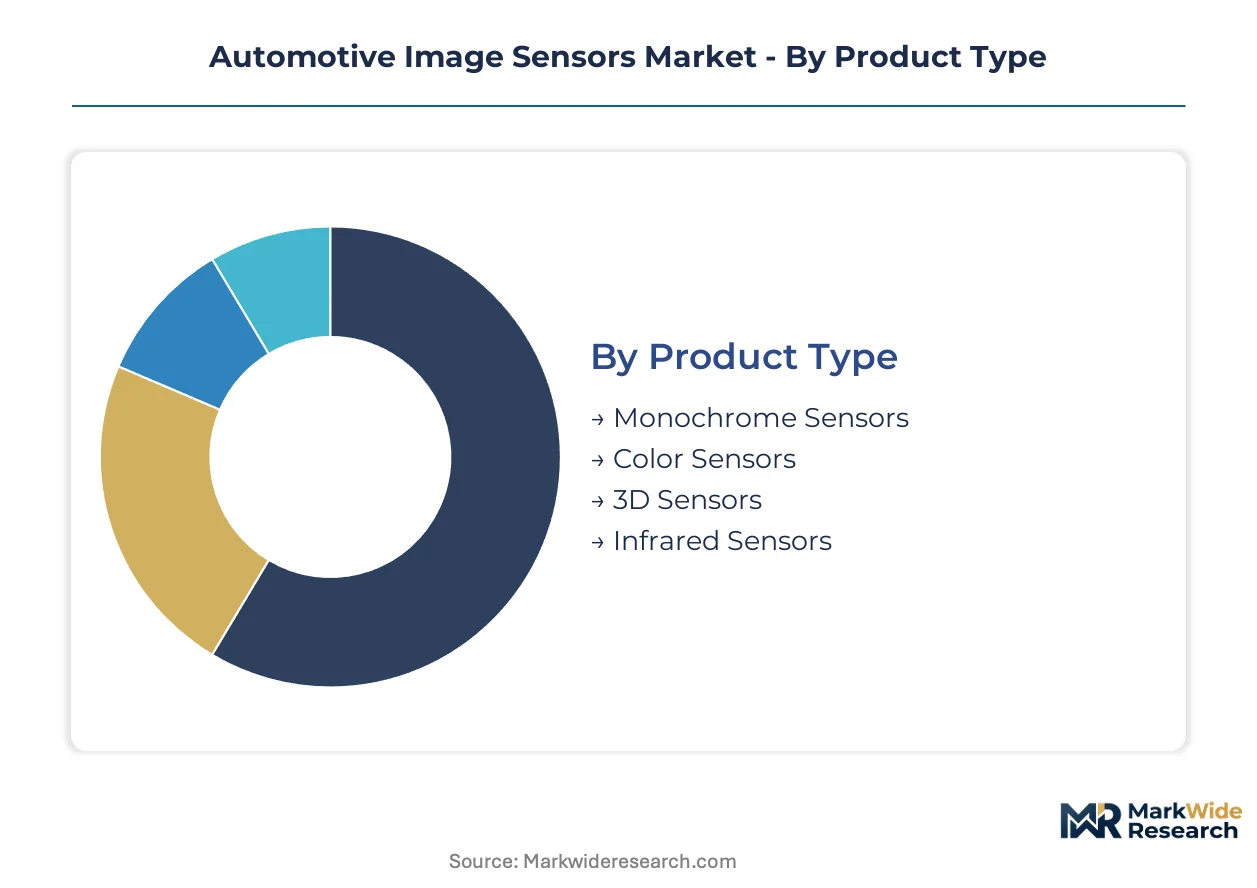
Automotive image sensors fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices lock in performance ceilings, while application and end-user channels dictate volume concentration and pricing power.
Product Type:
The use-case spectrum spans exterior vision systems prioritizing resolution and dynamic range against cabin-facing deployments demanding depth perception and privacy-compliant sensing.
- Monochrome Sensors:These devices capture luminance data without color filtration, delivering superior low-light sensitivity and reduced data throughput for surround-view and night-vision applications. German premium OEMs specify monochrome front-facing cameras for pedestrian automatic emergency braking systems where light-starved performance determines functional safety margins.
- Color Sensors:RGB photodiode arrays dominate rear-view and parking assistance modules where human-interpretable video feeds satisfy regulatory display requirements. Cost compression in this segment limits supplier differentiation, with procurement concentrating among Chinese and South Korean module integrators serving high-volume compact vehicle platforms.
- 3D Sensors:Depth-sensing variants combining structured light or stereoscopic principles enable cabin occupancy detection and gesture control interfaces. MIIT GB standards for intelligent connected vehicles now mandate minimum depth accuracy thresholds for driver monitoring systems.
- Infrared Sensors:NIR-enhanced devices extend detection range beyond visible spectrum limitations for nighttime pedestrian classification and thermal signature fusion. NHTSA research programs are evaluating infrared augmentation for vulnerable road user protection in reduced-visibility conditions.
Established volume favors Color Sensors; emerging adoption favors 3D Sensors.
Technology:
Cost tier stratification separates mature planar architectures from stacked-CMOS premium configurations commanding three-to-fourx unit pricing.
- CMOS:Complementary metal-oxide-semiconductor technology anchors over ninety percent of automotive volume through lower power draw and on-chip integration capacity. Sony Semiconductor Solutions and Onsemi compete through proprietary pixel architectures that compress noise floors while expanding dynamic range for high-contrast driving scenarios.
- CCD:Charge-coupled device sensors retain niche deployment in legacy surround-view systems where OEMs resist platform redesign investments. Japanese tier-1 suppliers maintain limited production lines for Toyota and Honda minivan programs with extended model cycles.
- Hyperfocal:Extended depth-of-field variants eliminate mechanical focus mechanisms for sealed-camera durability in wheel-well and underbody placements. German KBA type-approval processes now recognize hyperfocal designs for commercial vehicle blind-spot monitoring where vibration tolerance exceeds passenger vehicle specifications.
- Time-of-Flight:Direct depth measurement through photon timing enables compact cabin monitoring without multi-camera triangulation. This technology is expanding most quickly in Chinese electric vehicle programs where interior sensing supports both safety mandates and subscription-based feature activation.
Volume concentrates in CMOS; margin expansion concentrates in Time-of-Flight.
Application:
Customer type divergence separates regulatory-mandated exterior safety systems from discretionary autonomous driving investments subject to software readiness timelines.
- Advanced Driver Assistance Systems:Lane-keeping, adaptive cruise control, and traffic sign recognition depend on front-facing camera arrays with ASIL-B minimum qualification. Euro NCAP protocol updates are forcing multi-camera standardization across vehicle classes previously equipped with single-sensor configurations.
- Autonomous Driving:Level 3+ conditional automation requires redundant image sensing with diverse failure modes complementing LiDAR and radar coverage. Waymo and Cruise development programs in California and Arizona are specifying eight-plus camera architectures with 360-degree overlap zones.
- Collision Avoidance:Automatic emergency braking systems prioritize low-latency object detection over resolution density. NHTSA pending mandates for pedestrian AEB are accelerating front-camera deployment across light truck segments.
- Parking Assistance:Ultrasonic-fused camera systems for automated maneuvering represent the most cost-sensitive application tier. Chinese OEMs are driving specification inflation from standard-definition to high-definition surround-view as consumer expectations shift.
Mandate-driven deployment favors Collision Avoidance; technology-push investment favors Autonomous Driving.
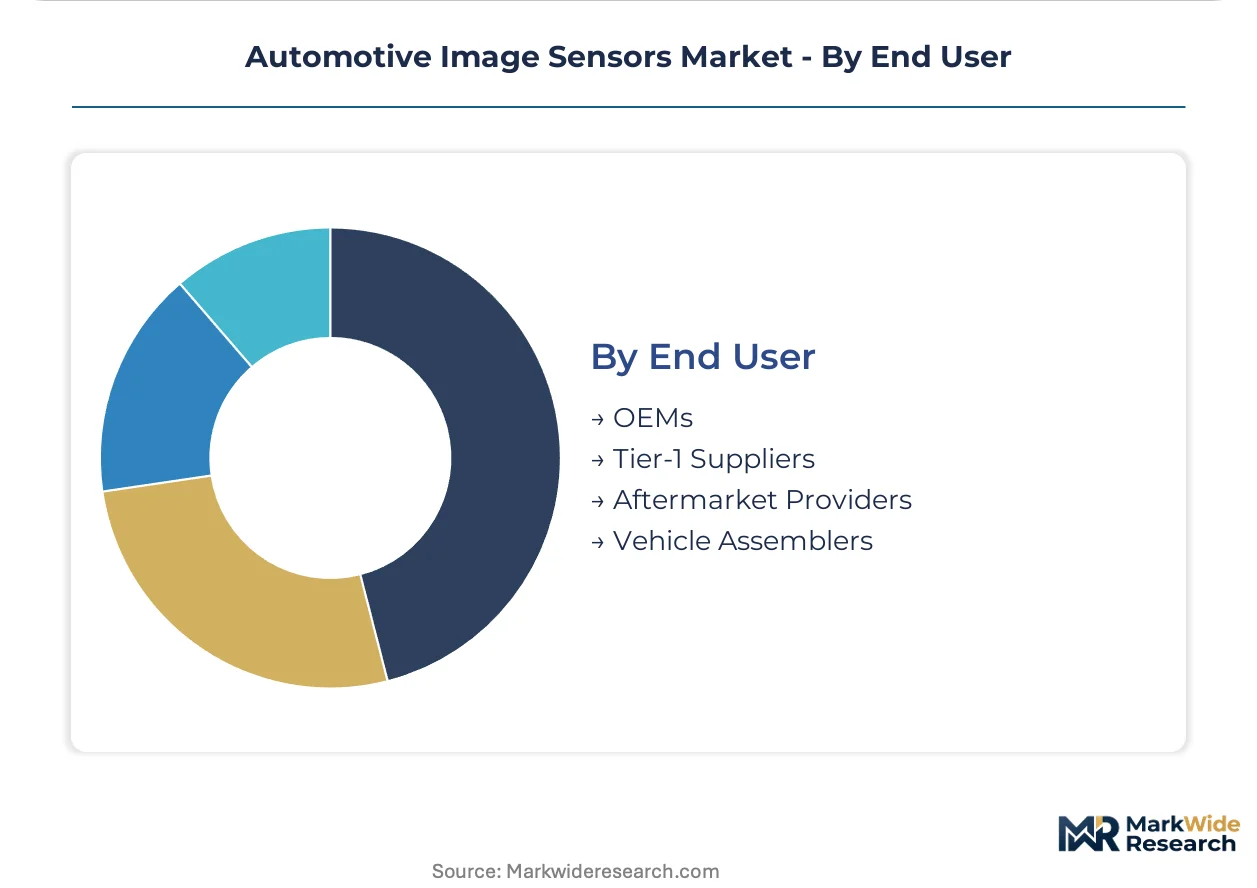
End User:
Supply concentration patterns differentiate captive OEM sensor development from open tier-1 module procurement and fragmented aftermarket calibration services.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz maintain direct sensor specification authority for premium ADAS suites with proprietary fusion algorithms. These manufacturers are internalizing software-defined vehicle architectures that compress tier-1 integration value capture.
- Tier-1 Suppliers:Bosch, Continental, and Magna aggregate sensor procurement across multiple OEM programs to achieve fabrication scale. Their module integration expertise retains pricing power in mid-tier vehicle segments where OEMs lack vertical integration economics.
- Aftermarket Providers:Independent calibration services face margin compression as OEM-captive diagnostic tools restrict access to sensor alignment protocols. Samsara and Geotab are consolidating fleet procurement through telematics-platform bundling.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-integrated camera modules to compress development timelines. Foxconn and Magna Steyr production lines for Fisker and Canoo exemplify this procurement pattern.
Procurement authority concentrates in OEMs; volume scaling concentrates in Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys automotive image sensors at the highest per-vehicle density for cabin monitoring and autonomous driving stacks, while Germany concentrates on premium ADAS front-camera specifications and the United States leads fleet telematics integration.
China
Domestic electric vehicle brands specify eight-plus camera architectures for Level 2+ automation, driving sensor volume at rates exceeding passenger vehicle production growth. MIIT GB standards for intelligent connected vehicles mandate minimum depth accuracy for driver monitoring systems. The Yangtze River Delta cluster around Shanghai hosts tier-1 module integrators supplying BYD, NIO, and Xpeng with time-of-flight variants for interior sensing.
Germany
Premium OEM procurement concentrates on monochrome front-facing cameras for pedestrian automatic emergency braking with ASIL-D functional safety margins. KBA type-approval processes incorporate extended REACH substance compliance documentation for sensor packaging. Bavaria's automotive electronics corridor anchors Continental and Bosch module development for Volkswagen Group and BMW ADAS suites.
United States
Light truck and SUV segments face pending NHTSA mandates for front-facing camera deployment in pedestrian automatic emergency braking systems. Fleet operators consolidate procurement through Samsara and Geotab telematics platforms bundling video intelligence subscriptions. Michigan's automotive engineering base supports tier-1 development centers serving Detroit Three captive sensor specifications.
South Korea
Hyundai Motor Group and Kia specify stacked CMOS architectures for surround-view systems across mass-market vehicle classes. The country's national automotive regulator enforces KC certification alignment with UN ECE R79 for camera-based driver assistance. Samsung's Pyeongtaek fabrication complex supplies domestic tier-1 integrators with high-volume CMOS wafer output.
Japan
Toyota and Honda maintain extended model cycles for legacy minivan surround-view systems using established CCD sensor configurations. METI coordinates cross-industry standards for autonomous vehicle sensor interoperability through the SIP automated driving project. Nagoya's Chubu manufacturing belt hosts specialized production lines serving Japanese OEM captive specifications.
Automotive Image Sensors Market Competitive Landscape
Capability concentration sits with stacked CMOS specialists commanding premium ADAS supply contracts; scale advantage sits with diversified semiconductor fabricators serving high-volume rear-view and parking assistance modules. The market structures around three tiers: premium sensor developers, high-volume CMOS suppliers, and emerging Chinese specialists. Consolidation pressures favor backward integration into wafer fabrication and strategic partnerships with domain controller integrators.
Among Asia-Pacific-based fabricators, Sony Semiconductor Solutions Corporation, Samsung, and Onsemi occupy positions across the capability-scale spectrum. Sony exemplifies the premium-tier archetype through stacked CMOS expertise anchoring high-resolution ADAS contracts. Samsung represents scale-driven fabrication capacity serving tier-1 module integrators from its Pyeongtaek complex. Onsemi sits within the diversified semiconductor tier competing through proprietary pixel architectures.
| Leading Market Players |
|---|
| STMicroelectronics |
| GalaxyCore |
| Sony Semiconductor Solutions Corporation |
| Canon |
| SK Hynix |
| Samsung |
| Onsemi |
| SmartSens Technology |
| OMNIVISION |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margins for high-volume color sensor shipments while amplifying price differentiation between stacked-CMOS premium tiers and commoditized rear-view modules. Supply concentration in East Asian foundry clusters feeds this bifurcation, as OEM procurement power concentrates against tier-1 integrators serving cost-sensitive parking assistance applications.
Pricing Analysis
Long-term offtake contracts dominate premium ADAS sensor procurement, with Volkswagen Group and BMW locking in stacked-CMOS supply through multi-year agreements that insulate Sony Semiconductor Solutions from spot-market volatility. Price differentiation hinges on ASIL-D functional safety certification and pixel architecture performance, with monochrome front-facing variants commanding substantial premiums over color rear-view alternatives. Cost compression in parking assistance modules is intensifying because Chinese OEMs are driving specification inflation from standard-definition to high-definition surround-view without corresponding price tolerance. Fleet operators bundling through Samsara and Geotab telematics platforms exhibit the highest price sensitivity, while German premium OEMs pursuing pedestrian automatic emergency braking systems show the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for automotive image sensor vendors, with module integrators reassessing Yangtze River Delta dependency for North American-bound production. Advanced CMOS fabrication draws from concentrated 300mm wafer supply in Taiwan, South Korea, and Japan, with silicon substrate and specialized photolithography equipment serving as critical input dependencies. Single-source vulnerability for extreme-ultraviolet lithography systems creates chokepoint exposure that could disrupt qualification timelines for next-generation pixel architectures. Distribution runs through tier-1 module integrators including Bosch, Continental, and Magna, which aggregate sensor procurement across multiple OEM programs to achieve fabrication scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures threaten to displace discrete sensor suppliers as domain controllers capture perception stack value, forcing incumbents to defend component-level pricing power against centralized compute integration.
For Market Incumbents: Entrench ASIL-D certification capabilities as a defensive moat against emerging Chinese specialists, while securing backward integration into 300mm wafer supply through strategic foundry partnerships in Taiwan and South Korea. Sony Semiconductor Solutions and Onsemi must prioritize embedded vision software talent acquisition to deliver complete perception subsystems rather than commoditized photodetectors.
For New Entrants and Emerging Players: Heavy-duty trucking and logistics fleets in Germany and the United States represent the most penetrable entry point, with insurance-driven safety mandates forcing ADAS adoption rates below passenger vehicle thresholds. Time-of-flight cabin monitoring for Chinese electric vehicle programs offers a second white-space target, with MIIT GB standards mandating minimum depth accuracy that creates specification barriers for established color sensor suppliers. Go-to-market execution should emphasize telematics-platform bundling partnerships with Samsara and Geotab rather than direct tier-1 competition.
For Investors and Strategic Acquirers: Pending NHTSA mandates for pedestrian automatic emergency braking reshape the acquisition landscape by accelerating front-facing camera deployment across light truck and SUV segments previously exempt from stringent car standards. Long-term viability favors stacked-CMOS specialists with established OEM supply relationships and ISO 26262 qualification track records, while commodity color sensor vendors face margin compression from Chinese module integrators. The signal to watch is fleet operator procurement consolidation through subscription-based video intelligence services, which compresses independent aftermarket channel economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces sensor variant complexity for OEMs integrating ADAS across multiple vehicle classes. |
| Backward Integration into Wafer Supply | Secures fabrication capacity for tier-1 module integrators facing 300mm wafer allocation constraints. |
| Software-Defined Vehicle Investment | Shifts value capture from discrete sensors to domain controller integrators with perception stack ownership. |
| Geographic Manufacturing Footprint | Positions tier-1 suppliers to serve Detroit Three requirements under pending NHTSA camera mandates. |
| Charging Infrastructure Partnership | Creates bundled service offerings for Chinese EV brands deploying eight-plus camera architectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation incorporated vehicle production databases, IHS Markit registration data, SEC filings from diversified semiconductor vendors, and MIIT GB standard documentation. Bottom-up triangulation across sensor unit shipments and top-down reconciliation against vehicle production volumes anchored the analysis.
Calibration against historical ADAS adoption curves and regulatory mandate implementation timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application tier, and end-user channel, with vehicle class and regional production cluster serving as additional automotive-specific stratifiers. CAGRs were derived from regression analysis of content-per-vehicle trends and fleet replacement cycles, with Euro NCAP protocol updates and NHTSA rulemaking schedules treated as demand-pull inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Speech Intelligibility Devices Market