
 US Sexual and Reproductive Health Clinics Market | 2026-2036
US Sexual and Reproductive Health Clinics Market Size, Share, and Industry Trends Forecast 2026-2036
US Sexual and Reproductive Health Clinics Market Insights
Medicaid expansion under the Affordable Care Act is consolidating access patterns for reproductive services across state lines. Planned Parenthood leverages its national clinic infrastructure to sustain high-volume service delivery in underserved counties. Kindbody differentiates through employer-sponsored fertility benefits and direct-to-patient digital scheduling. CCRM specializes in advanced reproductive technology laboratories with in-house embryology capabilities.
US Sexual and Reproductive Health Clinics constitute outpatient medical facilities delivering gynecological care, contraception management, sexually transmitted infection screening, fertility assessment, and prenatal monitoring through credentialed clinical staff and diagnostic equipment. These clinics operate under state licensure requirements, federal privacy protocols, and accreditation standards that govern laboratory quality, medication dispensing, and surgical procedure authorization. Service type segmentation shows family planning and STI testing occupying mature, high-frequency visit categories while prenatal care and counseling generate extended patient relationships with stronger reimbursement profiles. Care setting segmentation reveals outpatient clinics and community health centers anchoring volume due to Medicaid acceptance, whereas private practices and mobile units capture self-pay and employer-funded demand with greater pricing flexibility.
FDA oversight of contraceptive devices and fertility pharmaceuticals shapes product availability and clinic formulary decisions, while HIPAA mandates govern patient data management across telehealth platforms and electronic health records. State-level Title X funding allocations and abortion access legislation create divergent operating environments that clinics must navigate for service line planning and capital deployment. Stakeholders should monitor state Medicaid waiver applications and FDA guidance on over-the-counter contraceptive switches to anticipate reimbursement and competitive shifts.
Market Dynamics
Medicaid reimbursement rate compression and state-level Title X funding volatility are forcing clinic operators to restructure service line economics and site selection criteria. The shift toward value-based contracting for reproductive health services is accelerating consolidation among independent providers seeking scale for payer negotiations.
Growth Catalysts
- HIPAA-compliant telehealth expansion:Remote contraceptive counseling and STI screening protocols approved by state medical boards are extending clinic reach into rural counties with provider shortages.
- Employer-sponsored fertility benefits:Large self-insured employers in Texas and California are adding IVF and egg freezing to health plans, directing patient volume to affiliated clinic networks.
- FDA over-the-counter contraceptive switches:Regulatory pathways for non-prescription hormonal methods are expanding pharmacist-delivered care models and clinic-pharmacy partnerships.
Market Restraints
- Reimbursement rate stagnation:Medicaid fee schedules in non-expansion states fail to cover operational costs for IUD insertion and prenatal monitoring services.
- Concentrated pharmaceutical supply:Three manufacturers control 80% of long-acting reversible contraceptive device production, creating formulary vulnerability for clinics.
- State legislative fragmentation:Divergent abortion access laws across Texas, California, and New York complicate multi-state network planning and capital allocation.
Strategic Opportunities
- Mobile clinic deployment:Federally qualified health centers are adding reproductive health-equipped vehicles to serve agricultural worker communities in California's Central Valley.
- Digital fertility tracking integration:Partnerships between clinics and FDA-cleared wearable device platforms enable remote cycle monitoring and timed intervention scheduling.
- Medicaid managed care carve-outs:State contracts for family planning-only coverage in New York are creating dedicated reimbursement streams for specialized clinic operators.
Industry Challenges
- Certified nurse-midwife recruitment:Pipeline constraints for advanced practice clinicians trained in IUD placement and colposcopy are extending appointment wait times.
- Laboratory accreditation timelines:CAP and CLIA certification processes for in-house embryology labs delay fertility service line launches by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sexual and Reproductive Health Clinics Market |
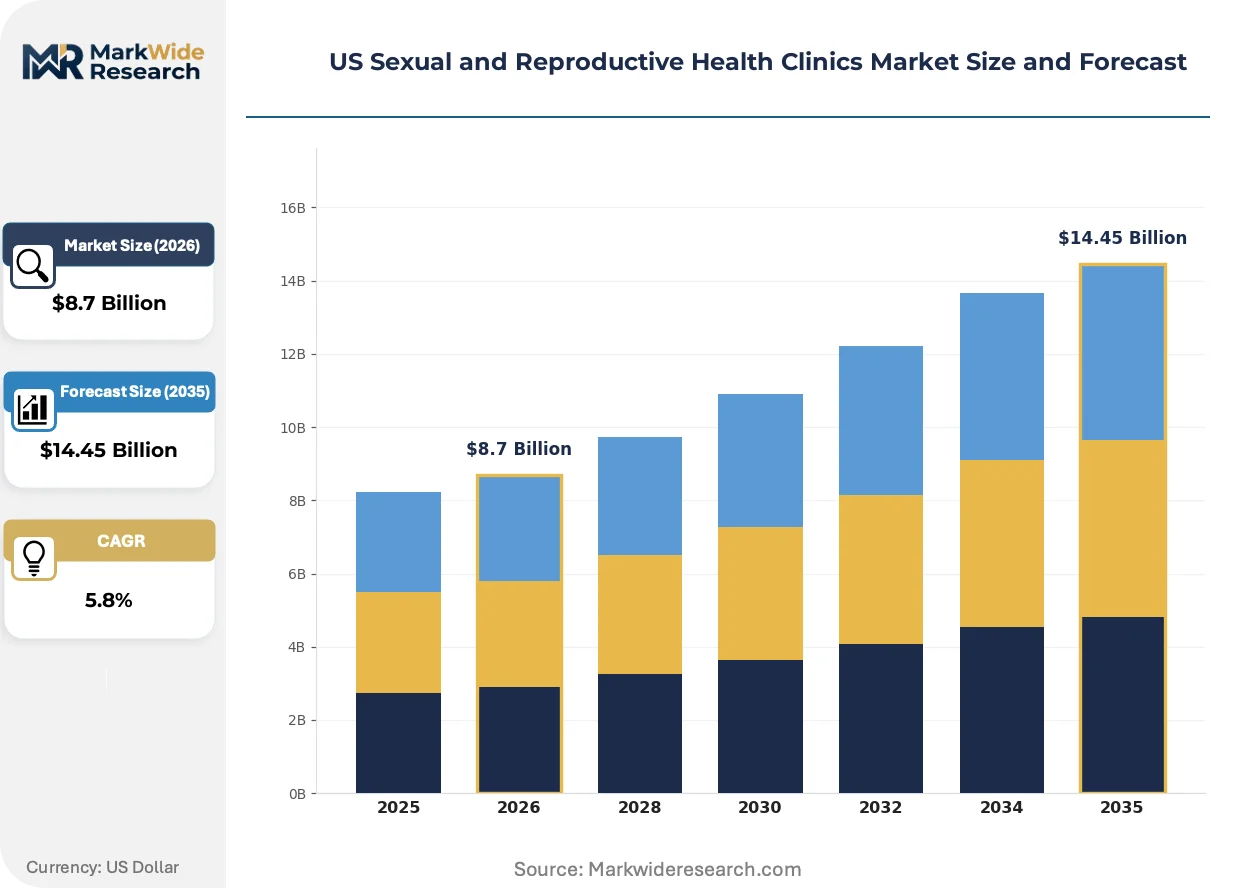
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Family Planning, STI Testing, Prenatal Care, Counseling Treatment Modality: Hormonal Methods, Barrier Methods, Surgical Procedures, Natural Family Planning Patient Demographics: Adolescents, Adults, Couples, Single Parents Care Setting: Outpatient Clinics, Community Health Centers, Mobile Units, Private Practices |
| Companies Covered | IntegraMed America, US Fertility, CCRM, Boston IVF, Reproductive Medicine Associates, Kindbody, Planned Parenthood, Shady Grove Fertility, IVF Centers of Excellence, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sexual and Reproductive Health Clinics Market Trends and Innovations
Digital health platforms are restructuring how patients access reproductive services, compressing the traditional referral pathway and enabling direct scheduling with specialists. This shift is forcing established clinic networks to reconfigure front-desk operations and patient intake protocols.
Telehealth platforms with integrated prescription fulfillment are consolidating routine contraceptive management and STI treatment into single-visit digital workflows. Federally qualified health centers in Medicaid expansion states are adopting these systems fastest, using them to absorb primary care overflow. The technology is consolidating low-acuity visits away from physical sites, freeing exam room capacity for procedural services.
FDA guidance on software-as-a-medical-device classification for fertility prediction algorithms is reshaping digital platform liability frameworks. The agency's draft recommendations require clinical validation studies for algorithm-driven ovulation tracking tools used in treatment planning. Fertility clinic networks with in-house software development are restructuring quality management systems to accommodate premarket notification pathways.
Self-pay patients are bypassing traditional referral channels to book directly with reproductive endocrinologists through employer benefit navigation platforms. This behavior is disrupting the historical gatekeeper role of obstetrician-gynecologists in fertility care access. The pattern is most visible in Texas metropolitan corridors where employer fertility benefits have achieved high penetration among technology sector workforces.
US Sexual and Reproductive Health Clinics Market Segmentation
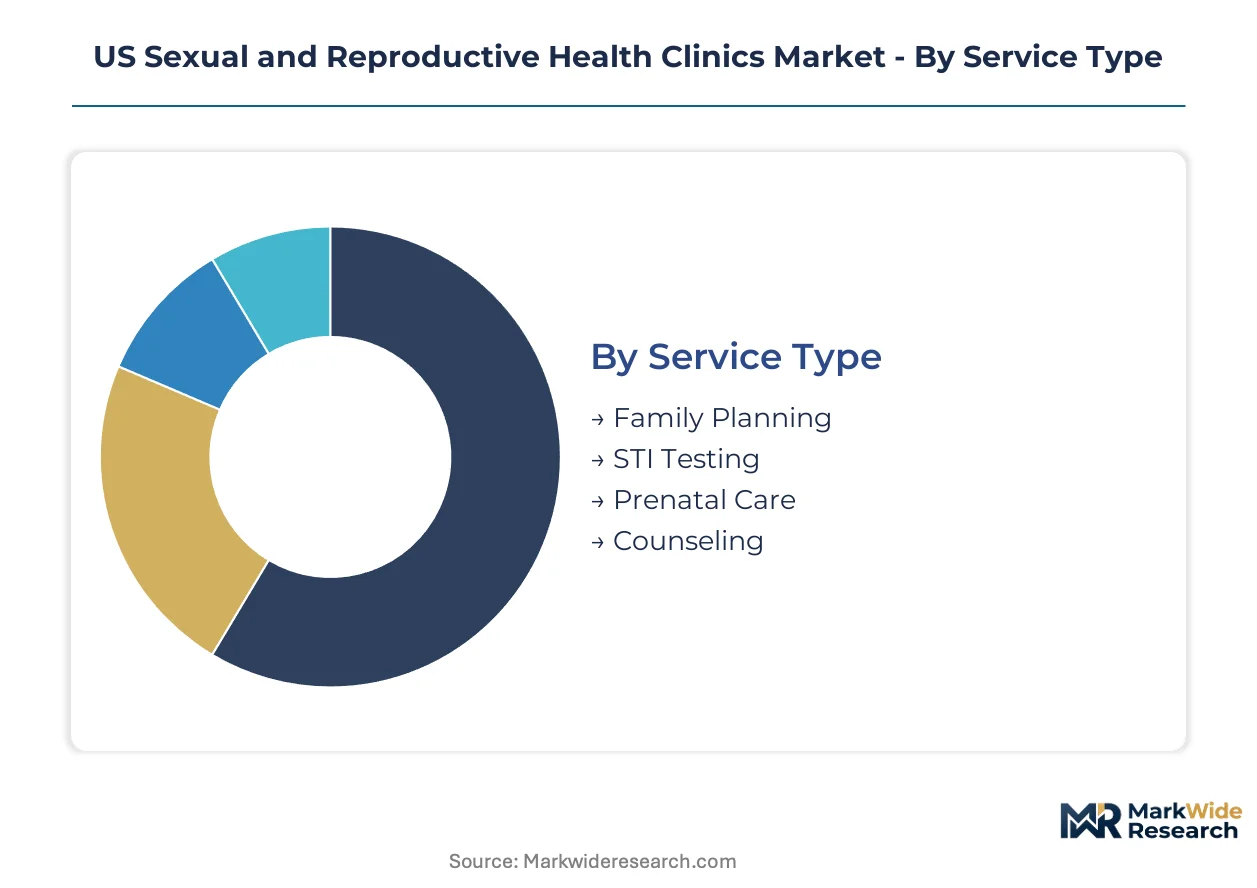
Service line economics in US reproductive health clinics vary sharply by capital requirements and reimbursement profiles. Segment-specific investment needs dictate site selection, equipment procurement, and staffing models across network operators.
Service Type:
Capital intensity peaks with prenatal monitoring infrastructure requiring ultrasound suites and laboratory partnerships, while counseling services demand minimal fixed assets beyond private consultation rooms.
- Family Planning:Contraceptive counseling and device provision dominate visit volume across Medicaid-served populations. Texas and California health centers process the highest caseloads where Title X funding streams remain intact.
- STI Testing:Rapid diagnostic platforms and CLIA-waived point-of-care systems enable same-visit treatment protocols. Demand concentrates in urban corridors with young adult density and mobile outreach capacity.
- Prenatal Care:Ultrasound imaging suites and fetal monitoring equipment require substantial upfront capital. Extended patient relationships generate stronger per-episode reimbursement under Medicaid managed care carve-outs.
- Counseling:Behavioral health integration for postpartum depression and fertility stress management operates with lower equipment thresholds. Licensed clinical social worker staffing scales faster than procedural service lines.
Family planning absorbs the bulk of installed capacity; prenatal care is expanding most quickly.
Treatment Modality:
Margin structures diverge between pharmaceutical-dependent methods and procedure-based interventions, with surgical services commanding premium reimbursement despite higher malpractice exposure.
- Hormonal Methods:Prescription contraceptives and long-acting reversible devices generate recurring pharmacy revenue. FDA over-the-counter switches for oral contraceptives are compressing clinic visit dependency for routine refills.
- Barrier Methods:Condom distribution and diaphragm fitting require minimal clinical oversight. Community health centers leverage these services for rapid patient acquisition with low operational overhead.
- Surgical Procedures:Tubal ligation and vasectomy suites demand operating room infrastructure and anesthesia protocols. Hospital-affiliated networks in New York capture this volume through integrated referral pathways.
- Natural Family Planning:Fertility awareness education and cycle tracking support appeal to self-pay patients seeking non-pharmaceutical alternatives. Digital platform partnerships extend reach without proportional staff expansion.
Hormonal methods anchor current revenue mix; surgical procedures are climbing the fastest as employer fertility benefits mature.
Patient Demographics:
Acquisition costs and service intensity vary by life stage, with adolescent populations requiring specialized consent protocols and adult couples driving higher per-episode spending.
- Adolescents:Minor consent laws and school-based clinic partnerships shape service delivery models. California's Central Valley agricultural communities rely on mobile units to reach this population.
- Adults:Fertility preservation and contraceptive management dominate service requests. Employer-sponsored benefits in Texas metropolitan corridors direct substantial volume to affiliated networks.
- Couples:Joint fertility assessments and preconception counseling generate extended care episodes. IVF referral coordination commands higher case management fees than individual services.
- Single Parents:Postpartum support and contraceptive access prioritize scheduling flexibility. Evening and weekend clinic hours capture this demand in Medicaid expansion states.
Adults represent the largest addressable population; couples are gaining share fastest as fertility benefit penetration deepens.
Care Setting:
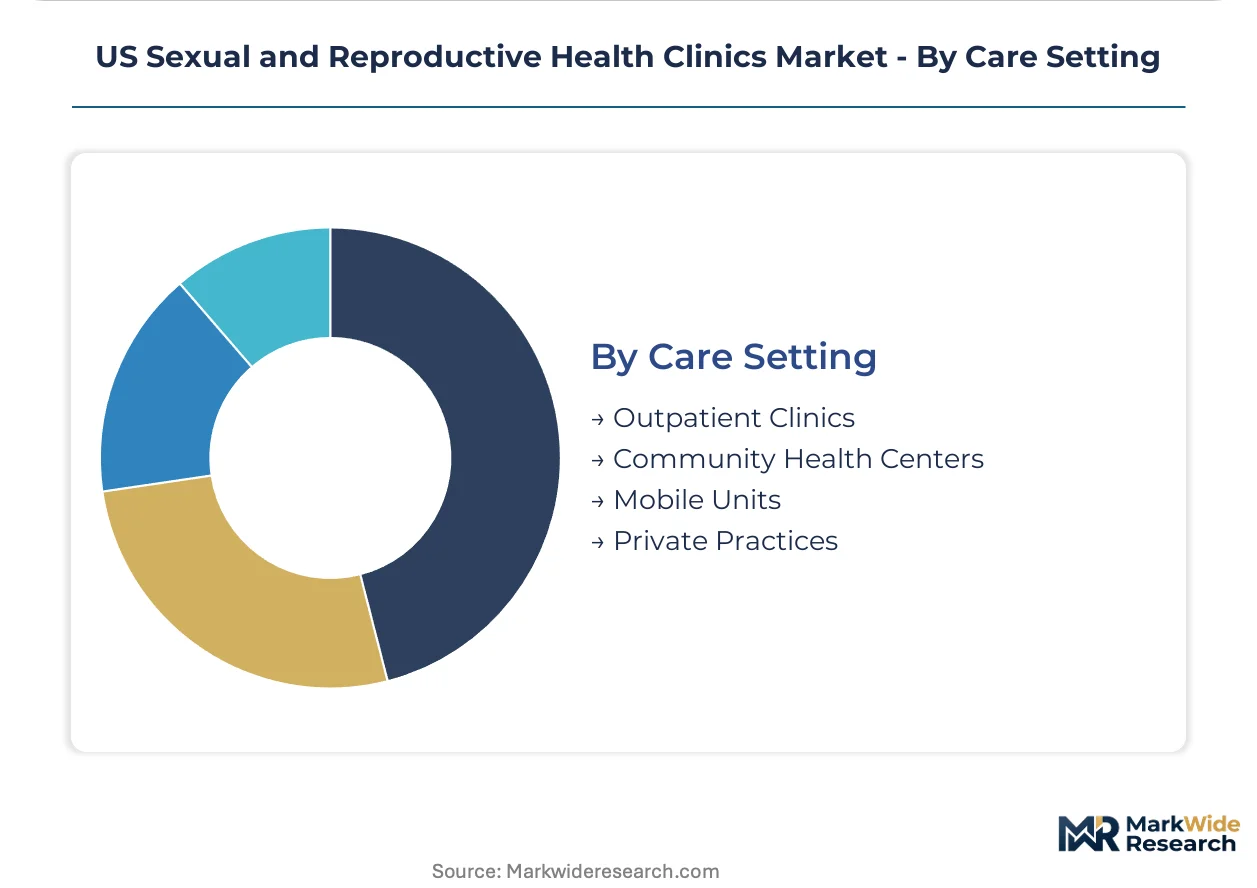
Real estate and regulatory compliance burdens separate institutional operators from independent practices, with mobile deployment offering capital-efficient geographic expansion.
- Outpatient Clinics:Federally qualified health centers anchor Medicaid-served volume with comprehensive service menus. HIPAA-compliant telehealth integration extends capacity without proportional facility expansion.
- Community Health Centers:Sliding fee scales and 340B pharmacy programs sustain operations in underserved counties. Title X funding volatility forces continuous service line restructuring.
- Mobile Units:Customized vehicles with exam capabilities reach agricultural worker communities and rural counties. California operators lead deployment scale for seasonal labor populations.
- Private Practices:Self-pay and employer-funded demand supports pricing flexibility absent from Medicaid-dependent settings. Reproductive endocrinology subspecialists concentrate in high-income metropolitan markets.
Outpatient clinics hold the majority of fixed infrastructure; mobile units are scaling most rapidly for geographic coverage extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas metropolitan corridors anchor US reproductive health clinic activity, with Houston and Dallas-Fort Worth hosting dense concentrations of employer-sponsored fertility benefit networks and Medicaid managed care contracts.
Texas
Employer fertility benefits and Title X funding volatility drive divergent clinic economics across metropolitan and rural counties. State-level abortion access restrictions reshape service line planning for multi-site operators. Houston's Texas Medical Center corridor hosts hospital-affiliated reproductive endocrinology networks serving self-pay patients with advanced IVF capabilities.
California
Medicaid expansion and agricultural worker mobile health programs sustain high-volume family planning delivery. State family planning funding supplements federal Title X allocations in underserved Central Valley counties. Los Angeles and San Francisco Bay Area fertility clinics capture employer benefit volume from technology sector workforces with concentrated self-insured plan penetration.
New York
Medicaid managed care carve-outs for family planning-only coverage create dedicated reimbursement streams for specialized operators. State-level privacy protections exceed federal HIPAA baselines, shaping data management infrastructure investments. New York City metropolitan clinics anchor regional networks with integrated prenatal and behavioral health service lines.
Florida
Retiree migration and seasonal population fluctuations create variable demand patterns for contraceptive and STI services. State Medicaid waiver applications for family planning expansion remain pending, constraining clinic network planning. Miami-Dade and Broward County health departments operate high-volume public clinic infrastructure with 340B pharmacy program support.
Illinois
Chicago metropolitan fertility clinics serve regional referral networks extending into neighboring non-expansion states. State-level contraceptive equity legislation mandates insurance coverage for all FDA-approved methods, expanding clinic formulary flexibility. Cook County health system operates federally qualified health center networks with integrated reproductive health capacity in underserved south and west side neighborhoods.
US Sexual and Reproductive Health Clinics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reimbursement sophistication and employer benefit integration. Hospital-affiliated networks and independent fertility specialists occupy distinct tiers with divergent capital requirements and payer contracting leverage. Three strategic archetypes dominate: integrated health system extensions, independent multi-site specialists, and digital-native direct-to-patient platforms. Consolidation through strategic partnerships and service line diversification into telehealth and mobile delivery represent the dominant competitive moves reshaping market structure.
Within the integrated health system tier, IntegraMed America and US Fertility exemplify scale-driven operators with multi-state clinic footprints and centralized laboratory infrastructure. Kindbody occupies a position representing employer benefit-anchored digital platforms with direct scheduling capabilities and fertility benefit navigation. CCRM exemplifies the specialized advanced reproductive technology laboratory archetype with in-house embryology capabilities and research-affiliated clinical protocols. Planned Parenthood represents the federally funded community health infrastructure archetype with Title X-dependent service delivery across underserved counties. These four anchors illustrate the competitive spectrum from public funding dependence to self-pay premium service positioning.
| Leading Market Players |
|---|
| IntegraMed America |
| US Fertility |
| CCRM |
| Boston IVF |
| Reproductive Medicine Associates |
| Kindbody |
| Planned Parenthood |
| Shady Grove Fertility |
| IVF Centers of Excellence |
| Others |
Pricing and Supply Chain Analysis
Hospital-affiliated premium tiers and federally qualified commodity tiers diverge sharply in US reproductive health clinic economics, with the former commanding employer-funded fertility bundles and the latter locked into Medicaid fee schedules that barely cover device procurement costs. This bifurcation manifests in supply chain configurations where premium networks source FDA-cleared long-acting reversible contraceptives directly from manufacturers under volume contracts, while community health centers draw from 340B pharmacy programs with formulary constraints.
Pricing Analysis
Value-based pricing anchors employer-sponsored fertility benefits where per-episode IVF reimbursement ties to live birth outcomes rather than cycle count. Three-tier pricing structure across premium, standard, and economy levels separates hospital-affiliated reproductive endocrinology from independent multi-site operators and federally funded clinics. Pricing pressure stems from Medicaid rate stagnation in non-expansion states where IUD insertion reimbursement fails to cover labor and device costs. Employer-funded patients show lowest price sensitivity while Medicaid-dependent populations face access barriers from uncovered services.
Supply Chain Analysis
Direct-to-clinic channels handle long-acting reversible contraceptive distribution from three dominant manufacturers controlling device production. Geographic supply concentration centers on US-based pharmaceutical manufacturing for hormonal methods and European sourcing for specialized fertility pharmaceuticals. Raw material dependencies include medical-grade silicone for intrauterine devices, recombinant hormones for injectable contraceptives, and culture media for embryology laboratories. Single-source vulnerability pervades long-acting device supply where manufacturing consolidation limits formulary flexibility. Distribution runs through group purchasing organizations for hospital-affiliated networks and 340B pharmacy intermediaries for federally qualified health centers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US reproductive health clinic economics function as a cost-of-compliance story where HIPAA privacy infrastructure and FDA device quality systems create substantial barrier-to-entry moats for operators with capital to invest in accredited laboratory and data management platforms.
For Market Incumbents: Anchor market position through backward integration into in-house embryology laboratory capacity with CAP and CLIA certification, defending against independent fertility specialists with research-affiliated clinical protocols. Pursue vertical control over telehealth platform development to capture employer benefit navigation volume before digital-native entrants consolidate patient scheduling relationships. Medicaid managed care carve-outs in expansion states offer channel control leverage for multi-site network expansion.
For New Entrants and Emerging Players: Launch via mobile clinic deployment targeting agricultural worker corridors in California's Central Valley where seasonal labor populations lack fixed-site access. White-space concentration appears in digital fertility tracking integration partnerships with FDA-cleared wearable platforms, enabling remote cycle monitoring without proportional staff expansion. Employer benefit navigation platforms in Texas metropolitan corridors offer the most penetrable patient acquisition channel for direct-to-patient scheduling models.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated health systems seeking reproductive service line diversification and employer benefit network access. Long-term viability favors operators with demonstrated HIPAA-compliant telehealth infrastructure and multi-state Medicaid contracting capability. The signal to watch is FDA guidance on over-the-counter contraceptive switches that would accelerate clinic-pharmacy partnership models and reshape reimbursement flows.
| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Compliant Telehealth Platform Development | Enables remote contraceptive counseling and STI screening in rural counties with provider shortages. |
| Medicaid Managed Care Carve-Out Pursuit | Secures dedicated reimbursement streams for family planning-only coverage in expansion states. |
| In-House Embryology Laboratory Certification | Delivers CAP and CLIA accreditation for advanced reproductive technology service line launches. |
| Mobile Clinic Geographic Expansion | Extends reach into agricultural worker communities and underserved rural counties with seasonal demand. |
| Employer Benefit Navigation Partnership | Captures self-pay fertility volume from technology sector workforces with concentrated plan penetration. |
Research Methodology
Independent corroboration across clinic operations executives, reproductive endocrinologists, Medicaid policy specialists, and employer benefits consultants underwrites the qualitative findings in this study. Primary interviews with GPO contracts managers and 340B pharmacy program administrators combined with secondary validation from CMS Medicare data, FDA device approval filings, and state Medicaid waiver applications. Bottom-up service line volume estimates and top-down market sizing approaches triangulate to produce convergent findings across the analysis.
Rate-of-change decomposition separates volume growth from pricing evolution across service type, treatment modality, patient demographic, and care setting dimensions. Segmentation modeling incorporates family planning visit frequency, fertility treatment cycle intensity, and telehealth adoption curves throughout the forecast period. CAGRs derive from regression analysis against Medicaid expansion trajectories, employer benefit penetration rates, and FDA regulatory pathway timelines for device and pharmaceutical approvals.
State legislative shifts, Title X funding volatility, and FDA over-the-counter contraceptive guidance are the dominant revision risks that could materially alter trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
IVF Services Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Fertility Services Market
Reproductive Health
Donor Egg IVF Services Market