
 Contraceptives Market | 2026-2036
Contraceptives Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptives Market Analysis
The contraceptives market is rebalancing between premium hormonal formulations and commodity condom segments as pricing power diverges by reimbursement status. Bayer AG leverages its vertical integration in hormone synthesis to sustain margin advantages across intrauterine device portfolios. Pfizer Inc. anchors its position through R&D intensity in novel progestin combinations, while Merck & Co. competes on manufacturing scale for implantable systems.
Contraceptives comprise pharmacological and mechanical interventions designed to prevent pregnancy through hormonal suppression of ovulation, physical barrier methods, or copper-mediated spermicidal action, with efficacy rates varying by mechanism from 85% to 99.9% under typical use conditions. Their primary purpose spans family planning, emergency intervention, and dual-protection against sexually transmitted infections across clinical and consumer channels. Intrauterine Devices command durable margin pools due to long-acting duration and clinic-dependent insertion protocols, while Online Retail channels are capturing the fastest growth in recurring hormonal pill prescriptions. Emergency Contraception applications face regulatory-driven access expansion, shifting volume toward pharmacy and clinic networks in markets with over-the-counter authorization.
The FDA oversees premarket approval and labeling standards for hormonal products in the United States, while the EMA enforces centralized marketing authorization and pharmacovigilance across European Union member states. REACH and RoHS frameworks indirectly shape material specifications for device polymers and copper alloys, constraining supplier qualification and import compliance. India's CDSCO and state-level drug controllers administer product registration and quality testing under the Drugs and Cosmetics Act, creating layered entry requirements for multinational manufacturers. Stakeholders must monitor evolving reimbursement tier classifications and digital pharmacy regulations to anticipate channel profitability shifts.
Market Dynamics
The contraceptives market is rebalancing around clinic-dependent insertion protocols for long-acting reversible methods versus direct-to-consumer access for hormonal pills, with reimbursement tier classifications determining margin capture across channels.
Growth Catalysts
- India's CDSCO streamlining:The national drug regulator is accelerating product registration timelines for intrauterine devices and subdermal implants, reducing entry friction for multinational manufacturers.
- Family planning program expansion:Government-backed initiatives in Southeast Asia are embedding long-acting reversible contraceptive services into primary care networks, driving volume through public procurement.
- Telemedicine integration:Digital health platforms are enabling remote prescription renewals for hormonal contraceptives, capturing recurring demand through pharmacy-integrated fulfillment.
Market Restraints
- Copper and polymer input volatility:Intrauterine device manufacturers face margin compression from fluctuating copper alloy and medical-grade polymer costs, constraining pricing flexibility in reimbursed segments.
- Insertion skill concentration:Clinic-dependent protocols for implants and IUDs create supply bottlenecks where trained provider availability limits geographic penetration, particularly in rural India and Indonesia.
- REACH material compliance:European chemical registration requirements are disqualifying legacy polymer suppliers, forcing device makers to qualify alternative materials under compressed timelines.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:The dispersed island geography creates whitespace for mobile clinic networks and pharmacy-based implant provision, bypassing fixed infrastructure constraints.
- FDA over-the-counter pathway:The regulatory framework for non-prescription hormonal contraceptive authorization offers first-mover advantage in pharmacy channel expansion.
- Biodegradable implant R&D:Convergence of polymer science and controlled-release formulation technology is opening segments for non-surgical removal alternatives.
Industry Challenges
- Specialized insertion training pipelines:Healthcare systems lack sufficient certified providers for long-acting device placement, creating fulfillment gaps even where product access exists.
- Multi-jurisdiction labeling harmonization:Divergent FDA, EMA, and CDSCO requirements for hormonal product safety data force redundant clinical documentation and delayed market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptives Market |
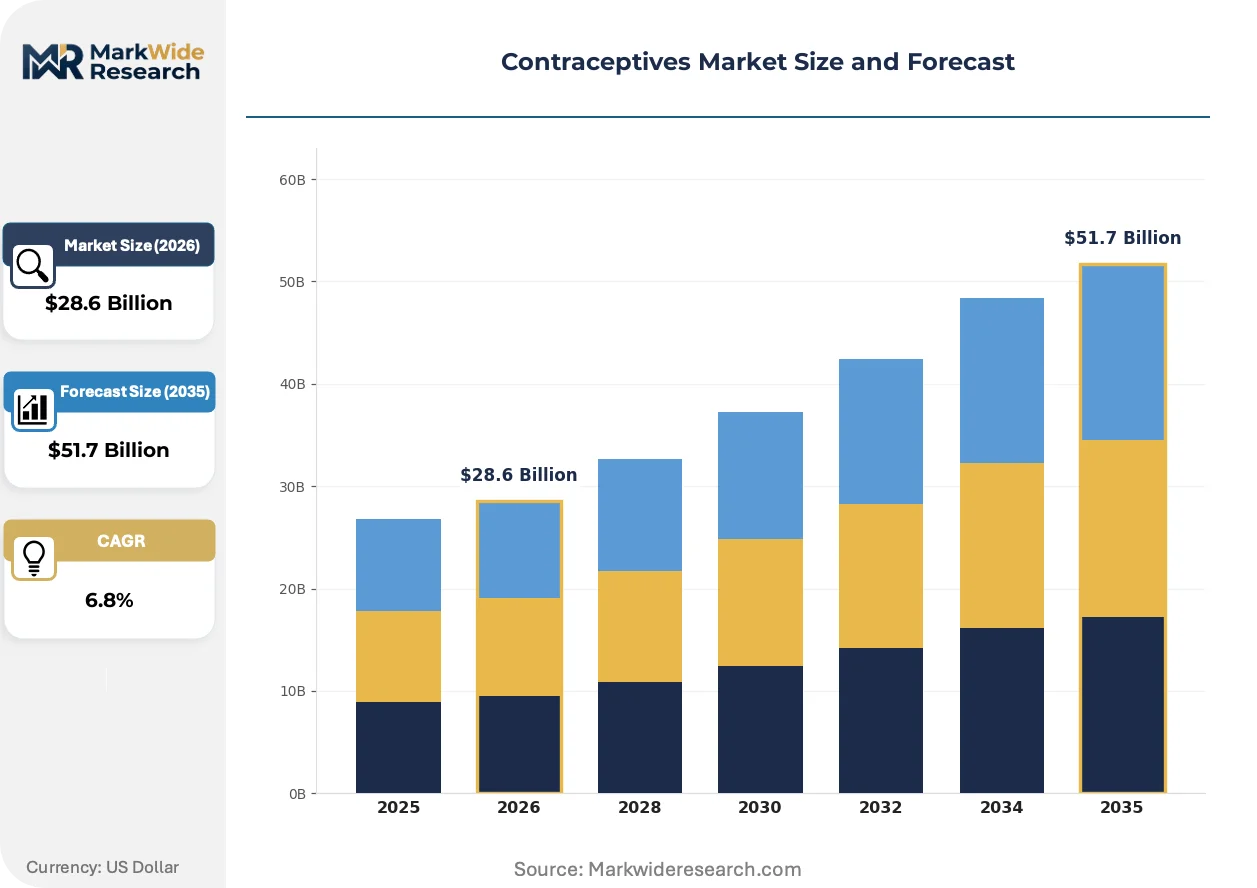
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Pills, Intrauterine Devices, Condoms, Implants Application: Family Planning, Emergency Contraception, Reproductive Health, STI Prevention Distribution Channel: Pharmacies, Hospitals, Clinics, Online Retail End User: Individuals, Couples, Healthcare Providers, Non-Governmental Organizations |
| Companies Covered | Pfizer Inc., Bayer AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Johnson & Johnson, AbbVie Inc., Church & Dwight Co., Inc., CooperSurgical, Inc., Reckitt Benckiser Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptives Market Emerging Trajectories
Digital distribution infrastructure and next-generation delivery systems are compressing the traditional clinic-pharmacy hierarchy, while regulatory frameworks accelerate access liberalization in select markets.
Subdermal implant technology with multi-year hormone release profiles is decentralizing contraceptive provision from specialized clinics to primary care and pharmacy settings. Nurse practitioners and community health workers in India and the Philippines are adopting simplified insertion protocols. This capability transfer is decentralizing volume capture from hospital systems toward distributed care networks.
The FDA's updated labeling requirements for combined hormonal contraceptives are mandating revised venous thromboembolism risk disclosure, forcing reformulation toward lower-dose progestin combinations. Manufacturers are responding by accelerating novel progestin development programs. The United States oral contraceptive segment is experiencing portfolio rotation as legacy products face prescribing preference shifts.
Subscription-based pharmacy fulfillment is replacing episodic prescription renewal for hormonal pill users, with automated delivery and telehealth consultation bundling. Younger demographics in urban India and Southeast Asian metropolitan areas are adopting these models fastest. This channel migration is compressing traditional retail pharmacy foot traffic while building direct manufacturer-consumer relationships.
Contraceptives Market Segmentation
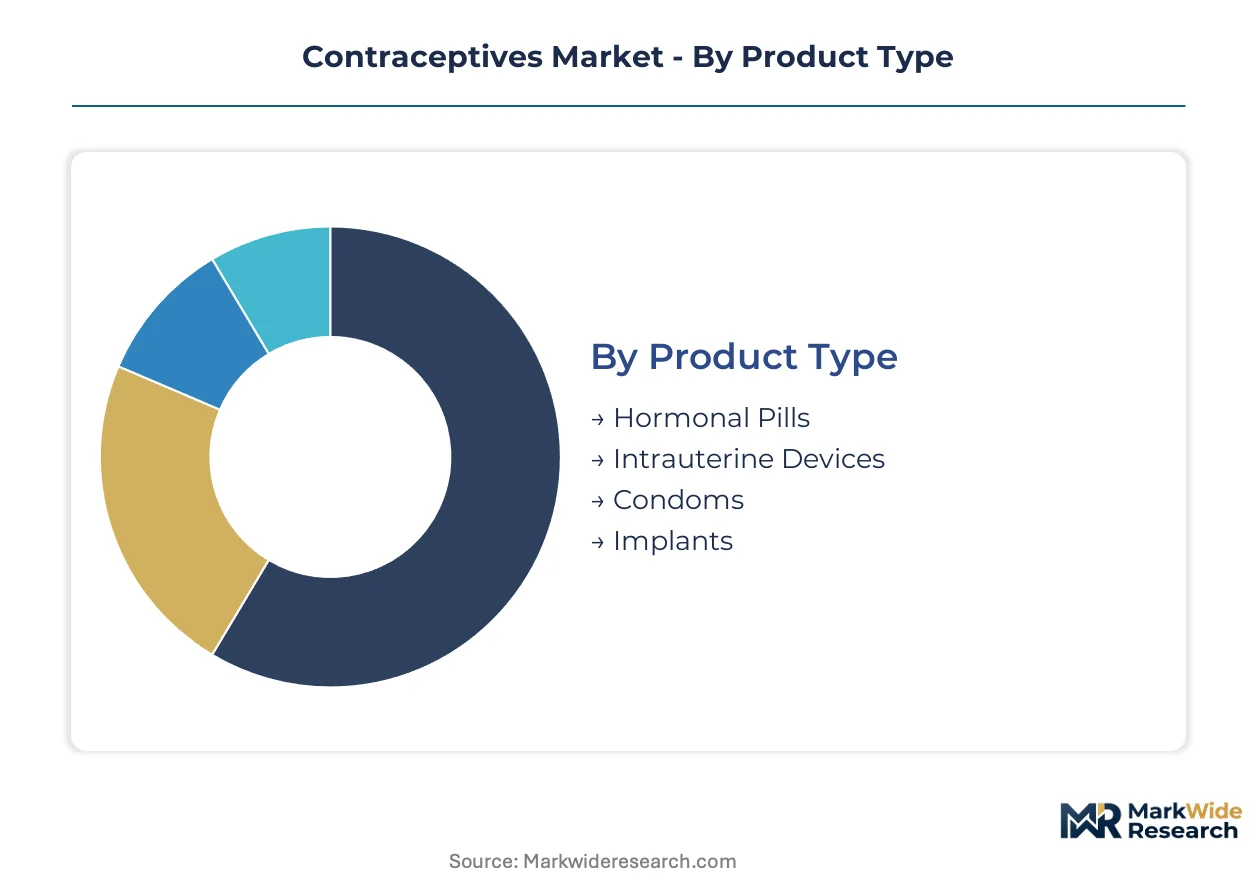
Segmentation in contraceptives reveals how regulatory pathways, insertion protocols, and reimbursement tiers fragment commercial opportunity. Each category carries distinct certification burdens and margin profiles that determine manufacturer positioning and channel strategy.
Product Type:
FDA premarket approval governs hormonal pills and implants, while intrauterine devices face additional device-specific PMA pathways; condoms navigate simpler 510(k) or equivalent national clearances depending on jurisdiction.
- Hormonal Pills:Synthetic estrogen-progestin combinations in daily oral formulations. Demand concentrates in urban India and Southeast Asian metropolitan areas where subscription pharmacy models are displacing retail foot traffic. The FDA's updated venous thromboembolism labeling requirements are forcing portfolio rotation toward lower-dose progestin variants.
- Intrauterine Devices:Copper alloy or hormone-eluting T-shaped devices requiring clinic-based insertion. Volume clusters in India's government procurement channels and Indonesia's expanding primary care networks, constrained by trained provider availability in rural geographies.
- Condoms:Latex or synthetic polymer barrier methods with minimal regulatory friction. Mass distribution through public health programs in the Philippines and Thailand drives volume in commodity segments.
- Implants:Subdermal rods releasing progestin over multi-year durations. Nurse practitioner adoption in India and the Philippines is decentralizing provision from specialized clinics.
Leading the category by volume: Hormonal Pills. Growing fastest: Implants.
Application:
Application segments diverge by urgency—scheduled prevention versus acute intervention—with reimbursement tiers determining whether products reach pharmacy shelves or remain clinic-captive.
- Family Planning:Routine contraceptive use spanning hormonal, mechanical, and long-acting reversible methods. India's national family planning program and Indonesia's district health offices anchor procurement volume for intrauterine devices and implants.
- Emergency Contraception:High-dose hormonal pills taken post-coitus. Over-the-counter authorization in select markets is shifting volume toward pharmacy networks; regulatory fragmentation limits multi-jurisdiction launches.
- Reproductive Health:Clinical management of menstrual disorders and hormonal conditions using contraceptive mechanisms. Specialist prescribing in Thailand's hospital systems and India's private clinic chains sustains premium pricing.
- STI Prevention:Dual-protection applications where condoms dominate. Public health procurement in Vietnam and Myanmar emphasizes commodity volume over margin.
Dominant by procurement scale: Family Planning. Expanding most quickly: Emergency Contraception.
Distribution Channel:
Channel selection dictates margin capture—clinic-dependent insertion protocols preserve premium pricing while direct-to-consumer access compresses spreads through competitive pharmacy and digital fulfillment.
- Pharmacies:Community and chain retail outlets handling pills, condoms, and over-the-counter emergency products. Urban India and Southeast Asian cities are experiencing subscription-model disruption as telehealth-integrated fulfillment builds recurring revenue streams.
- Hospitals:Tertiary care systems managing complex cases and surgical contraception. India's tier-1 cities and Thailand's Bangkok-centered hospital networks concentrate high-value reproductive health procedures.
- Clinics:Primary care and specialized family planning facilities performing device insertions. Indonesia's island geography creates access gaps where mobile clinic networks present whitespace opportunity.
- Online Retail:Digital pharmacies and direct-to-consumer platforms. Younger demographics in India's metropolitan areas and the Philippines are adopting automated prescription renewal fastest.
Highest volume capture: Pharmacies. Steepest expansion trajectory: Online Retail.
End User:
End user categories reflect purchasing authority fragmentation—individual consumers versus institutional procurement—with pricing power varying sharply by decision-maker type and funding source.
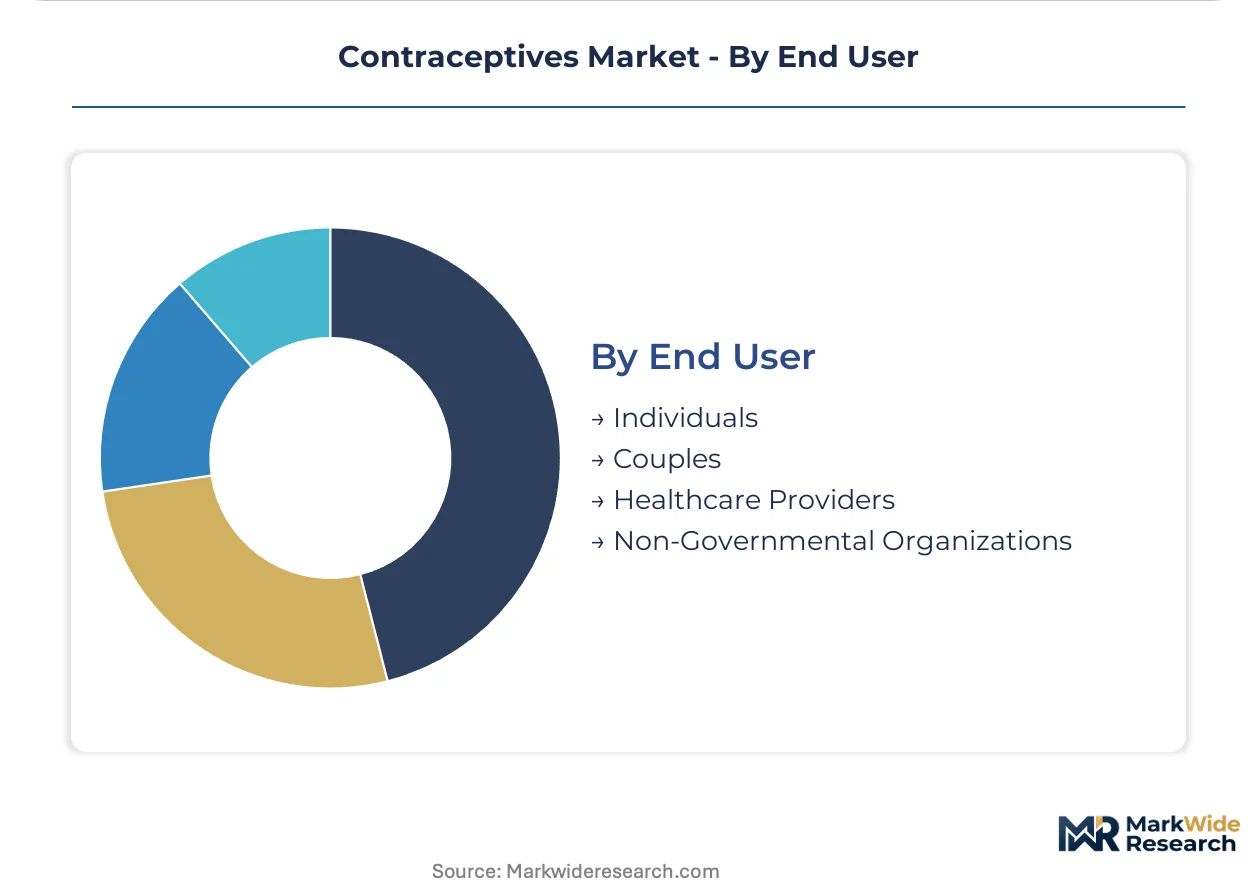
- Individuals:Direct consumers selecting over-the-counter or prescription products. India's rising middle class and Southeast Asian urban professionals are driving demand for discreet subscription delivery and premium hormonal formulations.
- Couples:Joint decision-making units prioritizing long-acting reversible methods. Clinic consultations in Thailand and Vietnam's private health sectors favor implant and intrauterine device counseling.
- Healthcare Providers:Physicians, nurse practitioners, and community health workers selecting products for patient populations. India's accredited social health activists and the Philippines' rural health midwives influence public procurement specifications.
- Non-Governmental Organizations:Development and advocacy organizations distributing subsidized products. Family planning-focused NGOs in Indonesia and Myanmar negotiate bulk purchasing agreements for commodity condoms and oral pills.
Largest procurement base: Individuals. Gaining share fastest: Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the Asia-Pacific contraceptives trade corridor, with pharmaceutical formulation clusters in Bhiwandi and Thane feeding distribution networks across India and Southeast Asia. Manufacturing scale concentrates in hormone synthesis facilities serving domestic procurement and export markets.
India
India's national family planning program drives bulk procurement of intrauterine devices through state-level health missions. CDSCO streamlines registration timelines for hormonal implants, accelerating market entry for multinational manufacturers. Hyderabad's pharmaceutical corridor hosts active pharmaceutical ingredient synthesis for progestin-based products.
Indonesia
Dispersed archipelago geography creates demand for mobile clinic networks delivering long-acting reversible contraceptives to remote islands. The Ministry of Health embeds implant services into primary care networks through district health offices. Java's urban corridors concentrate trained provider capacity while outer islands present whitespace for pharmacy-based provision models.
United States
Subscription pharmacy models capture recurring hormonal pill demand among urban professionals seeking discreet fulfillment. FDA updated labeling requirements for venous thromboembolism risk disclosure, forcing portfolio rotation toward lower-dose formulations. New Jersey's pharmaceutical corridor houses formulation R&D for novel progestin combinations.
Germany
EMA centralized marketing authorization shapes pan-European launch strategies for hormonal products. REACH chemical registration requirements disqualify legacy polymer suppliers, forcing device makers to qualify alternative materials. Frankfurt's regulatory consulting cluster supports compliance documentation for multi-jurisdiction submissions.
Thailand
Private hospital networks in Bangkok concentrate high-value reproductive health procedures and specialist prescribing for hormonal conditions. The Ministry of Public Health distributes subsidized condoms through primary care networks. Chonburi's medical device zone hosts regional distribution hubs for intrauterine device imports.
Contraceptives Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification burden. Hormonal specialists command pricing power through FDA and EMA premarket approvals, while condom manufacturers compete on manufacturing scale and public procurement relationships. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, device-focused manufacturers with polymer expertise, and mass-market consumer health groups. Competitive moves concentrate on M&A for hormone synthesis capabilities and strategic partnerships for telehealth distribution channels.
Within the vertically integrated tier, Bayer AG and Pfizer Inc. exemplify archetypes combining hormone synthesis with device portfolios. Among mass-market consumer health specialists, Church & Dwight Co., Inc. occupies a position representing commodity-scale manufacturing and retail channel dominance. These three anchors illustrate how regulatory depth and manufacturing scale separate premium-capture players from procurement-dependent competitors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| AbbVie Inc. |
| Church & Dwight Co., Inc. |
| CooperSurgical, Inc. |
| Reckitt Benckiser Group Plc |
| Others |
Supply Flow & Price Mechanics
Copper alloy and medical-grade polymer costs cascade through intrauterine device manufacturing into three-tier pricing structures separating premium hormone-eluting systems from standard copper devices and economy condom segments. Input volatility in reimbursed markets compresses margin flexibility while subscription pharmacy models for hormonal pills capture recurring revenue streams.
Pricing Analysis
Duration-based efficacy anchors value-based pricing for long-acting reversible contraceptives, with multi-year implant and intrauterine device premiums reflecting clinic-dependent insertion protocols and trained provider scarcity. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—FDA PMA pathways command highest tiers—and volume scale through public procurement. Cost compression in commodity condom segments intensifies because mass distribution programs emphasize unit economics over margin. Healthcare providers exhibit lowest price sensitivity due to reimbursement pass-through, while individual consumers in direct-to-access channels show highest elasticity.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients reshapes progestin sourcing patterns, compelling multinational formulators to establish local hormone synthesis partnerships or absorb import duty penalties. API concentration centers on India and China for synthetic estrogen-progestin combinations, with medical-grade polymer feedstocks drawing from Germany and specialty copper alloy suppliers in Chile. Single-source vulnerability pervades hormone precursor supply where CDSCO registration timelines create qualification bottlenecks. Distribution runs through pharmaceutical wholesale networks into hospital procurement systems, retail pharmacy chains, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contraceptives market functions as a cost-of-compliance arena where FDA premarket approval pathways and EMA centralized marketing authorization erect durable barriers against undercapitalized entrants. REACH chemical registration and India's CDSCO layered requirements compound certification burdens that favor incumbents with regulatory affairs infrastructure.
For Market Incumbents: Lock in hormone synthesis capabilities through backward integration or captive supply agreements with Hyderabad's API corridor, insulating margin pools from copper and polymer input volatility. Secure nurse practitioner training pipelines in Indonesia's outer islands and India's rural districts before insertion skill concentration hardens into structural bottlenecks that limit volume capture. For New Entrants and Emerging Players: The mid-tier price gap between premium hormonal implants and economy condoms offers whitespace for simplified subdermal systems targeting pharmacy-based provision in Vietnam and Myanmar. Indonesia's archipelago geography presents the most penetrable terrain for mobile clinic networks bypassing fixed infrastructure constraints. Pursue telehealth-integrated subscription fulfillment as the primary go-to-market angle, capturing recurring demand through automated prescription renewal. For Investors and Strategic Acquirers: CDSCO's acceleration of implant registration timelines is the leading indicator that India's public procurement volume will concentrate among early-mover multinational manufacturers. Five-to-ten-year viability favors vertically integrated players combining hormone synthesis with device portfolios. Target acquisition archetypes include regional API specialists with CDSCO-approved facilities and digital pharmacy platforms with established subscription infrastructure. Watch FDA over-the-counter pathway rulings as the inflection signal for pharmacy channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Early entrants capture India's expanding public procurement volume for implants and intrauterine devices. |
| Telehealth Platform Partnership | Subscription pharmacy integration builds direct manufacturer-consumer relationships in urban India and Southeast Asia. |
| Nurse Practitioner Training Scale-Up | Decentralized insertion capability transfers volume from hospital systems to primary care networks. |
| Biodegradable Implant R&D Investment | Non-surgical removal alternatives open segments beyond clinic-dependent long-acting methods. |
| REACH-Compliant Polymer Qualification | Alternative material sourcing preserves European market access as legacy suppliers face disqualification. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across regulatory affairs leads at multinational pharmaceutical manufacturers, GPO contracts managers at Indian hospital systems, and family planning program officers at Indonesia's Ministry of Health. FDA 510(k) and PMA databases, EMA centralized authorization records, CDSCO product registration logs, and pharmaceutical import-export declarations supplied validation layers. Bottom-up volume estimates from state-level health mission procurement and top-down value projections from manufacturer revenue disclosures underwent iterative reconciliation.
Data-stream reconciliation across product type, application, distribution channel, and end user segmentation generated volume and value outputs across the projection horizon. Modeled dimensions included hormonal mechanism, device material composition, reimbursement tier classification, and regional regulatory cluster. CAGRs derived from trend extrapolation of public procurement volumes, private clinic network expansion rates, and digital pharmacy adoption curves, cross-referenced against population demographics and family planning program budget allocations.
Inputs from CDSCO, FDA, and EMA regulatory databases were available through the study window; gaps in real-time procurement transaction data from Indonesia's district health offices introduce uncertainty bands around archipelago penetration estimates. Forecasts reflect assumptions regarding telehealth regulatory liberalization and nurse practitioner scope expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Fertility Services Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
IVF Services Market
Reproductive Health
Donor Egg IVF Services Market