
 Global Gynecology Drugs Market | 2026-2036
Global Gynecology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecology Drugs Market Foresight
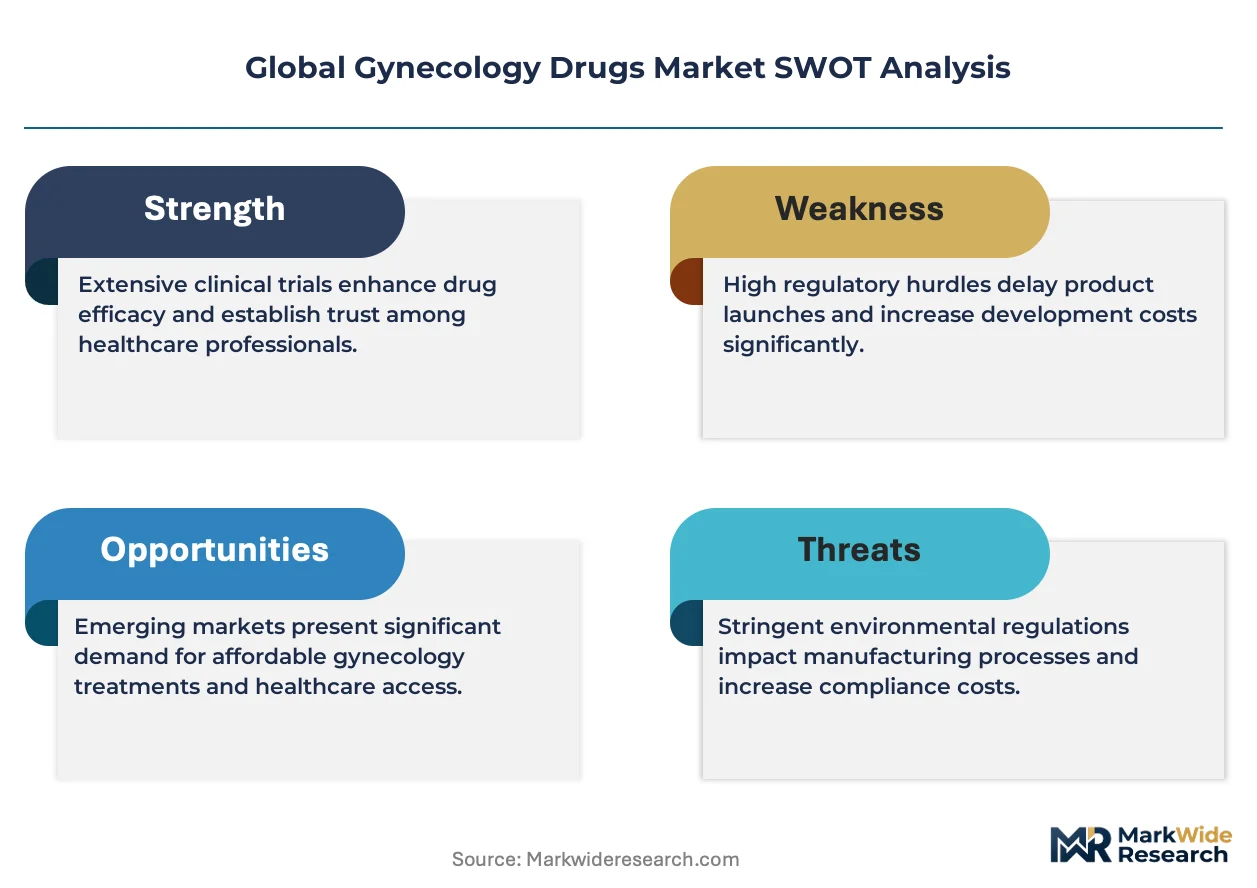
Modular therapy packaging is decoupling diagnostic workup from chronic disease management in gynecology care pathways. AbbVie leverages its immunology infrastructure to anchor endometriosis therapy development across multiple delivery formats. Pfizer competes through manufacturing scale in hormonal contraceptive supply, while GSK specializes in antimicrobial portfolios for vaginal infection management.
Gynecology drugs comprise pharmaceutical agents targeting female reproductive system disorders, formulated as oral tablets, injectables, intrauterine devices, and topical preparations with defined bioavailability profiles and dosing regimens. These therapies modulate endocrine function, induce uterine contraction, suppress inflammation, or eliminate pathogenic organisms to restore reproductive health and prevent disease progression. Hormonal contraceptives occupy the largest revenue pool given their chronic use profile and established reimbursement infrastructure, while fertility enhancers represent the fastest-expanding category driven by delayed childbearing trends and assisted reproduction expansion. Uterotonics command premium pricing in acute postpartum hemorrhage protocols where clinical efficacy determines formulary placement.
FDA endometriosis guidance, EMA centralized marketing authorization pathways, and WHO prequalification standards collectively elevate clinical evidence requirements for market entry and shape regional launch sequencing. The EU MDR transition imposes stricter post-market surveillance obligations on device-drug combination products including intrauterine hormonal systems. Stakeholders must monitor evolving pharmacovigilance mandates and pre-approval access programs as determinants of competitive positioning in women's health portfolios.
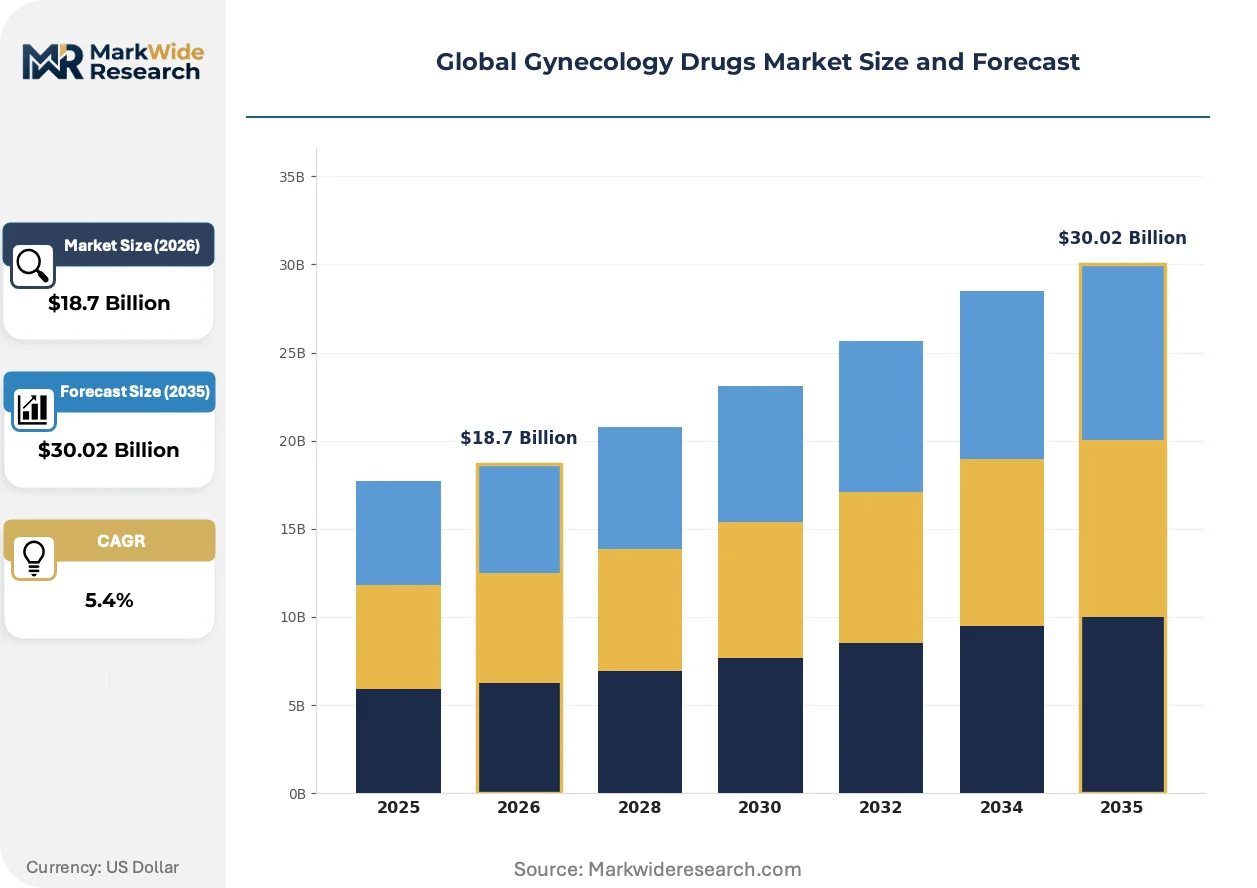
Market Dynamics
Specialty pharmacy networks are consolidating fertility and hormonal therapy dispensing, reshaping patient access pathways and formulary negotiation leverage across integrated health systems.
Growth Catalysts
- FDA Endometriosis Guidance:The updated framework accelerates novel therapy submissions by redefining clinical trial endpoints and patient-reported outcome measures.
- Delayed Childbearing Patterns:Rising maternal age across developed economies expands the addressable population for ovulation induction and assisted reproduction pharmaceuticals.
- Intrauterine Device Innovation:Extended-release hormonal systems with improved bleeding profiles drive replacement cycles and premium positioning in contraceptive portfolios.
Market Restraints
- API Supply Concentration:Synthetic progestin active pharmaceutical ingredients rely heavily on Chinese and Indian bulk manufacturing, exposing formulators to geopolitical and quality disruption risks.
- EMA Post-Market Surveillance:The EU MDR transition imposes extended vigilance obligations on device-drug combination products, lengthening compliance timelines for intrauterine systems.
- Generic Erosion in Oral Contraceptives:Patent expirations on established combined oral formulations compress pricing power for originator manufacturers.
Strategic Opportunities
- Brazil's ANVISA Fast-Track:The priority review pathway for women's health therapeutics enables accelerated entry into Latin America's largest pharmaceutical market.
- Digital Therapeutic Adjuvants:App-based medication adherence and symptom tracking platforms create bundled service opportunities around chronic gynecologic conditions.
- Biosimilar Fertility Hormones:Recombinant FSH and LH analogs approaching patent cliff open white space for follow-on biologics with improved injection devices.
Industry Challenges
- Specialized Reproductive Endocrinology Talent:The limited pool of investigators trained in ovarian stimulation protocols constrains clinical trial expansion for fertility pipeline assets.
- Legacy Electronic Health Record Integration:Modular therapy packaging requires interoperability with entrenched hospital information systems, complicating care pathway redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecology Drugs Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Contraceptives, Fertility Enhancers, Uterotonics, Anti-inflammatory Agents, Antimicrobials Therapy Area: Menstrual Disorders, Endometriosis, Polycystic Ovary Syndrome, Cervical Dysplasia, Vaginitis End User: Gynecology Clinics, Reproductive Health Centers, Specialty Pharmacies, Diagnostic Laboratories, Academic Hospitals Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales, Medical Representatives |
| Companies Covered | AbbVie, Novartis, Pfizer, GSK, Sanofi, Bayer, Johnson & Johnson, Ferring Pharmaceuticals, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecology Drugs Market Shifts & Advancements
Pharmaceutical delivery formats and diagnostic integration are reshaping how gynecologic therapies reach patients, with implications for adherence measurement and chronic disease management protocols.
Long-acting subcutaneous depot formulations is converging with connected injection devices to enable home administration of previously clinic-bound fertility and endometriosis therapies. Reproductive endocrinology practices in the United States and Germany are piloting these systems to reduce cycle monitoring burdens. This convergence is compressing the traditional site-of-care boundary between hospital-based infertility centers and patient-managed chronic therapy.
REACH authorization requirements for endocrine-disrupting chemical assessments are tightening excipient sourcing standards for vaginal and topical gynecologic preparations. European formulators must now document full supply chain toxicity profiles for preservatives and penetration enhancers. Intravaginal antimicrobial and hormonal products face reformulation pressures as ECHA evaluates candidate list substances.
Self-administered fertility monitoring via at-home hormone testing devices is redirecting patient traffic from traditional clinic-based cycle tracking. Direct-to-consumer channels and specialty pharmacy fulfillment are displacing hospital outpatient dispensing for ovulation induction protocols. This behavioral pivot is most pronounced in Australia and the United Kingdom, where regulatory frameworks accommodate remote prescribing for established fertility medications.
Global Gynecology Drugs Market Segmentation
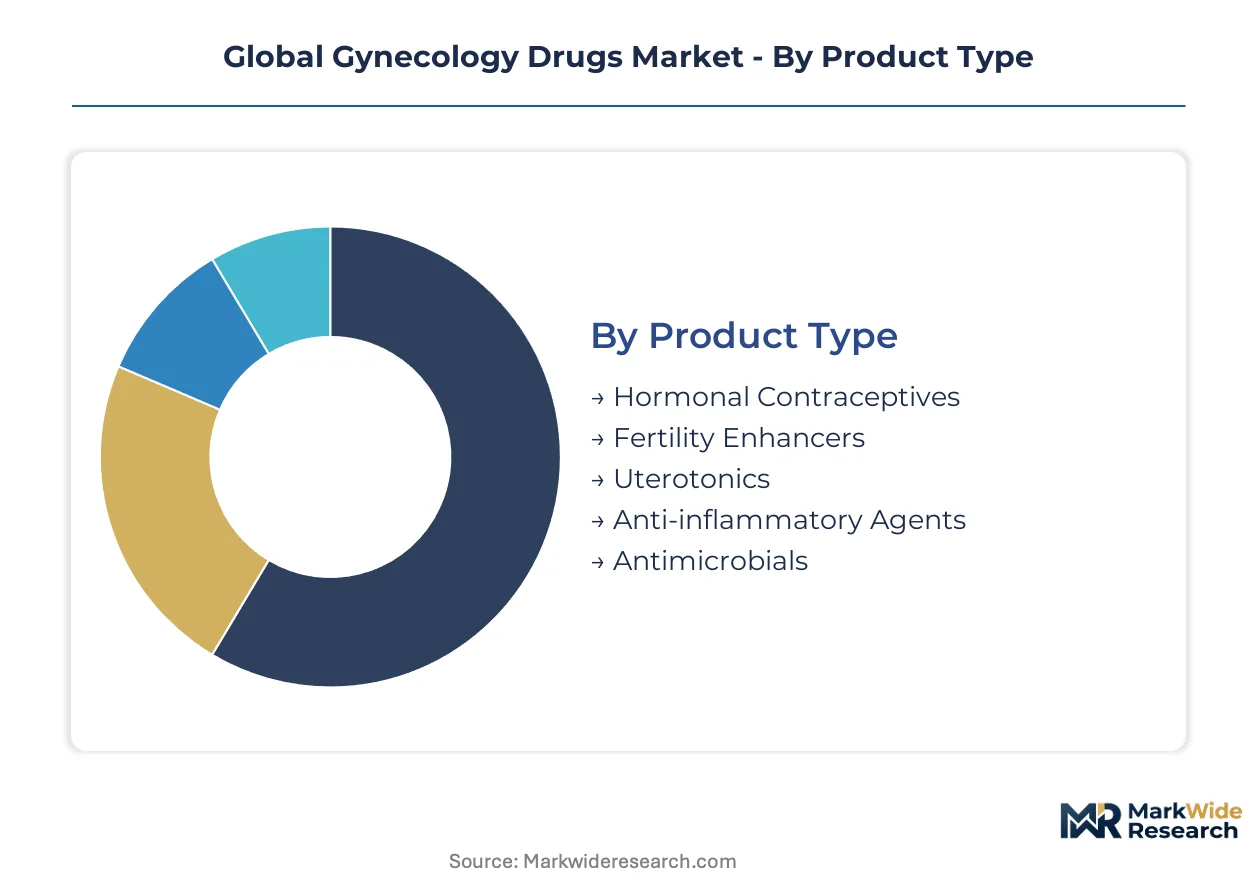
Segmentation in gynecology pharmaceuticals reveals distinct reimbursement pathways and site-of-care dependencies. Therapy area and distribution channel choices directly determine patient access velocity and formulary negotiation leverage across integrated health systems.
Product Type:
Volume leadership concentrates in chronic-use hormonal formulations, while acute intervention products command premium positioning through clinical efficacy thresholds.
- Hormonal Contraceptives:Synthetic estrogen-progestin combinations and progestin-only formulations dominate dispensing volumes through established retail pharmacy networks. United States integrated health systems negotiate these portfolios aggressively, with CVS Caremark and Express Scripts consolidating formulary placement decisions for combined oral tablets and transdermal patches.
- Fertility Enhancers:Recombinant follicle-stimulating hormone (FSH) and luteinizing hormone (LH) analogs, plus clomiphene citrate ovulation inducers, target assisted reproduction protocols. Demand is climbing fastest in Germany and Australia where delayed childbearing patterns expand the addressable population for ovarian stimulation pharmaceuticals.
- Uterotonics:Oxytocin and carboprost tromethamine formulations for postpartum hemorrhage management.
- Anti-inflammatory Agents:GnRH agonists and selective progesterone receptor modulators for endometriosis pain management.
- Antimicrobials:Metronidazole, clindamycin, and fluconazole preparations for bacterial vaginosis and candidiasis treatment.
Mature deployment sits with Hormonal Contraceptives. Newer deployment is concentrated in Fertility Enhancers.
Therapy Area:
Application intensity varies by diagnostic infrastructure density and specialty care access, with chronic conditions requiring sustained pharmaceutical management versus acute infectious episodes.
- Endometriosis:Medical therapy spans GnRH antagonists, progestins, and emerging selective estrogen receptor modulators targeting ectopic lesion proliferation. FDA updated guidance is accelerating novel submissions, with AbbVie and Myovant Sciences advancing oral antagonist formulations through priority review pathways.
- Polycystic Ovary Syndrome:Insulin sensitizers, combined oral contraceptives, and anti-androgen agents address metabolic and reproductive manifestations. Prescription concentration is heaviest in United States academic medical centers where reproductive endocrinology fellowship programs anchor specialized care pathways.
- Menstrual Disorders:Heavy menstrual bleeding and dysmenorrhea management through hormonal and non-hormonal interventions.
- Cervical Dysplasia:Topical imiquimod and therapeutic vaccines targeting HPV-related precancerous lesions.
- Vaginitis:Antimicrobial and antifungal therapies for infectious etiologies.
Established therapeutic infrastructure supports Endometriosis. Emerging protocol adoption is accelerating in Polycystic Ovary Syndrome.
End User:
Customer type segmentation tracks site-of-care evolution, with traditional hospital-based delivery fragmenting toward ambulatory and direct-to-consumer channels.
- Specialty Pharmacies:Dedicated fertility and hormonal therapy dispensing with embedded patient counseling and adherence monitoring. CVS Specialty and AllianceRx Walgreens Prime are expanding refrigerated biologic handling capabilities for gonadotropin injections across United States metropolitan markets.
- Reproductive Health Centers:Clinic-based dispensing of ovulation induction protocols and cycle monitoring pharmaceuticals. Germany's university-affiliated fertility networks maintain tighter vertical control over medication distribution than United States counterparts.
- Gynecology Clinics:Office-based administration of long-acting reversible contraceptives and acute infection treatment.
- Diagnostic Laboratories:Limited direct dispensing, primarily hormone testing companion services.
- Academic Hospitals:Research protocol drug supply and complex case management.
Concentrated volume flows through Specialty Pharmacies. Dispersion is widening toward Reproductive Health Centers.
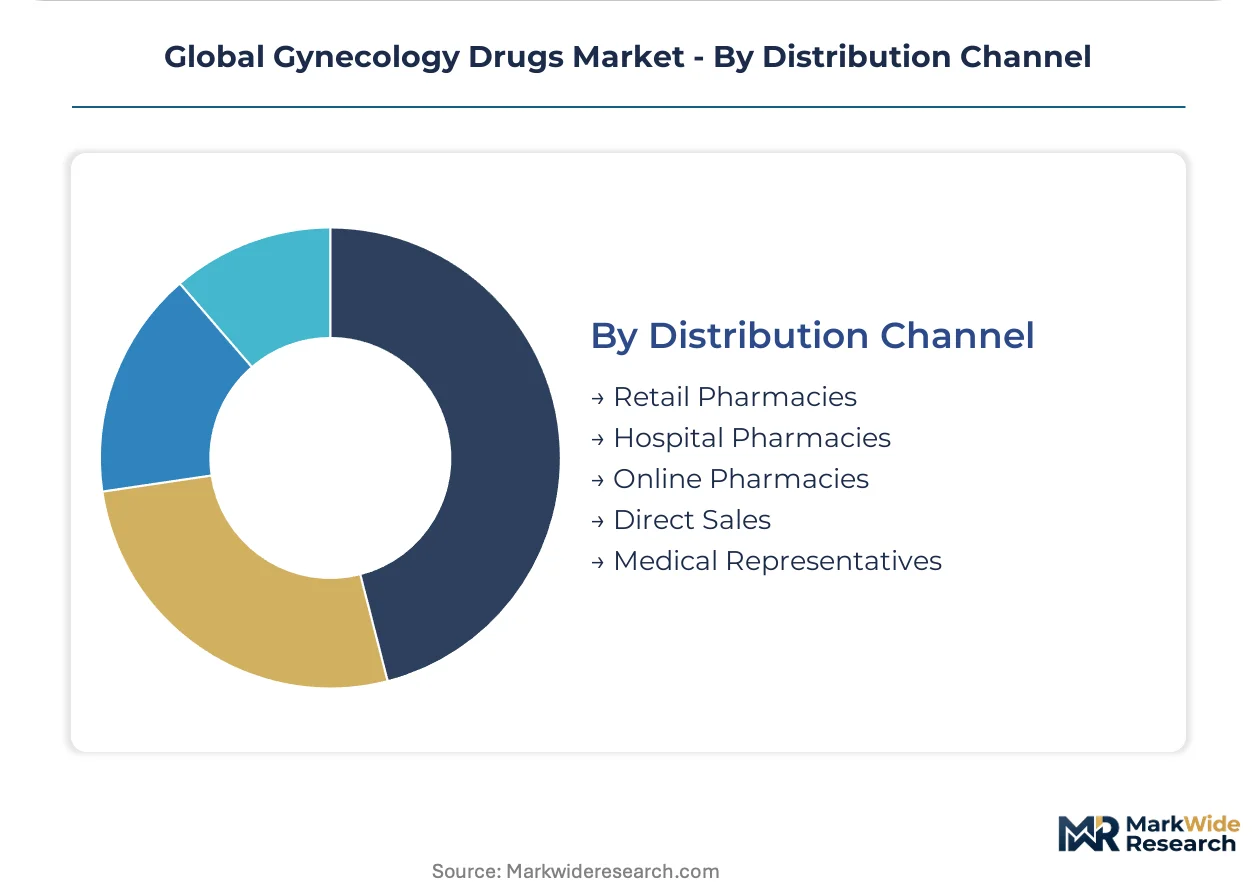
Distribution Channel:
Channel economics reflect pharmacy benefit manager consolidation and direct manufacturer contracting strategies for chronic therapy maintenance.
- Retail Pharmacies:Community pharmacy networks handling oral contraceptive maintenance refills and acute antimicrobial prescriptions. Walgreens and Rite Aid capture substantial hormonal contraceptive volume through 90-day refill programs and automated adherence packaging.
- Online Pharmacies:Direct-to-consumer fulfillment expanding for fertility medication self-administration and sensitive condition treatments. Ro Pharmacy and Hims & Hers are gaining traction in United States markets where telehealth prescribing regulations accommodate remote consultation models.
- Hospital Pharmacies:Inpatient dispensing for surgical prophylaxis and acute postpartum interventions.
- Direct Sales:Manufacturer-to-provider contracting for specialty biologics.
- Medical Representatives:Detailing-supported prescribing influence in institutional settings.
Established infrastructure anchors Retail Pharmacies. Channel expansion is accelerating through Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing concentrates in China and India, while formulation and consumption tilt toward the United States and Western Europe. Specialty pharmacy dispensing and reproductive endocrinology infrastructure create divergent access pathways across markets. Regulatory fragmentation around device-drug combinations shapes divergent compliance timelines.
United States
FDA endometriosis guidance accelerates novel therapy submissions through redefined clinical trial endpoints. Integrated health systems like Kaiser Permanente and Mayo Clinic negotiate consolidated formularies for women's health portfolios. CVS Specialty and AllianceRx Walgreens Prime expand refrigerated biologic handling for gonadotropin injections across metropolitan markets.
Germany
University-affiliated fertility networks maintain tighter vertical control over medication distribution than United States counterparts. EMA centralized marketing authorization pathways elevate clinical evidence requirements for intrauterine hormonal systems. Reproductive endocrinology practices in Munich and Hamburg pilot long-acting subcutaneous depot formulations with connected injection devices.
China
Synthetic progestin active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces. NMPA marketing authorization reforms streamline submissions for hormonal contraceptives while tightening pharmacovigilance for fertility biologics. Domestic formulators are consolidating backward integration into API supply to reduce import dependency.
Brazil
ANVISA fast-track priority review for women's health therapeutics enables accelerated entry into Latin America's largest pharmaceutical market. Delayed childbearing patterns in São Paulo and Rio de Janeiro expand demand for ovulation induction protocols. Specialty pharmacy networks are displacing hospital outpatient dispensing for chronic hormonal therapies.
Australia
TGA accommodates remote prescribing frameworks for established fertility medications, redirecting patient traffic toward direct-to-consumer channels. Self-administered fertility monitoring via at-home hormone testing devices compresses cycle monitoring burdens in Sydney and Melbourne. Digital therapeutic adjuvants for medication adherence create bundled service opportunities around chronic gynecologic conditions.
Global Gynecology Drugs Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with immunology and endocrinology infrastructure. Large integrated manufacturers anchor hormonal contraceptive supply through manufacturing scale, while specialty biotech firms concentrate on GnRH modulators and selective receptor targeting. Three archetypes dominate: immunology-platform extenders, manufacturing-scale hormonal suppliers, and antimicrobial portfolio specialists. Consolidation moves center on fertility hormone pipeline acquisitions and device-drug combination partnerships.
Among the immunology-platform extenders, AbbVie leverages existing infrastructure to anchor endometriosis therapy development. Pfizer occupies a scale-driven position in hormonal contraceptive manufacturing. GSK exemplifies the antimicrobial specialization archetype through vaginal infection management portfolios. These three represent divergent strategic bets on chronic disease management versus acute intervention market segments.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| Pfizer |
| GSK |
| Sanofi |
| Bayer |
| Johnson & Johnson |
| Ferring Pharmaceuticals |
| Merck |
| Others |
Supply & Pricing Matrix
Long-acting subcutaneous depot formulations are displacing clinic-administered fertility therapies, compressing site-of-care economics while concentrating manufacturing investment in sterile injectable capacity. This format shift simultaneously elevates cold-chain logistics costs and reduces hospital markup capture, redistributing pricing power toward specialty pharmacy networks and integrated delivery systems.
Pricing Analysis
Margin tightening in oral contraceptives reflects generic erosion across established combined formulations, while premium positioning persists in intrauterine hormonal systems and biologic fertility enhancers. Three-tier pricing structure across premium, standard, and economy levels separates originator GnRH modulators from authorized generics and commodity progestins. Price differentiation hinges on FDA priority review status and volume commitments through pharmacy benefit manager consolidated formularies. Self-pay fertility patients exhibit highest price sensitivity, whereas acute postpartum uterotonics face inelastic demand.
Supply Chain Analysis
Regional distribution centers in the United States and Western Europe maintain hub-and-spoke patterns for temperature-controlled fertility biologics, with secondary nodes in São Paulo and Sydney serving Latin American and Asia-Pacific markets. Synthetic progestin active pharmaceutical ingredients concentrate in Zhejiang and Jiangsu provinces of China, plus Gujarat and Maharashtra states of India. Supply chain risk centers on single-source vulnerability for recombinant gonadotropin cell lines. Distribution runs through specialty pharmacy direct-to-patient fulfillment, displacing traditional hospital outpatient dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected injection devices and at-home hormone monitoring platforms are supplanting clinic-based cycle tracking, compressing the traditional infertility center footprint while expanding patient-managed therapy segments.
For Market Incumbents: To counter generic erosion in oral hormonal portfolios, AbbVie and Pfizer should deepen backward integration into peptide API supply and secure exclusive formulary placement through outcomes-based contracting with CVS Caremark and Express Scripts. Priority investment in refrigerated biologic handling infrastructure anchors patient retention.
For New Entrants and Emerging Players: Capture white space in biosimilar recombinant FSH and LH analogs with improved injection devices, targeting Germany and Australia where delayed childbearing expands addressable populations. Direct-to-consumer telehealth prescribing models in TGA-regulated markets offer the most penetrable entry pathway.
For Investors and Strategic Acquirers: Exit pathways concentrate in device-drug combination acquisitions and fertility hormone pipeline bolt-ons. Mid-cap specialists with GnRH modulator platforms and EU MDR-compliant intrauterine systems present optimal target profiles. Watch FDA endometriosis guidance acceleration as inflection signal for novel therapy valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA endometriosis guidance accelerates novel GnRH antagonist submissions through patient-reported outcome endpoints. |
| Regulatory Approval Pathway | EMA centralized marketing authorization elevates evidence requirements for intrauterine hormonal systems entering EU markets. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Zhejiang province reduces import dependency for Chinese fertility formulators. |
| Pipeline Diversification | Selective progesterone receptor modulators address endometriosis pain while avoiding GnRH agonist bone density limitations. |
| Strategic Partnership | Specialty pharmacy alliances with AllianceRx Walgreens Prime embed adherence monitoring for chronic gynecologic therapies. |
Research Methodology
Multi-period observation of formulary placement decisions, API import volumes, and specialty pharmacy dispensing patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and reproductive endocrinology fellowship program directors. Secondary validation drew from FDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation ensured cross-verification.
Segment-weighting applied therapy area, product type, distribution channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated delayed childbearing demographic shifts, ANVISA fast-track utilization rates, and EU MDR transition compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical API supply disruptions, fertility biologic pharmacovigilance actions, and pharmacy benefit manager consolidation effects. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Fertility Services Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Surrogacy Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Contraceptives Market