
 Donor Egg IVF Services Market | 2026-2036
Donor Egg IVF Services Market Size, Share, and Industry Trends Forecast 2026-2036
Donor Egg IVF Services Market Analysis
The EU AI Act is repositioning how European fertility clinics deploy algorithmic donor-recipient matching tools, forcing recalibration of digital patient intake workflows. IVIRMA Global leverages its multi-continental laboratory footprint to sustain cross-border frozen egg logistics. Shady Grove Fertility anchors its competitive stance through high-volume fresh donor egg cycles across the Mid-Atlantic and Northeast corridors. Fairfax EggBank differentiates via proprietary cryopreservation protocols that extend viable storage windows for frozen oocytes.
Donor egg IVF services encompass clinical procedures wherein oocytes from a screened donor undergo in vitro fertilization with partner or donor sperm, with resulting embryos transferred to a recipient uterus; cryopreservation via vitrification at minus 196 degrees Celsius in liquid nitrogen preserves metaphase II spindle integrity for future thaw cycles. The primary purpose addresses diminished ovarian reserve, advanced maternal age, or genetic risk factors where autologous conception proves unviable. Frozen donor eggs command expanding share due to cycle flexibility and reduced synchronization burdens between donor and recipient, while fresh donor eggs retain margin concentration in premium segments demanding maximal blastocyst yield. The over-40 recipient age bracket absorbs disproportionate clinical attention as clinics refine protocols for this cohort's endometrial receptivity challenges.
The FDA governs donor screening and infectious disease testing under 21 CFR Part 1271, while state-level medical boards impose supplementary embryologist certification requirements that shape clinic staffing models. HIPAA constrains cross-clinic data sharing for donor-recipient matching platforms, complicating national registry development. The European Society of Human Reproduction and Embryology guidelines influence protocol standardization across EU member clinics even absent binding force. Stakeholders must monitor whether emerging genetic screening mandates for donor panels will concentrate procurement among vertically integrated egg banks or fragment across independent donor agencies.
Market Dynamics
Frozen donor egg cycles are compressing fresh cycle margins as vitrification protocols mature, while the EU AI Act forces algorithmic recalibration of donor-recipient matching platforms across European clinics.
Growth Catalysts
- 21 CFR Part 1271 Screening Mandates:FDA oversight of infectious disease testing and donor eligibility documentation raises clinical credibility benchmarks, reducing patient hesitation among high-risk demographics.
- Vitrification Protocol Maturation:Ultra-rapid freezing at minus 196 degrees Celsius preserves metaphase II spindle integrity, extending viable storage windows and enabling asynchronous donor-recipient scheduling.
- Spain:Liberal donor anonymity laws and centralized national registries attract cross-border fertility tourism from restrictive jurisdictions, concentrating procedure volumes in Barcelona and Madrid corridors.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryopreservation infrastructure depends on regional industrial gas distributors, with supply disruptions threatening frozen oocyte viability during transport.
- HIPAA Data Fragmentation:Privacy constraints block cross-clinic donor-recipient matching data sharing, preventing national registry development and limiting algorithmic optimization.
- Fresh Cycle Synchronization Burden:Donor and recipient menstrual alignment requires hormonal coordination spanning 4-6 weeks, compressing clinic scheduling throughput during peak demand periods.
Strategic Opportunities
- India:Underpenetrated assisted reproduction infrastructure in tier-2 cities creates whitespace for frozen egg bank networks targeting medical tourism from Middle Eastern and South Asian diaspora populations.
- Genetic Screening Integration:Expanded carrier panel testing converges with polygenic risk scoring, enabling clinics to market enhanced donor selection premiums to risk-averse recipients over 40.
- Direct-to-Patient Cryostorage Subscriptions:Monthly billing models for long-term oocyte preservation bypass traditional clinic intermediaries, capturing recurring revenue from fertility preservation deferrals.
Industry Challenges
- Embryologist Certification Bottlenecks:State-level medical boards impose supplementary laboratory personnel requirements, constraining clinic expansion velocity in high-demand metropolitan corridors.
- Cross-Border Cold Chain Integrity:Frozen oocyte logistics spanning multiple customs jurisdictions expose shipments to temperature excursion risks during extended ground transport segments.
- ESHR Guideline Harmonization:Non-binding European protocol recommendations create compliance ambiguity across EU member clinics, delaying standardized quality benchmarking implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Donor Egg IVF Services Market |
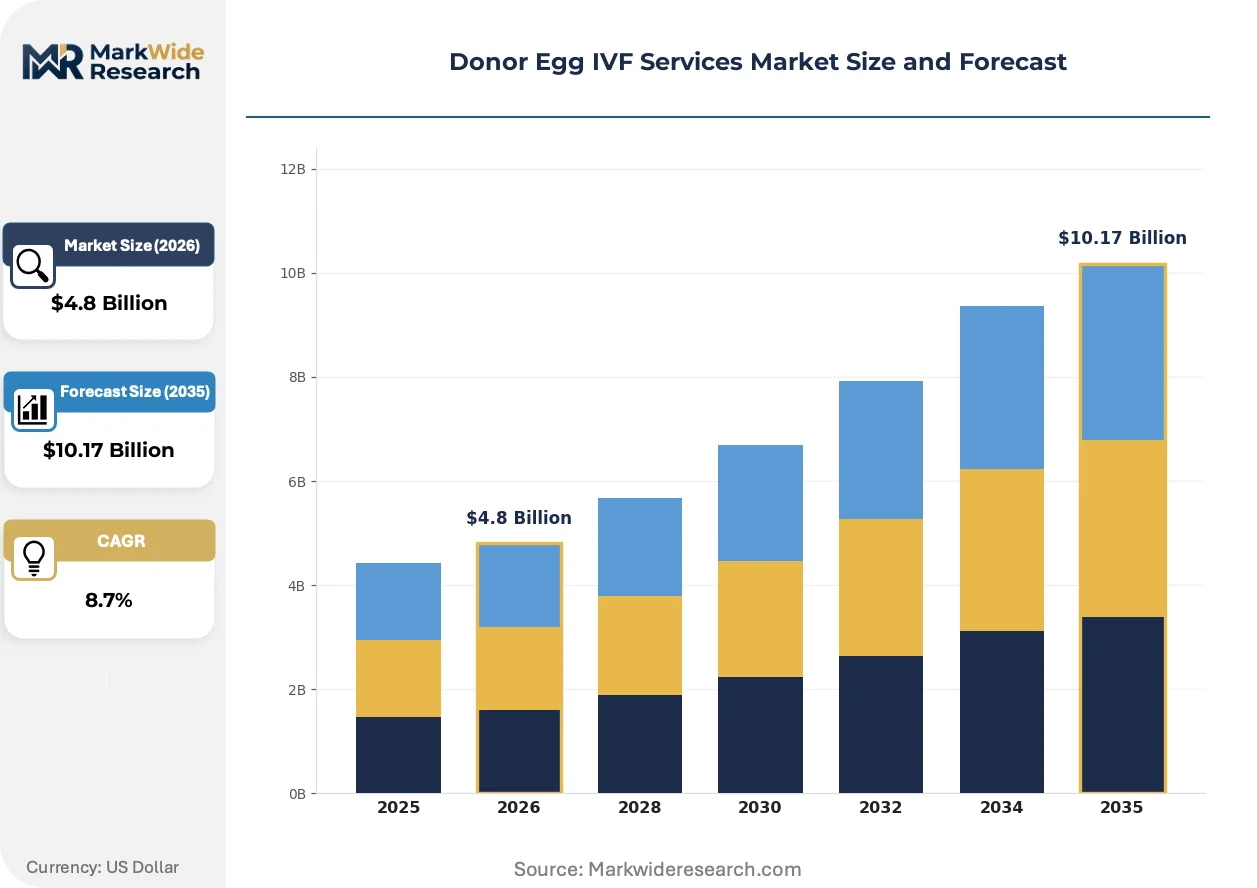
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fresh Donor Eggs, Frozen Donor Eggs, Egg Share Program, Gestational Carrier Recipient Age Group: Under 30, 30-35, 36-40, Over 40 Donor Selection: Anonymity, Known Donor, Open Donation, Family Donor Success Rate: High, Moderate, Low, Varies by Age |
| Companies Covered | Boston IVF, Shady Grove Fertility, Donor Egg Bank USA, Fairfax EggBank, IVIRMA Global, Instituto Bernabeu, California Fertility Partners, Fertility Centers of Illinois, Beacon CARE Fertility Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Donor Egg IVF Services Market Emerging Trajectories
Algorithmic matching tools and cryopreservation advances are redistributing clinical workflows away from centralized fresh-cycle hubs toward distributed frozen egg networks.
Time-lapse embryo imaging combined with artificial intelligence grading is decentralizing blastocyst selection authority from senior embryologists to automated scoring systems. Mid-sized fertility networks in the United States are adopting these platforms at accelerating pace. The technology is compressing inter-laboratory variability in embryo quality assessment.
The EU AI Act's risk classification framework is reclassifying donor-recipient matching algorithms as high-risk medical devices, mandating conformity assessments and post-market surveillance. European fertility clinics must now document algorithmic decision trails for audit. Spain and Denmark clinics are front-loading compliance investments ahead of enforcement deadlines.
Recipient self-education through online outcome databases is shortening clinic evaluation cycles from months to weeks. Prospective patients now cross-reference CDC success rates and SART registry data before initial consultations. This behavior concentrates demand among high-volume centers with transparent reporting histories, particularly in California and New York metropolitan clusters.
Donor Egg IVF Services Market Segmentation
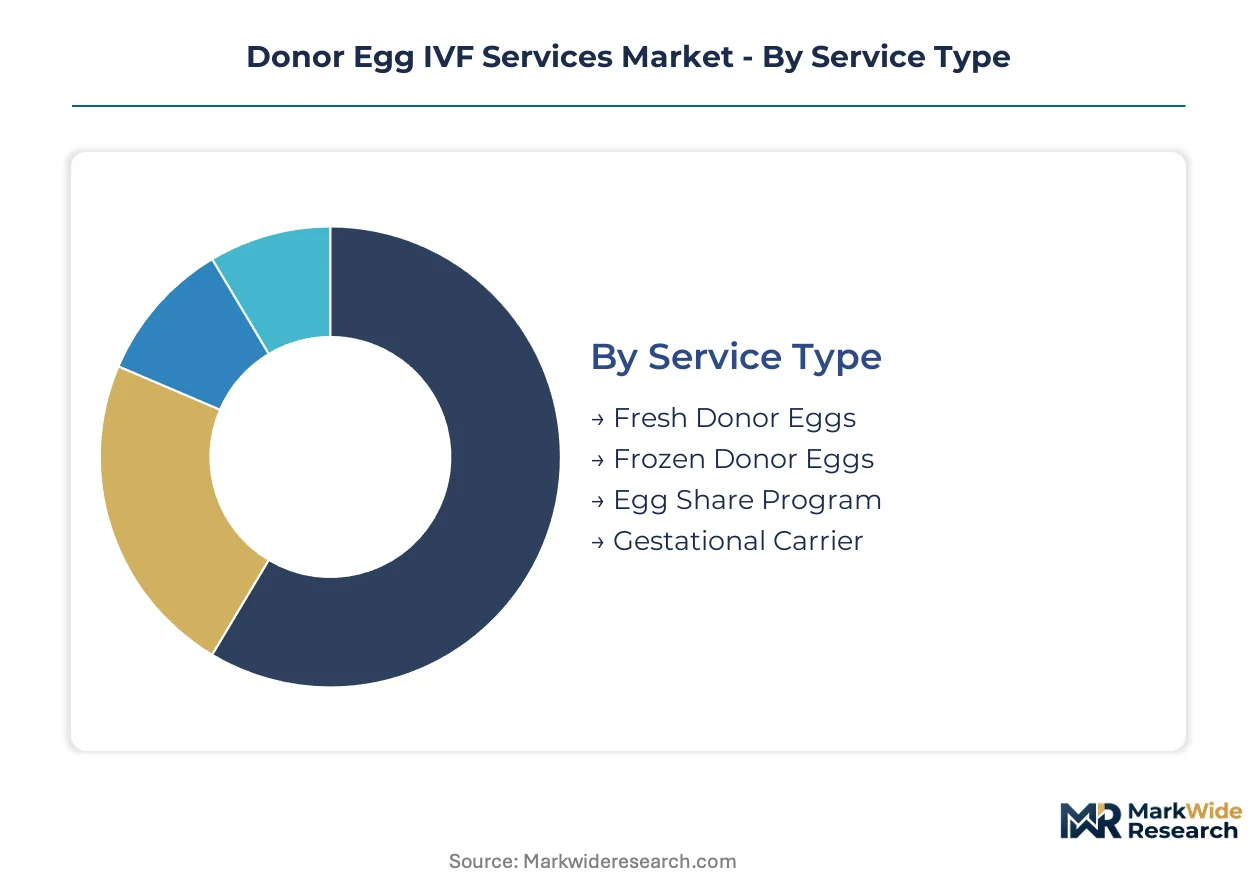
Service configuration in donor egg IVF determines regulatory pathway complexity, cryopreservation infrastructure requirements, and synchronization protocols between donor and recipient cycles. Segment selection directly shapes clinic staffing models and laboratory capital allocation decisions.
Service Type:
FDA 21 CFR Part 1271 mandates infectious disease screening for all donor gametes, though frozen egg cycles face additional cryostorage facility inspections while fresh cycles trigger heightened donor synchronization documentation.
- Frozen Donor Eggs:Vitrification at minus 196 degrees Celsius preserves metaphase II spindle integrity, enabling asynchronous scheduling that reduces clinic coordination overhead. Demand concentrates in United States metropolitan corridors where large network fertility centers command significant procedure volumes, driven by cycle flexibility and reduced synchronization burdens.
- Fresh Donor Eggs:Maximal blastocyst yield potential attracts premium-segment recipients prioritizing single-cycle success probability over convenience. Margin concentration persists in Mid-Atlantic and Northeast corridors where high-volume centers sustain donor recruitment pools.
- Egg Share Program:Cost-sharing arrangements split retrieved oocytes between donor and recipient, attracting price-sensitive patients in Spain's fertility tourism corridors.
- Gestational Carrier:Third-party uterine transfer services require supplemental legal and psychological screening protocols beyond standard gamete handling.
Leading the category by volume: Frozen Donor Eggs. Expanding most quickly: Egg Share Program.
Recipient Age Group:
Endometrial receptivity protocols and hormonal priming regimens vary substantially across age brackets, with over-40 protocols demanding specialized laboratory expertise and extended preparation timelines.
- Over 40:Diminished ovarian reserve and altered endometrial receptivity necessitate extended estrogen priming and specialized embryo transfer timing. Spain and United States clinics absorb disproportionate clinical attention for this cohort as rising utilization among women over 40 seeking fertility preservation broadens the patient base.
- 36-40:Perimenopausal transition markers trigger modified stimulation protocols and heightened genetic screening recommendations.
- 30-35:Optimal autologous fertility windows reduce donor egg dependency, though genetic risk factors sustain niche demand.
- Under 30:Premature ovarian failure and oncofertility preservation drive limited but high-complexity case volumes.
Dominant revenue concentration: Over 40. Steepest expansion trajectory: 36-40.
Donor Selection:
Privacy frameworks and identity disclosure protocols fragment procurement channels across jurisdictions, with anonymity laws directly shaping cross-border patient flows.
- Anonymity:Shielded donor identity under Spain's liberal anonymity laws attracts cross-border fertility tourism from restrictive jurisdictions, concentrating procedure volumes in Barcelona and Madrid corridors.
- Open Donation:Future contact provisions between donor and offspring require extended legal documentation and counseling infrastructure.
- Known Donor:Pre-existing relationship protocols trigger distinct psychological screening and legal clearance workflows.
- Family Donor:Related-party gamete transfer introduces genetic counseling complexity around consanguinity risk assessment.
Category leadership by volume: Anonymity. Gaining share fastest: Open Donation.
Success Rate:
Outcome transparency requirements from CDC and SART registries stratify clinic positioning, with high-success-rate centers capturing disproportionate patient evaluation traffic.
- High:Benchmark live birth rates per transfer attract recipient self-education through online outcome databases, shortening clinic evaluation cycles from months to weeks. Demand concentrates among high-volume centers with transparent reporting histories in California and New York metropolitan clusters.
- Moderate:Mid-tier outcomes compete on accessibility and reduced wait times rather than premium positioning.
- Low:Suboptimal rates typically reflect complex patient demographics or newer laboratory establishments building experience curves.
- Varies by Age:Age-stratified reporting aligns with CDC registry requirements but complicates direct clinic comparison for recipients.
Volume concentration: High. Climbing the fastest: Varies by Age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the highest procedure volumes for donor egg IVF services, while Spain and Denmark attract substantial cross-border patient flows through regulatory arbitrage on donor anonymity. Production of clinical capacity concentrates in metropolitan clusters with established cryopreservation infrastructure and high-volume laboratory networks.
United States
Large network fertility centers in California and New York metropolitan clusters command significant procedure volumes through transparent CDC and SART registry reporting. FDA oversight under 21 CFR Part 1271 governs donor screening and infectious disease testing protocols. The Mid-Atlantic and Northeast corridors sustain premium fresh donor egg cycles through concentrated donor recruitment pools.
Spain
Liberal donor anonymity laws attract cross-border fertility tourism from restrictive European jurisdictions, concentrating demand in Barcelona and Madrid corridors. The national health system supports centralized donor registries that streamline matching workflows. Instituto Bernabeu anchors clinical capacity in the Alicante-Valencia axis through high-volume egg donation programs.
Denmark
Progressive assisted reproduction legislation and established sperm bank infrastructure extend into donor egg services, capturing Scandinavian and German patient flows. The country's national pharmaceutical regulator maintains harmonized standards with EU tissue directive implementations. Copenhagen and Aarhus clusters specialize in cryopreserved oocyte logistics for Nordic cross-border demand.
United Kingdom
Human Fertilisation and Embryology Authority licensing requirements create compliance barriers that concentrate market share among established clinic groups. Beacon CARE Fertility Ltd. operates across multiple UK metropolitan centers under centralized quality frameworks. London and Manchester corridors absorb the highest domestic procedure volumes through HFEA-inspected laboratory networks.
India
Underpenetrated assisted reproduction infrastructure in tier-2 cities creates whitespace for frozen egg bank networks targeting Middle Eastern and South Asian diaspora medical tourism. The country's national pharmaceutical regulator oversees clinic licensing through assisted reproductive technology bills. Maharashtra and Karnataka states concentrate initial foreign patient acquisition through Mumbai and Bangalore international connectivity.
Donor Egg IVF Services Market Vendor Landscape
The competitive structure tilts toward multi-clinic network operators with integrated laboratory footprints. Consolidation pressures favor scale-driven players capable of sustaining cross-border frozen egg logistics and centralized donor recruitment operations. Three archetypes dominate: high-volume fresh-cycle hubs, distributed frozen egg bank networks, and cross-border fertility tourism specialists. Dominant competitive moves include geographic expansion through clinic acquisitions and backward integration into donor agency operations.
Among US-based network operators, Shady Grove Fertility exemplifies the high-volume fresh-cycle archetype across Mid-Atlantic and Northeast corridors, while Boston IVF occupies a position within academic-affiliated fertility center tier. IVIRMA Global represents the multi-continental laboratory footprint model, anchoring cross-border frozen oocyte logistics through Spanish and US operational nodes.
| Leading Market Players |
|---|
| Boston IVF |
| Shady Grove Fertility |
| Donor Egg Bank USA |
| Fairfax EggBank |
| IVIRMA Global |
| Instituto Bernabeu |
| California Fertility Partners |
| Fertility Centers of Illinois |
| Beacon CARE Fertility Ltd. |
| Others |
Supply Flow & Price Mechanics
Vitrification protocol maturation simultaneously compresses per-cycle cost economics and concentrates procurement leverage among cryostorage-integrated networks. Frozen donor egg adoption redistributes margin capture from fresh-cycle coordination fees toward liquid nitrogen infrastructure scale economies.
Pricing Analysis
Margin tightening in fresh donor egg cycles reflects donor recruitment cost inflation and synchronization overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by blastocyst yield guarantee and genetic screening depth. Price differentiation hinges on CDC success rate tiering and geographic proximity to high-volume laboratory clusters. Price-sensitive patients gravitate toward egg share programs and frozen egg bank subscriptions, while premium segments absorb fresh cycle premiums for maximal single-transfer success probability.
Supply Chain Analysis
FDA 21 CFR Part 1271 qualification gates donor agency procurement and cryostorage facility licensing, fragmenting supplier bases across state jurisdictions. Liquid nitrogen supply draws from regional industrial gas distributors in the United States, Spain, and Denmark, with cross-border cold chain logistics resting on specialized reproductive tissue couriers. Single-source vulnerability concentrates in liquid nitrogen transport during extended ground segments. Distribution runs through fertility clinic networks with integrated embryology laboratories and satellite cryostorage nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 1271 compliance costs erect barrier-to-entry moats that favor capitalized incumbents with established donor screening infrastructure and quality management systems.
For Market Incumbents: Acquire frozen egg bank networks and cryostorage facilities to anchor cross-border logistics capabilities. Consolidate donor agency relationships to secure oocyte supply pools against independent egg bank entrants. Defend against algorithmic matching platform displacement by embedding AI-driven recipient counseling into intake workflows. For New Entrants and Emerging Players: Launch via direct-to-patient cryostorage subscription models that bypass traditional clinic intermediaries. Target tier-2 Indian cities with underpenetrated assisted reproduction infrastructure for medical tourism positioning. Prioritize genetic screening integration as a service differentiator for risk-averse recipients over 40. For Investors and Strategic Acquirers: Exit pathways concentrate in multi-clinic network operators with integrated laboratory footprints and established CDC/SART reporting histories. Long-term viability favors scale-driven players capable of sustaining cross-border frozen egg logistics and centralized donor recruitment. Monitor EU AI Act enforcement deadlines as inflection indicator for algorithmic matching platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Donor Agency Operations | Captive oocyte supply pools reduce procurement cost volatility for high-volume fresh cycle networks. |
| Cryostorage Facility Network Expansion | Liquid nitrogen infrastructure scale economies compress per-cycle preservation costs across metropolitan clusters. |
| Algorithmic Matching Platform Deployment | EU AI Act compliance investments reposition European clinics ahead of high-risk medical device classification enforcement. |
| Genetic Screening Panel Expansion | Polygenic risk scoring integration commands premium pricing from risk-averse recipient segments over 40. |
| Cross-Border Fertility Tourism Partnership | Spain's liberal donor anonymity laws attract patient flows from restrictive European jurisdictions through Barcelona and Madrid corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with reproductive endocrinologists, embryology laboratory directors, donor agency coordinators, and fertility clinic operations managers. CDC success rate registries, SART clinic reports, FDA 21 CFR Part 1271 guidance documents, and ESHRE protocol guidelines furnished validation benchmarks. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across service type segmentation, recipient age cohorts, donor selection protocols, and regional regulatory clusters shaped the analytical framework. CAGRs derived from logistic diffusion modeling of frozen versus fresh cycle adoption curves, calibrated against vitrification protocol maturation timelines and cross-border patient flow elasticity. Forecast inputs incorporated HIPAA data fragmentation constraints and EU AI Act compliance cost trajectories.
Regulatory enforcement timing, liquid nitrogen supply disruptions, and genetic screening mandate expansion are the dominant revision risks to modeled projections. Forecasts reflect assumptions around cryopreservation technology diffusion and donor anonymity law stability. A model refresh is warranted upon material change in FDA tissue directive enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Gamete Preservation Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Contraceptives Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Surrogacy Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Fertility Treatments Market