
 Latin America Manufactured Homes Market | 2026-2036
Latin America Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Manufactured Homes Market Foresight
Brazil's Southeast corridor is reshaping regional capacity for panelized and modular output. Clayton Homes leverages its brand strength across direct-to-consumer channels in Mexico and Central America. Cavco Industries anchors production scale through factory-direct operations that bypass traditional dealer markups. Casas Brazil dominates local supply with in-house production of steel-frame components tailored to tropical climate loads.
Manufactured homes in Latin America comprise prefabricated dwelling units built in controlled factory environments, typically employing steel or wood framing with insulated wall panels engineered to resist seismic and humidity stress, then transported to sites for foundation anchoring and utility connection. Single-section units occupy the volume base for first-time home buyers across rural and peri-urban markets, while modular units capture expanding margin pools from developer-led multi-unit projects requiring faster completion cycles. Emergency housing applications sustain demand spikes following climate events, with governments procuring multi-section configurations through direct sales channels rather than retail networks.
Brazil's ABNT technical standards and Mexico's CONAVI compliance framework govern structural safety and energy efficiency, shaping product specifications that manufacturers must satisfy for market access. Argentina's IRAM certification adds another layer for cross-border trade, particularly for steel-frame suppliers serving Mercosur corridors. Stakeholders must monitor how municipal zoning reforms in Colombian and Chilean cities alter site preparation requirements and distribution channel economics.
Market Dynamics
Steel-frame fabrication advances from Argentine suppliers are compressing build timelines and redrawing competitive boundaries across the Latin America manufactured homes market.
Growth Catalysts
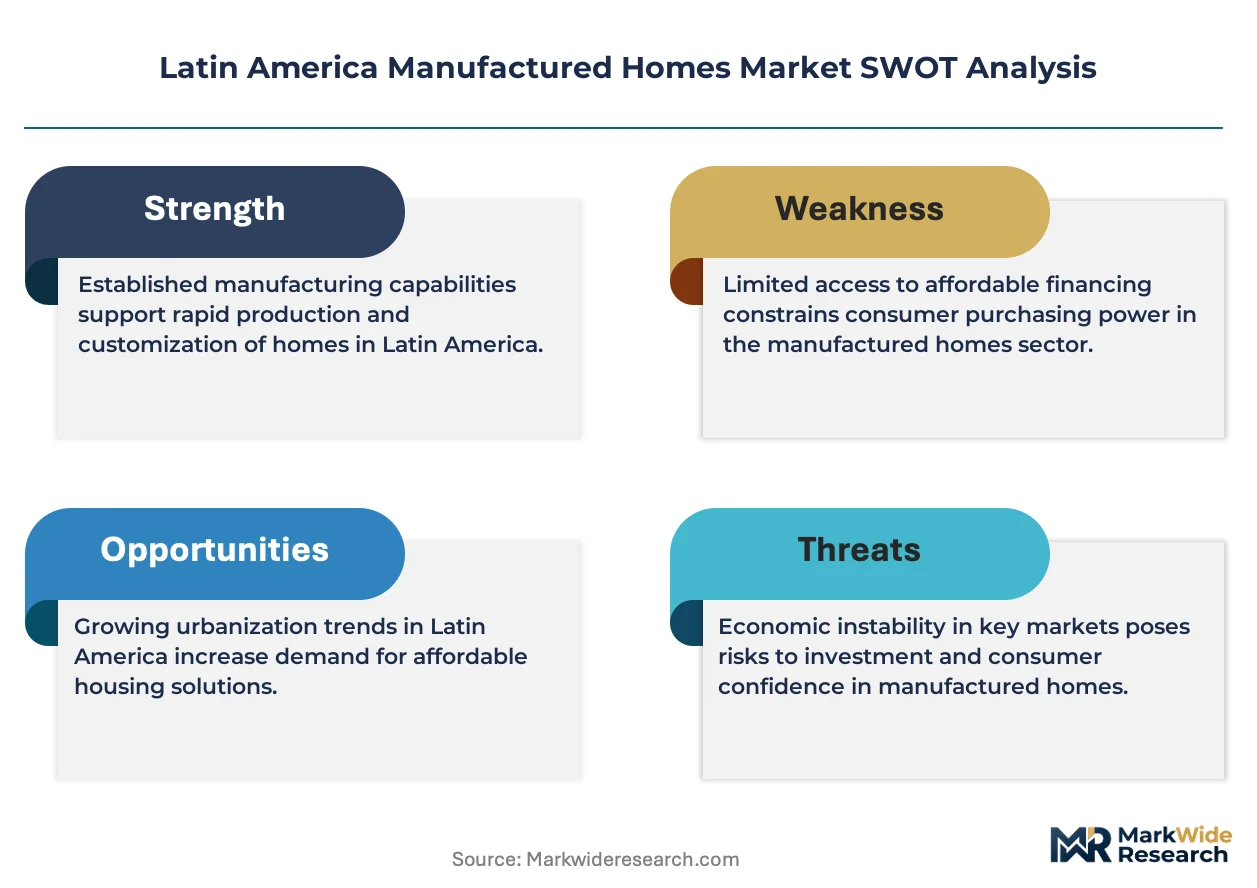
- ABNT Technical Standards Harmonization:Brazil's national standards body has streamlined certification pathways for modular steel structures, reducing factory-to-site approval cycles for manufacturers serving peri-urban zones.
- CONAVI Compliance Framework Expansion:Mexico's housing commission has relaxed zoning codes for modular construction in metropolitan peripheries, opening direct-to-consumer channels previously blocked by municipal restrictions.
- Seismic-Resistant Panel Engineering:Argentine IRAM-certified steel-frame systems now withstand tropical humidity loads, enabling cross-border trade into Mercosur corridors previously served only by wood-framed alternatives.
Market Restraints
- Steel Input Cost Volatility:Argentine mill supply interruptions transmit directly to frame fabrication costs, compressing margins for manufacturers without captive rolling capacity.
- Cross-Border Certification Friction:IRAM, ABNT, and CONAVI technical standards lack mutual recognition, forcing redundant testing for suppliers serving multiple Latin American markets.
- Site Preparation Labor Bottlenecks:Foundation anchoring and utility connection skills concentrate in São Paulo state and Mexico City metro zones, leaving interior markets underserved.
Strategic Opportunities
- Colombian Zoning Reform Pipeline:Bogotá and Medellín municipal governments are piloting modular construction incentives for informal settlement upgrading, creating first-mover access for certified suppliers.
- Climate Event Procurement Channels:Emergency housing applications are shifting from retail networks to direct government sales, favoring manufacturers with multi-section configuration capabilities.
- Factory-Direct Channel Disintermediation:Bypassing traditional dealer markups through captive distribution is capturing margin pools from developer-led multi-unit projects requiring accelerated completion cycles.
Industry Challenges
- Certification Timeline Compression:ABNT structural safety and energy efficiency testing cycles lag factory output capacity, creating inventory holding costs for high-volume producers.
- Foundation Integration Complexity:Seismic anchoring requirements vary unstandardized across Brazilian states and Mexican municipalities, forcing customized engineering for each deployment cluster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Manufactured Homes Market |
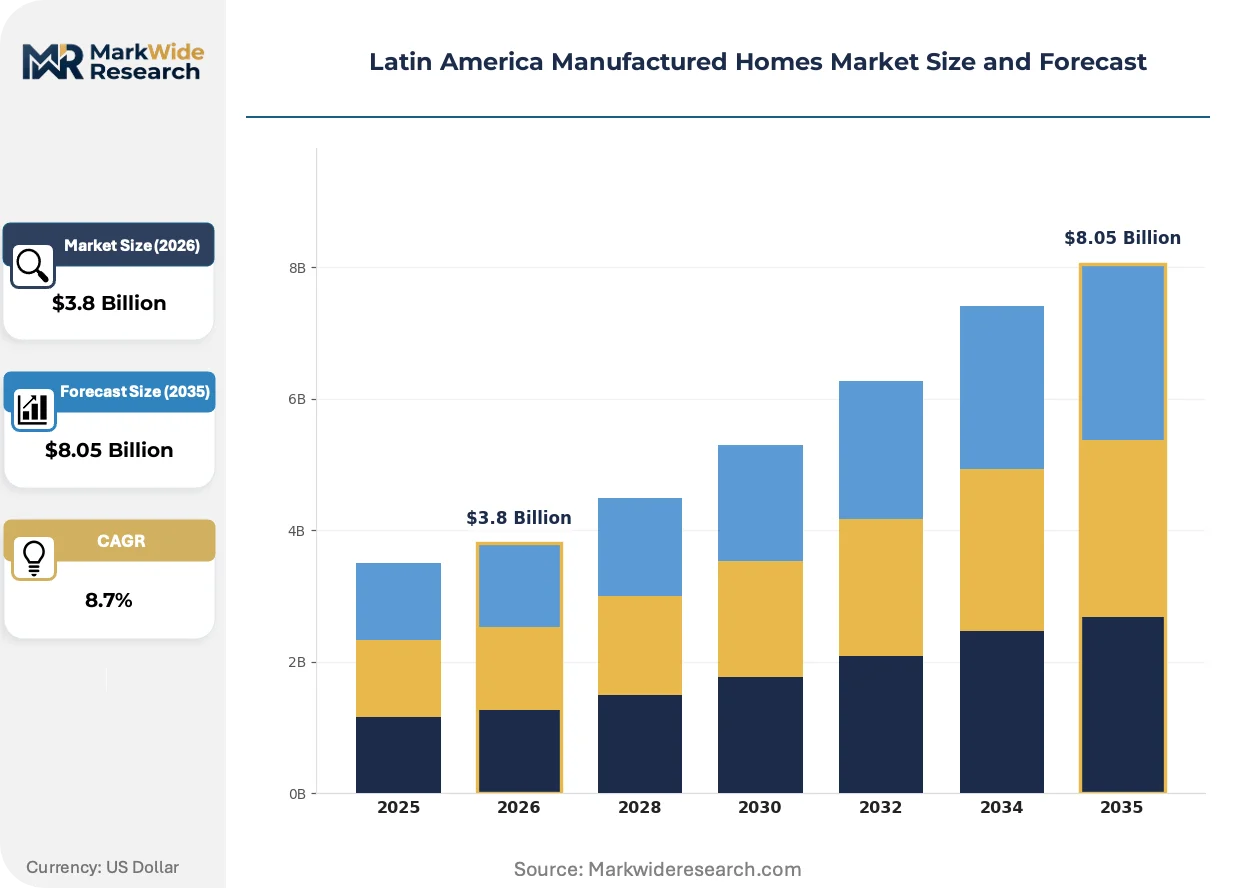
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Tiny Homes, Modular Units Application: Residential, Commercial, Recreational, Emergency Housing Customer Type: Home Buyers, Developers, Investors, Rental Agencies Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Dealers |
| Companies Covered | Brasmerc Group companies, Casas Brazil, Clayton Homes, Cavco Industries, CC's Modular & Manufactured Homes, Columbia Manufactured Homes, Home Nation, HomeMax, Titan Factory Direct, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Manufactured Homes Market Shifts & Advancements
Factory automation and digital design-to-fabrication workflows are collapsing traditional construction timelines and reconfiguring how housing units reach end buyers across Latin American markets.
Light-gauge steel roll-forming systems integrated with BIM design software are rendering obsolete manual cutting and welding processes that previously dominated frame fabrication. Developer-led multi-unit projects in São Paulo state are adopting these systems at accelerating rates. The technology is rendering obsolete the six-month traditional construction cycles that previously constrained affordable housing delivery.
CONAVI's updated compliance framework for energy-efficient envelope performance is mandating insulated panel specifications that exceed previous thermal resistance thresholds. Manufacturers must retool production lines to meet these standards or face market exclusion from subsidized housing programs. Low-income first-time buyers in Mexico's peri-urban zones are most affected, as certified units command pricing premiums over uncertified alternatives.
Direct-to-consumer digital channels are displacing traditional dealer networks for single-section unit sales. Factory-direct operations now bypass markup layers that previously absorbed fifteen to twenty percent of end pricing. This channel compression is most visible in Brazil's Southeast corridor, where São Paulo state infrastructure programs aggregate sufficient volume to justify captive distribution investments.
Latin America Manufactured Homes Market Segmentation
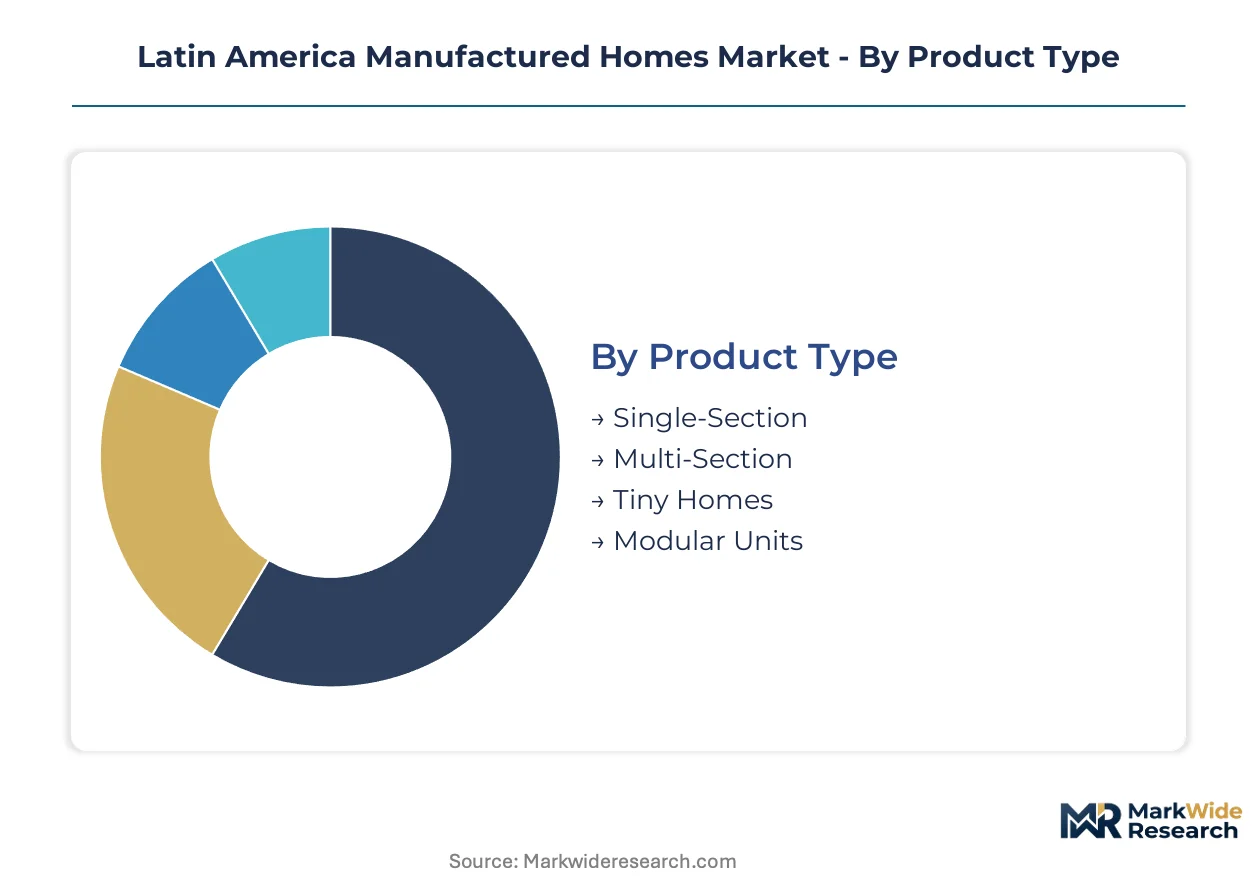
Manufactured homes in Latin America serve distinct buyer profiles and deployment contexts that reshape factory output specifications and channel economics. Segmentation reveals where steel-frame fabrication investments concentrate and which certification pathways unlock volume.
Product Type:
Mature configurations dominate peri-urban first-time buyer markets while emerging formats capture developer-led multi-unit projects.
- Single-Section:Compact steel or wood-framed units engineered for rapid foundation anchoring and minimal site preparation. Demand concentrates across Brazil's rural Northeast and Mexico's metropolitan peripheries where low-income buyers prioritize entry affordability over expansion capacity.
- Multi-Section:Configurable dwelling assemblies transported in separate modules for on-site joining. São Paulo state infrastructure programs and Colombian informal settlement upgrading initiatives drive procurement through direct government sales channels rather than retail networks.
- Tiny Homes:Sub-400 square foot units optimized for recreational land use and remote worker migration patterns.
- Modular Units:Factory-complete volumetric segments with MEP rough-in for stacked multi-story configurations.
Single-Section handles the majority of throughput; Modular Units are expanding most quickly on share.
Application:
Cost tier stratification separates subsidized mass housing from premium recreational deployments.
- Residential:Permanent primary dwellings for owner-occupiers across peri-urban zones. Brazil's ABNT certification requirements and Mexico's CONAVI compliance framework govern structural safety specifications that manufacturers must satisfy for subsidized program access.
- Emergency Housing:Rapid-deployment configurations procured by governments following climate events. Argentine IRAM-certified steel-frame systems now withstand tropical humidity loads, enabling cross-border trade into Mercosur corridors previously blocked by material incompatibility.
- Commercial:Workforce accommodation and site office modules for mining and energy projects.
- Recreational:Seasonal and vacation property applications with lower structural load requirements.
Residential absorbs the dominant share of factory capacity; Emergency Housing is gaining share fastest as climate procurement channels mature.
Customer Type:
Volume concentration sits with institutional buyers while margin capture favors direct-to-consumer channels.
- Home Buyers:Individual first-time purchasers in peri-urban zones seeking entry-level ownership. Factory-direct operations now bypass dealer markups that previously absorbed fifteen to twenty percent of end pricing, compressing affordability gaps in Brazil's Southeast corridor.
- Developers:Multi-unit project sponsors requiring accelerated completion cycles. Light-gauge steel roll-forming systems integrated with BIM software are collapsing traditional construction timelines for developer-led deployments in São Paulo state.
- Investors:Portfolio acquirers targeting rental yield in high-migration corridors.
- Rental Agencies:Institutional landlords deploying manufactured units for workforce housing.
Home Buyers represent the volume anchor; Developers are climbing the fastest on procurement scale.
Distribution Channel:
Supply concentration favors captive factory networks over fragmented dealer infrastructure.
- Direct Sales:Factory-owned channels bypassing intermediary markups for developer and government contracts. São Paulo state infrastructure programs aggregate sufficient volume to justify captive distribution investments that traditional dealer networks cannot match.
- Retail Outlets:Physical showrooms with model unit display and financing facilitation. Mexico's CONAVI compliance framework expansion into metropolitan peripheries is opening retail access previously blocked by municipal zoning restrictions.
- Online Platforms:Digital configuration and order placement for standardized single-section units.
- Dealers:Independent third-party networks with local site preparation and installation coordination.
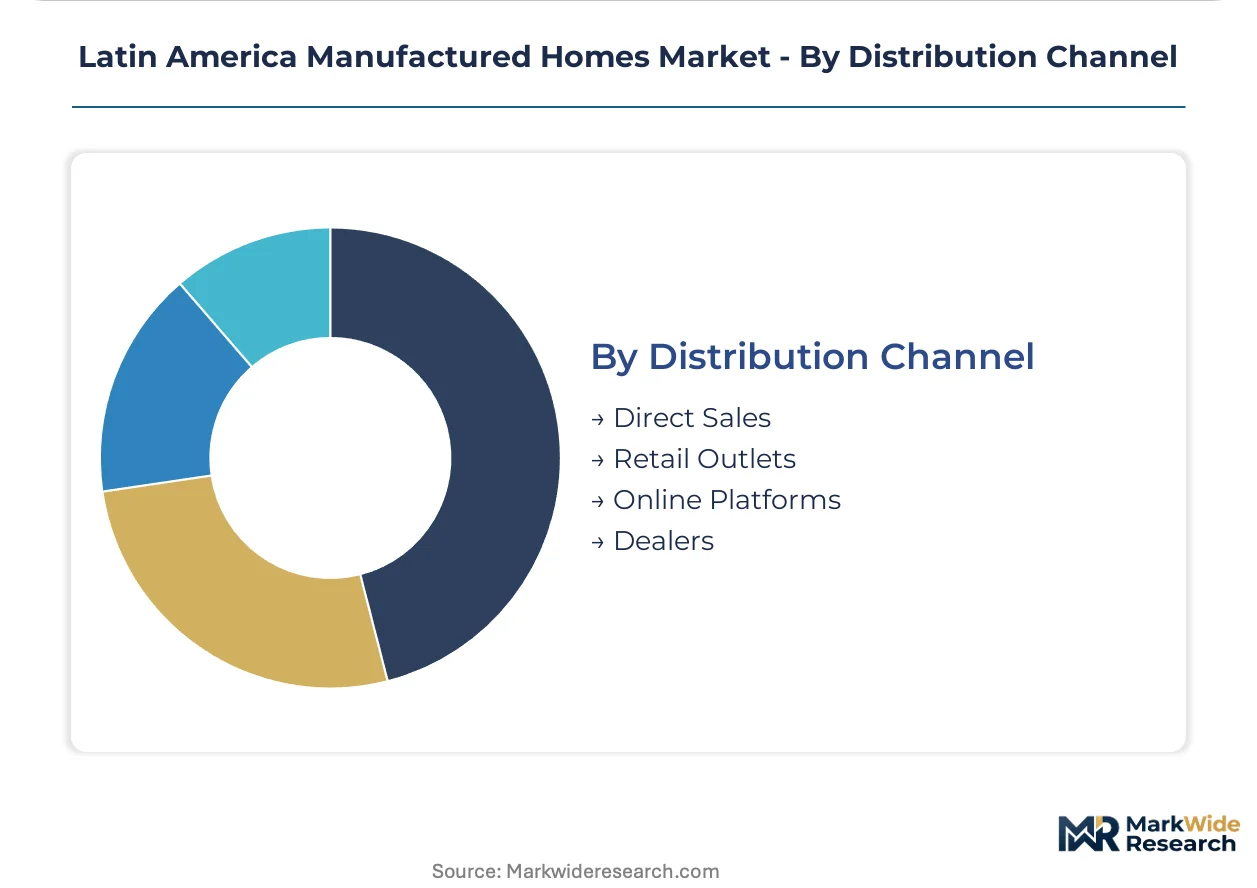
Direct Sales commands the throughput majority; Online Platforms are expanding most rapidly on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ABNT technical standards harmonization anchors Brazil's regulatory framework for modular steel structures, while CONAVI compliance frameworks govern Mexico's metropolitan periphery expansion. Argentine IRAM certification enables cross-border trade into Mercosur corridors. Colombia and Chile are piloting municipal zoning reforms that alter site preparation requirements.
Brazil
Peri-urban low-income home buyers in São Paulo state's Southeast corridor drive single-section unit demand through subsidized infrastructure programs. ABNT streamlined certification pathways reduce factory-to-site approval cycles for manufacturers serving these zones. Steel-frame fabrication clusters concentrate in São Paulo state's industrial belt, where panelized output scales to meet government procurement volumes.
Mexico
Metropolitan periphery zoning relaxations open direct-to-consumer channels previously blocked by municipal restrictions in Mexico City metro zones. CONAVI compliance framework expansion mandates energy-efficient envelope performance for subsidized program access. Factory-direct operations bypass traditional dealer markups in Nuevo León and Jalisco production corridors.
Argentina
Steel-frame fabrication advances from Buenos Aires province suppliers compress build timelines for cross-border Mercosur trade. IRAM-certified systems now withstand tropical humidity loads, enabling material compatibility with Brazilian and Paraguayan deployment contexts. Córdoba industrial clusters anchor rolling capacity that buffers mill supply interruptions.
Colombia
Bogotá and Medellín municipal governments pilot modular construction incentives for informal settlement upgrading initiatives. National housing regulators are drafting certification alignment with regional standards to reduce redundant testing burdens. Antioquia department manufacturing zones position for first-mover access as zoning reforms mature.
Chile
Santiago metropolitan zone developers procure multi-section configurations for accelerated completion cycles in high-migration corridors. Municipal zoning reforms in Valparaíso and Biobío regions alter foundation anchoring requirements for seismic-resistant panel engineering. Concepción industrial clusters supply steel-frame components adapted to coastal humidity stress.
Latin America Manufactured Homes Market Competitive Landscape
Capability concentration sits with regional fabricators commanding local certification pathways; scale advantage sits with factory-direct operators aggregating government procurement volumes. The market structures around three tiers: multinational manufacturers leveraging brand recognition, domestic specialists with captive steel-frame production, and emergency housing contractors serving climate event procurement channels. Competitive moves center on backward integration into rolling capacity and channel disintermediation bypassing dealer markups.
Among Brazil-based fabricators, Casas Brazil exemplifies the domestic specialist archetype with in-house production of climate-adapted components. Clayton Homes and Cavco Industries represent multinational manufacturers leveraging direct-to-consumer channels across Mexico and Central America. These three anchors illustrate how certification control and captive distribution investments separate margin capture from volume throughput.
| Leading Market Players |
|---|
| Brasmerc Group companies |
| Casas Brazil |
| Clayton Homes |
| Cavco Industries |
| CC's Modular & Manufactured Homes |
| Columbia Manufactured Homes |
| Home Nation |
| HomeMax |
| Titan Factory Direct |
| Others |
Supply & Pricing Matrix
Santos Port logistics corridors transmit steel coil freight cost volatility directly to São Paulo state fabricators, concentrating pricing power among mill-proximate producers while forcing peripheral suppliers into aggressive cost absorption or exit. This freight-cost gradient splits the market between ABNT-certified premium tiers and uncertified economy alternatives, with buyer sensitivity sharpest among peri-urban first-time purchasers.
Pricing Analysis
Geographic price spreads between Brazil's Southeast corridor and Mexico's metropolitan peripheries exceed fifteen percent on equivalent single-section units, driven by divergent certification cost burdens and steel input access. Three-tier pricing structure across premium ABNT-certified, standard CONAVI-compliant, and economy non-certified levels anchors transactional models, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Argentine mill supply interruptions transmitting to frame fabrication costs, compressing margins for manufacturers without captive rolling capacity. Peri-urban low-income buyers exhibit highest price sensitivity, while developer-led multi-unit projects absorb premiums for accelerated completion cycles.
Supply Chain Analysis
Contract manufacturing concentration sits with Buenos Aires province steel-frame specialists and São Paulo state panelized output clusters, with Córdoba industrial zones buffering mill supply volatility through captive rolling investments. Geographic supply concentration centers on Brazil, Argentina, and Mexico, with cross-border Mercosur trade flows dependent on IRAM-ABNT certification alignment. Raw material dependencies hinge on hot-rolled steel coil, polyurethane insulation foam, and seismic-grade anchoring hardware. Single-source vulnerability concentrates in Argentine mill supply for Mercosur frame fabrication. Distribution runs through factory-direct channels for government and developer procurement, with retail dealer networks retaining single-section consumer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-to-foundation integration capability represents the scarce asset separating margin capture from commodity throughput, with certification timeline compression and site preparation labor coordination as binding constraints. Manufacturers lacking in-house steel-frame production or direct municipal relationships face structural disadvantage.
For Market Incumbents: Build certification moats through ABNT-CONAVI dual compliance investments that block cross-border entrants from subsidized procurement channels. Anchor capacity additions in São Paulo state's industrial belt to capture infrastructure program volumes. Defend against Argentine mill supply interruptions through backward integration into rolling capacity or long-term offtake agreements with Córdoba clusters. For New Entrants and Emerging Players: Colombia's Antioquia department manufacturing zones offer underpenetrated access as Bogotá and Medellín zoning reforms mature, with first-mover positioning in informal settlement upgrading procurement. Target emergency housing direct government sales channels where retail network presence is not required. Lead with IRAM-certified steel-frame systems adapted to tropical humidity loads as differentiated entry angle. For Investors and Strategic Acquirers: Domestic specialists with captive climate-adapted component production and municipal zoning relationships represent priority acquisition archetypes. Long-term viability hinges on factory-direct channel control and certification pathway ownership rather than volume scale alone. Monitor CONAVI compliance framework expansion pace and Colombian national housing regulator certification alignment progress as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Córdoba and São Paulo state captive mill investments buffer Argentine supply interruptions and compress frame fabrication costs. |
| Dual Certification Pathway Investment | ABNT-CONAVI-IRAM alignment unlocks cross-border Mercosur trade and blocks single-standard competitors from government procurement. |
| Factory-Direct Channel Expansion | São Paulo state infrastructure program aggregation justifies captive distribution bypassing fifteen to twenty percent dealer markups. |
| Climate-Adapted Panel Engineering | Seismic-resistant envelope performance exceeding CONAVI thermal thresholds commands pricing premiums in subsidized housing programs. |
| Digital Design-to-Fabrication Workflow | BIM-integrated light-gauge steel roll-forming collapses six-month traditional construction cycles for developer-led multi-unit projects. |
Research Methodology
A standing panel of factory operations directors, municipal housing program administrators, steel procurement managers, and CONAVI compliance officers provided ongoing calibration across the primary research phase. Secondary validation drew from ABNT technical standard filings, CONAVI subsidized housing program disclosures, Argentine IRAM certification registries, and customs trade data on steel coil cross-border flows. Bottom-up unit shipment estimates from São Paulo state industrial clusters were triangulated against top-down government procurement budget allocations.
Scenario-bracketing framed low, base, and high case trajectories across the projection horizon, with segmentation dimensions spanning product type, application, customer archetype, and distribution channel. CAGRs were derived from installed base growth, replacement demand cycles, and penetration rate assumptions by peri-urban zone. Forecast inputs incorporated steel input cost elasticity, certification timeline compression rates, and municipal zoning reform implementation pace.
Practitioners should monitor Argentine mill supply stability, Colombian regulatory alignment progress, and climate event procurement channel maturation for early signals of forecast deviation. Quarterly review of ABNT certification backlog duration and CONAVI compliance framework expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Bathroom Remodeling Market
Residential Construction
Europe Residential Construction Market
Residential Construction
North America Residential Construction Market
Residential Construction
Germany Residential Construction Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Residential Construction Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Global Manufactured Homes Market