
 Germany Prefabricated Houses Market | 2026-2036
Germany Prefabricated Houses Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Prefabricated Houses Market Insights
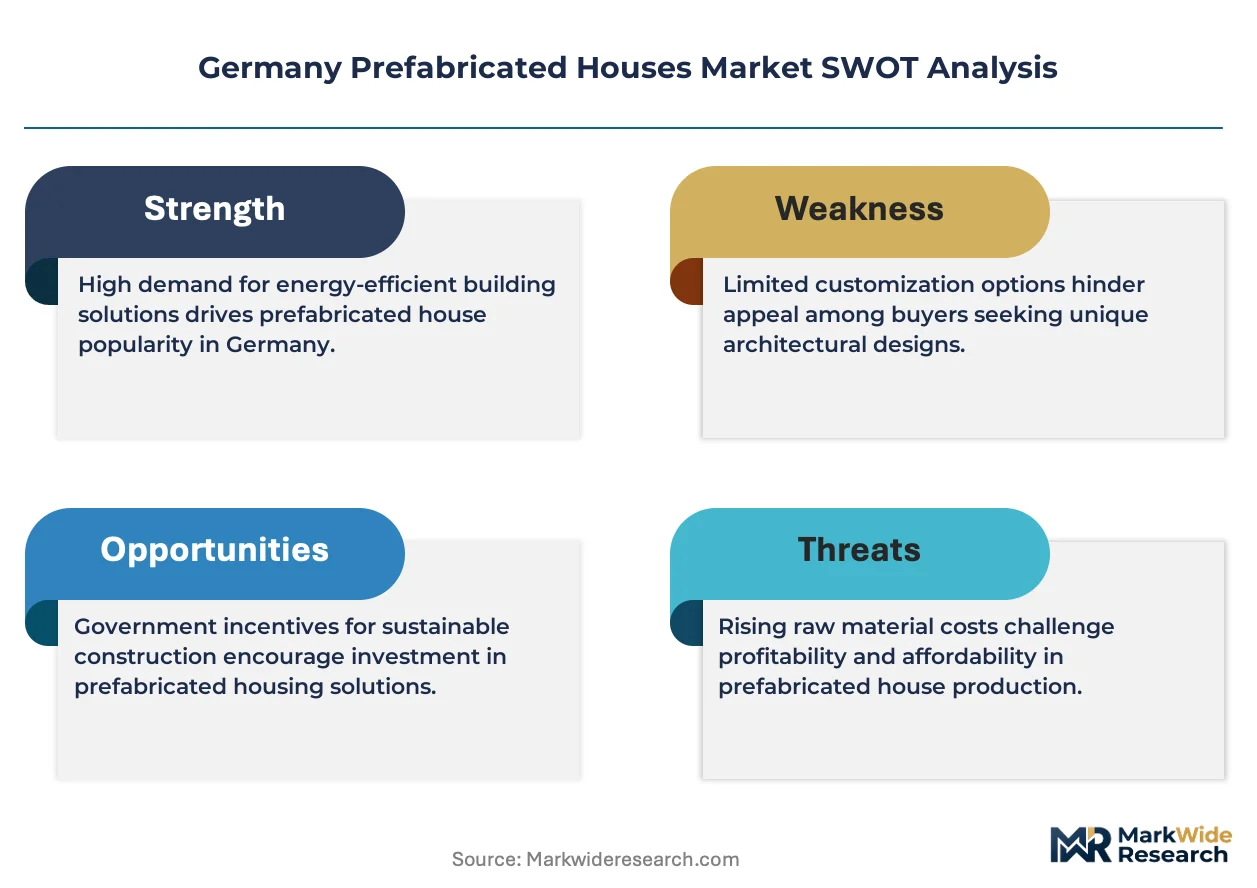
The German Building Energy Act (GEG) is consolidating the cost-of-entry calculus for prefabricated housing manufacturers by mandating near-zero-energy standards for new builds. SchwörerHaus KG leverages its timber engineering heritage to dominate premium wooden house segments across southern Germany. Hanse Haus GmbH anchors its position through panelized construction systems optimized for speed-to-occupancy. Bien-Zenker GmbH differentiates via modular affordable housing lines calibrated to municipal procurement budgets.
Germany prefabricated houses are factory-built residential structures assembled from pre-manufactured components, typically employing engineered wood frames, steel reinforcements, or concrete panels with U-values below 0.20 W/m²K to meet thermal performance thresholds. Their primary purpose is to compress construction timelines from months to weeks while holding quality tolerances within millimeter ranges. Wooden houses and hybrid houses command the widest manufacturing footprints, with hybrid systems capturing margin pools where steel-frame durability meets timber's carbon-sequestration appeal. Modular construction leads volume throughput, though 3D printing is attracting R&D capital for custom design segments where geometric complexity justifies slower cycle times.
KBA certification protocols for transportable modules and DIN 18599 energy calculation standards govern product compliance, while the federal KfW development bank channels subsidized credit toward efficiency-graded builds. The EU Green Deal's embodied-carbon tracking requirements are tightening material disclosure obligations for cross-border component suppliers. Stakeholders must monitor how the national building code's phased efficiency escalations reshape material specifications and factory automation investments.
Market Dynamics
The German Building Energy Act (GEG) is compressing construction timelines while elevating thermal performance thresholds, forcing manufacturers to retool factory automation around timber-frame and hybrid systems that satisfy near-zero-energy mandates. Bavarian and Baden-Württemberg housing clusters are pulling disproportionate capacity expansion as southern Germany concentrates demand density.
Growth Catalysts
- KfW Efficiency-Grade Financing:Subsidized credit channels from Germany's federal development bank accelerate buyer conversion toward premium thermal envelopes, particularly among first-time homeowners in urban cores.
- Timber Carbon Sequestration:Engineered wood frames satisfy EU Green Deal embodied-carbon tracking requirements while delivering U-values below 0.20 W/m²K, aligning manufacturer output with municipal procurement preferences.
- Munich-Hamburg Urban Density:Residential buyers in these metropolitan centers prioritize speed-to-occupancy, compressing decision cycles and pulling panelized and modular systems into mainstream housing finance.
Market Restraints
- Cross-Border Component Disclosure:EU Green Deal material tracking obligations impose documentation burdens on Polish and Czech timber suppliers, elevating compliance costs for German manufacturers dependent on eastern European feedstock.
- Steel Price Volatility:Hybrid system margins compress when steel reinforcement costs spike, forcing producers to absorb fluctuations or pass through to price-sensitive municipal buyers.
- Site Assembly Bottlenecks:Crane availability and skilled erection crews concentrate in southern Germany, constraining throughput velocity for projects in northern Länder where installation infrastructure remains thinner.
Strategic Opportunities
- Eastern Länder Underpenetration:Saxony and Thuringia exhibit lower prefabricated housing penetration rates, creating whitespace for manufacturers with distribution networks calibrated to smaller municipal budgets and rural parcel sizes.
- 3D Printing Convergence:Additive manufacturing integration with timber-frame systems enables geometric complexity for custom design segments where buyers accept extended cycle times for architectural differentiation.
- DIN 18599 Automation:Factory-level energy calculation standardization reduces engineering overhead per project, allowing mid-tier producers to compete on documentation speed against established premium brands.
Industry Challenges
- KBA Certification Timelines:Transportable module approval protocols create bottlenecks when factory output scales faster than regulatory inspection capacity, delaying revenue recognition on completed units.
- Digital Twin Integration:Legacy ERP systems at established manufacturers resist seamless integration with BIM-to-factory workflows, fragmenting quality control across design-to-production handoffs.
- Embodied-Carbon Audit Talent:Shortage of professionals credentialed in EU Green Deal material lifecycle assessment constrains disclosure accuracy and exposes manufacturers to greenwashing liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Prefabricated Houses Market |
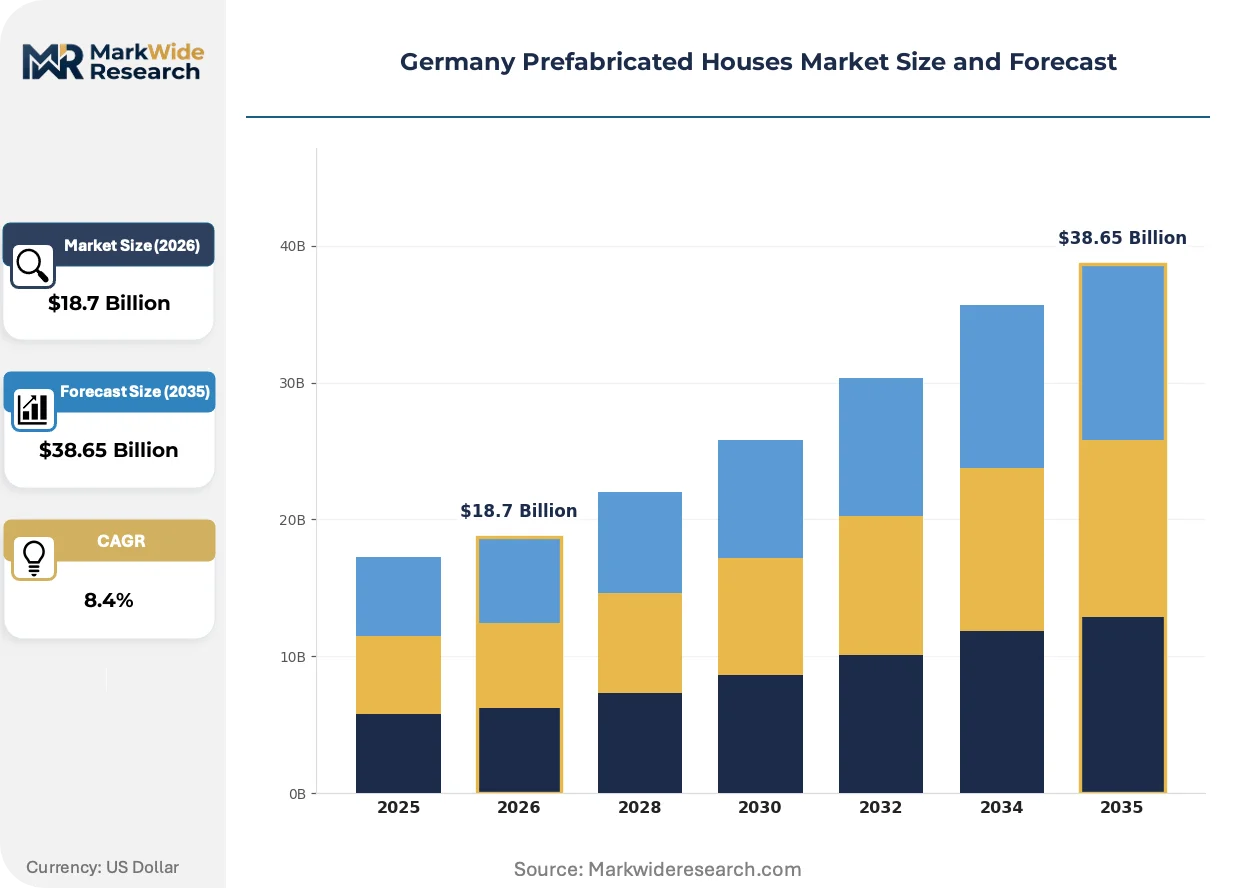
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Houses, Steel Frame Houses, Concrete Houses, Hybrid Houses Construction Method: Modular, Panelized, Pre-Cut, 3D Printing End User: Residential Buyers, Commercial Developers, Government Projects, Investment Firms Market Segment: Luxury Homes, Affordable Housing, Eco-Friendly Solutions, Custom Designs |
| Companies Covered | SchwörerHaus KG, Hanse Haus GmbH, WeberHaus GmbH & Co., Bien-Zenker GmbH, DFH Haus Holding AG, HUF Haus GmbH, FingerHaus GmbH, Baufritz GmbH & Co., Luxhaus GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Prefabricated Houses Market Trends and Innovations
Factory automation is converging with thermal engineering as German manufacturers retool around GEG-mandated performance floors. Timber processing, energy modeling, and logistics optimization are fusing into unified production systems that compress delivery windows while elevating specification precision.
Hybrid construction systems are unifying steel-frame durability with timber's carbon-sequestration properties in single structural envelopes. Municipal housing authorities in Bavaria are specifying these systems for multi-unit developments where lifecycle cost calculations dominate procurement scoring. The unification is collapsing the traditional trade-off between speed and sustainability, permitting manufacturers to bid premium segments without sacrificing throughput metrics.
The EU Green Deal's phased embodied-carbon disclosure requirements are tightening cross-border supply chain transparency for German manufacturers sourcing engineered wood from Polish and Czech mills. DIN standards are absorbing these tracking obligations into factory certification protocols, elevating documentation automation to competitive necessity. Panelized construction segments face the steepest compliance recalibration as material passports become mandatory for public procurement eligibility.
Direct-to-developer contracting is displacing traditional general contractor intermediation in urban infill projects across Hamburg and Munich. Housing cooperatives and institutional investors are consolidating purchase volumes, extracting volume pricing and customization concessions that fragment legacy distribution channels. This concentration is most visible in Baden-Württemberg's industrial housing clusters where procurement officers centralize multi-project specifications to secure factory allocation priority.
Germany Prefabricated Houses Market Segmentation
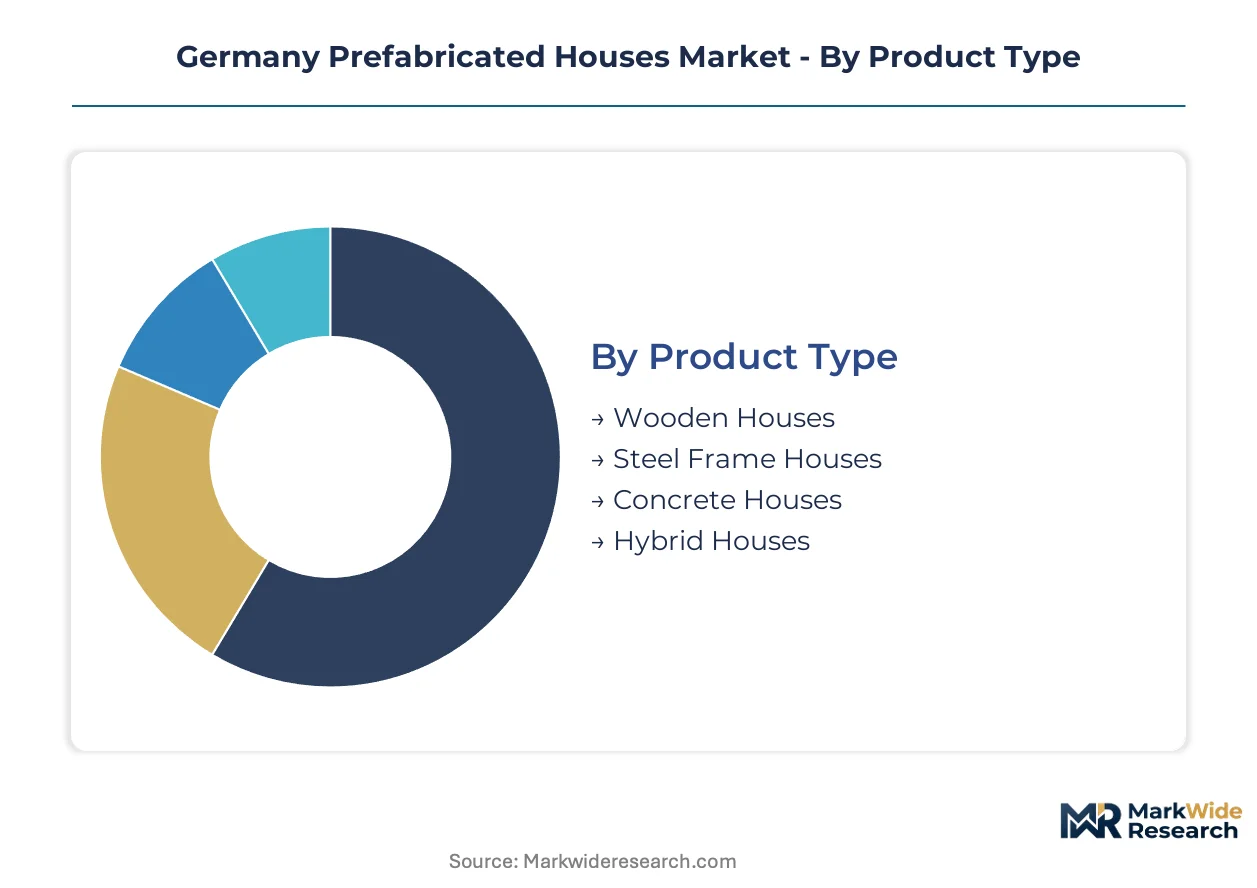
Segmentation in Germany's prefabricated housing market reveals how regulatory pressure and buyer economics split manufacturing capacity across competing technical approaches. Each dimension—product material, construction methodology, purchaser type, and market tier—channels factory investment toward distinct margin and volume profiles.
Product Type:
Material selection in German prefabricated housing splits between standalone structural systems and composite assemblies that embed multiple engineering layers. The Building Energy Act's thermal thresholds favor solutions that integrate insulation performance into the primary frame rather than treating it as an add-on layer.
- Wooden Houses:Engineered timber frames with U-values below 0.20 W/m²K dominate Bavarian and Baden-Württemberg procurement. Municipal housing authorities in Munich specify these systems for multi-unit developments where carbon-sequestration metrics influence scoring.
- Hybrid Houses:Steel-reinforced timber composites unify durability with embodied-carbon compliance, capturing premium segments where lifecycle cost calculations outweigh upfront price sensitivity. Baden-Württemberg's industrial housing clusters drive disproportionate demand for these systems.
- Steel Frame Houses:Cold-formed steel structures serve commercial developer timelines in Hamburg's urban infill zones.
- Concrete Houses:Precast concrete panels anchor government projects requiring fire-resistance ratings above timber capabilities.
Volume placements concentrate in Wooden Houses; the faster expansion belongs to Hybrid Houses.
Construction Method:
Factory-to-site integration depth varies dramatically across construction methodologies, with some approaches delivering near-complete modules while others ship flat-packed components requiring extensive on-site labor. The choice between these models determines logistics complexity, crane requirements, and the geographic radius within which manufacturers remain cost-competitive.
- Modular:Three-dimensional volumetric units arrive 85-95% complete from factory, compressing Hamburg and Munich site timelines to weeks. KBA certification protocols govern transportable module approval, creating regulatory bottlenecks when factory output scales faster than inspection capacity.
- Panelized:Wall and floor assemblies ship flat-packed for rapid on-site erection, balancing customization flexibility with speed-to-occupancy. Southern Germany's crane availability and skilled erection crews concentrate throughput in Bavaria while northern Länder face installation infrastructure constraints.
- Pre-Cut:Precision-cut timber components arrive labeled for traditional stick-frame assembly, serving rural parcel sizes in Thuringia and Saxony.
- 3D Printing:Additive manufacturing enables geometric complexity for custom design segments where buyers accept extended cycle times for architectural differentiation.
Modular construction leads current throughput; Panelized systems are gaining share fastest among urban infill developers.
End User:
Purchaser category shapes contract structure, customization depth, and financing channels. Direct-to-developer contracting is displacing traditional general contractor intermediation, with institutional buyers extracting volume pricing that fragments legacy distribution.
- Residential Buyers:First-time homeowners in Munich and Hamburg leverage KfW efficiency-grade financing to access premium thermal envelopes. These buyers prioritize speed-to-occupancy, compressing decision cycles toward panelized and modular systems.
- Commercial Developers:Housing cooperatives and institutional investors consolidate multi-project specifications to secure factory allocation priority, centralizing procurement in Baden-Württemberg's industrial clusters.
- Government Projects:Municipal procurement budgets in Bavaria specify hybrid systems for affordable housing developments where lifecycle cost dominates scoring.
- Investment Firms:Portfolio landlords acquire standardized modular units for rental yield optimization across eastern Länder.
Commercial Developers command the largest contract values; Residential Buyers show the steepest expansion trajectory as KfW credit channels deepen.
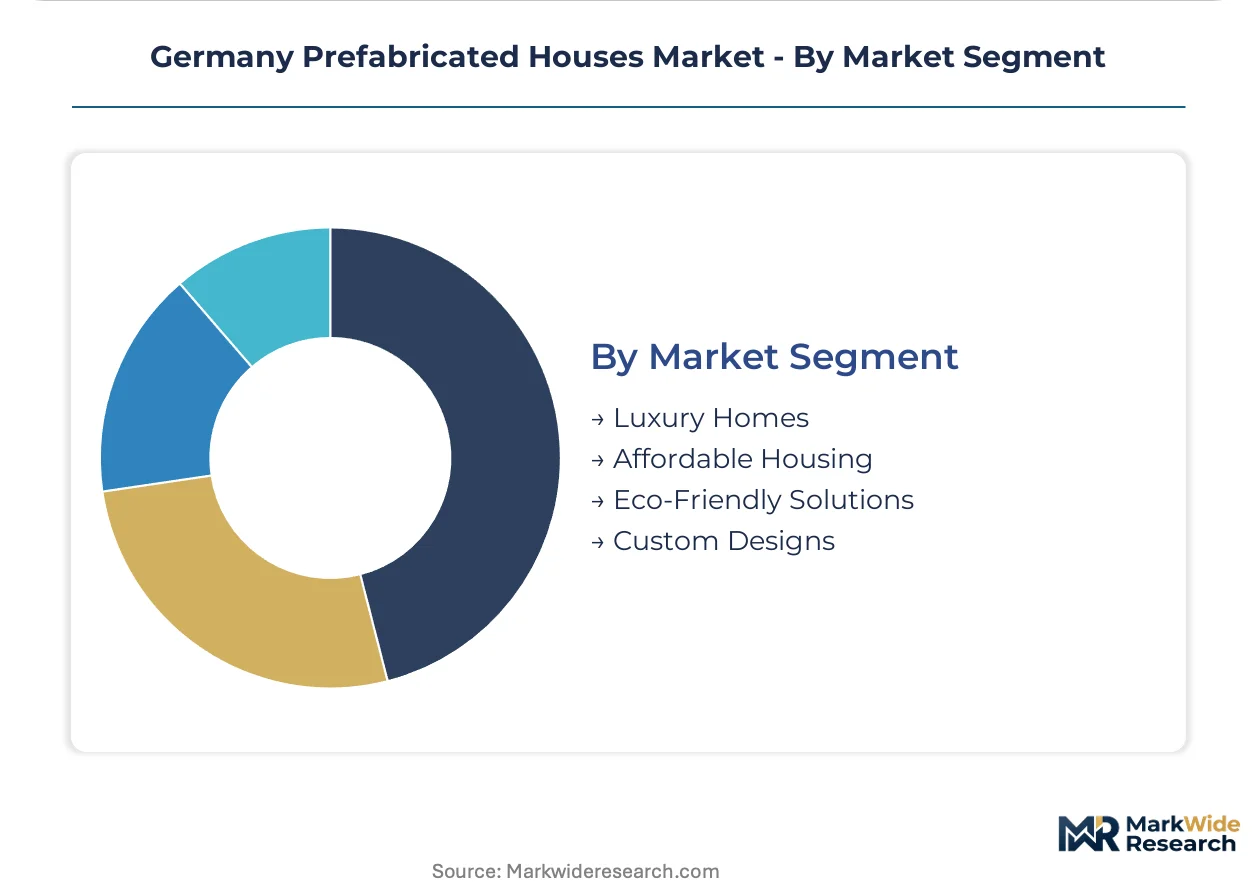
Market Segment:
Price-positioning tiers in German prefabricated housing align with certification grades, material specifications, and the sophistication of energy modeling embedded in factory workflows. DIN 18599 automation separates premium documentation speed from mid-tier competitors.
- Affordable Housing:Municipal procurement lines calibrate to strict budget ceilings, with Bien-Zenker GmbH and competitors optimizing panelized systems for cost-per-square-meter minimization. Eastern Länder underpenetration creates whitespace for distribution networks serving smaller rural parcel sizes.
- Eco-Friendly Solutions:EU Green Deal embodied-carbon tracking requirements tighten material disclosure obligations, elevating documentation automation to competitive necessity. Timber carbon sequestration satisfies municipal preferences in southern Germany.
- Luxury Homes:Custom timber engineering heritage commands premium positioning across Bavaria's premium housing clusters.
- Custom Designs:3D printing convergence enables geometric complexity where architectural differentiation justifies slower factory cycle times.
Affordable Housing absorbs the greatest unit volume; Eco-Friendly Solutions are climbing the fastest as GEG efficiency escalations reshape material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's premium housing clusters and Baden-Württemberg's industrial base concentrate procurement pipelines across southern Germany, while eastern Länder present whitespace for distribution expansion. The KfW development bank channels subsidized credit toward efficiency-graded builds nationwide.
Bavaria
Munich's metropolitan density accelerates residential buyer conversion toward panelized and modular systems. The Building Energy Act mandates near-zero-energy standards, pushing manufacturers toward timber-frame engineering. SchwörerHaus KG leverages its heritage across Bavaria's premium housing clusters to dominate wooden house segments.
Baden-Württemberg
Industrial housing clusters in Stuttgart and Karlsruhe centralize multi-project specifications from institutional buyers. DIN 18599 energy calculation standards govern factory-level compliance automation. Hybrid construction systems capture disproportionate demand where lifecycle cost calculations dominate municipal procurement scoring.
North Rhine-Westphalia
Rhine-Ruhr urbanization pulls panelized systems into mainstream housing finance for first-time homeowners. The federal KfW development bank's efficiency-grade financing accelerates buyer conversion toward premium thermal envelopes. Cologne and Düsseldorf concentrate crane availability and skilled erection crews.
Lower Saxony
Hanover's logistics infrastructure supports modular construction distribution networks serving northern Länder. Site assembly bottlenecks constrain throughput velocity where installation infrastructure remains thinner than southern counterparts. Pre-cut timber components serve rural parcel sizes across Thuringia-adjacent territories.
Hamburg
Urban infill projects compress construction timelines from months to weeks as housing cooperatives consolidate purchase volumes. Direct-to-developer contracting displaces traditional general contractor intermediation. Speed-to-occupancy priorities pull modular systems into mainstream housing finance.
Germany Prefabricated Houses Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's prefabricated housing market. The vendor base organizes into tiered clusters: premium timber engineers, mid-scale panelized producers, and municipal-focused affordable housing lines. Three strategic archetypes dominate: heritage wooden house manufacturers, speed-optimized panelized system builders, and modular volume players. Capacity expansion and factory automation retooling constitute the dominant competitive moves as manufacturers adapt to GEG-mandated performance floors.
Within the heritage timber engineering tier, SchwörerHaus KG and Bien-Zenker GmbH occupy archetypal positions—one representing premium wooden house dominance across southern Germany, the other exemplifying municipal procurement calibration. Hanse Haus GmbH anchors the panelized construction segment where speed-to-occupancy optimization drives competitive differentiation. These three GmbH and KG structures illustrate how German corporate forms cluster around distinct strategic postures: family-owned engineering heritage, municipal budget alignment, and urban infill velocity.
| Leading Market Players |
|---|
| SchwörerHaus KG |
| Hanse Haus GmbH |
| WeberHaus GmbH & Co. |
| Bien-Zenker GmbH |
| DFH Haus Holding AG |
| HUF Haus GmbH |
| FingerHaus GmbH |
| Baufritz GmbH & Co. |
| Luxhaus GmbH |
| Others |
Pricing and Supply Chain Analysis
Engineered timber feedstock originating from Polish and Czech mills travels through cross-border processing before reaching German factory floors, with transport costs and EU Green Deal material disclosure obligations stacking onto base material prices to stratify final housing tiers. Bavarian buyers absorb premium positioning for carbon-sequestered wooden frames while eastern Länder procurement operates on thinner margins where documentation automation remains underdeveloped.
Pricing Analysis
Lead-time compression commands measurable premiums across German prefabricated housing, with Munich and Hamburg buyers paying escalation for factory allocation priority that compresses site-to-occupancy windows below standard scheduling. Three-tier pricing structure across premium, standard, and economy levels separates SchwörerHaus heritage timber engineering from municipal-calibrated panelized lines and pre-cut rural offerings. Pricing pressure stems from steel reinforcement volatility in hybrid systems, forcing producers toward timber-heavy specifications. Municipal housing authorities exhibit acute price sensitivity, while institutional investors in Baden-Württemberg prioritize lifecycle cost over upfront outlay.
Supply Chain Analysis
Freight optimization dominates supply chain architecture as module dimensions hit KBA transport certification thresholds, constraining factory-to-site radius for volumetric units. Engineered timber draws from Poland, Czech Republic, and domestic Bavarian sawmills, while cold-formed steel hinges on German and Benelux rolling capacity. Single-source vulnerability concentrates in eastern European timber suppliers facing EU Green Deal disclosure burdens. Distribution runs through direct-to-developer contracting that displaces legacy general contractor networks, particularly in Hamburg urban infill corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The German Building Energy Act erects a cost-of-compliance barrier that filters out undercapitalized competitors, rewarding manufacturers with factory automation already calibrated to near-zero-energy thresholds. GEG-mandated performance floors function as a moat protecting incumbents who absorbed retooling costs early.
For Market Incumbents: Hedge against steel price volatility by deepening captive timber processing capabilities across Bavarian supply sheds. Accelerate DIN 18599 energy calculation automation to compress documentation overhead per project, defending margin position against mid-tier panelized competitors. Channel capacity expansion toward crane-constrained northern Länder where installation infrastructure scarcity limits rival throughput.
For New Entrants and Emerging Players: Begin with eastern Länder whitespace in Saxony and Thuringia, where prefabricated housing penetration trails southern benchmarks and municipal budgets favor standardized panelized systems. Target rural parcel sizes with pre-cut timber components that circumvent modular transport bottlenecks. Establish go-to-market positioning through KfW efficiency-grade financing partnerships that accelerate first-time homeowner conversion.
For Investors and Strategic Acquirers: KBA certification backlog expansion is the leading indicator that factory output is scaling faster than regulatory inspection capacity, signaling revenue recognition delays that compress working capital efficiency. Five-to-ten year viability favors manufacturers with unified BIM-to-factory workflows and embodied-carbon audit talent pipelines. Acquisition screening should prioritize mid-tier panelized producers with DIN automation gaps but defensible regional distribution in underpenetrated territories.
| Strategic Initiative | Industry Significance |
|---|---|
| Factory Automation Retooling | GEG-mandated thermal performance floors require timber-frame and hybrid system recalibration across production lines. |
| Backward Integration into Timber Processing | Captive engineered wood capacity insulates margins from Polish and Czech supplier disclosure cost escalations. |
| DIN 18599 Documentation Automation | Energy calculation standardization reduces engineering overhead and accelerates municipal procurement bid cycles. |
| Eastern Länder Distribution Buildout | Saxony and Thuringia underpenetration offers volume expansion where crane and crew constraints are less severe. |
| Embodied-Carbon Audit Capability Investment | EU Green Deal material passport requirements elevate lifecycle assessment talent to competitive necessity. |
Research Methodology
Independent corroboration across factory operations directors, municipal procurement officers, KfW financing administrators, and timber engineering specialists underwrites the qualitative findings. Primary interviews with Bavarian housing cluster managers and Baden-Württemberg industrial procurement leads combined with secondary validation from KBA certification databases, DIN standards documentation, and federal building code filings. Bottom-up project pipeline aggregation and top-down macro construction output triangulation anchored volume estimates.
Rate-of-change decomposition across product type, construction method, end user category, and regional adoption pattern structured the analytical framework. CAGRs derived from segmented growth trajectory modeling incorporating KfW credit channel expansion, GEG regulatory phase-in timing, and crane availability constraints. Forecast inputs included municipal housing authority budget cycles and eastern Länder infrastructure development schedules.
Underlying measurement precision varies by segment; modular construction and Bavarian regional data carry tighter precision than 3D printing and eastern Länder emerging markets. Forecasts reflect assumptions around regulatory inspection capacity scaling and cross-border timber supply stability. Stakeholders should weight assumptions against their own operating context and local permitting velocity experience.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
US Residential Remodeling Market
Residential Construction
US Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
UK Residential Construction Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
North America Residential Construction Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Europe Residential Construction Market