
 Global Recombinant Vaccines Market | 2026-2036
Global Recombinant Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recombinant Vaccines Market Foresight
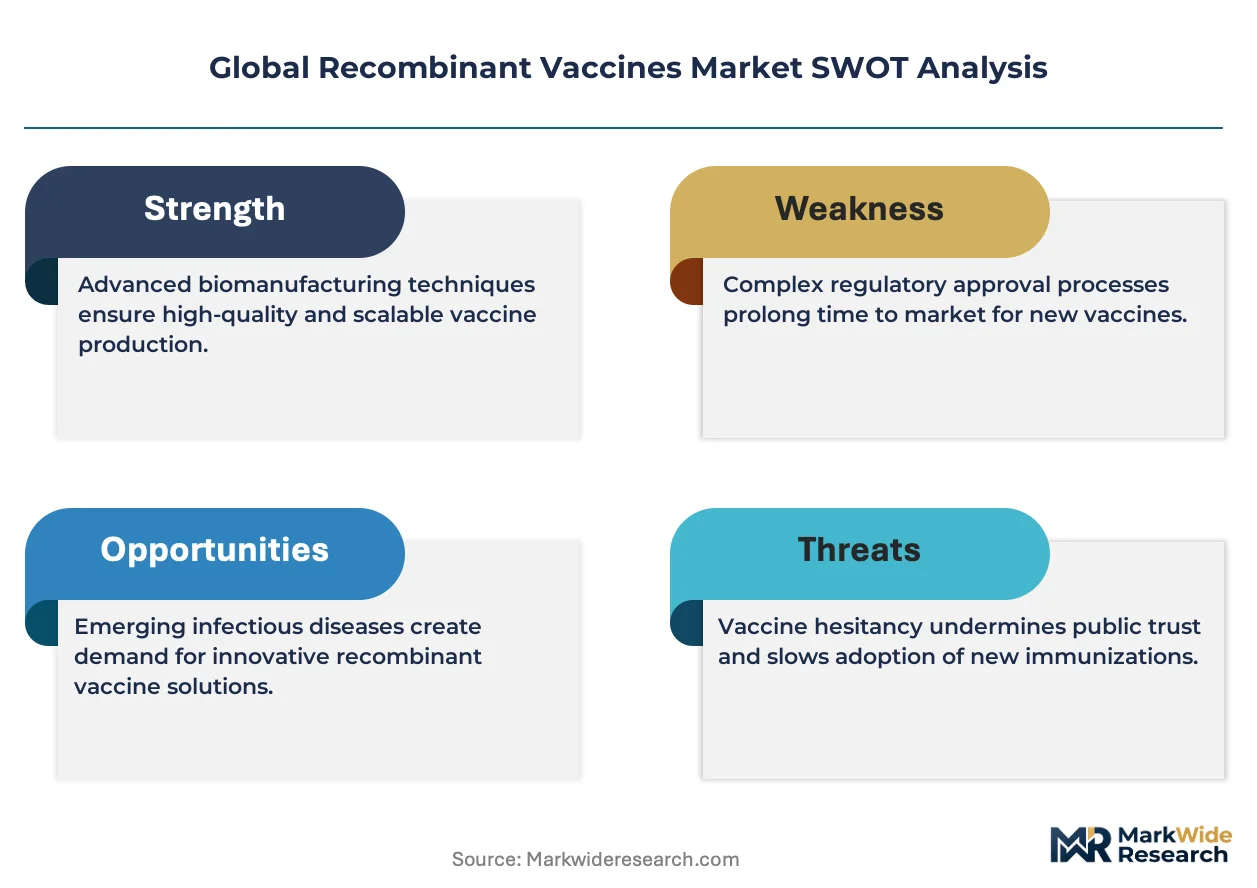
Project finance for biologics manufacturing facilities is narrowing the field of viable competitors. Merck & Co., Inc. anchors its position through captive fermentation capacity and backward integration into critical raw materials. GSK plc differentiates via sustained investment in adjuvant science and lipid nanoparticle delivery platforms. Pfizer Inc. leverages its scale advantage to occupy multiple technology lanes simultaneously.
Recombinant vaccines are biologics produced by inserting antigen-coding genes into host cells such as yeast, bacteria, or mammalian lines, then purifying the expressed proteins or assembled vectors for immunization. Protein subunit formulations dominate commercial output due to established manufacturing familiarity and favorable stability profiles. Viral vector platforms represent the fastest-expanding category, driven by their capacity to elicit robust cellular immunity in oncology prevention applications. DNA-based approaches remain concentrated in research institutions, though electroporation delivery advances may accelerate clinical translation.
FDA breakthrough therapy designations, EMA adaptive pathway frameworks, and WHO prequalification standards collectively determine which products achieve widespread procurement by public health agencies. These regulatory mechanisms reward sponsors that generate immunogenicity data across diverse populations, effectively filtering market access to organizations with global trial infrastructure. Stakeholders must monitor how emerging platform technologies interact with evolving pharmacovigilance requirements for novel delivery systems.
Market Dynamics
Platform technology convergence is compressing development timelines while fragmenting manufacturing footprints across distributed biologics networks. The shift from centralized bulk production to modular, portable manufacturing units is redrawing capital allocation and partnership structures across the value chain.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Compressed review timelines for recombinant candidates targeting unmet medical needs accelerate sponsor cash conversion cycles and de-risk late-stage development investments.
- Cellular Agriculture Infrastructure:Yeast and mammalian cell line optimization from food-grade bioreactor networks is spilling into vaccine production, expanding contract manufacturing capacity without greenfield capex.
- Pediatric Immunization Mandates:National immunization technical advisory groups in India, Nigeria, and Indonesia are expanding recombinant hepatitis B and HPV coverage through Gavi co-financing mechanisms.
Market Restraints
- Single-Use Bioreactor Supply Concentration:German and US suppliers dominate film and bag assemblies, creating input vulnerability for facilities scaling viral vector output.
- Cold Chain Incompatibility:mRNA-lipid nanoparticle formulations require ultra-low temperature distribution infrastructure absent in last-mile networks across sub-Saharan Africa and South Asia.
- EMA Adaptive Pathway Stringency:Post-authorization evidence requirements for novel adjuvants extend regulatory uncertainty and compress effective patent life for first movers.
Strategic Opportunities
- Brazil's ANVISA Parallel Review:Synchronized FDA-ANVISA submission pathways for recombinant dengue candidates reduce time-to-market in the hemisphere's largest outbreak zone.
- Plant-Based Expression Systems:Nicotiana benthamiana transient expression platforms bypass mammalian cell culture bottlenecks and enable rapid pandemic response manufacturing.
- Pharmacy Channel Expansion:Community pharmacist administration of recombinant zoster and pneumococcal vaccines in Japan and South Korea is capturing adult immunization visits outside clinic settings.
Industry Challenges
- Process Analytical Technology Integration:Real-time quality attribute monitoring for continuous bioprocessing requires cross-functional teams combining biostatistics, automation engineering, and regulatory science expertise that remains scarce.
- Multi-Product Facility Segregation:Viral vector and protein subunit campaigns in shared suites demand extensive changeover validation, compressing effective utilization rates and complicating capacity planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recombinant Vaccines Market |
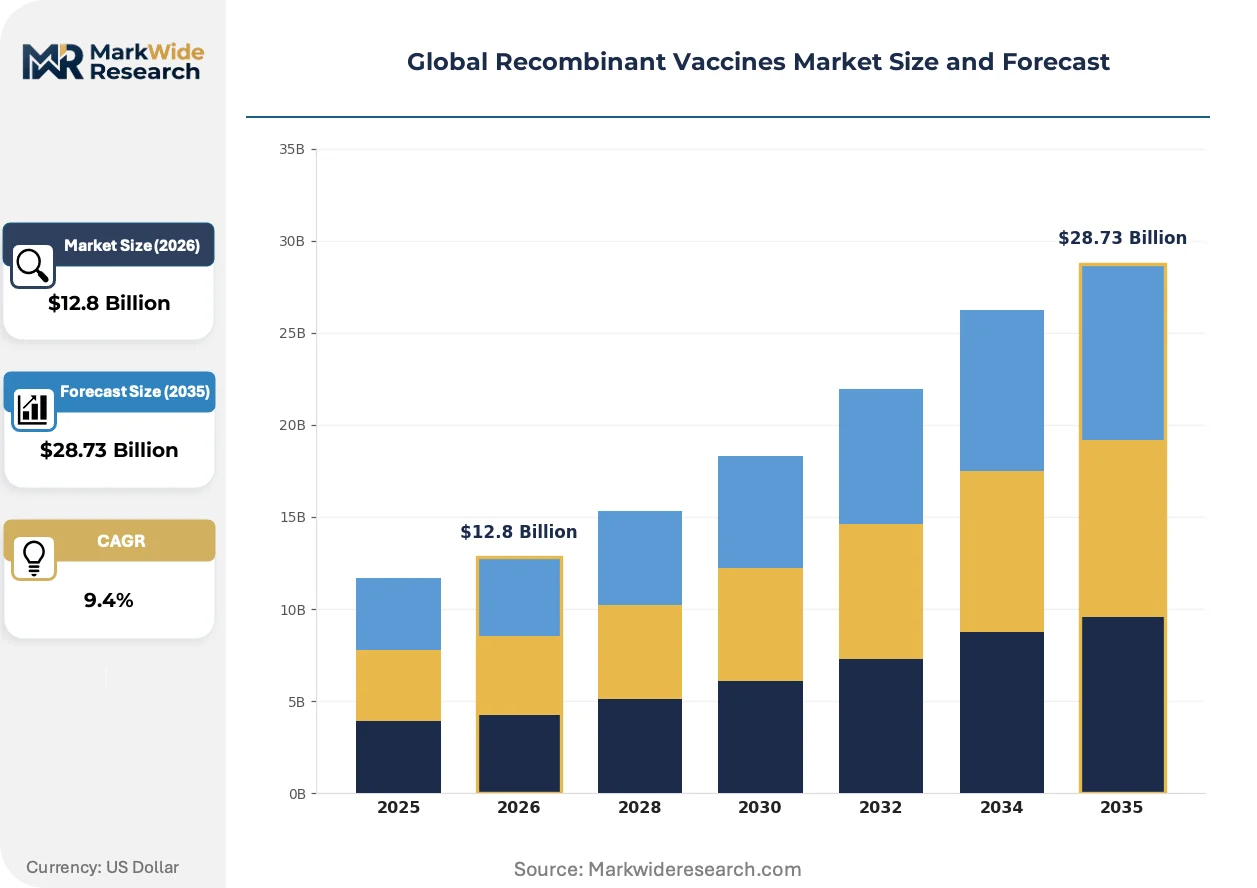
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Subunit, Viral Vector, DNA-based, Conjugate, Toxoid Application: Infectious Diseases, Oncology Prevention, Veterinary Immunization, Travel Medicine, Biodefense End User: Research Institutions, Pharmaceutical Companies, Veterinary Clinics, Public Health Agencies, Biotechnology Firms Delivery Technology: Lipid Nanoparticles, Electroporation, Viral Vectors, Adjuvant Formulations, Micro-needles |
| Companies Covered | Merck & Co., Inc., GSK plc, Pfizer Inc., Sanofi, Novavax, Inc., Bavarian Nordic, Serum Institute of India Pvt. Ltd., Johnson & Johnson, AstraZeneca Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recombinant Vaccines Market Shifts & Advancements
Recombinant vaccine platforms are converging with synthetic biology and digital manufacturing control systems, collapsing the traditional separation between upstream strain development and downstream formulation science. This integration is compressing the timeline from gene synthesis to clinical material release.
Self-amplifying RNA (saRNA) replicon platforms are hybridizing with established protein subunit manufacturing infrastructure. saRNA candidates from University of Tokyo and Imperial College London spinouts are entering Phase II trials with dose-sparing advantages over conventional mRNA. Contract manufacturers in South Korea and Switzerland are retrofitting existing microbial fermentation lines to accommodate saRNA production, blurring the boundary between nucleic acid and protein-based vaccine economics.
EMA's revised Good Manufacturing Practice Annex 1 for sterile medicinal products is mandating contamination control strategy documentation that exceeds prior facility design expectations. Single-use system suppliers must now provide extractables and leachables data packages spanning the full product contact surface area. Facilities in Ireland and the Netherlands are prioritizing isolator-based filling lines over conventional cleanroom architectures to preempt regulatory inspection findings.
Hospital procurement consortia in Germany and France are consolidating recombinant vaccine purchasing through framework agreements that bundle adult immunization across therapeutic areas. This concentration is displacing fragmented physician-office buying and shifting price negotiation leverage toward national tender bodies. Manufacturers are responding with indication-spanning portfolio bids rather than single-product contracting.
Global Recombinant Vaccines Market Segmentation
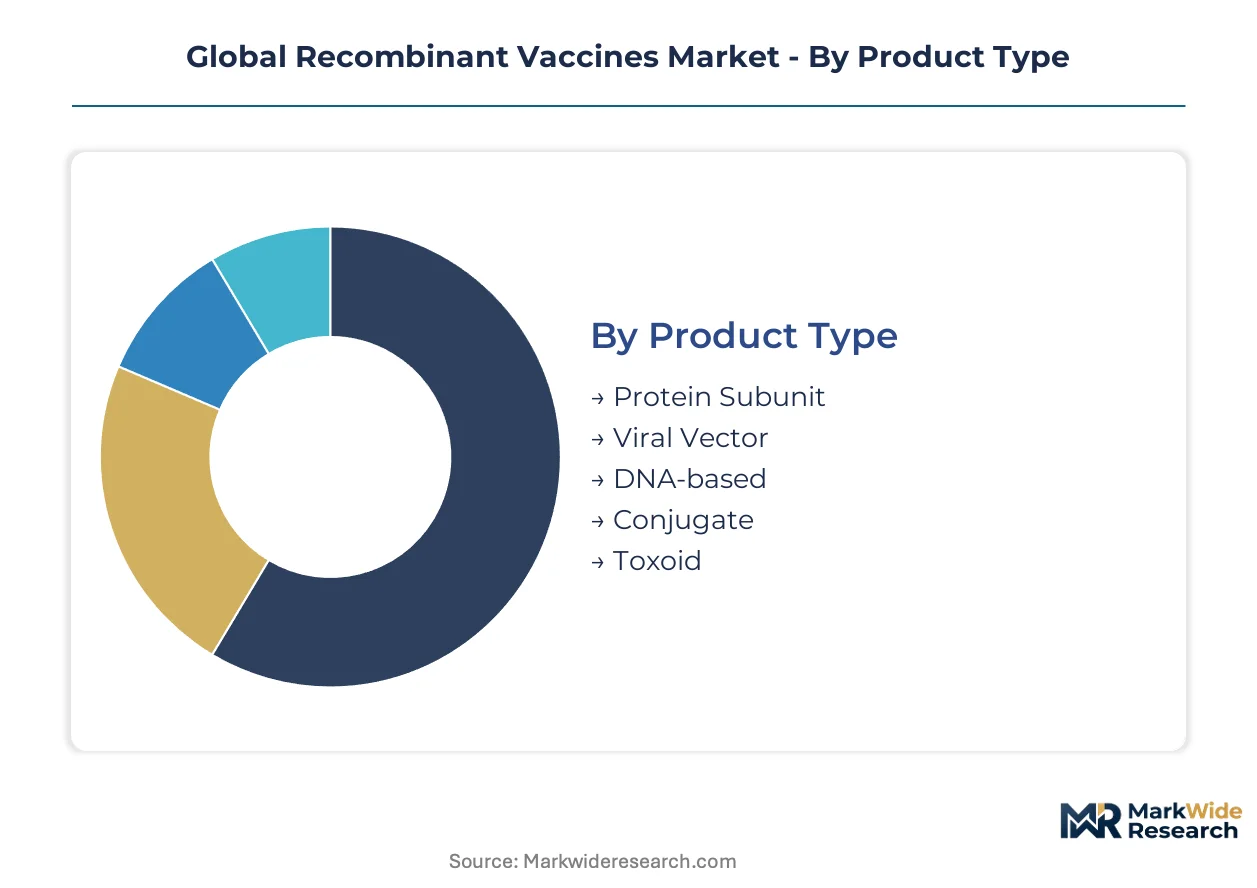
Recombinant vaccine segmentation reveals how platform maturity, delivery complexity, and procurement authority shape commercial outcomes across distinct technology lanes. Understanding these divides clarifies where manufacturing investment and regulatory strategy should concentrate.
Product Type:
Mature protein-based platforms coexist with emerging nucleic acid and advanced vector systems, creating divergent capital intensity and timeline profiles across the manufacturing base.
- Protein Subunit:Yeast or mammalian cell cultures express purified antigenic proteins with established downstream purification protocols. Pediatric hepatitis B programs in India and Nigeria rely on this format for thermal stability and familiar cold chain requirements.
- Viral Vector:Engineered adenoviruses or lentiviruses deliver transgenes directly into host cells, eliciting cellular immunity critical for oncology prevention applications. Facilities in the United States and Germany are scaling single-use bioreactor capacity to meet demand from therapeutic vaccine pipelines.
- DNA-based:Plasmid DNA encoding target antigens remains concentrated in research-phase candidates, though electroporation delivery advances from South Korean contract manufacturers may accelerate clinical translation.
- Conjugate:Polysaccharide-protein linkages enhance immunogenicity for pediatric pneumococcal formulations, with procurement concentrated through Gavi co-financing mechanisms in Indonesia and lower-income markets.
- Toxoid:Detoxified bacterial exotoxins retain relevance for diphtheria and tetanus combination vaccines in established immunization schedules.
Protein Subunit retains volume leadership; Viral Vector holds the steepest expansion curve.
Application:
Cost tier stratification separates mass preventive campaigns from premium therapeutic indications, with reimbursement pathways determining viable price points across each cluster.
- Infectious Diseases:Hepatitis B, HPV, and COVID-19 prevention drive procurement volume through national immunization technical advisory groups. WHO prequalification standards filter access to public health agencies in low- and middle-income countries.
- Oncology Prevention:Therapeutic vaccines targeting HPV-related malignancies and melanoma command premium pricing through hospital procurement consortia in Germany and France. Viral vector platforms dominate this segment due to cellular immunity requirements.
- Veterinary Immunization:Recombinant rabies and foot-and-mouth disease vaccines serve agricultural economies in Brazil and Argentina, with ANVISA and local regulators overseeing registration pathways.
- Travel Medicine:Japanese encephalitis and typhoid formulations target outbound travelers from Japan and South Korea, distributed through pharmacy channels outside traditional clinic settings.
- Biodefense:Anthrax and smallpox countermeasures stockpile requirements concentrate demand within US BARDA and allied national security frameworks.
Infectious Diseases captures the broadest procurement base; Oncology Prevention climbs fastest on per-dose value expansion.
End User:
Customer type determines contract structure, with public tenders favoring volume commitments and private research partnerships prioritizing intellectual property terms.
- Research Institutions:University of Tokyo and Imperial College London spinouts advance self-amplifying RNA platforms through early-phase trials, outsourcing manufacturing to Swiss and South Korean contract partners.
- Pharmaceutical Companies:Merck and GSK anchor demand through captive fermentation capacity and backward integration into critical raw materials.
- Veterinary Clinics:Agricultural extension networks in Brazil distribute recombinant livestock vaccines through regional cold chain cooperatives.
- Public Health Agencies:India's Universal Immunization Programme and Nigeria's National Primary Health Care Development Agency coordinate Gavi-funded procurement for hepatitis B and HPV coverage expansion.
- Biotechnology Firms:Emerging platform developers in South Korea and Switzerland retrofit existing microbial lines for saRNA production, blurring traditional manufacturing boundaries.
Public Health Agencies dominate procurement volume; Biotechnology Firms expand most quickly on platform diversification.
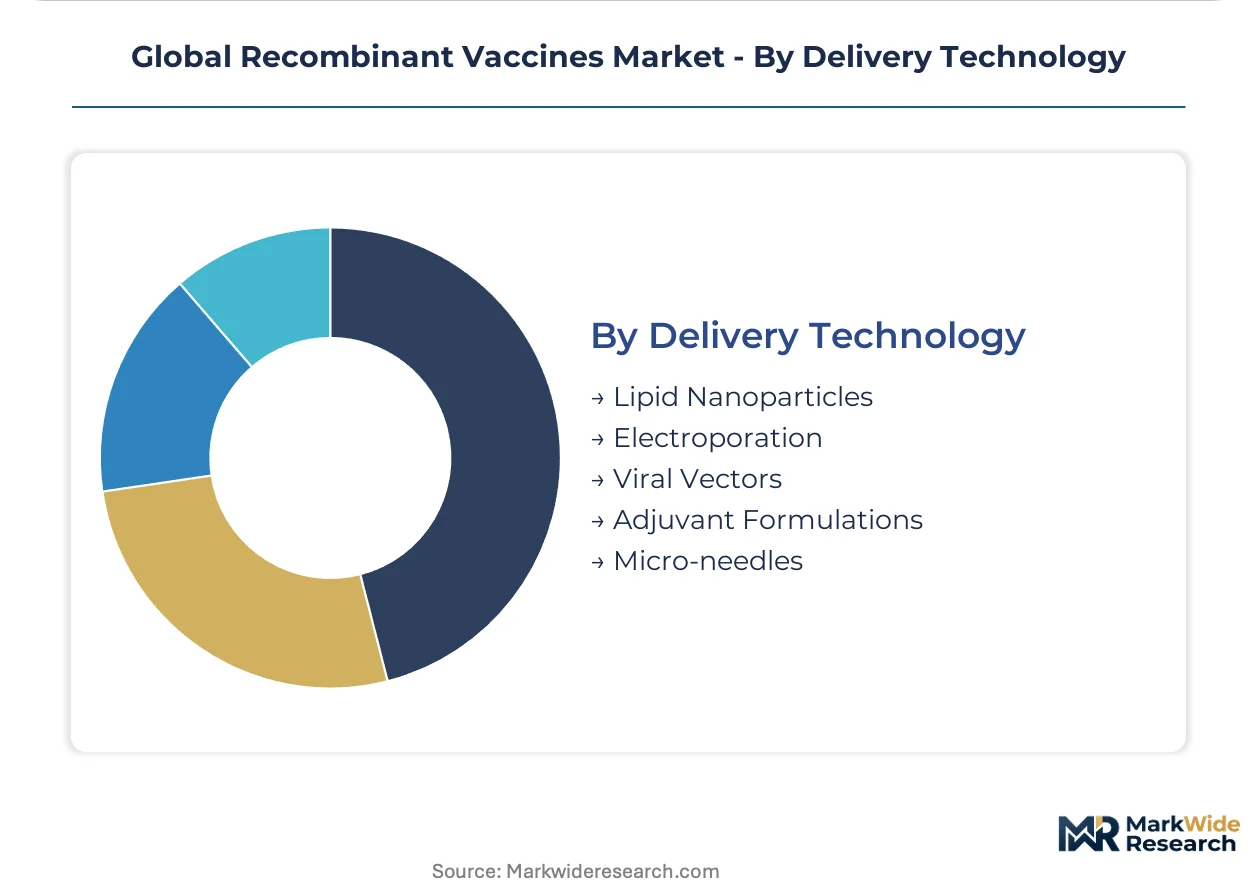
Delivery Technology:
Supply concentration in German and US component suppliers shapes accessibility for novel delivery systems, particularly for temperature-sensitive formulations.
- Lipid Nanoparticles:mRNA encapsulation systems require ultra-low temperature distribution infrastructure, limiting deployment in sub-Saharan Africa and South Asia where last-mile cold chains remain underdeveloped.
- Electroporation:Electrical pulse-mediated DNA uptake is gaining traction for DNA-based candidates, with South Korean manufacturers integrating portable devices into clinical trial protocols.
- Viral Vectors:Adenovirus and lentivirus delivery leverages existing bioreactor infrastructure, though changeover validation between campaigns compresses effective utilization rates in multi-product facilities.
- Adjuvant Formulations:GSK's sustained investment in lipid-based and oil-in-water systems differentiates cellular response profiles for protein subunit vaccines.
- Micro-needles:Dissolvable polymer arrays enable thermostable, pain-reduced administration, with Japanese and South Korean pharmacy channels piloting community-based adult immunization programs.
Viral Vectors retain installed capacity leadership; Micro-needles gain share fastest on cold chain simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital procurement consortia while Indian national immunization programs compress margins through volume tenders. This asymmetry fragments competitive strategy across Atlantic and Indian Ocean basins.
United States
BARDA stockpile requirements for anthrax and smallpox countermeasures anchor biodefense procurement, with Maryland and Massachusetts clusters housing viral vector manufacturing. FDA breakthrough therapy designations compress review timelines for oncology prevention candidates. The Research Triangle Park corridor in North Carolina concentrates process analytical technology development for continuous bioprocessing.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia consolidate adult immunization purchasing through framework agreements that bundle across therapeutic areas. EMA adaptive pathway frameworks extend post-authorization evidence requirements for novel adjuvants. The Rhine-Main biotech corridor near Frankfurt anchors lipid nanoparticle formulation science for mRNA platforms.
China
NMPA accelerated review pathways for recombinant hepatitis B and HPV vaccines expand pediatric coverage through provincial immunization programs. Domestic manufacturers in Jiangsu and Guangdong provinces scale yeast-based protein subunit capacity for Gavi co-financed export markets. The Suzhou Industrial Park cluster concentrates viral vector contract manufacturing for regional biotech firms.
India
The Universal Immunization Programme drives volume procurement of recombinant hepatitis B through Gavi co-financing mechanisms, with Serum Institute of India anchoring supply from Pune facilities. CDSCO streamlined registration for WHO-prequalified products accelerates market entry for export-oriented manufacturers. The Hyderabad-Genome Valley cluster concentrates DNA plasmid and viral vector research-phase production.
Brazil
ANVISA parallel review synchronization with FDA pathways reduces time-to-market for recombinant dengue candidates targeting the hemisphere's largest outbreak zone. Agricultural extension networks in São Paulo and Minas Gerais distribute veterinary recombinant vaccines through regional cold chain cooperatives. The São Paulo metropolitan cluster anchors Latin American clinical trial infrastructure for platform technology developers.
Global Recombinant Vaccines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adjuvant science and delivery technology. The field narrows around three strategic archetypes: multinational biopharmaceuticals with captive fermentation capacity, platform-agnostic contract manufacturers, and national champions serving immunization programs through cost-optimized production. Consolidation pressure intensifies as project finance for biologics manufacturing facilities filters viable competitors. Dominant competitive moves include backward integration into critical raw materials and strategic partnerships for modular manufacturing deployment.
Among the integrated multinational tier, Merck & Co., Inc. and GSK plc exemplify divergent specialization strategies—one through fermentation capacity scale, the other through sustained adjuvant science investment. Pfizer Inc. occupies a position spanning multiple technology lanes simultaneously. These three anchors represent how scale, platform breadth, and component depth partition competitive advantage in recombinant vaccine supply.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GSK plc |
| Pfizer Inc. |
| Sanofi |
| Novavax, Inc. |
| Bavarian Nordic |
| Serum Institute of India Pvt. Ltd. |
| Johnson & Johnson |
| AstraZeneca Plc. |
| Others |
Supply & Pricing Matrix
German and US suppliers of single-use bioreactor film and bag assemblies command upstream pricing leverage that pools margin in downstream viral vector manufacturing. This concentration forces buyers into long-term offtake commitments or captive capacity investments to secure input access.
Pricing Analysis
The customization-premium spread separates GMP-grade viral vector campaigns from standard protein subunit production, with novel adjuvant formulations commanding additional certification-tier premiums. Price differentiation rests on FDA breakthrough therapy designation status and WHO prequalification tier. Cost compression in pediatric hepatitis B supply runs through Gavi co-financing volume tenders in India and Nigeria. Public health agencies exhibit highest price sensitivity; hospital procurement consortia in Germany show lowest sensitivity due to bundled framework agreements.
Supply Chain Analysis
South Korean and Swiss contract manufacturers hold expanding capacity for self-amplifying RNA platform production, retrofitting existing microbial fermentation lines. Geographic supply concentration centers on Germany, the United States, and China for bioreactor hardware and lipid nanoparticle formulation science. Raw material dependencies include yeast extract, mammalian cell culture media, and pharmaceutical-grade lipids. Single-source vulnerability in German and US film suppliers creates input risk for viral vector scale-up. Distribution runs through hospital procurement consortia in Europe, Gavi-funded national immunization programs in lower-income markets, and pharmacy channels in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recombinant vaccines market is entering a cyclical recovery phase as pandemic-era capacity overbuild absorbs into steady-state pediatric and oncology prevention demand. FDA accelerated approval pathway utilization and EMA adaptive framework maturation are restoring sponsor investment confidence.
For Market Incumbents: Build captive fermentation capacity moats through backward integration into critical raw materials like yeast extract and cell culture media. Merck's model of upstream control over input supply should guide facility investment in Maryland and Massachusetts clusters. Defensive consolidation around adjuvant science intellectual property counters emerging platform-agnostic contract manufacturers from South Korea. Channel control through direct hospital procurement consortia relationships in Germany and France protects pricing power against tender aggregation.
For New Entrants and Emerging Players: Establish a beachhead in plant-based expression systems using Nicotiana benthamiana platforms to bypass mammalian cell culture bottlenecks. The most penetrable segment is veterinary recombinant vaccines distributed through Brazil's agricultural extension networks, where ANVISA registration pathways are synchronizing with FDA review timelines. A go-to-market angle targeting pandemic response manufacturing contracts with national stockpile authorities leverages rapid deployment advantages over incumbent fixed facilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding viral vector capacity in Ireland and the Netherlands. Long-term viability over a 5-10 year window favors platform-agnostic manufacturers with modular, portable production units that can pivot between protein subunit and nucleic acid campaigns. The acquisition target archetype is mid-cap facilities with isolator-based filling lines already compliant with EMA revised GMP Annex 1. The signal to watch is WHO prequalification submission volume from South Korean and Chinese developers as an indicator of emerging market procurement competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for oncology prevention candidates. |
| Manufacturing Scale-Up | Modular bioreactor deployment in Maryland and Massachusetts clusters anchors viral vector supply security. |
| Backward Integration | Captive yeast extract and cell culture media production insulates margin from German supplier concentration. |
| Strategic Partnership | ANVISA-FDA parallel review synchronization accelerates dengue candidate access to Brazil's outbreak zone. |
| Pipeline Diversification | Self-amplifying RNA platform addition blurs manufacturing economics between nucleic acid and protein vaccines. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for this analysis. Primary interviews with formulary directors at German hospital consortia and Gavi procurement officers supplemented secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up patient population modeling and top-down manufacturer capacity assessments were triangulated against national immunization program expansion targets.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation dimensions including platform technology type, application area, delivery mechanism, and regional regulatory cluster. CAGRs were derived from epidemiological trend modeling, procurement pipeline visibility, and manufacturing capacity expansion announcements. Industry-specific inputs included Gavi co-financing commitment trajectories and EMA adaptive pathway utilization rates.
Stress conditions across regulatory pathway delays, single-use bioreactor supply disruptions, and cold chain infrastructure gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about immunization program expansion timelines and platform technology substitution rates. Quarterly review of WHO prequalification submission volumes, ANVISA parallel review activation, and EMA GMP inspection findings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Global Cardiovascular Drugs Market