
 Alpha-Glucosidase Inhibitors Market | 2026-2036
Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha-Glucosidase Inhibitors Market Outlook
Good Manufacturing Practice certification under ICH Q7 guidelines is collapsing the supplier base for alpha-glucosidase inhibitor APIs, forcing smaller intermediaries out of commercial production. Bayer AG leverages its vertical integration from fermentation to finished dose to sustain cost advantages in acarbose supply. Takeda Pharmaceutical Company anchors its position through specialized expertise in voglibose manufacturing, while Sun Pharmaceutical Industries competes aggressively on generic miglitol pricing across emerging markets.
Alpha-glucosidase inhibitors are a class of oral antihyperglycemic agents that functionally delay carbohydrate absorption in the small intestine by reversibly binding to intestinal alpha-glucosidase enzymes, with acarbose specifically exhibiting IC50 values in the micromolar range against glucoamylase. Their primary commercial purpose centers on managing postprandial blood glucose spikes in Type 2 diabetes patients who require glycemic control beyond basal insulin or metformin monotherapy. The oral delivery mode dominates prescription volumes due to patient convenience and decades of clinical familiarity, though combination therapy formats are capturing margin pools as physicians seek simplified regimens. Type 2 diabetes as a therapy area remains the mature revenue foundation, while metabolic syndrome applications represent the fastest-growing prescriber interest segment.
FDA bioequivalence standards for generic acarbose and EMA stability requirements under ICH Q1A(R2) govern market access, with both agencies tightening dissolution profile specifications that directly filter which manufacturers qualify for abbreviated new drug applications. India's CDSCO enforces parallel bioequivalence protocols for domestic generics, creating a three-jurisdiction compliance burden that shapes R&D allocation across the supplier landscape. Stakeholders must monitor how evolving pharmacopeial monographs for impurity profiles in fermentation-derived APIs will redistribute manufacturing advantage between synthetic and biosynthetic production routes.
Market Dynamics
ICH Q7 Good Manufacturing Practice certification is collapsing the supplier base for alpha-glucosidase inhibitor APIs, forcing smaller intermediaries out of commercial production and consolidating manufacturing advantage among vertically integrated fermentation specialists.
Growth Catalysts
- Postprandial glucose management protocols:Hospital pharmacies are expanding procurement of these agents as first-line therapy for patients requiring glycemic control beyond metformin monotherapy.
- CDSCO bioequivalence protocols:India's domestic regulatory framework for generic acarbose and miglitol is creating export-qualified manufacturing capacity that serves emerging markets.
- Fermentation-to-finished-dose integration:Captive supply of biosynthetic APIs is compressing cost structures for acarbose production versus synthetic routes.
Market Restraints
- API supply concentration:Fermentation-derived acarbose production clusters among three dominant suppliers, creating single-source vulnerability for generic formulators.
- Dissolution profile specifications:FDA and EMA tightening of bioequivalence standards for generic acarbose is filtering abbreviated new drug application approvals.
- GLP-1 receptor agonist substitution:Semaglutide and tirzepatide therapies are capturing Type 2 diabetes patients who would otherwise receive alpha-glucosidase inhibitor prescriptions.
Strategic Opportunities
- Metabolic syndrome applications:Prescriber interest in prediabetes and insulin resistance management is expanding addressable patient populations beyond diagnosed Type 2 diabetes.
- Combination therapy formats:Fixed-dose combinations with metformin or SGLT2 inhibitors are capturing margin pools as physicians seek simplified regimens.
- PLI scheme incentives:India's production-linked incentive framework for active pharmaceutical ingredients is attracting capital expenditure for domestic voglibose and miglitol manufacturing.
Industry Challenges
- Fermentation scale-up expertise:Qualified personnel for industrial microbiology and downstream processing of macrolide APIs remain scarce relative to synthetic chemistry talent pools.
- Impurity profile validation:Evolving pharmacopeial monographs for fermentation-derived contaminants require continuous analytical method redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha-Glucosidase Inhibitors Market |
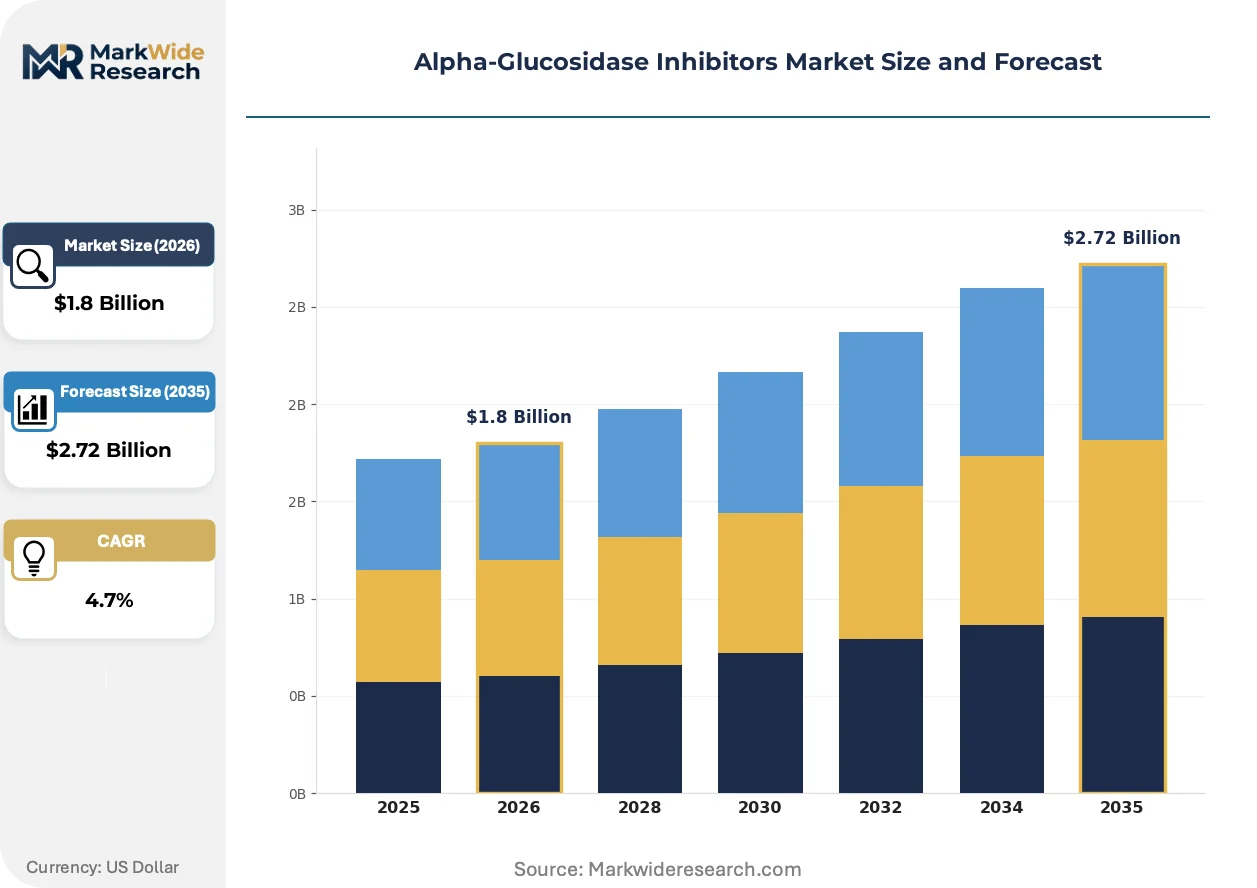
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others Therapy Area: Type 2 Diabetes, Obesity, Metabolic Syndrome, Others Delivery Mode: Oral, Injectable, Combination Therapy, Others End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Bayer AG, Takeda Pharmaceutical Company, Pfizer Inc., Sun Pharmaceutical Industries, Glenmark Pharmaceuticals, Merck & Co., Cipla Limited, Torrent Pharmaceuticals, Alkem Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha-Glucosidase Inhibitors Market Strategic Shifts
Continuous manufacturing technologies and real-time release testing are reshaping how alpha-glucosidase inhibitors are produced, shifting competitive advantage from batch-scale efficiency to process analytical technology integration.
Continuous flow fermentation systems coupled with in-line spectroscopic monitoring are displacing traditional batch fermentation for acarbose production. Mid-scale generic manufacturers in India and China are adopting these platforms to meet FDA dissolution profile specifications for abbreviated new drug applications. The technology is displacing legacy stainless-steel batch reactors that cannot achieve the process consistency required for tightened bioequivalence standards.
EMA stability requirements under ICH Q1A(R2) are forcing reformulation of alpha-glucosidase inhibitor tablets to meet accelerated and long-term storage protocols. Generic manufacturers must demonstrate comparable degradation profiles to originator products across temperature and humidity stress conditions. European hospital pharmacies are now requiring stability documentation that exceeds minimum regulatory thresholds, compressing supplier qualification timelines.
Hospital procurement consortia are consolidating purchasing of postprandial glucose management therapies through centralized tender processes. Group purchasing organizations are replacing individual pharmacy-level contracting, concentrating volume among suppliers with demonstrated bioequivalence documentation and supply security. This consolidation is most visible in India's tier-one cities where corporate hospital chains dominate diabetes care delivery.
Alpha-Glucosidase Inhibitors Market Segmentation
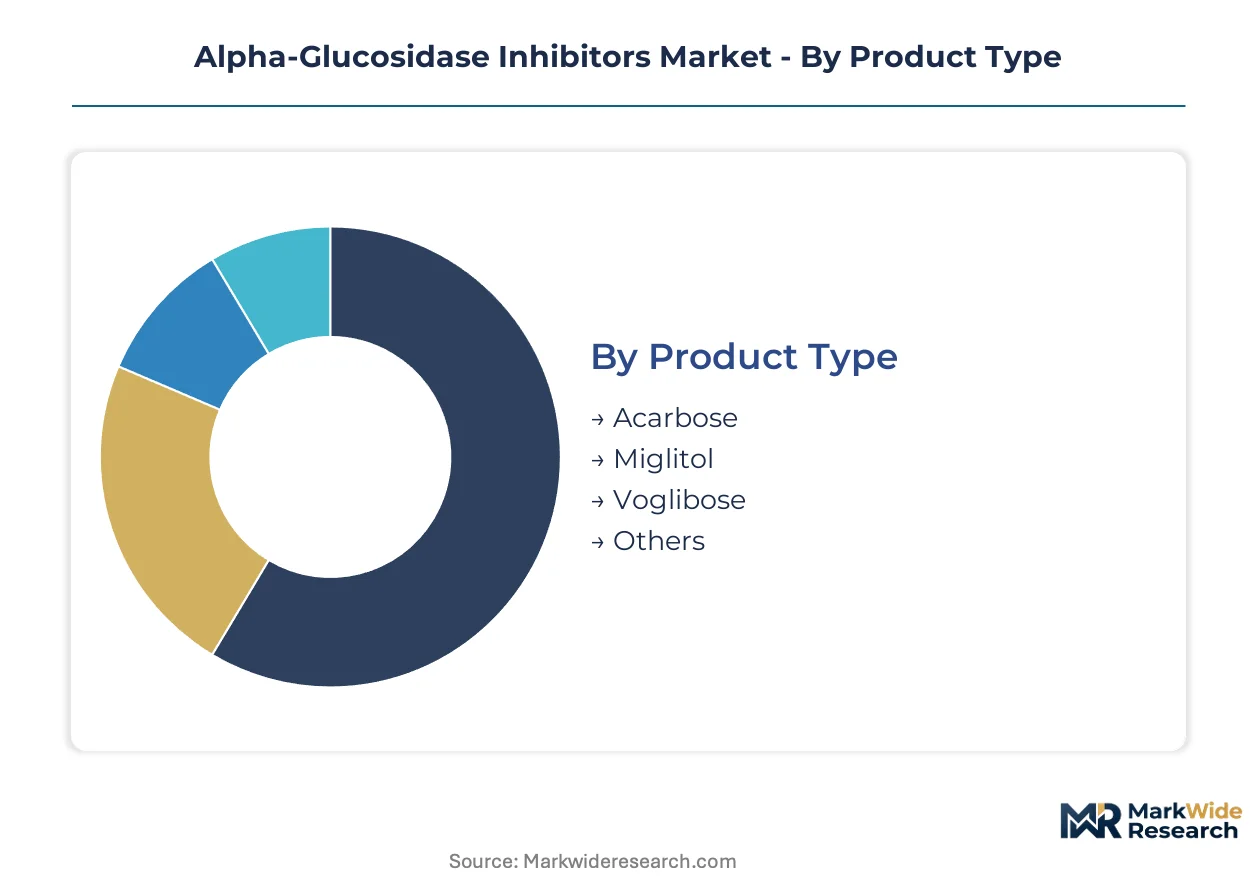
Segmentation in the alpha-glucosidase inhibitor market reveals how product chemistry, therapeutic application, and delivery format intersect to determine channel economics. Understanding these divisions exposes where formulation investment concentrates and which patient pathways drive procurement decisions.
Product Type:
Hospital pharmacies and retail chains source these agents through divergent procurement channels, with fermentation-derived products flowing through specialized distributors and synthetic alternatives competing on tender pricing.
- Acarbose:A pseudotetrasaccharide derived from Actinoplanes fermentation that irreversibly binds intestinal alpha-glucosidases. Hospital procurement consortia in India and China are expanding volume commitments for postprandial glucose protocols, though FDA dissolution specifications are filtering which generic suppliers qualify for centralized purchasing.
- Voglibose:A synthetic amino sugar with higher specificity for maltase and sucrase versus glucoamylase. Japanese hospital formularies and Southeast Asian retail pharmacies anchor demand, where Takeda's manufacturing expertise sustains premium positioning against emerging Indian generic competition.
- Miglitol:A desoxynojirimycin derivative produced through synthetic routes. Emerging market retail channels and clinic dispensing dominate procurement, with Sun Pharmaceutical and domestic Chinese manufacturers competing on price-accessibility for second-line therapy initiation.
- Others:Experimental analogs and region-specific formulations including emiglitate derivatives. Limited commercial penetration outside research hospital settings and niche European metabolic syndrome protocols.
By volume, acarbose leads across hospital and retail channels. By growth pace, voglibose is gaining share fastest in East Asian markets.
Therapy Area:
Cost tier differentiation separates premium-priced combination therapies from economy-positioned monotherapy, with reimbursement status determining which indications drive manufacturer margin capture.
- Type 2 Diabetes:The mature revenue foundation where alpha-glucosidase inhibitors serve as second-line or third-line therapy after metformin failure. Hospital pharmacy procurement in India, China, and Brazil concentrates volume here, though GLP-1 substitution is compressing new patient starts in insured populations.
- Metabolic Syndrome:Prediabetes and insulin resistance management represents the steepest expansion trajectory, with European endocrinology practices and Japanese preventive medicine clinics driving off-label prescriber interest ahead of formal indication expansion.
- Obesity:Adjunctive use for glycemic control in bariatric patient populations. Limited formulary penetration outside specialized metabolic surgery centers in Germany, South Korea, and select US academic medical centers.
- Others:Rare genetic glycogen storage disorders and investigational applications in polycystic ovary syndrome. Research hospital procurement only, with no commercial scale.
Type 2 diabetes commands absolute prescription volume. Metabolic syndrome applications are climbing the fastest as preventive medicine protocols expand.
Delivery Mode:
Volume concentration favors oral formats, while margin capture concentrates in combination products that simplify adherence for polypharmacy patients.
- Oral:Immediate-release and extended-release tablets dominate prescription volumes due to decades of clinical familiarity and patient self-administration convenience. Retail pharmacy dispensing in India, China, and Brazil sustains the channel, with bioequivalence documentation determining supplier qualification for hospital tenders.
- Combination Therapy:Fixed-dose combinations with metformin or SGLT2 inhibitors are capturing margin pools as physicians seek simplified regimens. European hospital formularies and Japanese clinic protocols are expanding procurement, with EMA stability requirements under ICH Q1A(R2) governing which manufacturers qualify.
- Injectable:No commercially available alpha-glucosidase inhibitor injectable formats exist; this segment captures experimental depot formulations and research protocols only.
- Others:Sublingual and orodispersible formulations in early development for dysphagia populations. No commercial presence.
Oral administration leads by prescription count. Combination therapy formats are expanding most quickly as adherence economics reshape prescribing patterns.
End User:
Customer type determines whether procurement flows through centralized tender processes or fragmented retail dispensing, with supply security requirements varying sharply.
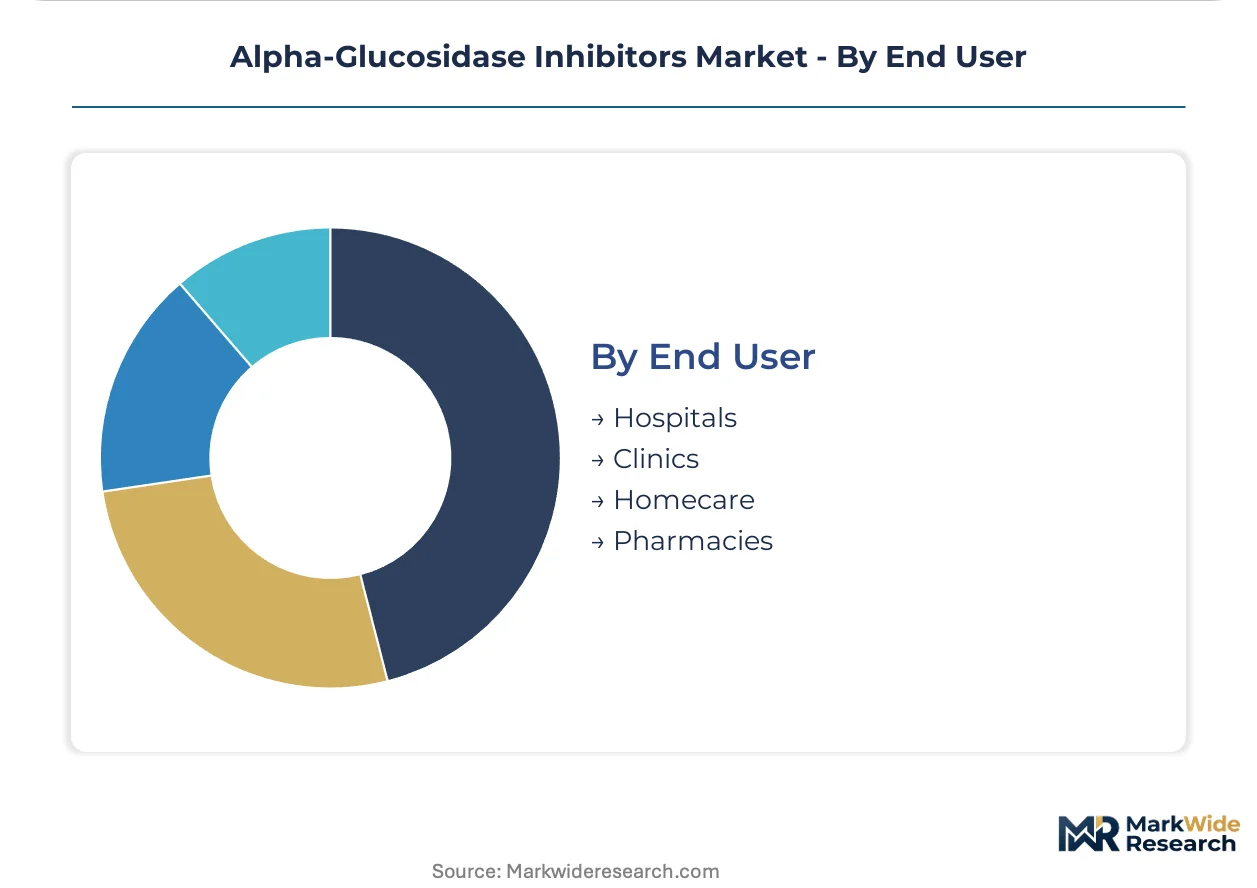
- Hospitals:Corporate hospital chains in India's tier-one cities and China's provincial medical centers are consolidating purchasing through group purchasing organizations. Bioequivalence documentation and supply security dominate qualification criteria, with fermentation-derived acarbose suppliers holding advantage.
- Clinics:Endocrinology and diabetes specialty practices in Japan, Germany, and Brazil drive voglibose and miglitol prescribing. Dispensing privileges and direct patient access create margin opportunities distinct from hospital tender economics.
- Homecare:Long-term diabetes management programs and visiting nurse services in aging populations. Limited alpha-glucosidase inhibitor penetration due to meal-timing complexity versus simpler basal insulin regimens.
- Pharmacies:Retail chains and independent dispensers in emerging markets handle the majority of generic acarbose and miglitol volume. CDSCO-compliant Indian manufacturers serve both domestic price-sensitive demand and export markets across Africa and Southeast Asia.
Hospitals lead by procurement value. Clinics are gaining share fastest as specialty diabetes care fragments from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Jawaharlal Nehru Port corridor anchors India's pharmaceutical export infrastructure for alpha-glucosidase inhibitors. Fermentation-derived API clusters in Gujarat and Maharashtra feed formulation plants serving domestic hospital consortia and African export markets.
United States
Hospital procurement consortia and group purchasing organizations concentrate demand for postprandial glucose management therapies. FDA bioequivalence standards for generic acarbose filter abbreviated new drug application approvals. The New Jersey-Pennsylvania pharmaceutical corridor hosts formulation specialists supplying hospital chains and retail pharmacy networks.
Germany
Specialized diabetes clinics and academic medical centers drive voglibose prescribing for metabolic syndrome protocols. EMA stability requirements under ICH Q1A(R2) govern which manufacturers qualify for European hospital tenders. The Rhine-Main industrial region anchors distribution networks serving hospital pharmacies across Central Europe.
China
Provincial medical centers and corporate hospital chains expand volume commitments for acarbose as second-line therapy. NMPA dissolution profile specifications align with FDA tightening for generic qualification. The Yangtze River Delta fermentation cluster supplies biosynthetic APIs to domestic formulators and Southeast Asian export markets.
Japan
Preventive medicine clinics and endocrinology practices anchor voglibose demand for prediabetes management ahead of formal indication expansion. PMDA manufacturing standards for fermentation-derived APIs sustain premium positioning against generic competition. The Kansai-Osaka pharmaceutical belt concentrates formulation capacity for domestic and regional supply.
Brazil
Public health system tenders and private hospital chains drive miglitol procurement for Type 2 diabetes protocols. ANVISA bioequivalence protocols for generic acarbose create compliance thresholds for market entry. The São Paulo state industrial corridor hosts formulation plants serving the Mercosur regional market.
Alpha-Glucosidase Inhibitors Market Competitive Environment
Listed leaders compete with private specialists across fermentation capacity and generic formulation expertise. The supplier base concentrates among vertically integrated fermentation specialists and mid-scale generic manufacturers competing on tender pricing. Three archetypes dominate: captive fermentation-to-finished-dose integrators, synthetic chemistry specialists, and emerging market generic formulators. Competitive moves center on backward integration into API production and geographic expansion through CDSCO-qualified export capacity.
Within the fermentation-integrated tier, Bayer AG exemplifies captive supply chain architecture from biosynthetic API through finished dose. Among Japanese pharmaceutical specialists, Takeda Pharmaceutical Company occupies a position representing specialized expertise in amino sugar manufacturing. At the emerging market generic end, Sun Pharmaceutical Industries and Cipla Limited sit within the price-competitive formulation segment serving hospital procurement consortia and retail pharmacy networks across India, Africa, and Southeast Asia.
| Leading Market Players |
|---|
| Bayer AG |
| Takeda Pharmaceutical Company |
| Pfizer Inc. |
| Sun Pharmaceutical Industries |
| Glenmark Pharmaceuticals |
| Merck & Co. |
| Cipla Limited |
| Torrent Pharmaceuticals |
| Alkem Laboratories |
| Others |
Value Chain & Pricing Dynamics
GLP-1 receptor agonist substitution for postprandial glucose management is simultaneously relocating manufacturing investment from synthetic chemistry hubs toward fermentation-capable geographies and compressing pricing power across acarbose and miglitol tiers. This displacement dynamic concentrates API procurement leverage among Indian and Chinese suppliers with captive biosynthetic capacity while forcing European and North American formulators into cost-passing negotiations with hospital procurement consortia.
Pricing Analysis
Certification level under ICH Q7 and FDA bioequivalence standards creates the primary spread between premium-positioned originator products and economy-tier generics. Three-tier pricing structure across originator-grade, CDSCO-qualified export, and domestic-only unbranded levels stratifies hospital tender outcomes, with EMA stability documentation commanding 15-20% premia over minimum-threshold alternatives. Cost compression in Indian domestic retail channels is intensifying because Sun Pharmaceutical and Cipla Limited are expanding volume-based contract structures. Hospital procurement consortia in tier-one Indian cities exhibit lowest price sensitivity due to formulary continuity requirements, while independent retail pharmacies across Africa and Southeast Asia drive aggressive tender competition.
Supply Chain Analysis
Inventory lead times for fermentation-derived acarbose APIs extend 8-12 weeks longer than synthetic miglitol alternatives due to downstream processing complexity and microbiological contamination testing protocols. Manufacturing gravity centers on India, China, and Japan, with the Mumbai-Jawaharlal Nehru Port corridor and Yangtze River Delta fermentation clusters anchoring global API flow. Active pharmaceutical ingredient production draws from Actinoplanes bacterial cultures, corn starch feedstocks, and specialized chromatography resins. Single-source vulnerability concentrates among three dominant acarbose fermentation suppliers, creating qualification risk for generic formulators dependent on external API procurement. Distribution runs through specialized pharmaceutical distributors serving hospital consortia and retail pharmacy networks, with CDSCO-compliant Indian manufacturers capturing emerging market export volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across prescriber preference—between metabolic syndrome prevention protocols and established Type 2 diabetes management—creates multiple niche entry points for differentiated positioning. This demand-side divergence rewards suppliers with formulation flexibility and regional regulatory expertise over scale-driven commodity competitors.
For Market Incumbents: Secure backward integration into fermentation capacity or long-term API offtake agreements with Gujarat and Maharashtra suppliers to defend against generic pricing erosion. Bayer AG's captive supply chain architecture from Actinoplanes culture to finished dose exemplifies the structural advantage; competitors must replicate this upstream control or accept margin compression from API spot market volatility. Hospital procurement consolidation demands bioequivalence documentation investments that smaller formulators cannot sustain. For New Entrants and Emerging Players: CDSCO bioequivalence fast-track certification for voglibose synthetic routes opens qualification pathways into Southeast Asian hospital tenders where Takeda's premium positioning leaves price-accessible gaps. Metabolic syndrome applications in European preventive medicine clinics represent the most penetrable prescriber segment, with off-label expansion ahead of formal indication growth enabling first-mover formulary capture. Direct-to-clinic dispensing partnerships bypass consolidated hospital purchasing and capture margin pools unavailable to tender-dependent competitors. For Investors and Strategic Acquirers: The market sits at a substitution-vulnerability phase that favors fermentation-capable API specialists with demonstrated FDA dissolution profile compliance. Long-term viability hinges on positioning for post-GLP-1 stabilization where alpha-glucosidase inhibitors retain cost-accessibility advantages in emerging markets and combination therapy formats. Acquisition targets should demonstrate ICH Q7 certification, captive bacterial strain libraries, and established CDSCO export channels. The signal to watch is EMA pharmacopeial monograph evolution for impurity profiles, which will redistribute manufacturing advantage between synthetic and biosynthetic production routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive API supply compresses cost structures versus spot market dependence for acarbose production. |
| CDSCO Bioequivalence Certification Investment | Qualifies manufacturers for Indian hospital consortia and African export market access. |
| Fixed-Dose Combination Development | Captures margin pools in European and Japanese adherence-focused prescribing protocols. |
| Continuous Manufacturing Technology Adoption | Meets tightened FDA dissolution specifications that disqualify legacy batch fermentation competitors. |
| Metabolic Syndrome Indication Expansion | Addresses fastest-growing prescriber interest segment in European preventive medicine clinics. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation operations directors, regulatory affairs leads at generic manufacturers, hospital procurement managers, and CDSCO compliance officers, then refined against secondary validation. Primary interviews explored ICH Q7 implementation costs, bioequivalence study design patterns, and tender pricing dynamics across Indian, Chinese, and European procurement contexts. Secondary sources encompassed FDA ANDA filings, EMA assessment reports, CDSCO manufacturing license databases, and pharmacopeial monograph evolution for fermentation-derived APIs. Bottom-up volume estimates from API production capacity and top-down demand triangulation from diabetes prevalence and treatment algorithm penetration were cross-referenced to establish forecast anchors.
Variance decomposition across product chemistry, therapy area, delivery mode, and geographic regulatory cluster shaped the analytical framework. Segmentation modeling tracked acarbose, voglibose, and miglitol demand through Type 2 diabetes, metabolic syndrome, and emerging obesity applications, with oral monotherapy and combination therapy formats treated as distinct margin pools. CAGRs were derived from prescription volume trajectories, pricing elasticity assumptions, and substitution rate modeling for GLP-1 receptor agonist displacement. Forecast inputs incorporated hospital procurement consolidation timelines, PLI scheme incentive disbursement patterns, and evolving pharmacopeial impurity thresholds.
Underlying assumptions cover sustained ICH Q7 enforcement intensity, stable Actinoplanes strain productivity, and continued CDSCO-FDA bioequivalence alignment, with deviation risk concentrated in GLP-1 substitution acceleration and fermentation scale-up bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market