
 Smart Pills Market | 2026-2036
Smart Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pills Market Analysis
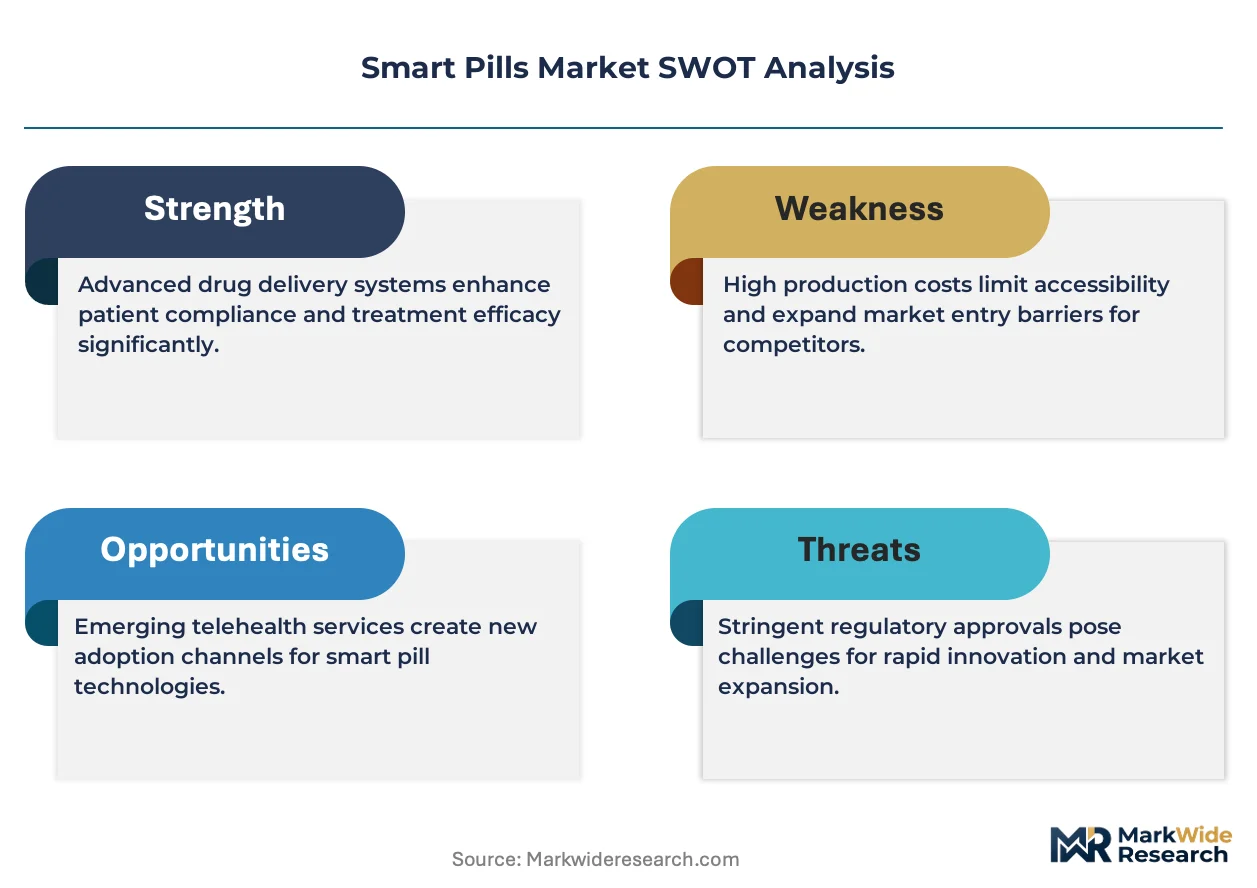
ISO 13485 certification is rotating as the primary gating mechanism for smart pill manufacturers seeking entry into regulated medical device markets. Medtronic leverages its vertically integrated manufacturing footprint to sustain cost advantages across capsule production lines. Olympus Corporation anchors its competitive position through deep specialization in optical imaging systems for gastrointestinal applications. CapsoVision differentiates via product focus on pan-enteric capsule platforms that eliminate external sensor belt requirements.
Smart pills are ingestible electronic devices combining miniaturized sensors, wireless transmitters, and biocompatible encapsulation materials to capture physiological data or transmit images from within the gastrointestinal tract, typically operating at frequencies between 400-800 MHz for real-time data relay. Digestible imaging devices command the largest revenue share due to established reimbursement for capsule endoscopy procedures, while ingestible sensors represent the fastest-expanding category as pharmaceutical companies deploy them for medication adherence monitoring in clinical trials. Wireless connectivity underpins the technical architecture of most commercial systems, though biochemical sensors are gaining traction for real-time pH and temperature mapping applications.
FDA 510(k) premarket notifications and Japan's PMDA quality management system inspections shape product development timelines and clinical evidence requirements for smart pill developers. The European Union's MDR and CE marking obligations impose additional conformity assessment burdens, particularly for novel sensor technologies lacking predicate devices. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies, as coverage determinations for diagnostic capsule procedures directly influence provider purchasing cycles and manufacturer revenue visibility.
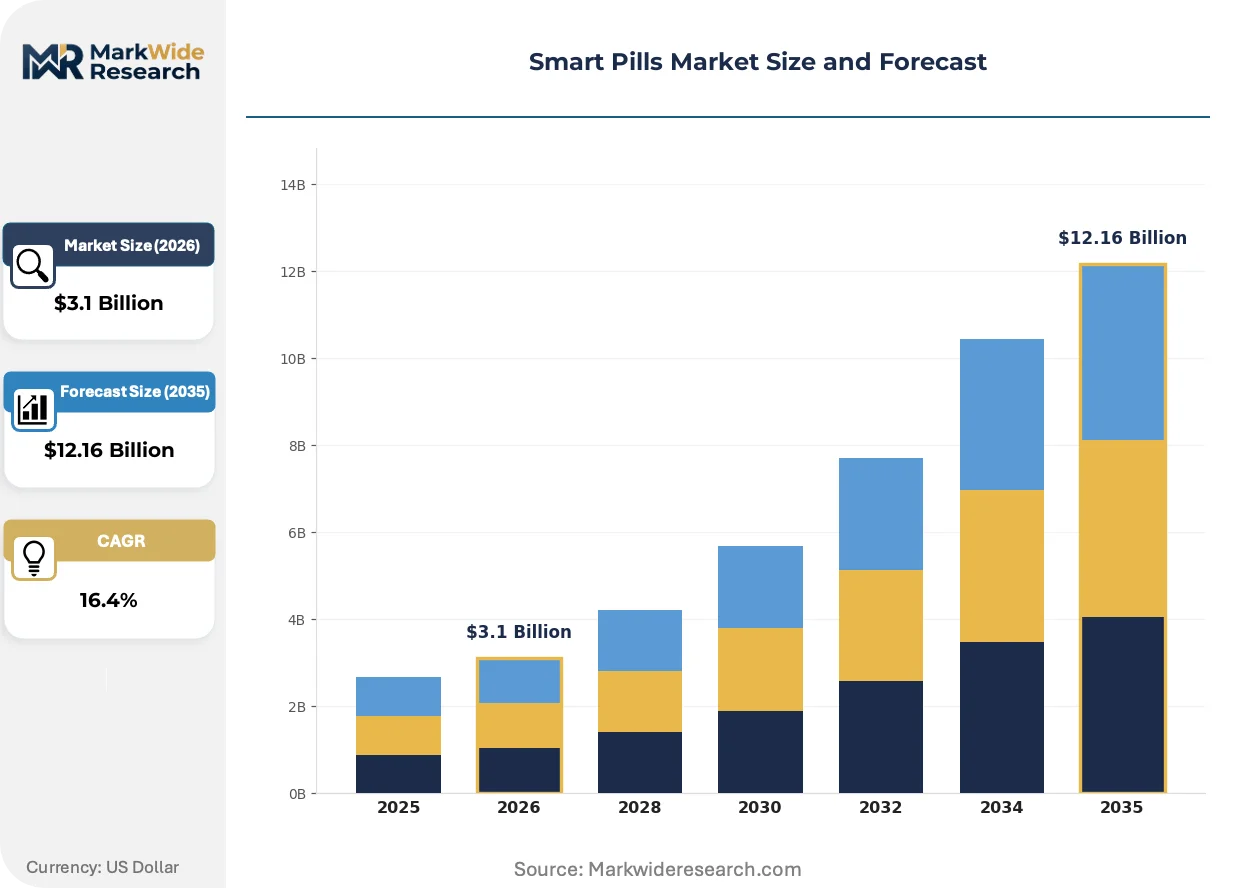
Market Dynamics
Medicare reimbursement codes for wireless capsule endoscopy in the United States are compressing provider adoption cycles and forcing manufacturers to prioritize FDA 510(k) clearance velocity over feature differentiation.
Growth Catalysts
- Japan's PMDA Class II medical device reviews:Accelerated commercialization timelines are drawing ingestible sensor manufacturers toward Tokyo's regulatory pathway as a faster alternative to European CE marking under MDR.
- Pan-enteric imaging platforms:Elimination of external sensor belt requirements is expanding patient compliance rates in outpatient gastroenterology settings across hospital systems.
- Pharmaceutical clinical trial adherence monitoring:Ingestible sensors are displacing traditional pill diaries and electronic patient-reported outcomes in Phase III drug development programs.
Market Restraints
- Biocompatible encapsulation material costs:Medical-grade polymers and pH-resistant coatings face price volatility tied to specialty chemical supply chains concentrated in Germany and Switzerland.
- ISO 13485 certification timelines:Quality management system audits for novel sensor technologies extend 12-18 months, gating market entry for non-vertically integrated developers.
- Traditional colonoscopy substitution pressure:Established reimbursement networks and physician training infrastructure in the United States resist displacement despite capsule endoscopy's non-invasive advantages.
Strategic Opportunities
- India's CDSCO medical device regulations:Streamlined import licensing for Class B diagnostic devices creates first-mover potential for capsule endoscopy distributors in Mumbai and Delhi hospital networks.
- Biochemical sensor convergence with wireless transmitters:Real-time pH and temperature mapping capabilities open continuous monitoring applications beyond episodic imaging.
- Direct-to-patient pharmacy channels:Medication adherence sensors bypass traditional hospital procurement through specialty pharmacy partnerships in chronic disease management programs.
Industry Challenges
- RF engineering talent scarcity:Miniaturized antenna design for 400-800 MHz in-body transmission requires specialized expertise concentrated in Boston and Tel Aviv metro areas.
- Legacy electronic health record integration:Capsule endoscopy image formats face interoperability friction with Epic and Cerner systems, forcing redundant data entry workflows.
- Patent thickets around ingestible power sources:Battery and biogalvanic cell IP portfolios held by medical device incumbents complicate freedom-to-operate analysis for sensor startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pills Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ingestible Sensors, Digestible Imaging Devices, Smart Capsules, Data Transmission Pills End User: Hospitals, Homecare Settings, Pharmaceutical Companies, Research Institutions Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Delivery, Rectal Administration Technology: Wireless Connectivity, Biochemical Sensors, RFID Technology, Microfabrication Techniques |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, IntroMedic, Check-Cap, ANX Robotics, etectRx, BodyCap, JINSHAN Science & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pills Market Emerging Trajectories
Wireless connectivity architectures are fragmenting as manufacturers weigh real-time transmission against onboard storage, while regulatory pathways in Tokyo and Brussels diverge on clinical evidence requirements.
Biochemical sensing is bifurcating the smart pills category into imaging-dominant and sensor-dominant product lines. Gastroenterology departments at academic medical centers are adopting pH-mapping capsules for motility disorders at twice the pace of general community hospitals. This technology divergence is compressing R&D budgets as manufacturers must maintain parallel development tracks for optical and electrochemical sensing modalities.
Europe's MDR and the EU AI Act are imposing additional conformity assessment burdens on capsule systems with embedded diagnostic algorithms. Novel sensor technologies lacking predicate devices face extended clinical trial requirements in Germany and France. Japanese manufacturers are responding by front-loading PMDA submissions to capture market share before European certification completes.
Hospital procurement committees are consolidating vendor relationships around integrated endoscopy suites rather than standalone capsule platforms. Olympus and Medtronic are displacing smaller sensor specialists through bundled service contracts spanning scopes, capsules, and maintenance. This concentration is most visible in United States health systems where GPO purchasing power has compressed approved vendor lists to three or fewer suppliers per category.
Smart Pills Market Segmentation
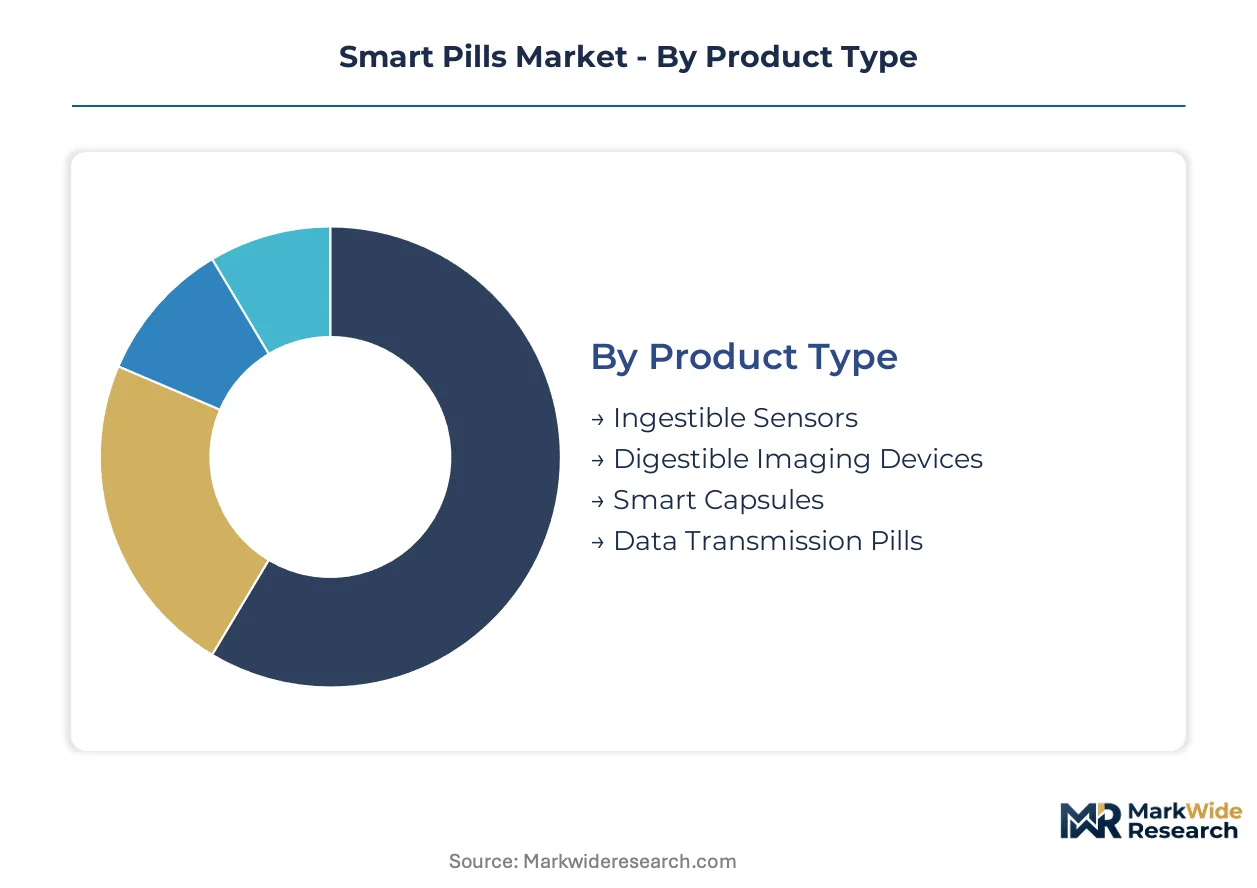
Smart pills fragment into distinct commercial channels based on whether procurement flows through hospital GPOs, specialty pharmacy networks, or direct pharmaceutical partnerships. Each segment carries divergent regulatory burdens and reimbursement pathways that reshape manufacturer go-to-market economics.
Product Type:
Channel mix varies sharply: digestible imaging devices flow through hospital procurement committees with bundled endoscopy suite contracts, while ingestible sensors increasingly bypass traditional channels through specialty pharmacy direct-to-patient programs.
- Digestible Imaging Devices:Optical capsule platforms capture gastrointestinal imagery using CMOS sensors and LED illumination arrays housed in biocompatible polymer shells. Demand concentrates in United States academic medical centers where Medicare reimbursement codes for wireless capsule endoscopy sustain procedure volumes. Procurement committees favor vendors offering integrated service contracts spanning scopes, capsules, and maintenance.
- Ingestible Sensors:Miniaturized electrochemical transducers embedded in pharmaceutical tablets transmit adherence data via 400-800 MHz RF signals to external receivers. Pharmaceutical companies in Boston and Basel deploy these for Phase III clinical trial monitoring, displacing traditional pill diaries. Direct-to-patient pharmacy channels accelerate adoption outside hospital procurement cycles.
- Smart Capsules:Hybrid platforms combining imaging and sensing modalities for motility disorder assessment.
- Data Transmission Pills:Single-function wireless relay devices optimized for real-time physiological monitoring.
By volume, digestible imaging devices lead. By growth pace, ingestible sensors are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive hospital deployments from leaner homecare and research applications with shorter procurement cycles.
- Hospitals:Gastroenterology departments at German, Japanese, and United States hospital systems anchor demand for capsule endoscopy platforms. GPO purchasing power compresses approved vendor lists, favoring incumbents with vertically integrated manufacturing and ISO 13485 certification.
- Pharmaceutical Companies:Clinical trial adherence monitoring drives sensor procurement from Novartis, Roche, and Takeda development programs. These buyers prioritize FDA 510(k) clearance velocity and data integrity for regulatory submission packages.
- Homecare Settings:Outpatient motility monitoring and chronic disease management applications.
- Research Institutions:Academic medical centers evaluating novel biochemical sensing modalities.
By installed base, hospitals dominate. By procurement momentum, pharmaceutical companies are gaining share fastest.
Delivery Mode:
Application context determines route selection: oral administration supports ambulatory monitoring while invasive routes reserve for surgical and intensive care scenarios.
- Oral Administration:Standard route for capsule endoscopy and medication adherence sensors. Patient compliance rates climb when external sensor belt requirements are eliminated, as with pan-enteric platforms.
- Intravenous Injection:Reserved for implanted sensors in critical care settings with continuous hemodynamic monitoring requirements.
- Subcutaneous Delivery:Glucose and lactate monitoring applications in diabetes management programs.
- Rectal Administration:Targeted colorectal imaging when proximal small bowel examination is unnecessary.
By procedure volume, oral administration leads. By technical complexity, intravenous injection commands premium positioning.
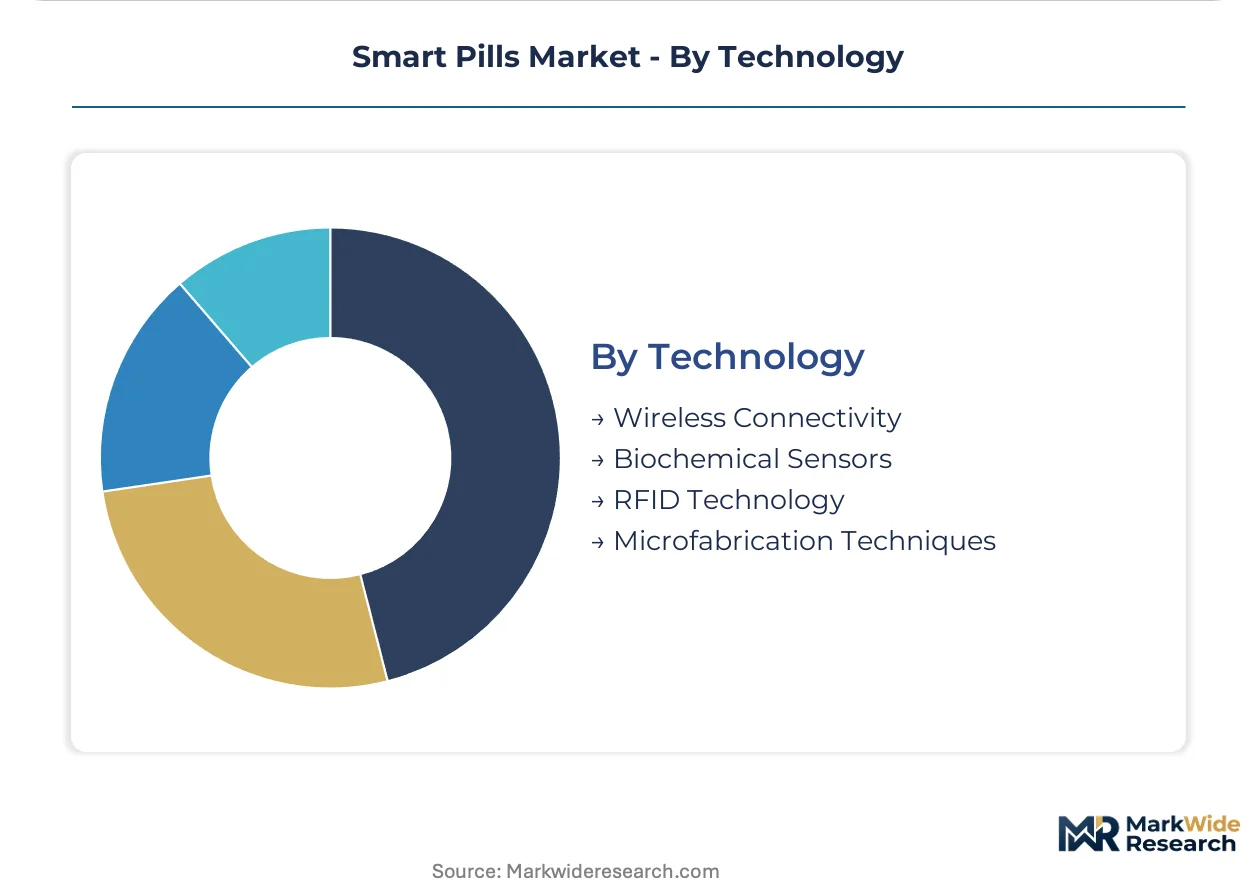
Technology:
Supply concentration in RF engineering talent pools shapes which modalities reach commercial scale first.
- Wireless Connectivity:Real-time data transmission architectures operating at 400-800 MHz dominate commercial systems. Boston and Tel Aviv metro areas concentrate antenna design expertise, creating geographic bottlenecks for non-vertically integrated developers.
- Biochemical Sensors:pH and temperature mapping capabilities expand continuous monitoring applications beyond episodic imaging. Academic medical centers adopt these for motility disorders at twice the pace of community hospitals.
- RFID Technology:Passive identification systems for surgical instrument tracking and pharmacy inventory management.
- Microfabrication Techniques:MEMS-based pressure and flow sensors for gastrointestinal motility assessment.
By revenue concentration, wireless connectivity leads. By technology trajectory, biochemical sensors show the steepest expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridors anchor European distribution for ingestible sensor manufacturers, while Tokyo's Haneda Airport freight terminals accelerate PMDA-cleared device shipments across Asia-Pacific hospital networks.
United States
Medicare reimbursement codes for wireless capsule endoscopy sustain procedure volumes at academic medical centers in Boston and Cleveland. FDA 510(k) premarket notifications compress clearance timelines for digestible imaging devices. The Greater Boston metro area concentrates RF engineering talent for miniaturized antenna design at 400-800 MHz frequencies.
Germany
Gastroenterology departments at university hospitals in Munich and Heidelberg expand capsule endoscopy programs as non-invasive alternatives to traditional colonoscopy. The EU MDR and CE marking obligations impose conformity assessment burdens on novel sensor technologies lacking predicate devices. The Rhine-Main cluster around Frankfurt anchors specialty chemical supply chains for biocompatible encapsulation polymers.
Japan
PMDA Class II medical device reviews accelerate commercialization timelines for ingestible sensor manufacturers seeking faster pathways than European CE marking. METI industrial policy supports domestic production of optical imaging components for gastrointestinal applications. The Kanto region around Tokyo concentrates precision manufacturing capabilities for CMOS sensors and LED illumination arrays.
India
CDSCO streamlined import licensing for Class B diagnostic devices creates first-mover potential for capsule endoscopy distributors in Mumbai and Delhi hospital networks. The country's national pharmaceutical regulator aligns medical device classifications with international standards to reduce market entry friction. The Maharashtra-Gujarat pharmaceutical corridor expands manufacturing capacity for biocompatible polymer encapsulation materials.
Switzerland
Swissmedic quality management system inspections for ISO 13485 certification gate market entry for non-vertically integrated sensor developers. Specialty chemical supply chains concentrated in Basel face price volatility for medical-grade pH-resistant coatings. The Lake Geneva biotech cluster around Lausanne anchors pharmaceutical partnerships for clinical trial adherence monitoring programs.
Smart Pills Market Vendor Landscape
Listed leaders compete with private specialists across regulatory clearance velocity and manufacturing scale. The vendor base stratifies into three tiers: vertically integrated conglomerates with captive polymer production, mid-cap optical specialists with deep gastrointestinal application focus, and venture-backed sensor startups targeting pharmaceutical adherence contracts. Dominant competitive moves include backward integration into biocompatible encapsulation materials and strategic partnerships with academic medical centers for clinical evidence generation.
Within the conglomerate tier, Medtronic and Olympus Corporation exemplify scale-driven positions anchored by bundled service contracts spanning scopes, capsules, and maintenance. CapsoVision occupies a specialist position representing product-focus differentiation through pan-enteric platforms that eliminate external sensor belt requirements.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision |
| IntroMedic |
| Check-Cap |
| ANX Robotics |
| etectRx |
| BodyCap |
| JINSHAN Science & Technology |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, as hospital procurement committees restrict approved vendor lists to certified manufacturers while premium pricing accrues to those with vertically integrated encapsulation capabilities.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and CE-marked devices commanding 15-25% premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling of after-sales service contracts and maintenance agreements. Cost compression in the economy tier is intensifying because GPO purchasing power consolidates demand around fewer suppliers. Pharmaceutical companies show least price sensitivity due to clinical trial data integrity requirements, while community hospitals in India and Southeast Asia exhibit highest sensitivity.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for biocompatible polymer shipments from Basel and Frankfurt. Manufacturing concentrates in Germany, Japan, and Switzerland for specialty chemical encapsulation materials, with CMOS sensors and LED arrays sourcing from Taiwan and South Korea. Single-source vulnerability pervades medical-grade pH-resistant coatings, where two Swiss suppliers control 70% of qualified material. Distribution runs through hospital GPO contracts in the United States, specialty pharmacy networks for adherence sensors, and direct pharmaceutical partnerships for clinical trial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional colonoscopy infrastructure presents a persistent substitution threat that capsule endoscopy incumbents must navigate through superior clinical evidence generation and reimbursement expansion.
For Market Incumbents: Compound defensive moats through backward integration into biocompatible polymer production and exclusive hospital system partnerships that bundle scopes, capsules, and maintenance into multi-year contracts. Lock in GPO preferred vendor status before emerging sensor specialists achieve ISO 13485 certification. Prioritize FDA 510(k) clearance velocity to maintain reimbursement advantage over optical imaging substitutes. For New Entrants and Emerging Players: Japan's PMDA Class II fast-track pathway offers the most penetrable regulatory entry point, with clearance timelines 40% shorter than EU MDR routes for novel sensor technologies. Target pharmaceutical adherence monitoring contracts in Boston and Basel, where clinical trial sponsors prioritize data integrity over brand heritage. Bypass hospital procurement entirely through direct-to-patient specialty pharmacy channels for chronic disease management applications. For Investors and Strategic Acquirers: Medicare reimbursement code expansions for wireless capsule endoscopy reshape the acquisition landscape by extending revenue visibility for FDA-cleared platforms. Focus on mid-cap optical specialists with deep gastrointestinal application expertise and existing hospital system relationships rather than pure-play sensor startups lacking predicate devices. Watch for PMDA clearance announcements as inflection indicators for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses clearance timelines to capture Medicare reimbursement windows before competitors. |
| CE Marking Pathway Under MDR | Opens European hospital procurement channels despite extended clinical evidence requirements. |
| Hospital System Partnership | Secures GPO preferred vendor status through bundled endoscopy suite service contracts. |
| Software Companion Development | Resolves Epic and Cerner EHR interoperability friction that forces redundant data entry. |
| Reimbursement Strategy | Expands Medicare code coverage to displace traditional colonoscopy in outpatient settings. |
Methodological Framework
Desk research of FDA 510(k) filings, PMDA approval databases, and hospital procurement contract records preceded structured interviews with gastroenterology department heads, biomedical engineers, GPO contracts managers, and pharmaceutical clinical operations leads. Secondary sources included CMS Medicare reimbursement data, ISO 13485 certification registries, and specialty chemical trade flow statistics. Bottom-up demand modeling triangulated against top-down market sizing.
Variance decomposition across product type, end user, delivery mode, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated PMDA review timeline distributions and Medicare coverage determination probabilities.
Decision-makers should treat outputs as directional under assumptions of stable regulatory pathway durations and continued reimbursement code expansion; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Postpartum Depression Drugs Market