
 Behavioral Rehabilitation Market | 2026-2036
Behavioral Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
Behavioral Rehabilitation Market Intelligence
Market Context
Digital biomarker integration is broadening the economic viability of remote patient monitoring in behavioral care. Acadia Healthcare leverages its national facility footprint to anchor inpatient capacity across underserved regions. Universal Health Services sustains operational scale through diversified service lines spanning acute psychiatric and residential treatment. Magellan Health competes via carved-out behavioral health plans that control payer channel access.
Technical Definition and Segments
Behavioral rehabilitation encompasses structured therapeutic interventions designed to modify maladaptive cognitive patterns, emotional responses, and conduct disorders through evidence-based protocols administered in clinical or virtual settings. These programs typically operate on standardized session frequencies, licensed practitioner ratios, and outcome measurement frameworks to restore functional capacity in occupational, social, and residential domains. Cognitive Behavioral Therapy occupies the largest share of therapy type revenue due to its established reimbursement codes and workforce training infrastructure, while Teletherapy represents the fastest-expanding service model as asynchronous platforms reduce geographic barriers to licensed care. Intensive Outpatient Programs command premium positioning by bridging the gap between inpatient acuity and outpatient flexibility.
Regulatory Frame and Outlook
The FDA oversees digital therapeutic submissions for software-based behavioral interventions, while CMS determines Medicare coverage parameters that dictate provider revenue stability; state insurance commissioners enforce parity mandates that shape commercial plan design. HIPAA compliance requirements constrain data architecture choices for platforms capturing sensitive mental health records across state lines. Stakeholders must monitor evolving state licensure reciprocity agreements that determine whether teletherapy providers can serve patients across jurisdictional boundaries without physical presence.
Market Dynamics
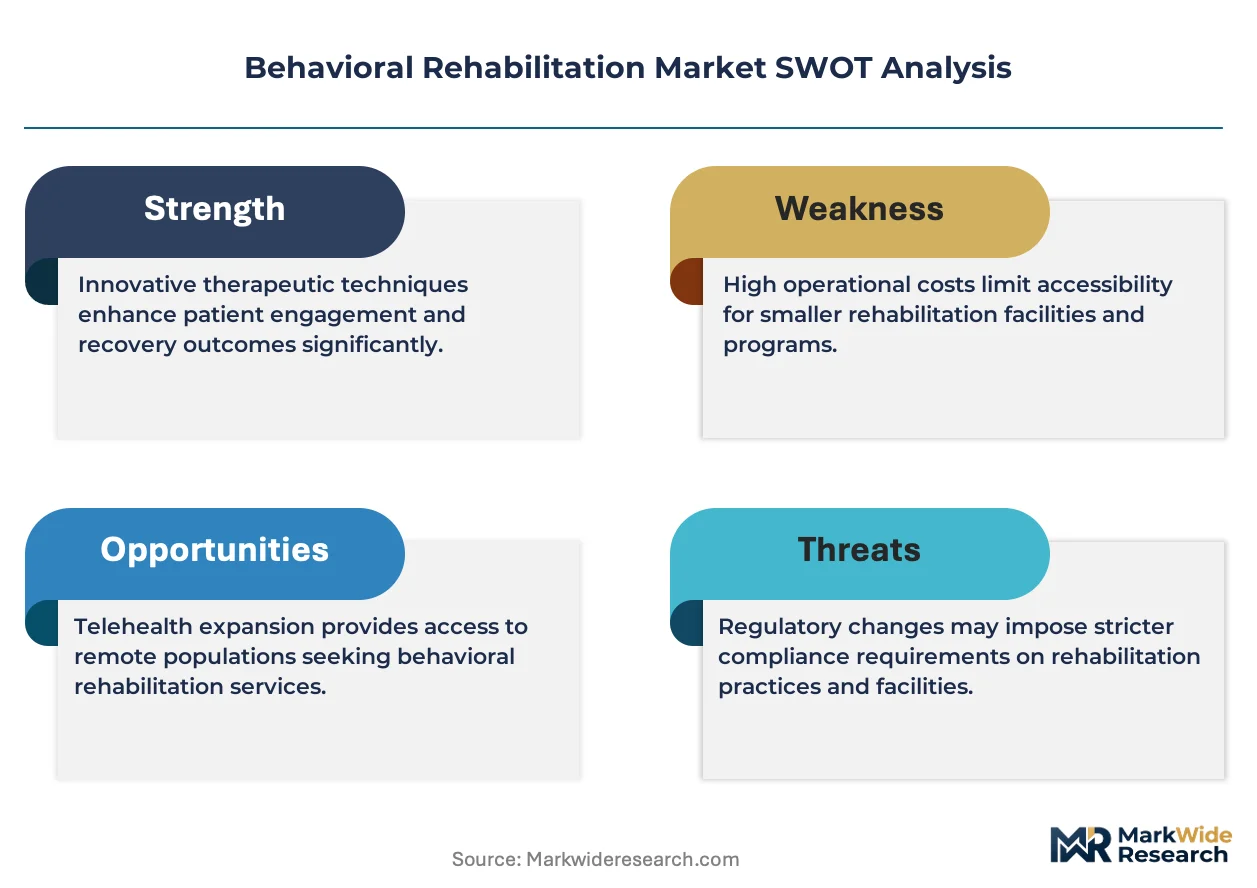
Reimbursement parity mandates across US states are compressing the gap between behavioral and physical health coverage, forcing providers to restructure service delivery models around value-based contracting frameworks.
Growth Catalysts
- Medicare Coverage Expansion:CMS reimbursement for intensive outpatient programs is pulling elderly patients into structured behavioral interventions previously gated by out-of-pocket cost barriers.
- Telehealth Licensure Reciprocity:Interstate compacts for practitioner licensing are dissolving geographic supply constraints that historically limited rural patient access to credentialed specialists.
- Digital Biarker Integration:Wearable-derived physiological markers are validating remote therapeutic monitoring protocols, enabling CMS billing codes for asynchronous care supervision.
Market Restraints
- Workforce Supply Concentration:Licensed clinical social workers cluster in coastal metropolitan corridors, leaving interior regions dependent on travel clinicians with elevated locum tenens cost structures.
- HIPAA Compliance Architecture:State-by-state privacy law fragmentation forces platform operators to maintain redundant data infrastructure, inflating per-patient technology overhead.
- Inpatient Bed Scarcity:Psychiatric facility closures in rural counties concentrate acute capacity within urban hospital systems, extending wait times for crisis stabilization services.
Strategic Opportunities
- Employer-Sponsored EAP Convergence:Fortune 500 benefits administrators are consolidating vendor relationships, creating openings for integrated behavioral-primary care platforms.
- Justice-Involved Populations:State corrections departments are outsourcing reentry mental health services to community-based providers under performance-based contracts.
- School-Based Intervention Mandates:State education department requirements for on-campus counseling are generating demand for district-wide service partnerships.
Industry Challenges
- Credentialing Timeline Compression:Payer enrollment processes for newly licensed practitioners extend 90-120 days, delaying revenue recognition for expansion-stage providers.
- Interoperability Friction:Electronic health record fragmentation between acute and behavioral settings obstructs care coordination and quality measurement reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behavioral Rehabilitation Market |
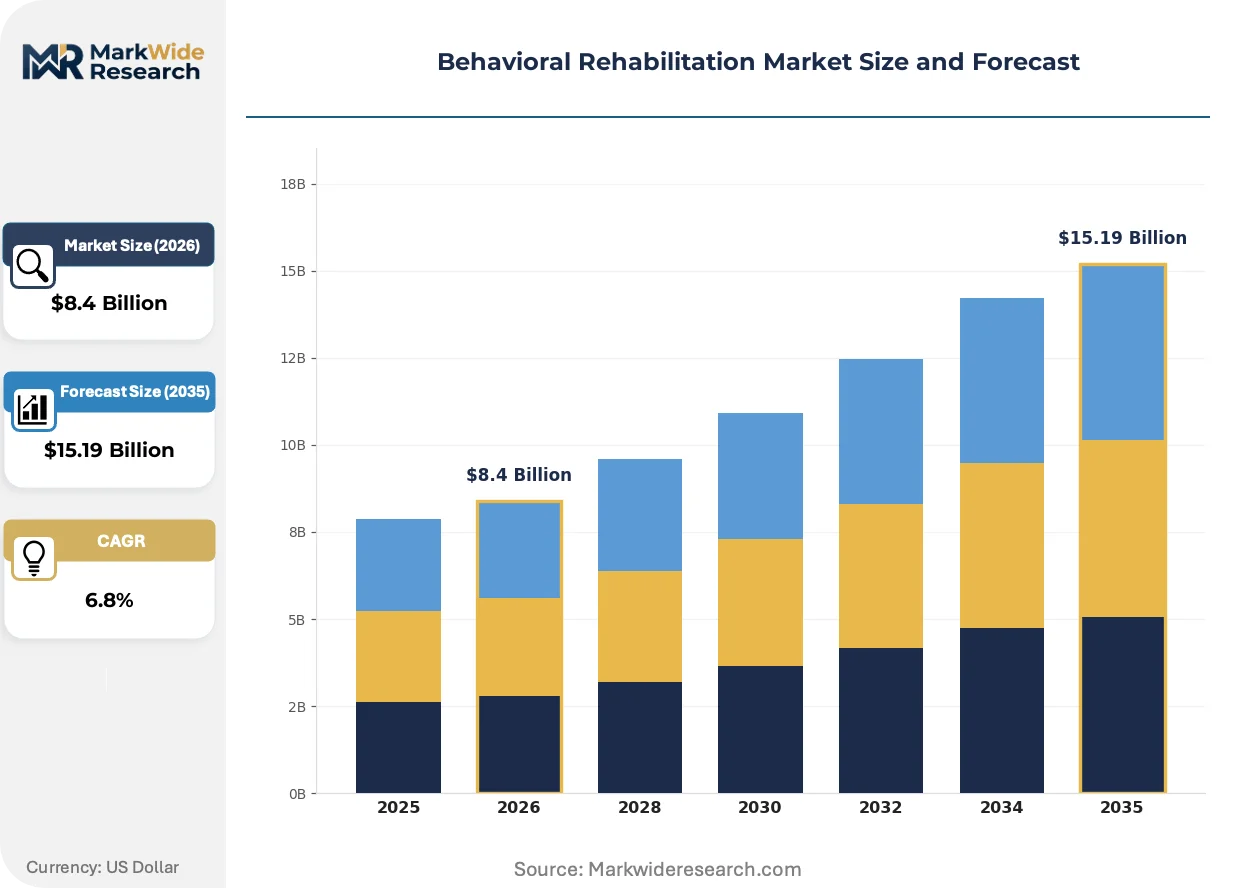
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cognitive Behavioral Therapy, Dialectical Behavior Therapy, Exposure Therapy, Group Therapy Patient Type: Adults, Adolescents, Children, Veterans Service Model: Outpatient, Inpatient, Teletherapy, Intensive Outpatient Program Treatment Duration: Short-term, Medium-term, Long-term, Ongoing |
| Companies Covered | Acadia Healthcare, Universal Health Services, Magellan Health, Aurora Behavioral Health System, Haven Behavioral Healthcare, Promises Behavioral Health, BHG Holdings, Niznik Behavioral Health, Lucet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behavioral Rehabilitation Market Strategic Shifts & Innovations
Platform architectures are fragmenting the traditional episode-based care model into discrete, billable micro-interventions that align with evolving reimbursement granularity.
Artificial intelligence-powered clinical decision support is modularizing assessment protocols into adaptive, session-level guidance tools. Community mental health centers are deploying these systems to extend supervisor oversight across larger caseloads. This compression of clinical judgment into algorithmic assistance is modularizing the traditional therapist-patient dyad into tiered care teams.
State insurance commissioners are accelerating parity enforcement actions against commercial plans with quantitative treatment limit disparities. Carriers are responding by eliminating separate behavioral health deductibles and expanding in-network specialty access. Employer-sponsored plans in California and New York face the most immediate compliance pressure.
Benefit administrators are unbundling traditional employee assistance programs into point-solution subscriptions for specific conditions. Procurement teams at self-insured employers now evaluate vendors on measured clinical outcome trajectories rather than utilization rates. This shift is most pronounced among technology sector employers with concentrated millennial workforces.
Behavioral Rehabilitation Market Segmentation
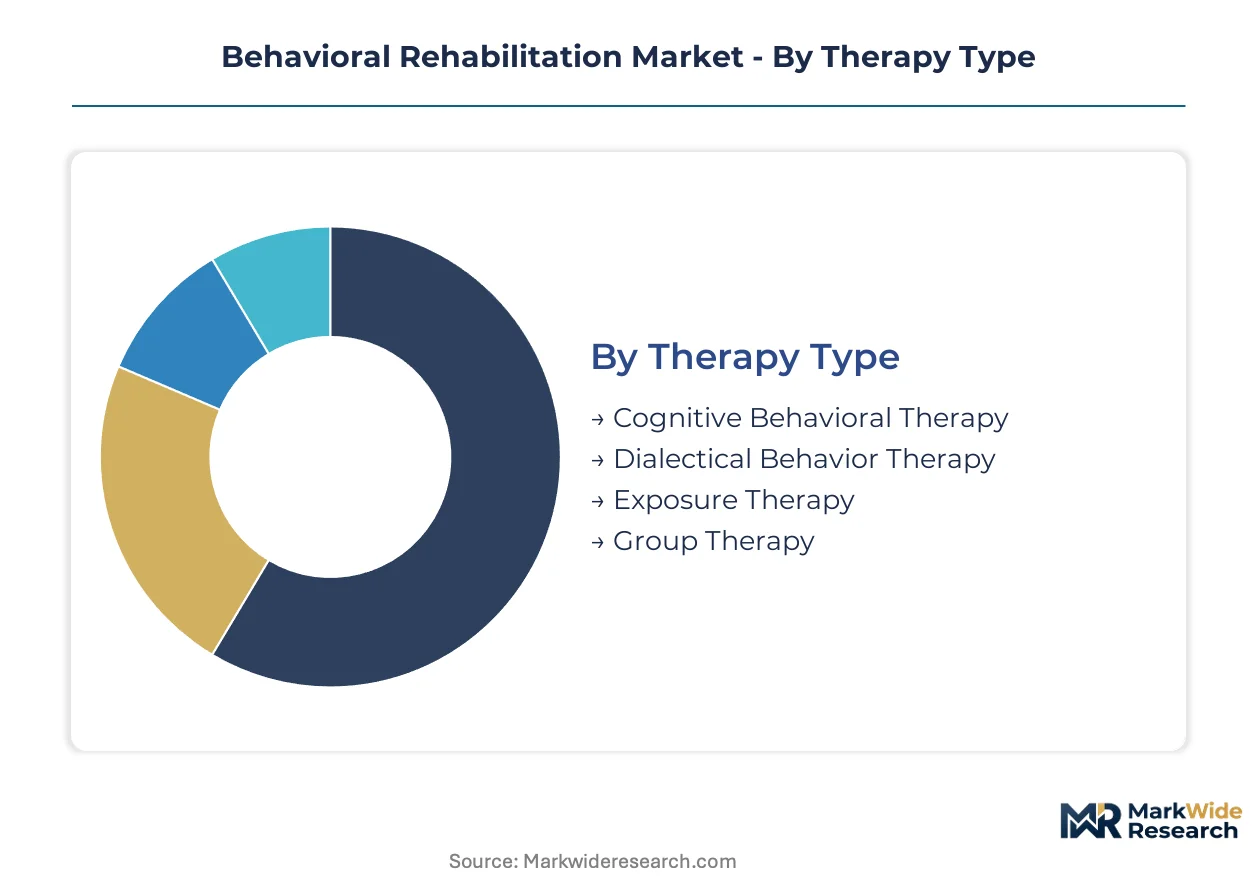
Behavioral rehabilitation markets fragment across therapeutic modality, patient acuity, and care delivery infrastructure. Each segmentation dimension carries distinct capital requirements, reimbursement profiles, and workforce constraints that determine provider economics.
Therapy Type:
Capital intensity peaks in modalities requiring specialized practitioner certification and proprietary training infrastructure.
- Cognitive Behavioral Therapy:Structured protocols target maladaptive thought patterns through standardized session frameworks. Demand concentrates in United States integrated care networks where CMS reimbursement codes anchor revenue stability for licensed clinical psychologists.
- Dialectical Behavior Therapy:Skills-based intervention emphasizes emotional regulation and distress tolerance through individual and group modalities. Concentrated demand appears in adolescent residential facilities and veterans administration medical centers facing chronic self-harm presentations.
- Exposure Therapy:Graduated stimulus confrontation protocols require controlled environment infrastructure.
- Group Therapy:Scalable delivery model reduces per-patient labor cost through shared session dynamics.
Most installed capacity flows through Cognitive Behavioral Therapy. Expansion is steepest in Dialectical Behavior Therapy.
Patient Type:
Service intensity and payment source vary sharply across developmental stages and eligibility categories.
- Adults:Largest volume segment spanning employer-sponsored benefits and commercial insurance. Workforce productivity mandates drive corporate procurement of outpatient cognitive behavioral programs.
- Adolescents:School-based service mandates and family court referrals concentrate demand in residential and intensive outpatient settings. State education department contracts create procurement concentration.
- Children:Early intervention protocols require specialized play therapy infrastructure and developmental assessment tools.
- Veterans:VA healthcare system purchasing dominates with trauma-focused service requirements and polytrauma rehabilitation center referrals.
Adults absorb the majority of service volume. Steepest expansion trajectory belongs to Adolescents.
Service Model:
Facility investment and staffing ratios diverge across acuity levels and supervision requirements.
- Outpatient:Lowest capital barrier with leased clinical space and standard liability coverage. United States metropolitan corridors concentrate demand where licensed practitioner density supports appointment availability.
- Teletherapy:Platform infrastructure replaces physical footprint with asynchronous supervision capabilities and HIPAA-compliant architecture. Interstate licensure compacts are dissolving geographic supply constraints fastest in this segment.
- Inpatient:Psychiatric facility construction and 24-hour staffing impose substantial fixed cost burdens.
- Intensive Outpatient Program:Bridging acuity level requires structured group programming and medication management capabilities.
Outpatient channels carry the greatest installed capacity. Teletherapy is gaining share fastest.
Treatment Duration:
Revenue recognition patterns and patient retention economics split across time-bound versus continuing care frameworks.
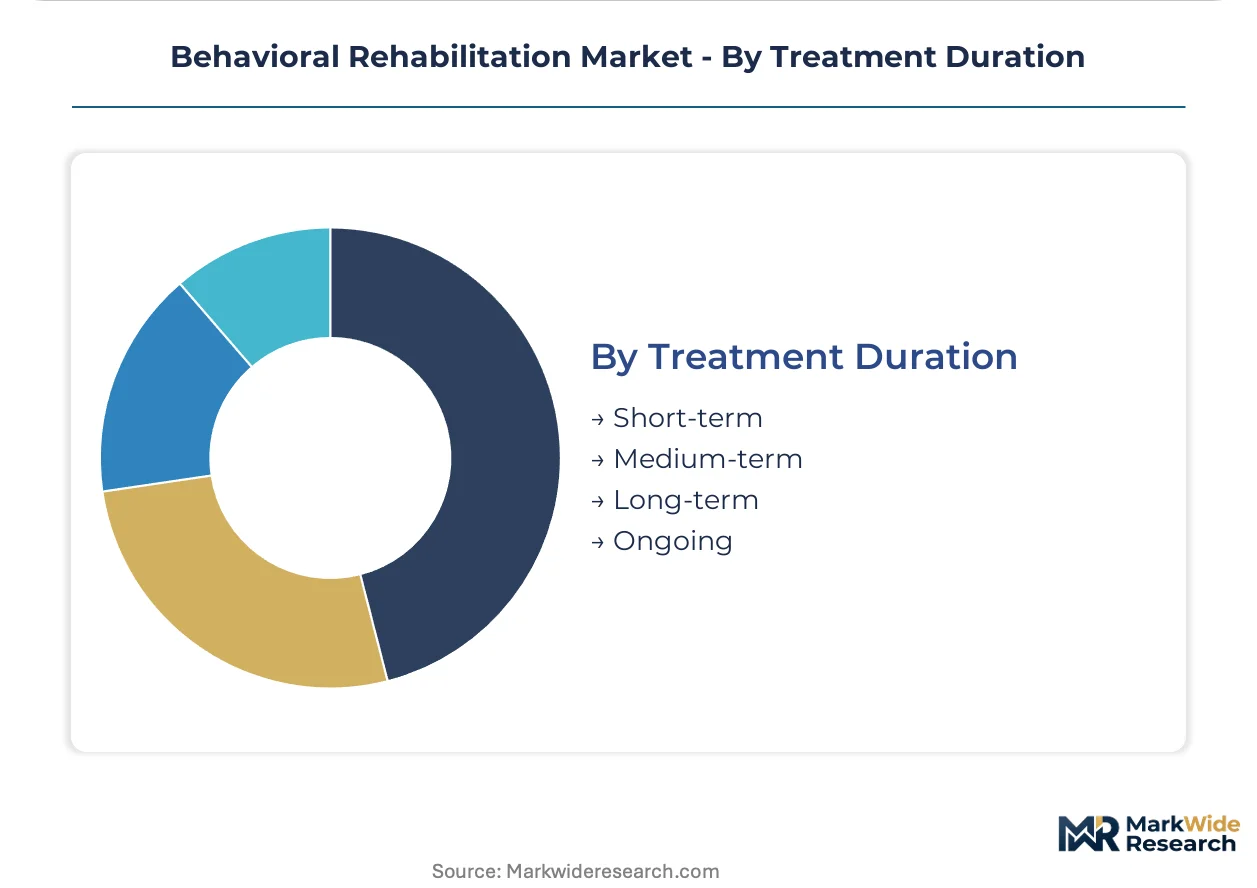
- Short-term:Episode-based billing aligns with acute crisis intervention and employer assistance program benefit limits. Commercial insurance prior authorization requirements concentrate demand in brief cognitive behavioral protocols.
- Medium-term:Standardized 12-16 week frameworks match evidence-based protocol completion rates and typical deductible cycles.
- Long-term:Chronic condition management requires sustained care coordination and relapse prevention infrastructure.
- Ongoing:Maintenance therapy models generate recurring revenue but face utilization review scrutiny.
Medium-term protocols dominate current capacity deployment. Long-term engagement is climbing fastest as chronic disease recognition expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated care networks in the United States concentrate the largest installed capacity for behavioral rehabilitation services. Medicare coverage expansions and employer-sponsored mental health benefits are accelerating service utilization across metropolitan corridors.
United States
Employer-sponsored mental health benefits and Medicare coverage expansions are pulling elderly patients into structured behavioral interventions. CMS reimbursement for intensive outpatient programs anchors revenue stability for licensed clinical psychologists. The Northeast Corridor concentrates demand where practitioner density supports appointment availability and integrated care networks dominate.
Germany
Statutory health insurance integration of digital therapeutics is broadening access to cognitive behavioral protocols. The country's national pharmaceutical regulator oversees software-based intervention approvals through established medical device pathways. Bavaria anchors inpatient psychiatric capacity with university hospital systems expanding teletherapy infrastructure.
United Kingdom
NHS Talking Therapies program procurement is standardizing cognitive behavioral delivery across primary care networks. National Institute for Health and Care Excellence guidelines shape reimbursement eligibility for evidence-based protocols. Greater London concentrates digital health startup activity with platform operators securing NHS framework agreements.
Canada
Provincial health authority contracts for community mental health services are consolidating vendor relationships. Health Canada determines coverage parameters for digital therapeutic submissions that dictate provider revenue stability. Ontario concentrates demand where employer-sponsored benefits supplement provincial coverage gaps.
Australia
Medicare Benefits Schedule item numbers for psychological services are expanding telehealth eligibility. The Therapeutic Goods Administration oversees software-based intervention classifications for reimbursement purposes. New South Wales anchors national capacity with public hospital networks piloting integrated behavioral-primary care models.
Behavioral Rehabilitation Market Key Industry Players
Global majors compete with regional champions across facility footprint and payer channel access. The vendor base clusters around three tiers: national facility networks, carved-out behavioral health plans, and specialized residential operators. Strategic archetypes include scale-driven inpatient operators, platform-centric teletherapy providers, and condition-specific residential specialists. M&A activity targets geographic white space, while strategic partnerships with employer benefits administrators secure direct-to-consumer channels.
Within the national facility network tier, Acadia Healthcare and Universal Health Services exemplify scale-driven operators with distributed inpatient footprints. Magellan Health occupies a position within the carved-out health plan segment, controlling payer channel access through specialized behavioral contracts. These three entities represent distinct competitive positioning strategies: facility-based volume, diversified service line breadth, and payer-adjacent channel control.
| Leading Market Players |
|---|
| Acadia Healthcare |
| Universal Health Services |
| Magellan Health |
| Aurora Behavioral Health System |
| Haven Behavioral Healthcare |
| Promises Behavioral Health |
| BHG Holdings |
| Niznik Behavioral Health |
| Lucet |
| Others |
Cost & Logistics Intelligence
Captive workforce development pipelines anchor supply position and pricing power for behavioral rehabilitation providers operating across United States metropolitan corridors. Licensed clinical social worker concentration in coastal states creates geographic supply asymmetry that permits premium rate-setting in practitioner-scarce interior regions.
Pricing Analysis
Input-cost pass-through from licensed practitioner salaries and facility overhead dominates pricing structures across service models. Three-tier pricing structure across premium, standard, and economy levels separates intensive outpatient programs with psychiatric oversight from standard outpatient sessions and unlicensed peer support. Price differentiation rests on certification level—CMS-approved providers command reimbursement premiums versus non-participating practitioners. Cost compression in teletherapy is intensifying because platform operators compete on per-session rates. Self-insured employers show least price sensitivity for measurable outcome-based contracts, while individual cash-pay patients exhibit highest sensitivity to session fees.
Supply Chain Analysis
Workforce availability constraints in United States, Canada, and United Kingdom manufacturing geographies of behavioral health training programs limit licensed practitioner pipeline expansion. Raw material dependencies include graduate psychology programs, clinical supervision hours, and state licensure examination capacity. Supply chain risk centers on single-source vulnerability where regional accreditation bodies control training program approval. Distribution runs through integrated care networks, employer benefits administrators, and direct-to-consumer platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behavioral rehabilitation constitutes a late-cycle quality story as employer procurement shifts toward premium specifications demanding measured clinical outcome trajectories rather than utilization metrics.
For Market Incumbents: Deepen vertical integration into licensed practitioner training pipelines to secure workforce supply against locum tenens cost inflation. Expand inpatient capacity in rural counties where psychiatric facility closures have concentrated acute demand within urban systems. Threat of digital therapeutic platforms with FDA clearance requires defensive investment in asynchronous care supervision capabilities. For New Entrants and Emerging Players: The price-point gap between premium intensive outpatient programs and economy-tier peer support services offers white-space entry at the mid-market bridge position. Target justice-involved populations under state corrections department performance-based reentry contracts. School-based intervention mandates present the most penetrable segment given state education department procurement concentration. Go-to-market angle should emphasize district-wide service partnerships with embedded outcome measurement. For Investors and Strategic Acquirers: Roll-up economics work for regional facility networks because state-level licensure reciprocity agreements create geographic expansion friction that favors consolidated platforms. Long-term viability over the next decade hinges on Medicare coverage expansion sustainability and telehealth parity enforcement durability. Acquisition target archetype: carved-out behavioral health plans controlling payer channel access. Watch interstate licensure compact adoption velocity as inflection indicator for teletherapy platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Secures Medicare coverage expansion for intensive outpatient programs anchors revenue stability. |
| Interstate Licensure Compact Participation | Dissolves geographic supply constraints that historically limited rural patient access. |
| Digital Biomarker Platform Integration | Enables CMS billing codes for asynchronous care supervision via wearable-derived validation. |
| Employer Benefits Administrator Partnership | Consolidates vendor relationships for integrated behavioral-primary care platform positioning. |
| Justice-Involved Population Contracting | Captures state corrections department outsourcing of reentry mental health services. |
Research Approach
Coverage spans United States, Germany, United Kingdom, Canada, and Australia, with primary inputs from each regional cluster combining structured interviews with behavioral health executives, payer contracting officers, hospital system procurement managers, and state regulatory affairs leads. Secondary validation draws from CMS Medicare data, FDA digital therapeutics guidance filings, state insurance commissioner parity enforcement records, and employer benefits administrator vendor disclosures. Bottom-up facility capacity modeling triangulates against top-down reimbursement flow analysis.
Rate-of-change decomposition separates volume expansion from price-mix effects across therapy type, patient acuity, service model, and treatment duration segmentation dimensions. CAGRs derive from logistic adoption curves for teletherapy penetration and linear capacity build assumptions for inpatient bed expansion. Forecast inputs include interstate licensure compact ratification timelines and CMS digital therapeutic coverage determination schedules.
Caveats apply where workforce supply concentration, HIPAA compliance architecture fragmentation, or inpatient bed scarcity could materially shift the outlook. Forecasts reflect assumptions regarding Medicare reimbursement stability and employer-sponsored benefit expansion continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market