
 Eye Care Surgical Market | 2026-2036
Eye Care Surgical Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Care Surgical Market Analysis
The gap between premium femtosecond laser platforms and conventional phacoemulsification systems is expanding as reimbursement divergence widens. Alcon leverages vertical integration across consumables and capital equipment to sustain margin capture across both tiers. Johnson & Johnson Vision anchors its position in advanced intraocular lenses through proprietary extended depth of focus designs. Carl Zeiss Meditec differentiates via integrated surgical visualization and biometry workflows that dominate premium cataract workflows.
Eye care surgical procedures encompass micro-invasive interventions performed on ocular structures using specialized instruments, lasers, and robotic systems, typically requiring sub-millimeter precision and sterile field maintenance. Cataract surgery represents the mature volume base, while refractive surgery carries higher per-procedure margins tied to elective consumer payment. Glaucoma surgery is gaining traction as micro-invasive stent technologies shift procedures toward outpatient settings. Surgical robotics occupies the fastest-growing technology position, though laser technology still commands the largest installed base across hospital systems.
The FDA's premarket notification and PMA pathways govern device commercialization timelines in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for ophthalmic implants. Japan's PMDA maintains distinct biocompatibility testing protocols that shape product registration strategies for Asian market entry. Stakeholders must monitor evolving reimbursement coding for femtosecond laser-assisted procedures versus manual techniques, as payer decisions will determine capital equipment replacement cycles and technology diffusion rates across delivery settings.
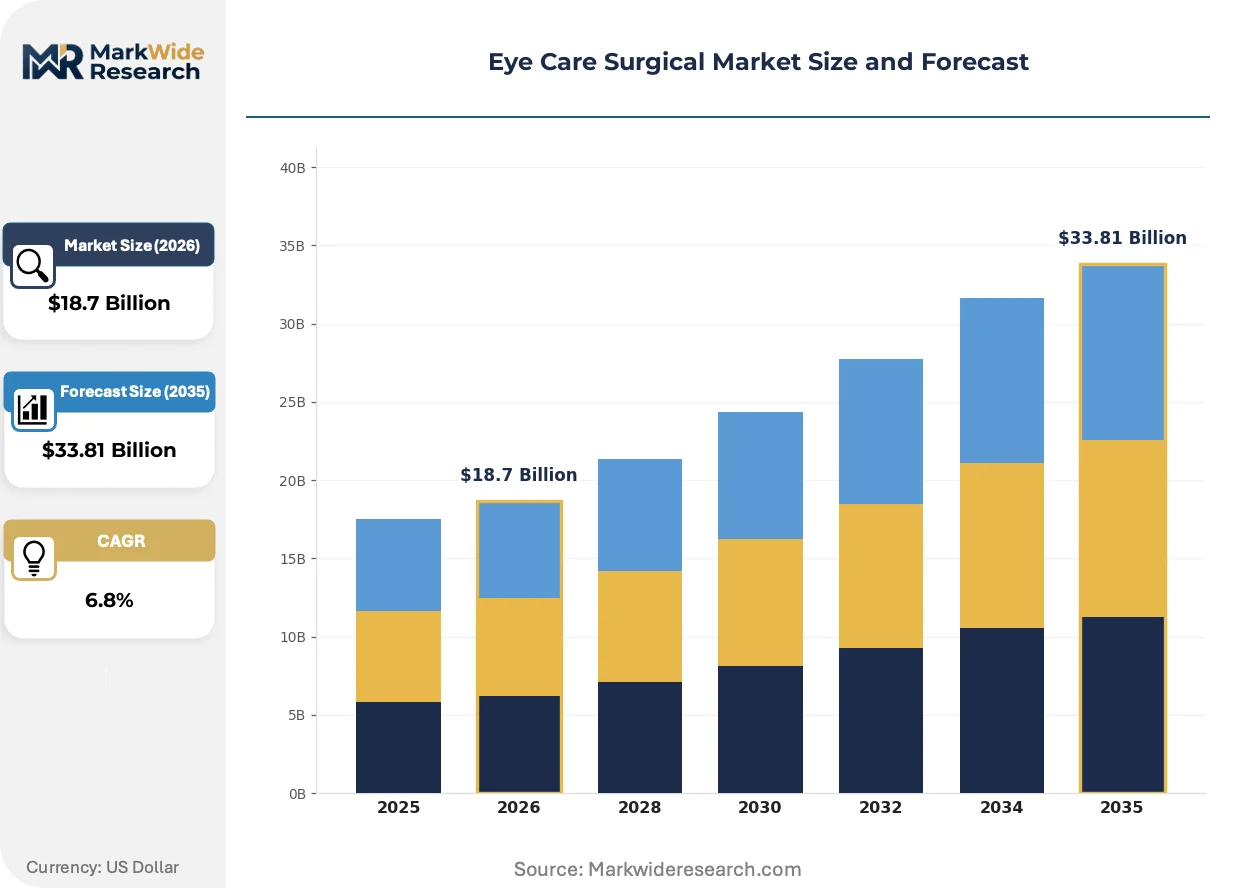
Market Dynamics
Femtosecond laser platforms are compressing procedure times while elevating capital intensity requirements across ambulatory surgical centers, forcing equipment financing restructuring and consolidated procurement consortia formation.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence mandates for ophthalmic implants are accelerating M&A activity as smaller manufacturers seek regulatory capacity through acquisition rather than internal buildout.
- Ambulatory Surgery Centers:Outpatient facility expansion in the United States is redirecting surgical volume away from hospital-based settings toward specialized environments optimized for high-throughput cataract workflows.
- Micro-invasive Glaucoma Stents:Device miniaturization is enabling procedure migration from operating rooms to procedure suites, expanding addressable patient populations previously excluded from invasive surgical candidacy.
Market Restraints
- Capital Equipment Concentration:Femtosecond laser system costs exceeding $500,000 per unit create barrier concentration among high-volume surgical centers, excluding smaller practices from premium technology access.
- Reimbursement Divergence:CMS coding distinctions between laser-assisted and manual cataract techniques compress margin capture for capital-intensive platforms despite superior clinical outcomes.
- Biocompatibility Testing Fragmentation:Japan's PMDA maintains distinct silicone oil extraction protocols that extend registration timelines by 12-18 months versus FDA pathways, delaying Asian market entry.
Strategic Opportunities
- India:CDSCO streamlined medical device registration under 2017 rules is reducing time-to-market for European and American manufacturers seeking access to 1.4 billion population base with rising diabetic retinopathy prevalence.
- AI-integrated Surgical Planning:Machine learning convergence with optical biometry is enabling predictive IOL power calculation refinement, reducing enhancement rates and building platform loyalty.
- Direct-to-Consumer Refractive Marketing:Elective LASIK and SMILE procedures bypass traditional referral channels through digital patient acquisition, capturing margin previously allocated to optometric co-management fees.
Industry Challenges
- Femtosecond Laser Technician Scarcity:Specialized training requirements for platform operation and maintenance outpace certified technician pipeline development, constraining equipment utilization rates.
- Legacy EMR Integration:Surgical planning software interoperability with hospital information systems requires customized API development, extending implementation timelines and elevating IT consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Care Surgical Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cataract Surgery, Refractive Surgery, Glaucoma Surgery, Vitreoretinal Surgery Technology: Laser Technology, Microsurgery, Endoscopy, Surgical Robotics End User: Hospitals, Outpatient Surgery Centers, Eye Clinics, Specialty Hospitals Delivery Mode: Inpatient, Outpatient, Telemedicine, Emergency Care |
| Companies Covered | Alcon, Johnson & Johnson Vision, Bausch + Lomb, Carl Zeiss Meditec, Glaukos Corporation, STAAR Surgical, Hoya Corporation, Topcon Corporation, NIDEK Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Care Surgical Market Emerging Trajectories
Digital surgical workflows are compressing preoperative planning cycles while elevating precision requirements, reshaping how ophthalmic practices configure their technology stacks and staff competencies.
Femtosecond laser technology is decentralizing cataract surgery preparation from centralized hospital settings toward ambulatory centers equipped with in-house biometry and planning capabilities. Mid-sized surgical groups in Germany and Japan are acquiring platforms previously restricted to academic medical centers. This capability diffusion is compressing referral patterns and enabling same-day diagnostic-to-surgical workflows.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending ophthalmic implant registration timelines and elevating post-market surveillance obligations. Manufacturers must now submit prospective registry data for premium IOL categories previously cleared through predicate equivalence. Extended depth of focus and trifocal designs face disproportionate scrutiny, forcing portfolio prioritization toward platforms with robust long-term outcome documentation.
Patient direct payment models are displacing traditional insurance-reimbursed channels for refractive procedures. Younger demographics in South Korea and Brazil are researching surgeons through social media verification rather than optometric referral networks. This channel disintermediation is elevating marketing expenditure ratios while compressing co-management fee structures that historically sustained optometric practice economics.
Eye Care Surgical Market Segmentation
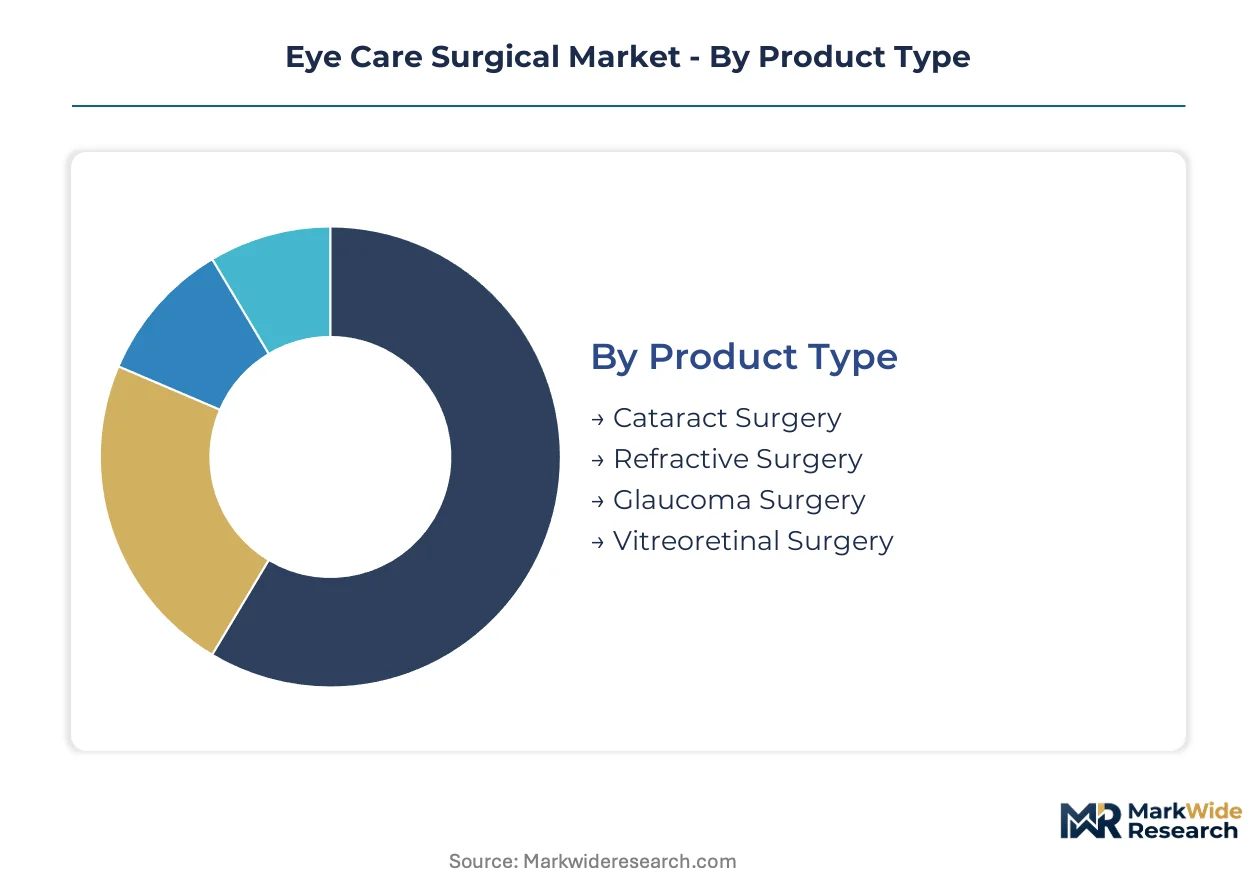
Surgical modality selection dictates capital deployment patterns and reimbursement coding across eye care delivery settings. Procedure volume distribution and margin capture vary substantially across these dimensions, requiring targeted portfolio positioning.
Product Type:
FDA PMA pathways govern premium IOL platforms, while CMS coding distinctions separate reimbursed cataract workflows from elective refractive procedures.
- Cataract Surgery:Phacoemulsification with monofocal or premium IOL implantation constitutes the procedural volume base across Medicare-aged populations. United States ambulatory surgery centers concentrate demand where CMS reimbursement sustains equipment amortization schedules.
- Refractive Surgery:LASIK, PRK, and SMILE procedures operate outside insurance channels through direct consumer payment. South Korea and Brazil exhibit concentrated demand from younger demographics seeking spectacle independence via social media-influenced surgeon selection.
- Glaucoma Surgery:Trabeculectomy and micro-invasive stent procedures address intraocular pressure management. Device miniaturization enables migration from operating rooms to procedure suites.
- Vitreoretinal Surgery:Pars plana vitrectomy addresses retinal detachment, macular hole, and diabetic complications. Complex instrumentation requirements sustain hospital-based concentration.
Cataract Surgery sits at the top of the volume ranking, with Glaucoma Surgery climbing the fastest.
Technology:
Capital intensity and technician training requirements stratify adoption across delivery settings, with laser platforms demanding $500,000-plus investments.
- Laser Technology:Femtosecond laser platforms automate corneal incisions, capsulotomies, and lens fragmentation with sub-micron precision. Germany's mid-sized surgical groups are acquiring systems previously restricted to academic centers.
- Microsurgery:Conventional phacoemulsification and manual instrumentation sustain cost-competitive positioning where reimbursement compression limits capital expenditure. Smaller United States practices rely on this tier for margin preservation.
- Endoscopy:Minimally invasive visualization systems enable trans-scleral and angle-based procedures. Outpatient facility expansion drives demand for compact, portable configurations.
- Surgical Robotics:Automated suturing and instrument positioning systems occupy the steepest expansion trajectory. Japan's PMDA maintains distinct validation protocols that shape product registration timelines.
Laser Technology commands the largest installed base, with Surgical Robotics gaining share fastest.
End User:
Facility reimbursement structures and case throughput requirements determine technology tier accessibility.
- Hospitals:Academic medical centers and community hospitals manage complex vitreoretinal and trauma cases requiring anesthesia support and overnight observation. United States hospital systems face volume erosion to ambulatory competitors.
- Outpatient Surgery Centers:Dedicated ophthalmic facilities optimize cataract workflow efficiency with same-day discharge protocols. United States Medicare ASC fee schedules sustain high-throughput business models.
- Eye Clinics:Office-based settings concentrate diagnostic biometry and refractive consultation. Direct-to-consumer marketing channels reshape patient acquisition economics.
- Specialty Hospitals:Dedicated eye hospitals in India and China aggregate surgical volume for training and research missions. CDSCO streamlined registration under 2017 rules accelerates technology access.
Outpatient Surgery Centers sit at the top of the volume ranking, with Eye Clinics climbing the fastest.
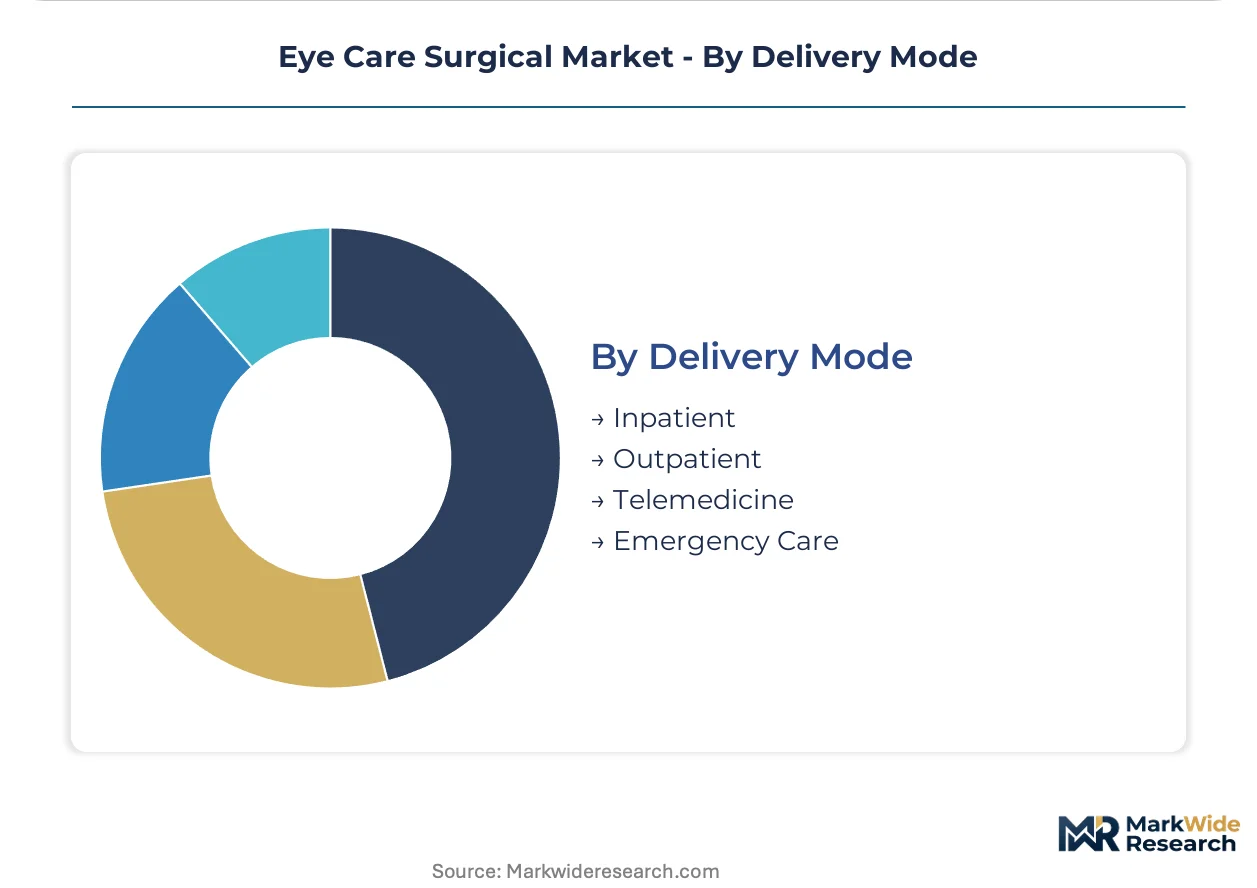
Delivery Mode:
Reimbursement coding and clinical risk stratification determine site-of-service selection.
- Inpatient:Reserved for complex trauma, combined procedures, and patients with significant comorbidities requiring monitoring. Hospital cost structures pressure utilization rates.
- Outpatient:Same-day discharge protocols dominate cataract, refractive, and select glaucoma procedures. Ambulatory facility expansion redirects volume from inpatient settings.
- Telemedicine:Preoperative screening and postoperative monitoring extend geographic reach. Regulatory scope limitations prevent surgical intervention via remote platforms.
- Emergency Care:Acute trauma, chemical injury, and retinal detachment require immediate surgical intervention. Urban emergency departments stabilize before definitive repair.
Outpatient sits at the top of the volume ranking, with Telemedicine climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmic surgeons concentrate in metropolitan medical corridors across five countries where aging demographics and reimbursement infrastructure sustain procedural volume expansion. Training program density and capital equipment financing availability determine regional competitive positioning.
United States
Medicare reimbursement rates for ambulatory surgery centers sustain high-throughput cataract workflows in Florida, Arizona, and Texas retirement corridors. FDA premarket approval pathways for femtosecond laser platforms shape product launch sequencing. The Cleveland Clinic and Bascom Palmer Eye Institute anchor surgical training and technology evaluation clusters.
Germany
Mid-sized surgical groups in Bavaria and North Rhine-Westphalia acquire femtosecond platforms previously restricted to academic centers. EU Medical Device Regulation enhanced clinical evidence mandates accelerate consolidation among implant manufacturers. The Ruhr Valley and Munich metropolitan areas concentrate outpatient facility expansion.
Japan
PMDA biocompatibility testing protocols extend registration timelines for silicone oil-dependent devices. Tokyo and Osaka academic medical centers dominate vitreoretinal surgical training. Kansai region ambulatory centers pioneer same-day diagnostic-to-surgical workflows for aging populations.
India
CDSCO streamlined registration under 2017 rules reduces time-to-market for European and American manufacturers. Maharashtra and Tamil Nadu specialty hospitals aggregate surgical volume for training missions. Aravind Eye Hospital in Madurai demonstrates high-volume cataract efficiency models.
South Korea
Younger demographics drive direct-to-consumer refractive procedure demand through social media-influenced surgeon selection. MFDS maintains distinct validation protocols for laser vision correction platforms. Seoul metropolitan area clinics concentrate elective LASIK and SMILE marketing expenditure.
Eye Care Surgical Market Vendor Landscape
Top-tier vendors anchor premium femtosecond laser and advanced intraocular lens segments, while mid-tier specialists occupy conventional phacoemulsification and manual instrumentation tiers. The vendor base stratifies across capital equipment manufacturers, consumable suppliers, and integrated platform providers. Three archetypes dominate: integrated ophthalmic conglomerates with vertical control across consumables and equipment; specialized laser technology developers with premium visualization workflows; and regional implant manufacturers with cost-competitive monofocal portfolios. Competitive moves concentrate on regulatory capacity acquisition through M&A and AI-integrated surgical planning software development.
Among integrated ophthalmic conglomerates, Alcon and Johnson & Johnson Vision exemplify backward integration strategies spanning consumables and capital equipment. Carl Zeiss Meditec occupies a position within the premium visualization and biometry workflow tier. These three entities represent divergent approaches to margin capture across reimbursed cataract and elective refractive channels.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Vision |
| Bausch + Lomb |
| Carl Zeiss Meditec |
| Glaukos Corporation |
| STAAR Surgical |
| Hoya Corporation |
| Topcon Corporation |
| NIDEK Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Femtosecond laser platform miniaturization simultaneously compresses per-procedure consumable costs and concentrates manufacturing among German and Japanese precision optics specialists, reshaping procurement economics for ambulatory surgical centers.
Pricing Analysis
Bundled femtosecond laser service contracts dominate premium cataract workflows, while unbundled phacoemulsification consumables sustain cost-competitive positioning. Pricing stratifies across premium, standard, and economy tiers based on FDA PMA certification status and after-sales technical support intensity. Cost compression in conventional phacoemulsification is intensifying because ambulatory surgery centers negotiate consolidated procurement volumes. Independent ophthalmology practices exhibit highest price sensitivity, whereas academic medical centers prioritize outcome consistency over per-unit expenditure.
Supply Chain Analysis
Air freight costs for precision optical components from Germany, Japan, and Switzerland constrain just-in-time inventory strategies for femtosecond laser manufacturers. Supply chains draw from specialized silica glass foundries in Heraeus's German operations, precision motion control systems from Japanese suppliers, and rare-earth laser crystals sourced from US defense contractors. Single-source vulnerability permeates excimer laser gas mixtures, where Russian and Ukrainian noble gas refining disruptions ripple through refractive surgery device production. Distribution runs through manufacturer-direct field service organizations for capital equipment, while consumables flow through GPO-authorized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
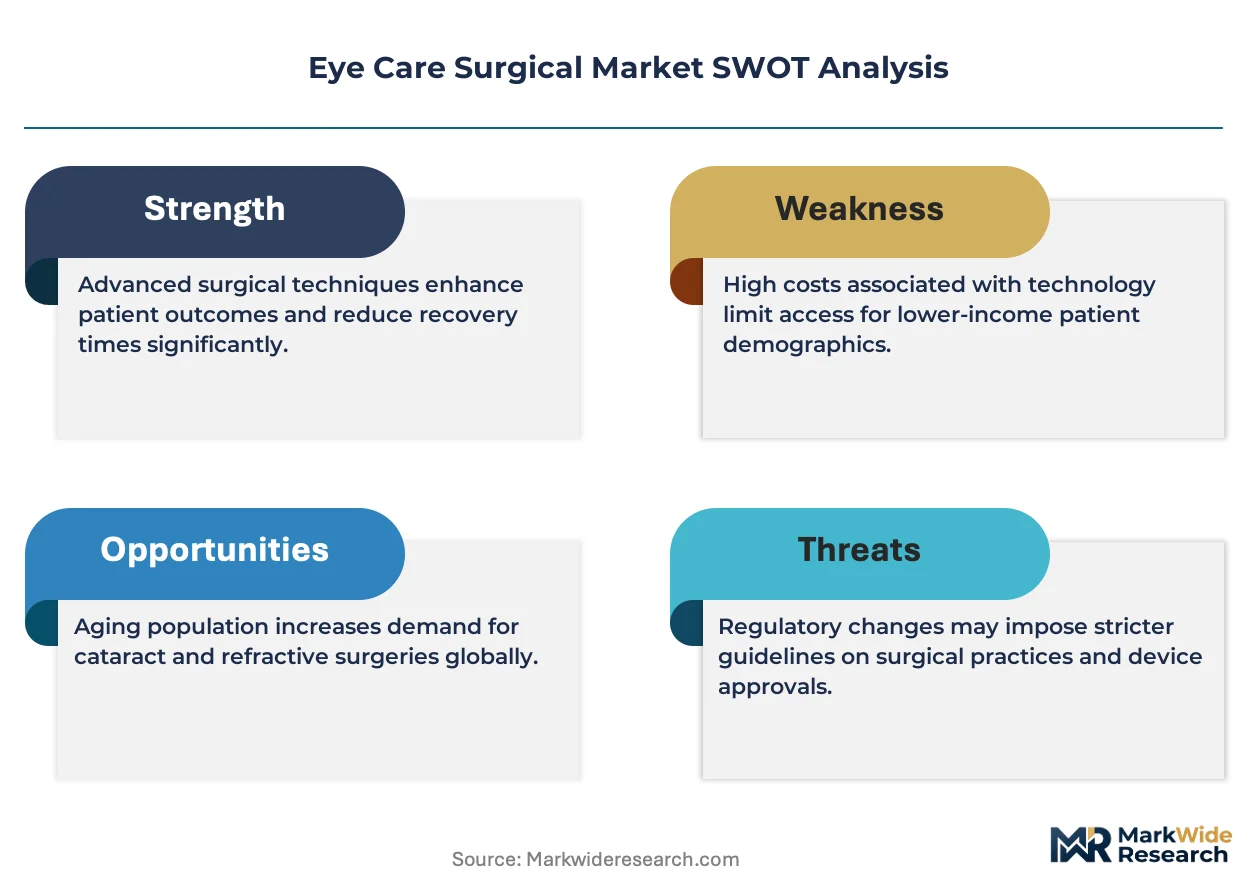
This market represents a late-cycle quality story as patient direct payment for refractive procedures displaces insurance-reimbursed channels, elevating surgeon reputation and outcome transparency as premium differentiators.
For Market Incumbents: Anticipate reimbursement coding divergence between laser-assisted and manual cataract techniques by deepening backward integration into proprietary IOL designs that lock surgical planning software ecosystems. Defend installed base positions through captive technician training pipelines that constrain competitor platform switching. Alcon and Johnson & Johnson Vision anchor this consolidation logic through consumable-equipment bundling. For New Entrants and Emerging Players: Social media-influenced patient acquisition channels offer the most penetrable route into South Korean and Brazilian refractive markets, where younger demographics bypass traditional optometric referrals. Target mid-sized surgical groups in Germany's Bavaria and North Rhine-Westphalia regions seeking femtosecond platforms previously restricted to academic centers. Deploy AI-integrated surgical planning software as a loss-leader to build platform loyalty before hardware placement. For Investors and Strategic Acquirers: Valuations sit cheapest among regional implant manufacturers with cost-competitive monofocal portfolios and limited regulatory capacity for EU MDR compliance. Long-term viability hinges on M&A consolidation as enhanced clinical evidence mandates force smaller manufacturers toward acquisition rather than internal buildout. Monitor CDSCO registration acceleration under India's 2017 rules as an inflection signal for Asian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submission timelines govern femtosecond laser platform launch sequencing and capital equipment replacement cycles. |
| EU MDR Clinical Evidence Buildout | Prospective registry data requirements for premium IOLs force portfolio prioritization toward documented long-term outcomes. |
| Hospital System Partnership | Academic medical center alliances anchor surgical training clusters that shape technology evaluation and resident preference formation. |
| Software Companion Development | AI-integrated biometry workflows reduce enhancement rates and build platform loyalty through predictive IOL power calculation refinement. |
| Reimbursement Strategy | CMS coding distinctions between laser-assisted and manual techniques determine capital equipment amortization feasibility across delivery settings. |
Methodological Framework
Bottom-up ambulatory surgery center procedure modeling reconciled against top-down femtosecond laser installed base tracking forms the analytical core. Primary interviews with cataract surgeons, ASC administrators, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at FDA and PMDA converge with secondary validation from CMS Medicare reimbursement databases, hospital procurement records, EU MDR submission filings, and manufacturer capital equipment disclosure statements.
Input-output matrices map laser platform shipments against consumable utilization rates across procedure modalities. Segmentation dimensions span surgical modality, technology tier, end-user facility type, and delivery mode. CAGRs derive from equipment replacement cycle analysis and procedure volume elasticity to demographic aging patterns. Forecast inputs incorporate PMDA biocompatibility testing timeline differentials and CDSCO registration streamlining impacts across the analysis window.
Reimbursement coding revisions, regulatory pathway delays, and technician training pipeline constraints are the dominant revision risks. Forecasts reflect documented assumptions about capital equipment financing availability and ambulatory facility expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Personalized LASIK Surgery Market