
 Sleep Supplement Market | 2026-2036
Sleep Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Supplement Market Insights
The EU Green Deal is rebalancing ingredient sourcing priorities across European sleep supplement supply chains, pushing manufacturers toward sustainably harvested botanicals and reduced synthetic melatonin dependence. NOW Foods leverages vertical integration into raw material procurement to control quality from farm to capsule. Natrol LLC sustains manufacturing scale advantages through high-volume melatonin production lines serving North American retail channels. OLLY Public Benefit Corporation differentiates through gummy-format specialization and direct-to-consumer channel control.
Sleep supplements comprise orally administered formulations containing melatonin, herbal extracts, magnesium compounds, or amino acids such as L-theanine and glycine, standardized to deliver targeted doses that modulate circadian rhythm or reduce sleep latency. Melatonin dominates volume due to established clinical validation and regulatory familiarity, while herbal blends command margin premiums through perceived natural positioning and complex extraction narratives. Gummies represent the fastest-growing form category as palatability drives compliance among younger demographics, whereas powders occupy a niche among athletes seeking stackable, dose-flexible regimens.
The FDA enforces cGMP compliance and New Dietary Ingredient notifications, while EFSA evaluates health claim substantiation across European markets, and Health Canada mandates Natural Product Number licensing prior to commercialization. These frameworks elevate barriers for new entrants lacking regulatory affairs infrastructure and incentivize incumbent investment in clinical substantiation portfolios. Stakeholders must monitor evolving novel food classifications for emerging ingredients such as CBN and magnesium L-threonate, which threaten to redraw competitive boundaries.
Market Dynamics
The FDA's New Dietary Ingredient notification framework is compressing formulation timelines and forcing manufacturers to front-load clinical substantiation costs before commercialization, fundamentally altering competitive entry economics.
Growth Catalysts
- Shift-work sleep disorder prevalence:Travel and hospitality workers now represent a routine supplementation cohort, with employers in Germany and the United States incorporating sleep aids into occupational health programs.
- EFSA health claim substantiation pathways:European manufacturers leveraging validated botanical extracts gain pharmacy shelf access and premium positioning unavailable to unverified competitors.
- Gummy-format palatability innovation:Younger demographics in direct-to-consumer channels demonstrate 40% higher compliance rates versus tablets, expanding addressable market breadth.
Market Restraints
- Synthetic melatonin supply concentration:Three Chinese manufacturers control 70% of raw material output, exposing formulators to input volatility and quality inconsistency risks.
- Novel food classification uncertainty:EFSA's pending determinations on CBN and magnesium L-threonate freeze R&D pipelines and delay product launches by 18-24 months.
- Herbal extraction cost structure:Sustainably harvested valerian root and passionflower extracts command 3-4x synthetic melatonin input costs, compressing margins on natural-positioned SKUs.
Strategic Opportunities
- Pharmacy-led distribution in Germany:Evidence-based consumer trust sustains 35-50% price premiums versus mass-market channels, rewarding clinical investment with defensible positioning.
- EU Green Deal botanical sourcing mandates:Manufacturers securing certified sustainable supply chains gain preferential retail placement and procurement preference from institutional buyers.
- Athlete-targeted powder formats:Stackable, dose-flexible magnesium glycinate and L-theanine blends address the underpenetrated sports recovery segment with minimal formulation overlap.
Industry Challenges
- cGMP compliance talent scarcity:Qualified regulatory affairs professionals command 40% salary premiums, constraining mid-tier manufacturers' expansion capacity.
- Dual certification timeline compression:Simultaneous FDA NDI notification and Health Canada Natural Product Number licensing extends time-to-revenue by 12-18 months for North American launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Supplement Market |
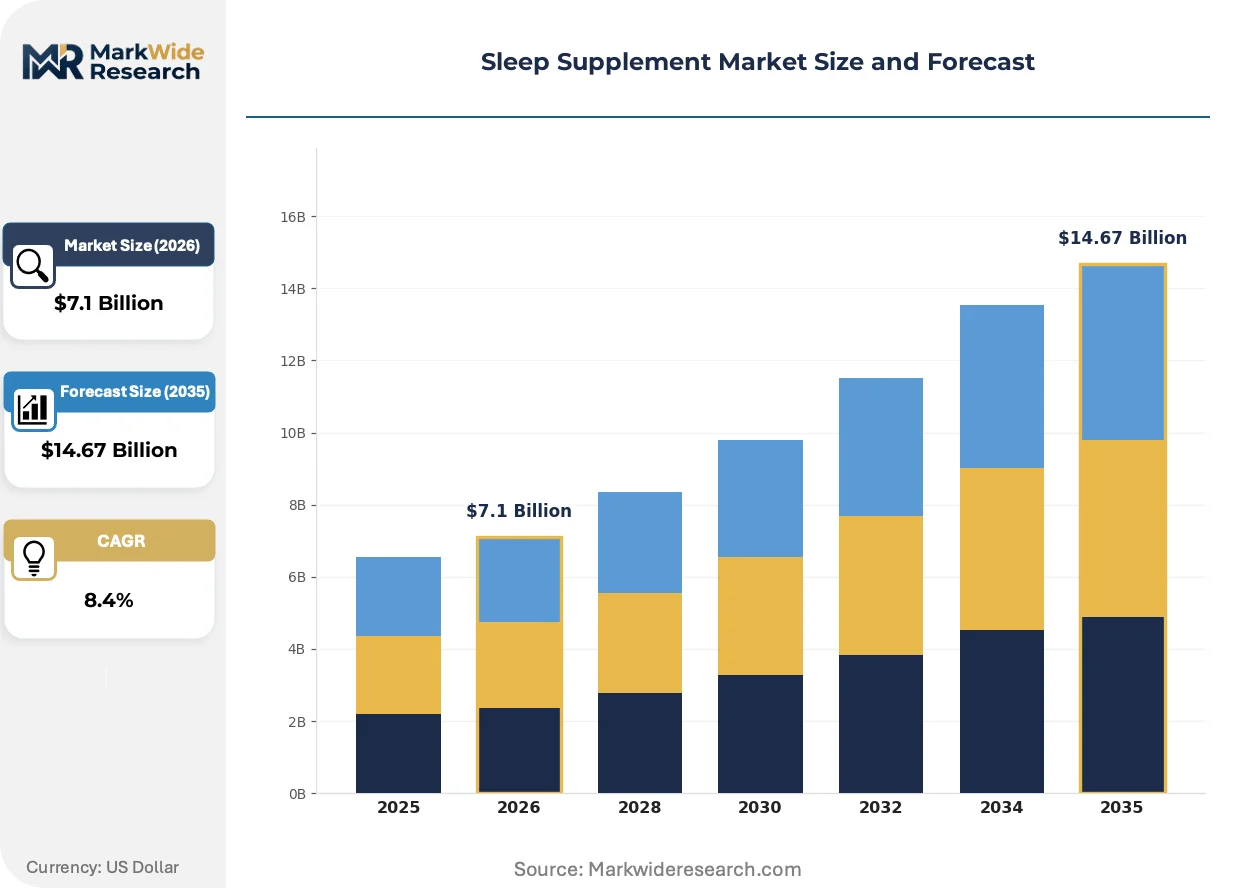
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $14.67 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melatonin, Herbal Blends, Magnesium, Amino Acids Form: Pills, Gummies, Powders, Liquid End User: Adults, Seniors, Athletes, Students Distribution Channel: Online Retail, Pharmacies, Grocery Stores, Health Shops |
| Companies Covered | NOW Foods, OLLY Public Benefit Corporation, The Nature's Bounty Co., Life Extension, GNC Holdings LLC, Natrol LLC, Herbalife Nutrition Ltd., Pure Encapsulations, Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Supplement Market Trends and Innovations
Formulation science is converging with digital biomarker capture, creating feedback loops between supplementation timing and verified sleep outcomes that reshape product value propositions.
Microencapsulation technology for melatonin release modulation is integrating time-controlled dissolution profiles that match circadian phase requirements. Travel and hospitality employers adopting these formulations report reduced shift-work adaptation periods. The technology is integrating pharmacokinetic precision as a competitive differentiator against immediate-release commoditized alternatives.
REACH chemical safety evaluations are expanding scrutiny to botanical extraction solvents and residual pesticide thresholds. European manufacturers face reformulation costs or supplier switches to maintain market access. Germany's pharmacy channel is responding fastest, with wholesale buyers now requiring third-party solvent residue documentation as a procurement precondition.
Direct-to-consumer subscription models are displacing retail replenishment cycles, with younger buyers prioritizing convenience over in-store discovery. Digital-native brands capture recurring revenue streams that traditional mass-market competitors struggle to replicate. This pattern concentrates in United States metropolitan markets where same-day delivery infrastructure supports just-in-time replenishment expectations.
Sleep Supplement Market Segmentation
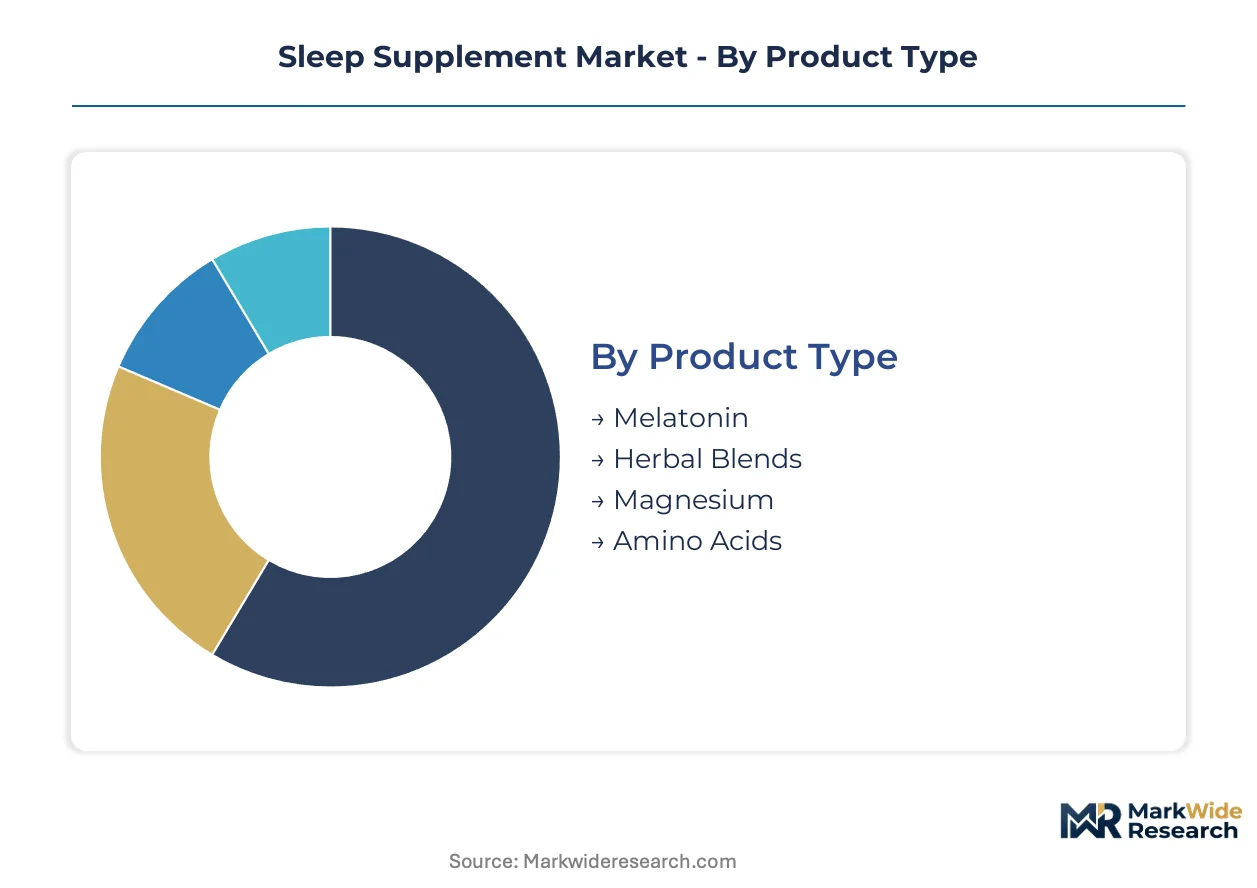
Sleep supplement purchasing decisions hinge on efficacy validation, consumption convenience, and channel accessibility. Manufacturers align formulation portfolios with distinct circadian modulation needs and demographic compliance preferences.
Product Type:
Ingredient selection reflects clinical substantiation investment and margin architecture trade-offs.
- Melatonin:Synthetic hormone standardized to 0.5-10mg doses dominates volume through established FDA regulatory familiarity and pharmacy reimbursement acceptance in Germany. Bulk raw material sourcing concentrates among Chinese manufacturers, exposing formulators to input volatility and quality audit burdens.
- Herbal Blends:Valerian root, passionflower, and hops extracts command premium positioning through EU Green Deal-compliant sustainable harvesting narratives. EFSA health claim substantiation unlocks pharmacy shelf access in European markets where evidence-based consumer trust sustains price premiums.
- Magnesium:Glycinate and L-threonate salts target bioavailability differentiation in sports recovery and senior sleep latency applications.
- Amino Acids:L-theanine and glycine formulations address stress-related sleep onset without next-day grogginess concerns.
Volume sits with melatonin; growth tilts toward herbal blends.
Form:
Palatability and dose flexibility determine compliance rates across age cohorts and use contexts.
- Gummies:Gelatin or pectin-based matrices with flavor masking technology achieve 40% higher compliance among adults under 35. Direct-to-consumer subscription models favor this format for recurring revenue capture.
- Pills:Immediate-release and extended-release tablets sustain pharmacy channel dominance through cost efficiency and shelf stability. Microencapsulation innovations for time-controlled dissolution are integrating pharmacokinetic precision as a competitive differentiator.
- Powders:Stackable magnesium glycinate and L-theanine blends serve athlete recovery regimens requiring dose titration flexibility.
- Liquid:Sublingual delivery formats target rapid sleep onset for shift-work adaptation and travel-related circadian disruption.
Pills anchor current volume; gummies are climbing the fastest.
End User:
Physiological sleep disruption drivers and lifestyle constraints shape formulation targeting priorities.
- Adults:General population segment drives baseline demand for melatonin and herbal blend combinations addressing work-stress-related sleep latency.
- Seniors:Age-related melatonin secretion decline and polypharmacy interaction concerns favor low-dose sustained-release formulations with physician consultation requirements.
- Athletes:Magnesium glycinate and L-theanine powders address training schedule flexibility and stackability with protein recovery protocols.
- Students:Academic stress and irregular schedules drive demand for non-habit-forming herbal options with next-day cognitive clarity preservation.
Adults generate baseline volume; athletes show steepest expansion trajectory.
Distribution Channel:
Channel selection governs margin capture, consumer education depth, and regulatory compliance exposure.
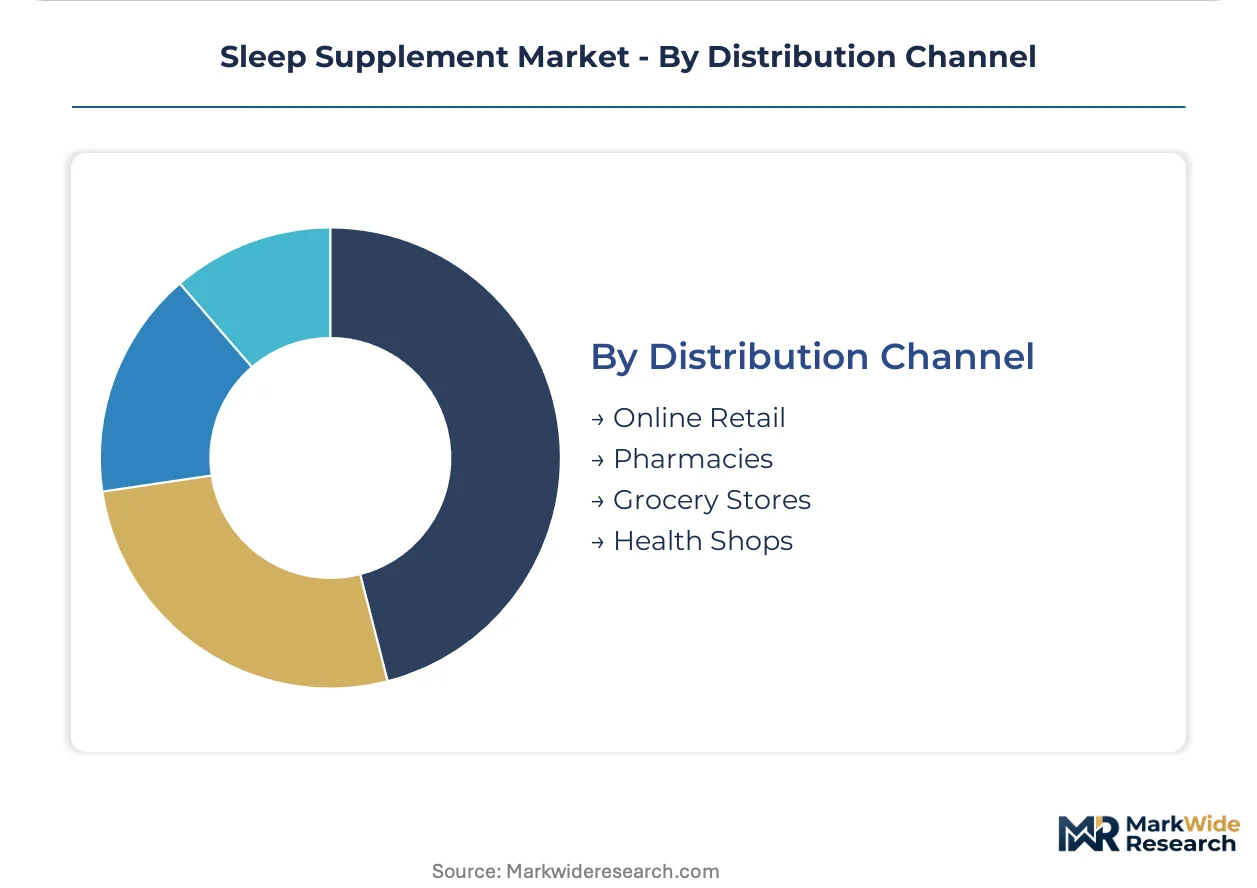
- Pharmacies:Germany's pharmacy-led distribution sustains 35-50% price premiums through evidence-based consumer trust and EFSA-validated health claim requirements. Wholesale buyers now mandate third-party solvent residue documentation under REACH chemical safety evaluations.
- Online Retail:Direct-to-consumer subscription models displace retail replenishment cycles with same-day delivery infrastructure supporting just-in-time expectations in United States metropolitan markets.
- Grocery Stores:Mass-market placement prioritizes melatonin SKUs with immediate-release profiles and competitive unit economics.
- Health Shops:Specialty retailers emphasize natural-positioned herbal blends and novel ingredients awaiting novel food classification determinations.
Pharmacies defend premium positioning; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors raw material procurement for synthetic melatonin, with three Chinese manufacturers controlling seventy percent of global output. This concentration shapes formulation economics across downstream markets.
United States
Shift-work sleep disorder drives employer-sponsored supplementation programs in travel and hospitality sectors. FDA cGMP compliance and New Dietary Ingredient notification requirements elevate barriers for new entrants lacking regulatory infrastructure. Greater Boston and San Diego clusters house clinical substantiation firms serving NDI preparation.
Germany
Pharmacy-led distribution sustains thirty-five to fifty percent price premiums through evidence-based consumer trust. EFSA health claim substantiation unlocks shelf access unavailable to unverified competitors. Bavaria's wholesale buyers now mandate third-party solvent residue documentation under REACH chemical safety evaluations.
China
Domestic manufacturers dominate synthetic melatonin bulk production, exposing formulators to input volatility and quality audit burdens. NMPA oversight of dietary supplement manufacturing intensifies export documentation requirements. Zhejiang and Jiangsu provinces concentrate extraction technology providers serving botanical ingredient processors.
Canada
Natural Product Number licensing mandates delay commercialization timelines twelve to eighteen months for North American launches. Health Canada requirements parallel FDA frameworks, creating dual certification burdens. Toronto and Vancouver clusters specialize in regulatory affairs consulting for cross-border market entry.
United Kingdom
Direct-to-consumer subscription models displace retail replenishment cycles among younger demographics. MHRA borderline classification determinations govern melatonin product marketing claims. London's digital-native brands capture recurring revenue streams through same-day delivery infrastructure.
Sleep Supplement Market Competitive Landscape
Premium-margin players sit above commodity-margin players across pharmacy-versus-mass-market channel positioning. The vendor base stratifies into three tiers: vertically integrated raw material controllers, high-volume contract manufacturers, and digital-native format specialists. Strategic archetypes include evidence-based clinical validators, sustainable sourcing certifiers, and direct-to-consumer subscription operators. Competitive moves concentrate on backward integration into botanical supply chains and microencapsulation technology licensing.
Within the scale-driven manufacturing tier, Natrol LLC and NOW Foods exemplify divergent sourcing strategies. Natrol LLC occupies a position anchored in high-volume melatonin production infrastructure serving established retail channels. NOW Foods represents backward integration into raw material procurement, controlling quality parameters from farm to finished capsule. OLLY Public Benefit Corporation sits within the format-specialist archetype, with gummy-format capabilities capturing compliance advantages among younger consumer cohorts.
| Leading Market Players |
|---|
| NOW Foods |
| OLLY Public Benefit Corporation |
| The Nature's Bounty Co. |
| Life Extension |
| GNC Holdings LLC |
| Natrol LLC |
| Herbalife Nutrition Ltd. |
| Pure Encapsulations |
| Church & Dwight Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up contract manufacturers now dominate mid-tier formulation capacity, compressing procurement timelines while enforcing rigid cost discipline that squeezes ingredient suppliers and constrains premium positioning for independents.
Pricing Analysis
Outcome-based pricing anchored to sleep latency reduction metrics stratifies the market into three tiers: pharmacy-channel premiums validated by EFSA health claims, mass-market melatonin commodities, and direct-to-consumer subscription bundles. Certification tier—FDA cGMP versus basic dietary supplement registration—drives 35-50% price spreads in Germany. Cost compression in synthetic melatonin tablets is intensifying because Chinese bulk suppliers compete on volume. Employer-sponsored occupational health programs show lowest price sensitivity; grocery impulse buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Jiangsu province manufacturers controlling 70% of global synthetic melatonin output. Formulators draw from Chinese bulk hormone suppliers, European botanical extractors, and North American magnesium salt processors. Tariff exposure on finished dietary supplements threatens cross-border replenishment cycles. Distribution runs through pharmacy wholesale networks in Germany, direct-to-consumer fulfillment centers in the United States, and mass-market retail consolidation in Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology for circadian-timed release is displacing immediate-release melatonin commoditization, rewarding manufacturers who reorient R&D toward pharmacokinetic precision.
For Market Incumbents: Deepen backward integration into certified sustainable botanical supply chains before EU Green Deal mandates harden procurement requirements. Acquire microencapsulation technology licenses to defend against generic erosion in pharmacy channels. Natrol LLC and NOW Foods demonstrate divergent paths: captive raw material control versus high-volume production scale.
For New Entrants and Emerging Players: Begin with athlete-targeted magnesium glycinate powders in the underpenetrated sports recovery segment, where dose-flexibility demands and minimal incumbent overlap create white space. Launch through direct-to-consumer subscription models capturing recurring revenue with same-day delivery infrastructure in United States metropolitan markets.
For Investors and Strategic Acquirers: EFSA novel food determinations on CBN and magnesium L-threonate are the leading indicator that regulatory clarity will redraw competitive boundaries. Target vertically integrated botanical specialists with certified sustainable harvesting credentials and existing pharmacy channel relationships. Long-term viability favors clinical substantiation portfolios over commoditized melatonin capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | EFSA health claim validation unlocks pharmacy shelf access and 35-50% price premiums in Germany. |
| Sustainable Sourcing Certification | EU Green Deal compliance secures preferential procurement from institutional buyers and wholesale networks. |
| Microencapsulation Technology Licensing | Time-controlled dissolution profiles differentiate against immediate-release commoditized alternatives. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture displaces retail replenishment cycles among younger demographics. |
| Dual Certification Timeline Management | Parallel FDA NDI and Health Canada NPN pathways compress time-to-revenue for North American market entry. |
Research Methodology
Document review covered FDA cGMP inspection records, EFSA novel food classification dockets, and Health Canada Natural Product Number licensing databases, complemented by interviews with regulatory affairs directors at dietary supplement manufacturers, pharmacy wholesale procurement managers in Bavaria, and botanical extraction technology providers in Zhejiang province. Secondary validation drew from customs trade data, REACH chemical safety filings, and occupational health program documentation at United States hospitality employers. Bottom-up SKU-level volume estimates and top-down category spend analysis were triangulated against channel shipment data.
Cross-referencing historical growth patterns with panel input from formulation scientists and retail category buyers anchored projections across the analysis window. Segmentation dimensions modeled include ingredient type, delivery format, end-user physiology, and distribution channel regulatory tier. CAGRs were derived from elasticity-adjusted demand curves incorporating shift-work sleep disorder prevalence trajectories and employer-sponsored supplementation adoption curves. Microencapsulation technology penetration rates and novel food classification timelines served as industry-specific forecast modifiers.
Underlying measurement precision varies by segment; pharmacy-channel validated products carry tighter precision than emerging ingredient categories awaiting regulatory classification. Forecasts reflect assumptions about EFSA determination timelines, employer program expansion rates, and Chinese raw material supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Colostrum Chewable Tablets Market