
 Global Home Rehabilitation Products and Services Market | 2026-2036
Global Home Rehabilitation Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Rehabilitation Products and Services Market Foresight
The home rehabilitation market is pivoting around a widening split between premium neuro-rehabilitation robotics and commodity mobility aids, with reimbursement tiers determining which patient populations access advanced therapeutic equipment versus basic assistive devices. Medline Industries leverages its distribution scale to dominate commodity supply chains across North American home healthcare networks. Stryker Corporation anchors its position through hospital-to-home discharge coordination, embedding rehabilitation services into surgical episode bundles. DJO Global differentiates via orthopedic bracing specialization that bridges acute recovery and long-term functional restoration.
Home rehabilitation products and services encompass therapeutic equipment, mobility aids, respiratory devices, and professional therapy delivered in residential settings rather than clinical facilities, with functional parameters typically calibrated to patient-specific range-of-motion metrics and activity tolerance thresholds measured through validated assessment instruments. The primary commercial purpose centers on reducing institutional care costs while preserving or restoring patient independence. Tele-rehabilitation services represent the fastest-expanding segment as remote monitoring technologies enable real-time clinician oversight without geographic proximity constraints. Mobility aids constitute the most mature product category, with margin pools shifting toward smart-enabled devices featuring fall-detection sensors and GPS connectivity. Patient lifts command premium positioning due to caregiver safety regulations and bariatric population needs.
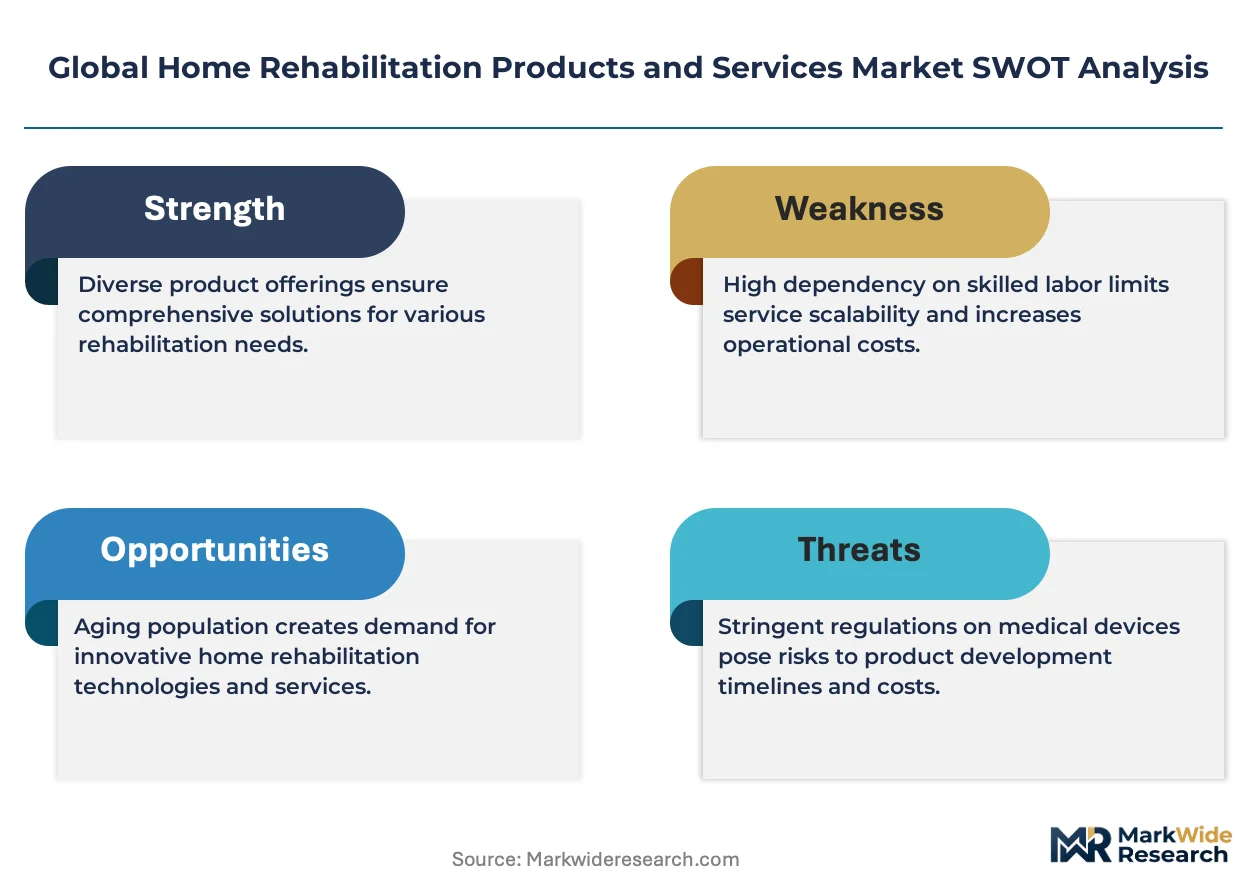
FDA software-as-medical-device frameworks and HIPAA interoperability standards shape product development roadmaps for connected rehabilitation equipment, while the EU MDR and GDPR impose parallel compliance burdens on European market entrants. Reimbursement policy divergence between Medicare Advantage expansion and traditional fee-for-service constraints creates strategic uncertainty for service model design. Stakeholders must monitor regulatory clarity on digital therapeutic prescribing authority to determine platform investment pacing.
Market Dynamics
Medicare Advantage plan expansion is compressing traditional fee-for-service reimbursement timelines, forcing providers to reconfigure service delivery models around capitated episode bundles rather than per-visit billing.
Growth Catalysts
- Hospital discharge acceleration protocols:Post-surgical length-of-stay reductions in the United States are pushing rehabilitation into residential settings faster than facility capacity can absorb.
- FDA software-as-medical-device pathways:Streamlined 510(k) clearances for digital therapeutic platforms are cutting time-to-market for remote monitoring systems by half.
- Tele-rehabilitation infrastructure:HIPAA-compliant video platforms paired with Bluetooth-enabled assessment tools enable real-time clinician oversight without geographic constraints.
Market Restraints
- Semiconductor supply concentration:Sensor chip fabrication bottlenecks in Taiwan are delaying production of smart mobility aids and connected respiratory monitors.
- Reimbursement fragmentation:Divergent Medicare Advantage versus traditional Medicare coverage criteria create administrative complexity for multi-payer service providers.
- Caregiver labor scarcity:Certified home health aide shortages in rural United States counties limit service scalability regardless of equipment availability.
Strategic Opportunities
- India's geriatric care gap:Underpenetrated home rehabilitation services among India's aging population present first-mover advantages for tele-rehabilitation platforms adapted to lower-cost operating models.
- EU MDR digital health incentives:The Medical Device Regulation's software classification clarity is accelerating European market entry for AI-powered gait analysis tools.
- Voice-interface integration:Convergence of natural language processing with environmental control systems enables hands-free device operation for quadriplegic patients.
Industry Challenges
- Interoperability certification delays:HL7 FHIR compliance testing for connected rehabilitation devices stretches product launch timelines by eight to fourteen months.
- Physical therapist licensing reciprocity:State-by-state credentialing requirements block seamless tele-rehabilitation service expansion across United States jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Rehabilitation Products and Services Market |
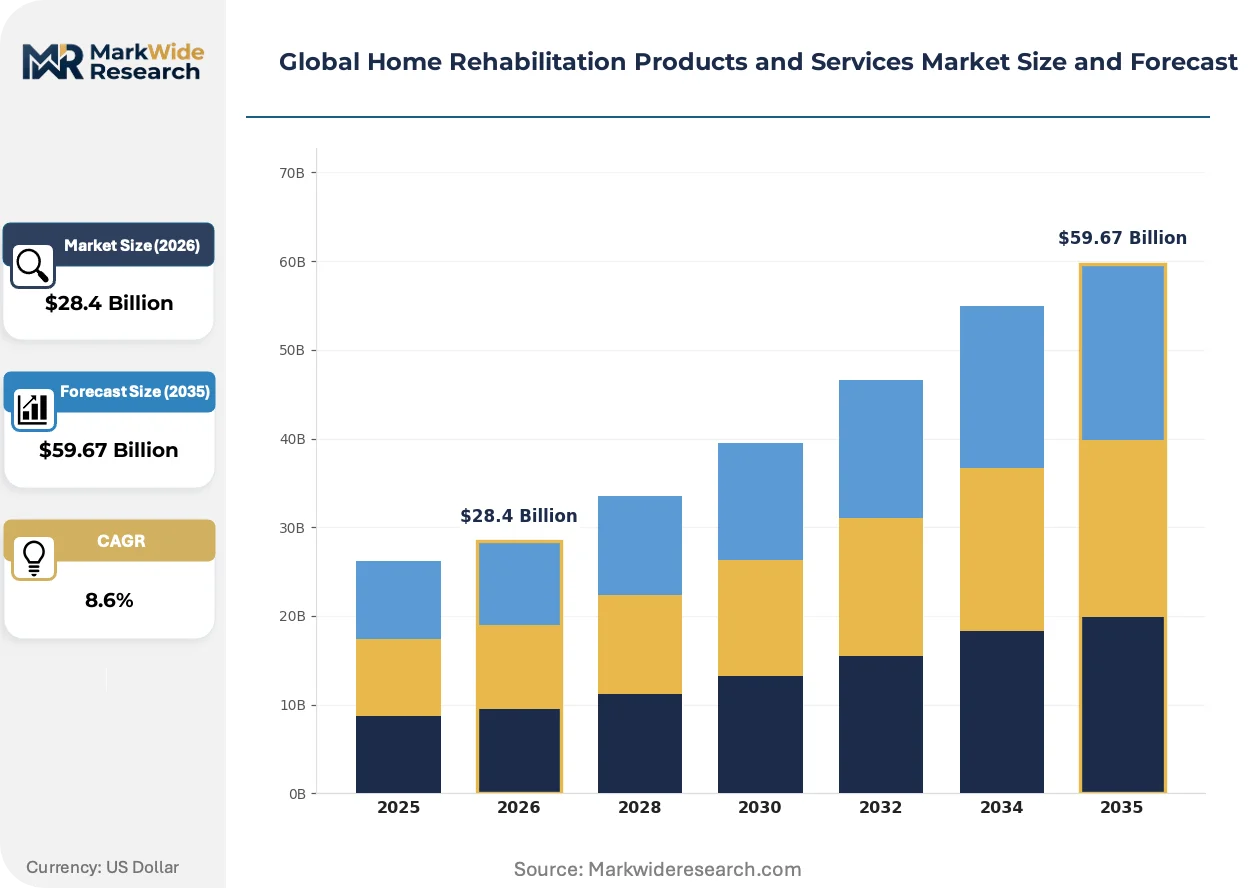
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Therapeutic Equipment, Respiratory Devices, Orthopedic Supports, Patient Lifts Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Respiratory Therapy, Tele-rehabilitation End User: Elderly Patients, Post-Surgical Patients, Neurological Disorder Sufferers, Pediatric Patients, Injured Workers Distribution Channel: Direct Sales, Home Healthcare Providers, Online Retailers, Medical Equipment Suppliers, Specialty Stores |
| Companies Covered | Medline Industries, Stryker Corporation, Invacare Corporation, DJO Global, Hocoma AG, Ekso Bionics Holdings, Inc., Performance Health, LLC, Prism Medical Ltd., AliMed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Rehabilitation Products and Services Market Shifts & Advancements
Sensor miniaturization and edge computing are collapsing the cost curve for real-time biomechanical feedback, enabling consumer-grade devices to deliver previously clinical-grade therapeutic monitoring.
Exoskeleton-assisted gait training is automating repetitive motor pattern reinforcement that previously required two therapists per patient. Stroke rehabilitation centers in Germany and Japan are deploying these systems for home-based programs. The technology is automating labor-intensive neuroplasticity protocols while reducing caregiver injury risk.
The EU Medical Device Regulation's Class IIa software classification is forcing digital therapeutic developers to maintain quality management systems equivalent to hardware manufacturers. European notified bodies are backlogged eighteen months for initial audits. Rehabilitation platform vendors are responding by segregating EU-specific code bases to isolate compliance scope.
Episode-based bundled payments are compressing equipment procurement decisions into pre-discharge windows measured in hours rather than days. Hospital case managers in the United States now select home rehabilitation vendors based on same-day delivery capability. This shift favors distributors with regional warehouse networks over manufacturers selling direct.
Global Home Rehabilitation Products and Services Market Segmentation
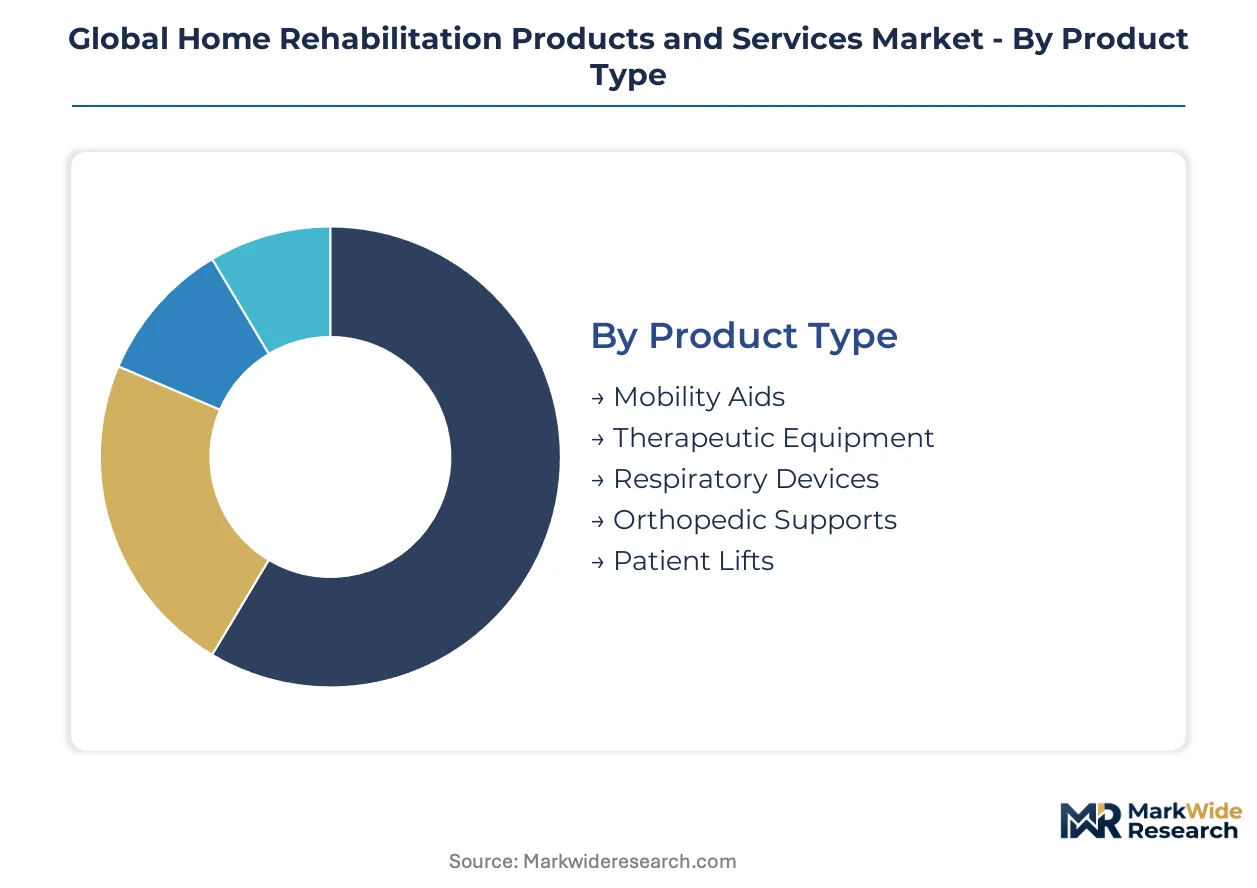
Home rehabilitation markets fragment across equipment, services, and patient populations with divergent reimbursement profiles. Each segment carries distinct regulatory pathways, replacement cycles, and margin structures that shape vendor strategy.
Product Type:
Equipment upgrade cycles accelerate where sensor integration and connectivity create obsolescence pressure against legacy mechanical devices.
- Mobility Aids:Canes, walkers, wheelchairs, and scooters form the volume base. Medicare Advantage plans in Florida and Texas now mandate GPS-enabled fall detection for durable medical equipment coverage.
- Therapeutic Equipment:Continuous passive motion machines, electrical stimulation devices, and thermal therapy systems. Post-surgical knee replacement protocols in Germany and Japan are shortening acute facility stays and expanding residential therapeutic equipment deployment.
- Respiratory Devices:Oxygen concentrators, nebulizers, and ventilators calibrated for home settings. FDA 510(k) clearances for portable oxygen concentrators with Bluetooth telemetry are compressing product development timelines.
- Orthopedic Supports:Braces, splints, and compression garments bridging acute recovery to functional restoration.
- Patient Lifts:Hydraulic and electric transfer systems addressing caregiver safety regulations and bariatric patient needs.
Mobility Aids sits at the top of the volume ranking, with Therapeutic Equipment climbing the fastest.
Service Type:
Service margins concentrate where licensure barriers and technology integration create differentiation against commodity visit-based care.
- Physical Therapy:Musculoskeletal rehabilitation delivered through manual techniques and exercise prescription. State-by-state licensing reciprocity gaps in the United States fragment multi-jurisdictional tele-therapy platforms.
- Occupational Therapy:Activities of daily living training and environmental adaptation. Post-stroke patients in Ontario and British Columbia drive demand for home-based ADL assessment through provincial health authority contracts.
- Speech Therapy:Swallowing and communication rehabilitation for neurological conditions.
- Respiratory Therapy:Ventilator management and pulmonary rehabilitation in residential settings.
- Tele-rehabilitation:Remote monitoring and video-based therapeutic intervention. HIPAA-compliant platforms paired with Bluetooth assessment tools enable real-time clinician oversight without geographic constraints.
Physical Therapy captures the largest service revenue pool, though Tele-rehabilitation is gaining share fastest through platform scalability.
End User:
Patient acuity and reimbursement generosity determine equipment sophistication tiers and service intensity levels.
- Elderly Patients:Age-related functional decline drives demand for mobility aids and fall prevention systems. Japan's super-aged prefectures and Florida's Medicare Advantage penetration create concentrated demand for sensor-enabled home monitoring.
- Post-Surgical Patients:Accelerated discharge protocols push rehabilitation into residential settings faster than facility capacity absorbs. Bundled payment models in the United States compress vendor selection into pre-discharge windows measured in hours.
- Neurological Disorder Sufferers:Stroke, Parkinson's, and multiple sclerosis patients requiring specialized neuro-rehabilitation.
- Pediatric Patients:Developmental and congenital conditions requiring adaptive equipment and family-centered therapy models.
- Injured Workers:Occupational rehabilitation governed by workers' compensation fee schedules with state-specific variability.
Elderly Patients anchor volume demand, while Post-Surgical Patients show the steepest expansion trajectory from hospital discharge acceleration.
Distribution Channel:
Channel power shifts toward same-day fulfillment capability as episode-based bundling compresses procurement timelines.
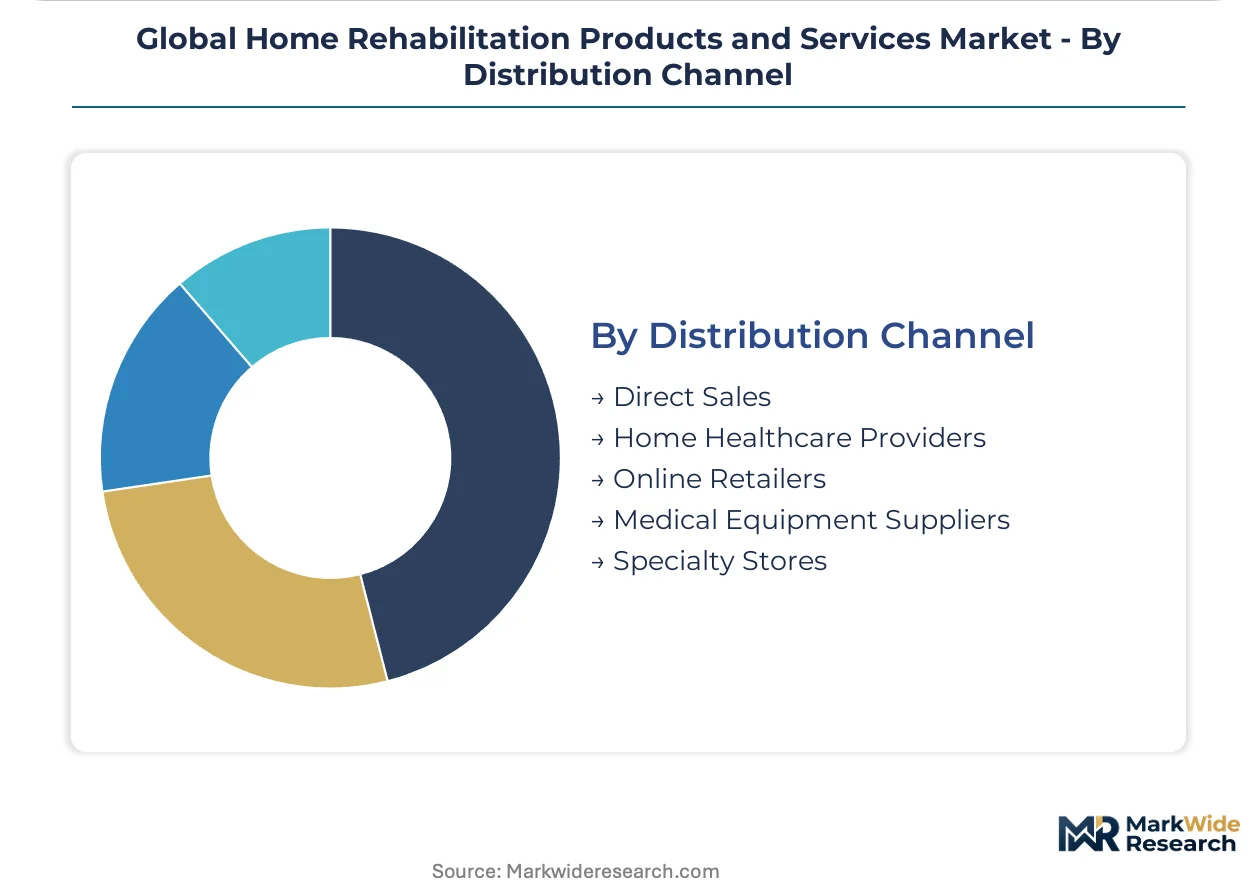
- Direct Sales:Manufacturer-to-patient transactions for premium therapeutic equipment. DJO Global and Stryker deploy direct channels for orthopedic bracing and surgical episode coordination.
- Home Healthcare Providers:Integrated equipment and service bundling under capitated contracts. Medicare Advantage plans in Arizona and Pennsylvania favor vertically integrated providers for episode accountability.
- Online Retailers:E-commerce platforms for commodity mobility aids with consumer-grade specifications.
- Medical Equipment Suppliers:Regional distributors with warehouse networks enabling same-day delivery to hospital discharge planners.
- Specialty Stores:Retail locations with fitting services for custom orthopedic and mobility devices.
Home Healthcare Providers command the highest service-attached revenue, with Online Retailers expanding most quickly in standard product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Physical therapist density in metropolitan Germany and certified home health aide concentrations across the United States Sun Belt anchor regional service capacity. Rehabilitation robotics engineering talent clusters in Swiss and Japanese medical device corridors. Tele-rehabilitation platform development concentrates where HIPAA and GDPR compliance expertise intersects with cloud infrastructure scale.
United States
Medicare Advantage penetration in Florida and Arizona drives demand for bundled home rehabilitation services. FDA 510(k) clearances for software-as-medical-device compress digital therapy platform deployment timelines. Hospital discharge coordinators in Houston and Phoenix select vendors based on same-day equipment delivery capability.
Germany
Post-surgical knee replacement protocols are shortening acute facility stays and expanding residential therapeutic equipment deployment. EU MDR Class IIa software classification mandates quality management systems equivalent to hardware manufacturers. Stroke rehabilitation centers in Munich and Heidelberg deploy exoskeleton-assisted gait training for home-based neuroplasticity programs.
Japan
Super-aged prefectures concentrate demand for sensor-enabled home monitoring and fall prevention systems. METI medical device approval pathways accommodate AI-powered gait analysis tools. Rehabilitation robotics development in Nagoya and Osaka corridors automates labor-intensive motor pattern reinforcement.
India
Underpenetrated home rehabilitation services among the aging population present first-mover advantages for tele-rehabilitation platforms. CDSCO medical device regulations are adapting to software-as-medical-device classifications. Bengaluru and Hyderabad technology clusters enable lower-cost remote monitoring operating models.
Switzerland
Swissmedic regulatory clarity supports premium neuro-rehabilitation robotics development for export markets. GDPR-aligned data governance frameworks attract digital therapeutic platform headquarters. Zurich and Basel medical device engineering corridors specialize in biomechanical feedback systems for home deployment.
Global Home Rehabilitation Products and Services Market Competitive Landscape
Top-tier vendors anchor hospital-to-home discharge coordination, while mid-scale distributors compete on regional warehouse density and same-day fulfillment. The vendor base stratifies across three tiers: integrated equipment-service bundlers, specialized therapeutic device manufacturers, and commodity mobility aid distributors. Two dominant competitive moves are vertical acquisition of home healthcare providers and technology licensing partnerships for Bluetooth-enabled assessment tools.
Within the integrated service tier, Medline Industries and Stryker Corporation exemplify divergent scale strategies. Medline leverages North American distribution networks to dominate commodity supply chains for durable medical equipment. Stryker anchors positioning through surgical episode bundle integration, embedding rehabilitation services into hospital discharge workflows. DJO Global occupies a specialization position bridging orthopedic bracing between acute recovery and long-term functional restoration.
| Leading Market Players |
|---|
| Medline Industries |
| Stryker Corporation |
| Invacare Corporation |
| DJO Global |
| Hocoma AG |
| Ekso Bionics Holdings, Inc. |
| Performance Health, LLC |
| Prism Medical Ltd. |
| AliMed, Inc. |
| Others |
Supply & Pricing Matrix
EU MDR sustainability and lifecycle traceability mandates gate qualified supply access and premium-tier pricing eligibility for connected rehabilitation equipment manufacturers seeking European market entry. Buyers with certified quality management systems command pricing power in bundled service contracts while commodity mobility aid suppliers face margin compression from unbundled transactional procurement.
Pricing Analysis
Bundled episode-based payment models dominate hospital discharge coordination, while unbundled per-visit billing persists in traditional fee-for-service channels. Pricing stratifies across premium neuro-rehabilitation robotics, standard therapeutic equipment with Bluetooth telemetry, and economy mechanical mobility aids without connectivity. Cost compression in the commodity tier intensifies because Medicare Advantage plans mandate sensor-enabled fall detection for durable medical equipment coverage. Post-surgical patients in bundled payment corridors show lowest price sensitivity; rural elderly patients purchasing canes and walkers through online retailers exhibit highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-supplier qualification for patient lifts and respiratory devices to mitigate caregiver safety liability exposure. Component manufacturing concentrates in Taiwan for sensor chip fabrication, China for injection-molded plastic housings, and Germany for precision drive systems in exoskeletons. Supply chains draw from semiconductor foundries, medical-grade polymers, and rare-earth magnet suppliers. Single-source vulnerability in Taiwan sensor fabrication creates production delays for smart mobility aids. Distribution runs through regional medical equipment suppliers with same-day delivery capability to hospital discharge planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA software-as-medical-device clearance acceleration and Medicare Advantage expansion compound demand generation for integrated home rehabilitation platforms.
For Market Incumbents: Deploy hospital-to-home discharge coordination as the primary defensive lever. Deepen backward integration into tele-rehabilitation platform development to counter digital therapeutic entrants. Secure same-day delivery warehouse density in Sun Belt metropolitan corridors to maintain vendor selection preference from hospital case managers operating under compressed bundled payment windows. For New Entrants and Emerging Players: Hospital-at-home program coordinators represent the most accessible channel partner type for platform-based service insertion. India's underpenetrated geriatric rehabilitation services offer white-space expansion with lower-cost tele-rehabilitation operating models adapted to price-sensitive patient populations. Target post-surgical knee and hip replacement protocols in Germany and Japan where acute length-of-stay compression outpaces facility capacity absorption. For Investors and Strategic Acquirers: Roll-up economics work for regional home healthcare providers because Medicare Advantage capitation creates scale advantages in episode accountability and same-day fulfillment infrastructure. Five-to-ten year viability hinges on reimbursement policy convergence between bundled and fee-for-service models. Watch FDA digital therapeutic prescribing authority clarity as the inflection signal determining platform investment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates time-to-market for remote monitoring platforms by compressing regulatory review timelines. |
| Hospital System Partnership | Embeds rehabilitation services into surgical episode bundles through discharge coordinator relationships. |
| CE Marking Pathway under EU MDR | Opens European market access for AI-powered gait analysis tools with Class IIa software classification. |
| Software Companion Development | Enables Bluetooth-enabled assessment tools for real-time clinician oversight in tele-rehabilitation delivery. |
| Reimbursement Strategy | Aligns service model design with Medicare Advantage coverage expansion and traditional fee-for-service constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hospital discharge coordinators, home healthcare agency executives, biomedical engineers, Medicare Advantage plan contracting officers, and physical therapy licensure board administrators. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU MDR notified body audit records, and hospital procurement contract filings. Bottom-up equipment shipment modeling and top-down service revenue estimation were cross-checked for convergence.
Historical reference periods anchored volume and value trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product type, service delivery mode, patient acuity tier, and distribution channel structure. CAGRs were synthesized from equipment replacement cycle analysis, service penetration rate trending, and reimbursement policy elasticity assessment. Forecast inputs incorporated sensor cost curve decline rates and tele-rehabilitation platform adoption velocity by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization, Medicare Advantage penetration velocity, and physical therapist licensing reciprocity legislation. Deviation in FDA digital therapeutic prescribing authority timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market