
 US Orthopedic Implants Market | 2026-2036
US Orthopedic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
US Orthopedic Implants Market Insights
Asset-light leasing models for robotic surgical systems is rewriting capital deployment across orthopedic service lines. Stryker leverages its installed base of Mako surgical robots to lock in implant pull-through. Zimmer Biomet sustains competitiveness through backward integration into titanium forging operations. Johnson & Johnson Services, Inc. anchors its position via dense contracting with academic medical centers.
Orthopedic implants are load-bearing prosthetic devices manufactured from cobalt-chrome alloys, titanium, or ceramics, designed to replace or stabilize damaged bone and joint structures through mechanical fixation or articulating surfaces. Hip implants and knee implants command the largest revenue pools, though spinal devices and robotic-assisted surgery represent the fastest-expanding technology layer. Ceramic components and titanium alloys dominate material selection where longevity and biocompatibility determine revision risk. Ambulatory surgical centers and orthopedic clinics are capturing volume migration as payers narrow hospital reimbursement differentials for routine arthroplasty.
FDA 510(k) premarket notification and NHTSA adverse event reporting requirements shape product liability exposure and post-market surveillance obligations for manufacturers. The IRA Medicare price negotiation provisions for selected Part B drugs are extending scrutiny toward implantable device costing models. Stakeholders must monitor CMS procedural coding decisions that determine site-of-service economics between hospitals and freestanding surgical facilities.
Market Dynamics
Site-of-service migration from hospitals to ambulatory surgical centers is compressing implant procurement cycles and forcing manufacturers to reconfigure distribution logistics around freestanding facilities.
Growth Catalysts
- IRA Medicare Provisions:The Inflation Reduction Act's cost scrutiny on Part B drugs is extending analytical frameworks toward implantable device economics, prompting providers to optimize implant selection for total episode value.
- 3D-Printed Patient-Specific Implants:FDA 510(k) clearance pathways for additive-manufactured orthopedic devices are compressing development timelines from design to commercial implantation.
- Retiree Migration Clusters:Demand concentrates in Florida, Texas, and Arizona where demographic inflows elevate elective procedure scheduling and implant consumption density.
Market Restraints
- Cobalt-Chrome Alloy Supply Concentration:Specialized foundry capacity for medical-grade cobalt-chrome concentrates among a limited supplier base, exposing manufacturers to input volatility and qualification delays.
- FDA Premarket Notification Friction:510(k) substantial equivalence determinations for novel bearing surfaces or porous coatings create regulatory uncertainty that extends commercialization timelines.
- Ceramic Component Brittleness:Ceramic-on-ceramic articulating surfaces carry catastrophic fracture risk that constrains application in high-impact patient populations and younger active demographics.
Strategic Opportunities
- Outpatient Joint Replacement Expansion:Payer approval for total knee and hip arthroplasty in ambulatory surgical centers creates volume capture potential outside traditional hospital purchasing agreements.
- Robotic-Assisted Surgery Convergence:Integration of haptic feedback systems with preoperative planning software is collapsing the learning curve for complex revision procedures.
- CMS Site-of-Service Recalibration:Procedural coding decisions that narrow hospital reimbursement differentials for routine arthroplasty accelerate freestanding facility investment.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 biological evaluation protocols for novel surface treatments extend validation timelines and strain regulatory affairs capacity.
- Legacy EHR Integration Complexity:Implant tracking systems must interface with heterogeneous hospital information architectures, complicating Unique Device Identifier compliance and recall management.
- Orthopedic Surgeon Training Gaps:Robotic platform proficiency requires dedicated proctoring programs that constrain deployment velocity and concentrate expertise within academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Orthopedic Implants Market |
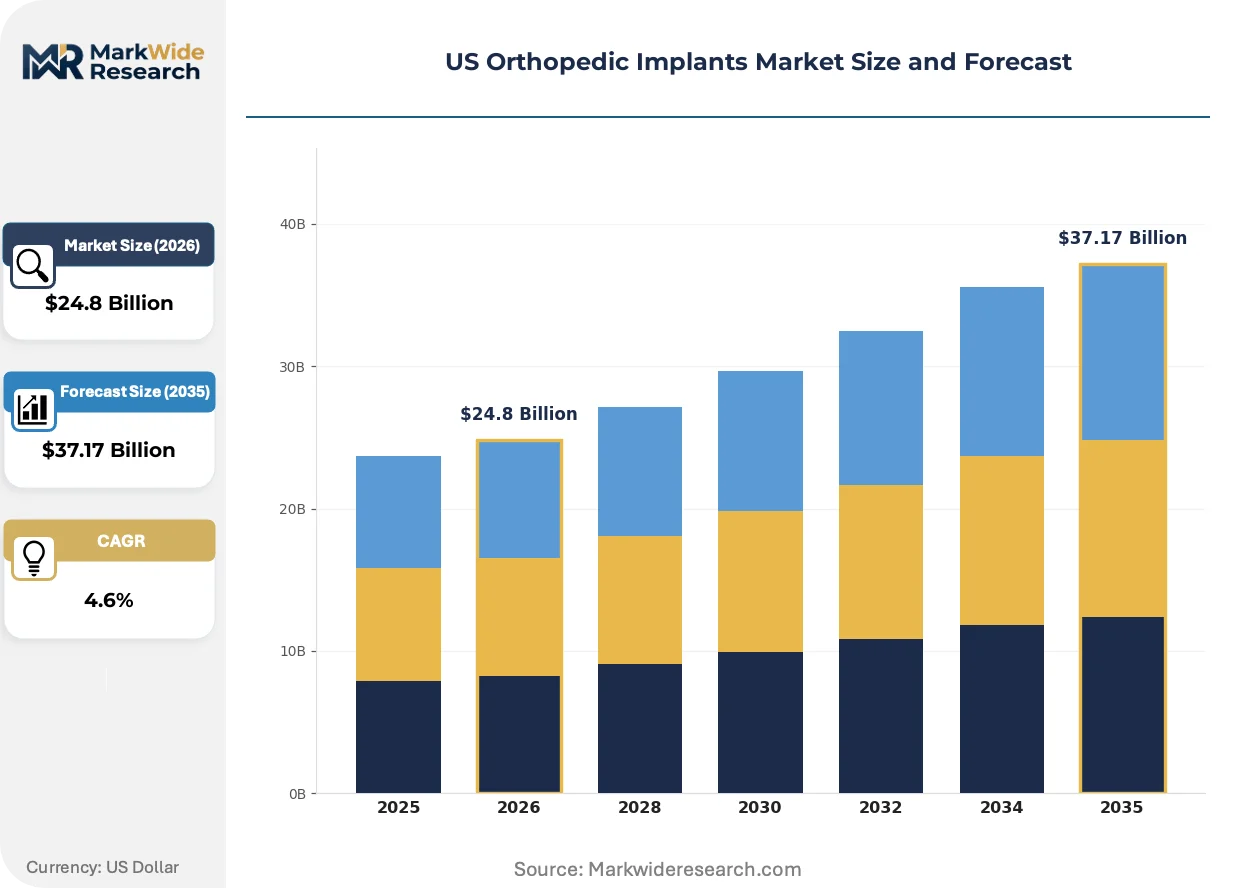
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Implants, Knee Implants, Spinal Devices, Shoulder Implants, Elbow Implants, Ankle Implants Technology: 3D Printing, Biodegradable Materials, Navigation Systems, Robotic-Assisted Surgery, Ceramic Components, Titanium Alloys Application: Fracture Fixation, Joint Replacement, Spinal Fusion, Arthroscopy, Trauma Treatment, Pediatric Orthopedics End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers, Specialty Clinics, Academic Medical Centers |
| Companies Covered | Zimmer Biomet, Stryker, Johnson & Johnson Services, Inc., Smith+Nephew, Medtronic, Arthrex, Inc., Globus Medical, CONMED Corporation, Enovis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Orthopedic Implants Market Trends and Innovations
Digital manufacturing workflows and patient-matched implant geometries are collapsing traditional economies of scale in orthopedic production, enabling lot-size-one manufacturing at viable unit economics.
Patient-specific instrumentation derived from preoperative CT segmentation is collapsing the variability in component positioning that drives revision surgery rates. Ambulatory surgical centers in Arizona and Florida are adopting these guides fastest, compressing operative time and reducing instrument tray sterilization burdens. The structural consequence is a shift from hospital-owned sterilization infrastructure toward vendor-managed instrument logistics.
FDA 510(k) clearance pathways for 3D-printed titanium implants are accelerating commercial entry for lattice-structured acetabular cups and patient-matched cranial plates. The agency's guidance on additive manufacturing quality systems is forcing manufacturers to document powder reuse protocols and build-chamber environmental controls. Spinal fusion cages and maxillofacial reconstruction plates represent the categories most affected, with sponsors responding through dedicated quality management system modules.
Episode-based payment bundles from commercial payers are compressing implant procurement autonomy for hospital materials managers. Freestanding surgical facilities in Texas are consolidating purchasing through orthopedic-focused group purchasing organizations, displacing hospital-centric contracting structures. This behavioral shift is most visible in total joint replacement, where facility-specific implant contracts now override physician preference item traditions.
US Orthopedic Implants Market Segmentation
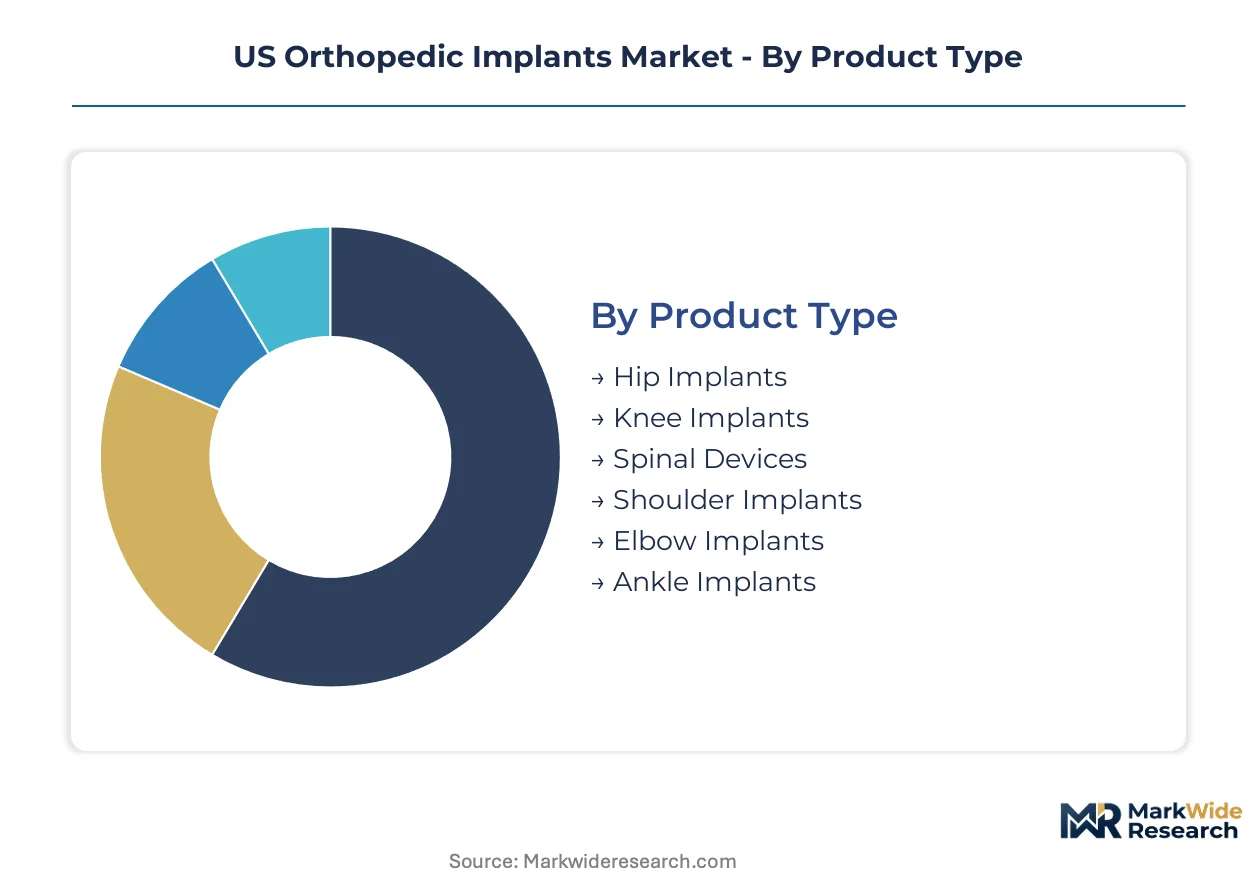
Orthopedic implant procurement cycles vary dramatically by product durability and surgical setting. Revision schedules and site-of-service migration patterns create distinct velocity profiles across segment categories.
Product Type:
Replacement intervals span from permanent fixation hardware to decade-limited articulating surfaces, creating divergent revenue recognition patterns.
- Hip Implants:Cobalt-chrome femoral heads articulate against polyethylene or ceramic liners in load-bearing configurations. Florida retiree clusters drive primary replacement volume, while ceramic component brittleness limits application in younger demographics.
- Knee Implants:Titanium tibial trays support polyethylene inserts in hinged or condylar designs. Texas ambulatory surgical centers are capturing fastest volume migration as payer approval for outpatient arthroplasty expands.
- Spinal Devices:Interbody cages and pedicle screw systems address degenerative disc disease and deformity correction.
- Shoulder Implants:Reverse total shoulder arthroplasty dominates revision scenarios with rotator cuff deficiency.
- Elbow Implants:Linked and unlinked designs address trauma sequelae and rheumatoid destruction.
- Ankle Implants:Total ankle replacement competes with arthrodesis for end-stage arthritis, constrained by bearing surface longevity concerns.
Hip implants dominate installed base. Knee implants are where expansion concentrates.
Technology:
Material selection and manufacturing method determine biocompatibility profiles and regulatory pathway complexity.
- 3D Printing:Additive manufacturing of titanium lattice structures enables patient-specific geometries with optimized osseointegration. FDA 510(k) clearance pathways for porous acetabular cups are compressing development timelines.
- Robotic-Assisted Surgery:Haptic feedback systems integrated with preoperative planning software reduce component positioning variability. Arizona surgical facilities are deploying these platforms fastest for outpatient joint replacement.
- Titanium Alloys:Ti-6Al-4V and commercially pure titanium dominate structural components requiring fatigue resistance.
- Ceramic Components:Alumina and zirconia-toughened alumina provide low-wear articulation with catastrophic fracture risk.
- Biodegradable Materials:Magnesium and polymer-based fixation devices eliminate secondary removal surgery in pediatric applications.
- Navigation Systems:Optical and electromagnetic tracking guides instrument positioning without capital-intensive robotic infrastructure.
Titanium alloys anchor current production volumes. Robotic-assisted surgery is gaining share fastest.
Application:
Procedure reimbursement and site-of-service economics reshape demand concentration across clinical indications.
- Joint Replacement:Total hip and knee arthroplasty command the largest revenue pools with established episode-based payment models. CMS procedural coding decisions are narrowing hospital reimbursement differentials for routine cases.
- Spinal Fusion:Interbody and posterolateral fusion address degenerative conditions and deformity. Florida academic medical centers concentrate complex revision volume requiring navigated instrumentation.
- Fracture Fixation:Plates, screws, and intramedullary nails stabilize traumatic injuries across anatomies.
- Arthroscopy:Soft tissue repair and debridement procedures utilize disposable shavers and fixation devices.
- Trauma Treatment:Emergency fracture management requires immediate implant availability without patient-matched manufacturing delays.
- Pediatric Orthopedics:Growth-preserving implants and biodegradable fixation address skeletal immaturity constraints.
Joint replacement dominates procedure volume. Spinal fusion is climbing the fastest as navigated techniques expand indications.
End User:
Capital intensity and sterilization infrastructure requirements filter implant procurement authority across facility types.
- Ambulatory Surgical Centers:Freestanding facilities in Texas and Arizona are consolidating purchasing through orthopedic-focused group purchasing organizations. Payer approval for outpatient joint replacement is displacing hospital-centric contracting structures.
- Hospitals:Academic medical centers anchor complex revision and trauma volume with dense research infrastructure. Johnson & Johnson Services, Inc. leverages dense contracting with these institutions.
- Orthopedic Clinics:Office-based settings concentrate preoperative planning and postoperative surveillance.
- Rehabilitation Centers:Post-acute facilities influence implant selection through outcome reporting in bundled payment arrangements.
- Specialty Clinics:Sports medicine and hand surgery centers drive niche procedure volume with surgeon-specific instrument preferences.
- Academic Medical Centers:Training programs and research protocols shape early adoption of robotic platforms and patient-specific instrumentation.
Hospitals retain complex case volume. Ambulatory surgical centers are capturing share fastest in routine arthroplasty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida commands premium pricing leverage over Texas for ceramic hip components, while Arizona's ambulatory surgical centers extract volume discounts through consolidated purchasing power that hospitals in the Northeast cannot match.
Florida
Retiree migration clusters in Tampa and Orlando drive elective joint replacement scheduling density unmatched elsewhere. FDA 510(k) clearance timelines for patient-specific implants compress as sponsors prioritize submissions targeting Florida's high-volume surgeons. Miami academic medical centers anchor complex revision procedures requiring navigated instrumentation.
Texas
Dallas-Fort Worth and Houston ambulatory surgical centers capture fastest volume migration as commercial payers approve outpatient total knee arthroplasty. CMS procedural coding decisions narrowing hospital reimbursement differentials accelerate freestanding facility investment across the state's metropolitan corridors. Texas Medical Center in Houston concentrates robotic platform deployment for complex cases.
Arizona
Phoenix and Tucson surgical facilities adopt patient-specific instrumentation fastest, collapsing operative time and reducing sterilization burdens. The IRA Medicare provisions extend cost scrutiny toward implantable device economics, prompting Arizona providers to optimize selection for total episode value. Sun City retiree communities generate predictable demand cycles for primary hip and knee replacement.
California
Los Angeles and San Francisco academic medical centers shape early adoption of 3D-printed titanium lattice structures through research protocols. ISO 10993 biocompatibility testing bottlenecks for novel surface treatments strain regulatory affairs capacity among sponsors with California-based operations. Stanford and UCLA anchor training pipelines for robotic platform proficiency.
New York
Manhattan and Long Island hospitals retain complex trauma and revision volume through dense research infrastructure. Johnson & Johnson Services, Inc. leverages dense contracting with New York-Presbyterian and Mount Sinai networks. Upstate New York orthopedic clinics concentrate postoperative surveillance and bundled payment outcome reporting.
US Orthopedic Implants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and bearings. The vendor base organizes around three strategic archetypes: diversified conglomerates with robotic ecosystems, mid-cap implant pure-plays with backward integration into forging, and emerging additive manufacturing specialists. Consolidation pressure intensifies as episode-based payment bundles compress procurement autonomy. M&A activity targets robotic platform capabilities and patient-specific manufacturing workflows.
Within the diversified conglomerate tier, Stryker and Zimmer Biomet occupy positions defined by installed base scale and captive supply chain control. Johnson & Johnson Services, Inc. anchors the academic medical center contracting vector through dense institutional relationships. These three entities exemplify competitive positioning built on capital intensity, surgeon training infrastructure, and purchasing consortium leverage rather than component pricing alone.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Johnson & Johnson Services, Inc. |
| Smith+Nephew |
| Medtronic |
| Arthrex, Inc. |
| Globus Medical |
| CONMED Corporation |
| Enovis |
| Others |
Pricing and Supply Chain Analysis
Port of Long Beach container throughput cost dynamics amplify supply concentration effects for cobalt-chrome alloy shipments, compressing margins for manufacturers locked into long-haul freight contracts while enabling price differentiation between just-in-time premium tiers and standard inventory-buffered procurement.
Pricing Analysis
The customization-premium spread between patient-matched 3D-printed implants and standard catalog components now exceeds three-to-one across hip and knee categories. Pricing stratifies across premium, standard, and economy tiers driven by FDA clearance pathway complexity and surgeon training certification level. Cost compression in standard polyethylene insert categories is intensifying because ambulatory surgical centers consolidate purchasing through orthopedic-focused GPOs. Hospital systems exhibit lowest price sensitivity due to bundled payment risk retention, while freestanding ASCs in Texas and Arizona demonstrate highest sensitivity as they compete on episode-based cost targets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for titanium sponge and precision-forged components. Manufacturing concentration in the United States, Germany, and Switzerland anchors high-reliability hip and knee implant production, drawing from specialized cobalt-chrome foundries and ceramic bearing suppliers. Raw material dependencies center on medical-grade titanium alloys, cobalt-chrome superalloys, and alumina ceramic blanks. Single-source vulnerability persists for electron-beam melting powder feedstock qualified to FDA additive manufacturing guidance. Distribution runs through manufacturer-direct sales forces for hospital systems, with third-party logistics providers managing instrument tray circulation to ambulatory facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US orthopedic implants market sits in early-cycle recovery as elective procedure deferrals from prior years release pent-up revision demand and retiree migration accelerates primary arthroplasty scheduling in Sun Belt states.
For Market Incumbents: Harden implant pull-through economics by deepening backward integration into titanium forging operations and locking in exclusive robotic platform agreements with high-volume ASC chains. Defend against additive manufacturing specialists by accelerating FDA 510(k) submissions for patient-specific instrumentation. Priority investment targets haptic feedback system training infrastructure to concentrate surgeon proficiency within captive proctoring networks.
For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in secondary Texas metropolitan corridors represent the most penetrable entry point for robotic-assisted surgery platform challengers. Arizona freestanding facilities adopting patient-specific instrumentation fastest offer white-space for disposable guide manufacturing partnerships. Go-to-market execution should anchor on GPO contracting bypass strategies that undercut incumbent hospital-centric pricing structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming orthopedic divisions lacking robotic ecosystem integration. Long-term viability across the next decade hinges on episode-based payment bundle capture rather than component pricing power. Monitor CMS procedural coding decisions narrowing hospital reimbursement differentials as the inflection signal for ASC volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Patient-Specific Instrumentation Partnership | Reduces operative time and sterilization burdens for ASCs in Arizona and Florida. |
| FDA 510(k) Acceleration Program | Compresses clearance timelines for 3D-printed titanium lattice acetabular cups. |
| Robotic Platform Training Infrastructure | Builds surgeon proficiency concentration within academic medical center networks. |
| Orthopedic-Focused GPO Consolidation | Displaces hospital-centric contracting for Texas ambulatory surgical centers. |
| Backward Integration into Titanium Forging | Captures margin and insulates against cobalt-chrome supplier concentration risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare claims data, hospital procurement contract repositories, and SEC filings of publicly traded device manufacturers. Bottom-up volume estimates by procedure type and implant category were triangulated against top-down market sizing derived from manufacturer revenue disclosures and distributor channel audits.
Calibration against historical implant revision rates and site-of-service migration patterns anchored the analytical framework across the projection horizon. Segmentation modeling captured product type, technology platform, application indication, and end-user facility category dimensions. CAGRs were derived from regression analysis of procedure volume growth, pricing trend assumptions, and technology substitution curves. Specific forecast inputs included retiree demographic migration projections and payer policy evolution toward outpatient joint replacement authorization.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, commercial payer bundle design, or cobalt-chrome alloy commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and surgeon training adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Orthopedic Consumables Market