
 Global Plastic Surgery Devices Market | 2026-2036
Global Plastic Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Surgery Devices Market Foresight
The direct-to-clinic distribution channel is narrowing as manufacturers consolidate relationships with high-volume aesthetic centers and specialized hospitals. AbbVie Inc. (Allergan) leverages its injectables heritage to anchor premium device portfolios across North American and European clinics. Zimmer Biomet Holdings Inc. competes through its established orthopedic surgical infrastructure, extending capital equipment reach into reconstructive plastic surgery suites. Stryker Corporation dominates craniomaxillofacial and microsurgical instrument lines, controlling supply relationships with academic medical centers.
Plastic surgery devices comprise electromechanical and energy-delivery instruments engineered for tissue manipulation, contouring, and aesthetic modification, typically operating at wavelengths between 532 nm and 10,600 nm for laser-based systems or generating radiofrequency energy at 1-40 MHz for thermal remodeling procedures. These devices serve commercial purposes across reconstructive correction, elective cosmetic enhancement, and post-traumatic restoration in outpatient and inpatient settings. Laser systems command substantial margin pools due to consumable handpiece replacement cycles and service contract attach rates, while cryolipolysis devices represent the fastest-expanding product type as non-invasive body contouring displaces traditional liposuction in wellness centers. Radiofrequency equipment occupies a mature growth trajectory in skin tightening applications, though manufacturers are repositioning these platforms toward combination therapy protocols with microneedling attachments.
The US FDA regulates these devices under 510(k) and de novo pathways for energy-based surgical equipment, while the EU Medical Device Regulation (MDR) imposes strengthened clinical evidence requirements and post-market surveillance obligations across CE-marked products. Health Canada's Therapeutic Products Directorate maintains parallel review standards that delay market entry for novel laser platforms without predicate device alignment. Stakeholders must monitor evolving reimbursement classifications for non-invasive aesthetic procedures, as private payer coverage denials reshape clinic capital expenditure cycles and device financing structures.
Market Dynamics
The US FDA's tightened 510(k) clearance pathways for energy-based surgical equipment are compressing product development timelines and elevating compliance costs, forcing manufacturers to consolidate direct-to-clinic distribution around high-volume aesthetic centers and academic medical centers.
Growth Catalysts
- Non-invasive facial rejuvenation protocols:Aesthetic centers in South Korea are expanding device procurement for laser and radiofrequency systems that reduce patient downtime. Seoul's Gangnam district now hosts the densest concentration of high-throughput clinics globally.
- EU Medical Device Regulation (MDR) harmonization:Strengthened clinical evidence requirements and post-market surveillance obligations are accelerating consolidation among CE-marked manufacturers with robust quality management systems.
- Cryolipolysis platform adoption:Wellness centers across Brazil's private clinic corridor spanning São Paulo and Rio de Janeiro are displacing traditional liposuction with non-invasive body contouring devices.
Market Restraints
- Consumable handpiece replacement cycles:Laser systems command substantial margin pools through recurring service contracts, but clinic capital expenditure cycles face pressure from private payer coverage denials for aesthetic procedures.
- Predictive device alignment requirements:Health Canada's Therapeutic Products Directorate maintains parallel review standards that delay market entry for novel laser platforms without established predicates.
- Radiofrequency equipment maturity:Skin tightening applications face saturation as manufacturers reposition platforms toward combination therapy protocols, compressing standalone system pricing.
Strategic Opportunities
- Microneedling attachment convergence:Radiofrequency equipment manufacturers are integrating microneedling capabilities to capture combination therapy revenue streams in North American and European clinics.
- Post-traumatic restoration demand:Reconstructive correction applications in outpatient settings present underpenetrated volume for craniomaxillofacial and microsurgical instrument lines.
- Academic medical center partnerships:Stryker Corporation's supply relationship model with teaching hospitals offers a template for capital equipment financing structures that bypass traditional distributor markups.
Industry Challenges
- 510(k) submission complexity:Energy-based surgical equipment manufacturers face extended FDA review timelines as the agency demands more substantial equivalence demonstrations for laser wavelengths between 532 nm and 10,600 nm.
- Service contract attach rate execution:Clinic procurement teams are unbundling after-sales support from initial capital purchases, pressuring manufacturer recurring revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Surgery Devices Market |
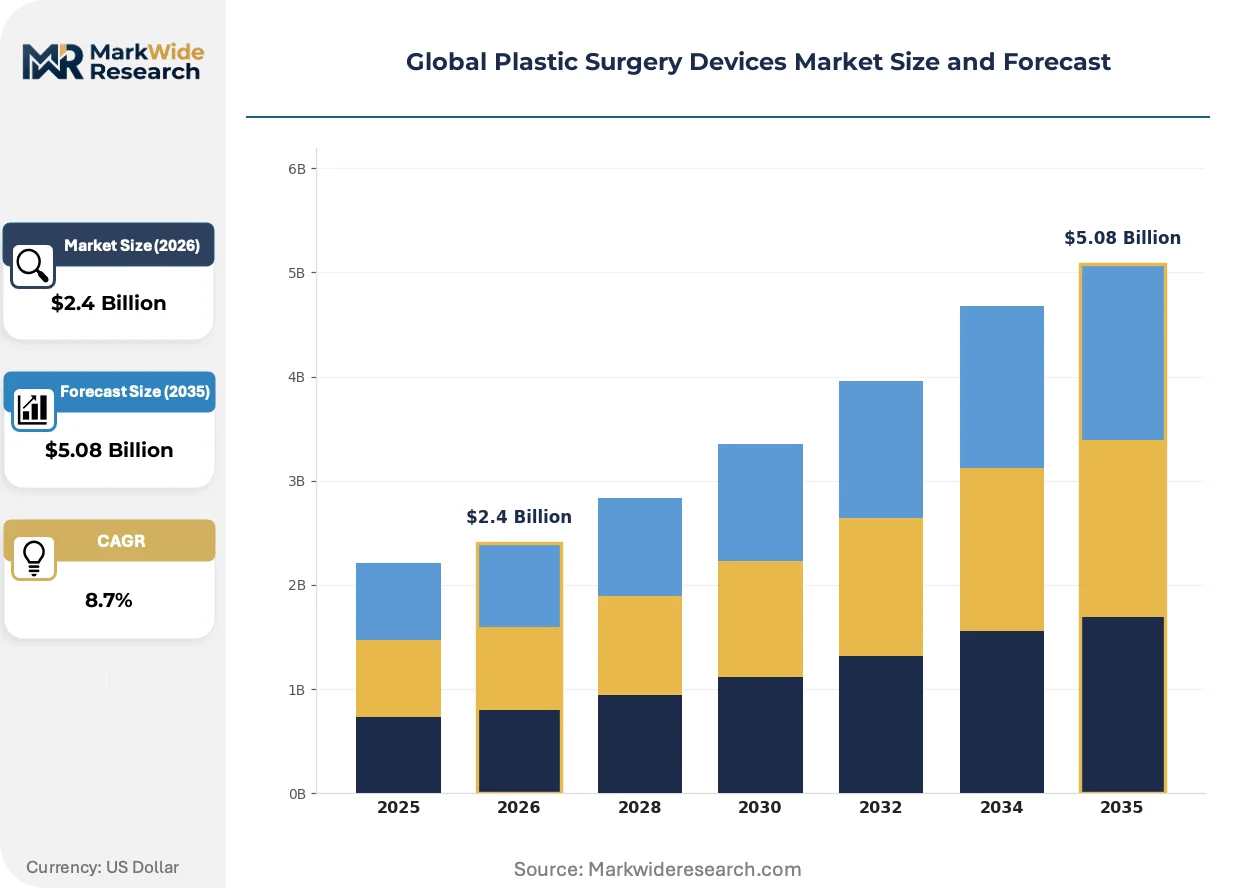
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposuction Machines, Laser Systems, Ultrasound Devices, Radiofrequency Equipment, Cryolipolysis Devices, Sclerotherapy Tools Technology: CO2 Laser, Erbium Laser, Intense Pulsed Light, Microdermabrasion, Electrosurgery, LED Therapy Application: Body Contouring, Scar Revision, Breast Augmentation, Facial Rejuvenation, Skin Tightening, Tattoo Removal End User: Plastic Surgeons, Dermatology Clinics, Aesthetic Centers, Specialized Hospitals, Cosmetic Surgery Institutes, Wellness Centers |
| Companies Covered | AbbVie Inc. (Allergan), Zimmer Biomet Holdings Inc., Integra LifeSciences Corporation, Stryker Corporation, B. Braun Melsungen AG, KLS Martin Group, KARL STORZ SE & Co. KG, Johnson & Johnson Services, Inc., BMT Medizintechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Surgery Devices Market Shifts & Advancements
Device architecture is converging around multi-wavelength platforms and modular handpiece systems that enable procedure-specific customization without full system replacement, compressing capital refresh cycles.
Fractional laser technology is migrating from ablative resurfacing toward non-ablative dermal remodeling protocols. MedSpa chains in the United States are adopting these systems at accelerated replacement cycles of 24-36 months. The shift is compressing standalone radiofrequency equipment demand as combination platforms absorb skin tightening functionality.
The EU Medical Device Regulation (MDR) is imposing strengthened clinical evidence requirements on CE-marked aesthetic devices. Manufacturers must now maintain post-market surveillance obligations that extend 15 years beyond product discontinuation. Laser system suppliers with legacy ISO 13485 certifications face the steepest compliance reconfiguration costs.
Clinic buying committees are consolidating vendor relationships around manufacturers offering bundled financing and training certification programs. High-volume aesthetic centers in South Korea and Brazil are displacing traditional medical device distributors with direct manufacturer partnerships. This channel compression is most visible in São Paulo's Jardins district, where three procurement groups now control 60 percent of capital equipment orders.
Global Plastic Surgery Devices Market Segmentation
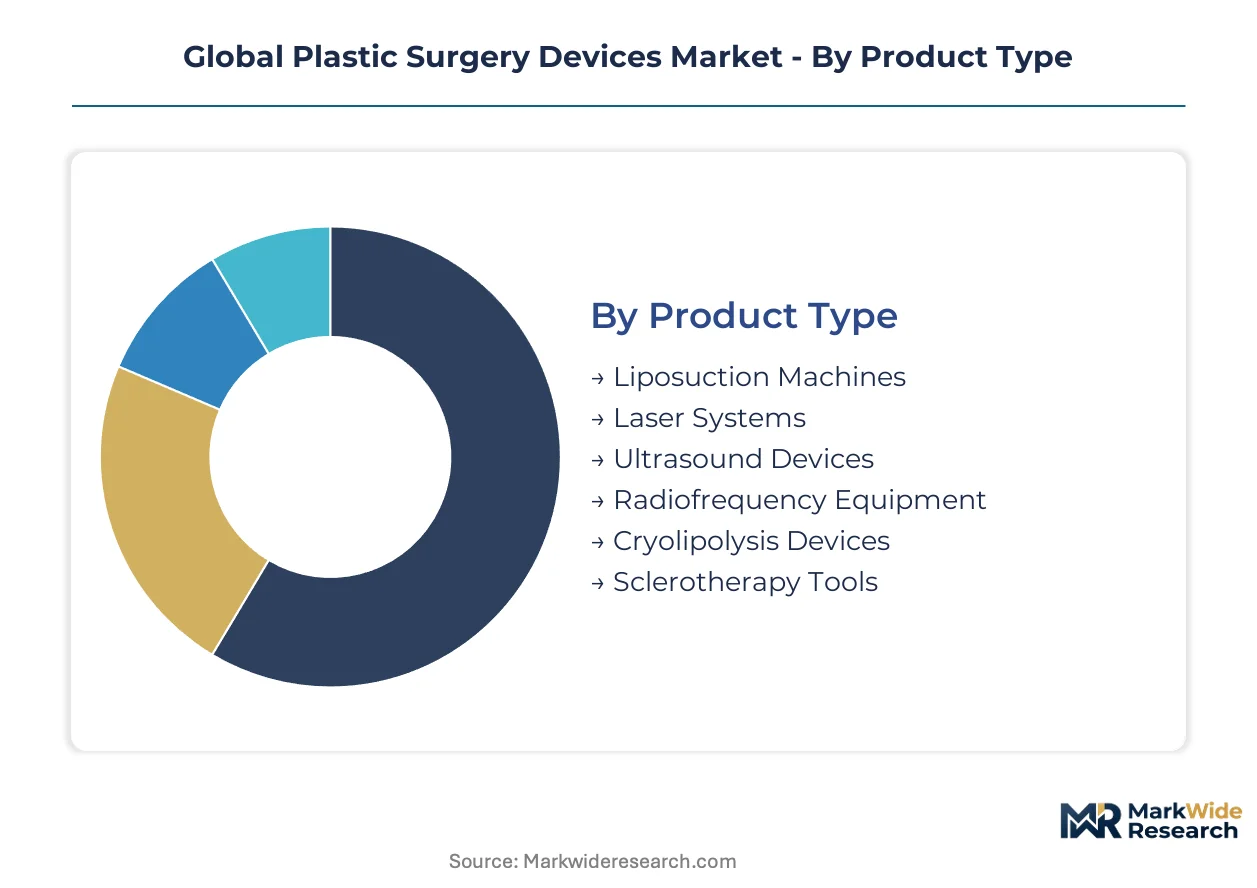
Device segmentation in plastic surgery reveals divergent capital cycles across product categories. Laser systems and cryolipolysis platforms command accelerated replacement schedules, while traditional electromechanical instruments sustain decade-long service lives.
Product Type:
Capital refresh cycles vary dramatically across this category, with energy-delivery platforms turning over every 24-36 months versus surgical equipment lasting 7-10 years.
- Laser Systems:Multi-wavelength platforms operating between 532 nm and 10,600 nm dominate high-margin consumable revenue through handpiece replacement cycles. Seoul's Gangnam district aesthetic centers drive procurement volume for fractional and ablative configurations.
- Cryolipolysis Devices:Non-invasive fat reduction platforms utilize controlled cooling at -11°C to -5°C to crystallize subcutaneous adipocytes. São Paulo and Rio de Janeiro wellness centers are displacing traditional liposuction with these systems, compressing surgical suite utilization rates.
- Radiofrequency Equipment:Thermal remodeling devices generating 1-40 MHz energy for dermal collagen contraction are repositioning toward combination therapy protocols.
- Liposuction Machines:Traditional suction-assisted lipectomy systems face demand erosion in premium urban markets.
- Ultrasound Devices:High-intensity focused ultrasound platforms for non-invasive fat reduction and skin lifting occupy niche positioning.
- Sclerotherapy Tools:Injectable foam and liquid systems for varicose vein treatment represent mature, low-innovation segments.
Laser Systems dominate installed base. Cryolipolysis Devices are where expansion concentrates.
Technology:
Technology selection directly determines regulatory pathway complexity and clinical evidence requirements for market authorization.
- CO2 Laser:Ablative systems at 10,600 nm wavelength deliver precise tissue vaporization with controlled thermal damage zones. US FDA 510(k) submissions for these platforms face extended review timelines as equivalence demonstrations tighten.
- Erbium Laser:2,940 nm wavelength systems offer more superficial ablation with faster re-epithelialization. European clinics under EU MDR jurisdiction prioritize these platforms for reduced downtime protocols.
- Intense Pulsed Light:Broad-spectrum flashlamp systems for photorejuvenation and hair removal face pricing compression from diode laser substitutes.
- Microdermabrasion:Mechanical exfoliation devices using aluminum oxide or diamond-tipped wands occupy entry-level aesthetic service tiers.
- Electrosurgery:Radiofrequency cutting and coagulation instruments maintain essential positioning in reconstructive procedures.
- LED Therapy:Low-level light devices for acne and anti-aging applications carry minimal regulatory burden but limited reimbursement.
CO2 Laser technology commands premium pricing tiers. Erbium Laser configurations are gaining share fastest in post-procedure recovery-sensitive segments.
Application:
Procedure volume distribution shapes manufacturer R&D prioritization and training program investments.
- Facial Rejuvenation:Combination protocols integrating laser resurfacing, injectables, and energy-based tightening dominate aesthetic center revenue mix. South Korean clinics lead protocol innovation and device procurement intensity.
- Body Contouring:Non-invasive fat reduction and skin tightening procedures are expanding beyond traditional surgical candidates into wellness-oriented demographics.
- Skin Tightening:Radiofrequency and ultrasound-based dermal remodeling face saturation as combination platforms absorb standalone functionality.
- Scar Revision:Fractional laser and surgical techniques for traumatic and surgical scar improvement serve reconstructive and elective markets.
- Breast Augmentation:Implant-based and fat transfer procedures rely on surgical instrumentation with minimal energy-device penetration.
- Tattoo Removal:Q-switched and picosecond laser systems serve dedicated removal clinics and expanding medspa service menus.
Facial Rejuvenation anchors manufacturer training investments. Body Contouring is where patient acquisition economics are shifting most dramatically.
End User:
Procurement authority consolidation is reshaping distribution economics across customer categories.
- Aesthetic Centers:High-throughput clinics in Seoul's Gangnam district and São Paulo's Jardins corridor are consolidating vendor relationships and displacing traditional distributors with direct manufacturer partnerships.
- Specialized Hospitals:Academic medical centers with craniomaxillofacial and reconstructive programs maintain capital equipment financing structures that bypass distributor markups.
- Plastic Surgeons:Individual practitioner offices face pressure to consolidate procurement through group purchasing organizations.
- Dermatology Clinics:Physician-directed aesthetic services compete for device access against dedicated aesthetic centers.
- Cosmetic Surgery Institutes:Multi-specialty facilities balance reconstructive and elective service lines with divergent equipment needs.
- Wellness Centers:Non-medical facilities are expanding into body contouring with lower-regulation device categories.
Aesthetic Centers control the steepest expansion trajectory. Specialized Hospitals anchor premium reconstructive device demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's medical device export infrastructure, channeling laser systems and radiofrequency platforms to aesthetic centers across East Asia. This maritime gateway underwrites Seoul's dominance in high-throughput facial rejuvenation device procurement.
United States
FDA's tightened 510(k) clearance pathways for energy-based surgical equipment are compressing product development timelines. The agency demands more substantial equivalence demonstrations for laser wavelengths between 532 nm and 10,600 nm. MedSpa chains in Los Angeles and Miami are adopting fractional laser systems at accelerated 24-36 month replacement cycles.
South Korea
Gangnam district aesthetic centers drive procurement volume for multi-wavelength laser platforms and radiofrequency systems. MFDS maintains strengthened clinical evidence requirements for novel energy-delivery devices. Seoul's densest concentration of high-throughput clinics globally is displacing traditional distributors with direct manufacturer partnerships.
Brazil
ANVISA regulates aesthetic devices under converging standards with international harmonization efforts. São Paulo's Jardins corridor and Rio de Janeiro wellness centers are displacing traditional liposuction with cryolipolysis platforms. Three procurement groups now control 60 percent of capital equipment orders in this private clinic corridor.
Germany
EU Medical Device Regulation imposes 15-year post-market surveillance obligations on CE-marked aesthetic devices. BfArM maintains parallel review standards that delay market entry without established predicate alignment. Baden-Württemberg and Bavaria host the densest concentration of precision surgical instrument manufacturers serving reconstructive applications.
Japan
PMDA's pharmaceutical and medical device agency maintains rigorous clinical trial requirements for novel laser platforms. Tokyo and Osaka aesthetic centers prioritize Erbium laser configurations for reduced downtime protocols. METI's industrial policy supports domestic manufacturers in radiofrequency equipment repositioning toward combination therapy protocols.
Global Plastic Surgery Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying handpieces, consumables, and precision optical assemblies. The vendor base organizes around three archetypes: diversified medical technology conglomerates with aesthetic device divisions, pure-play energy-based equipment manufacturers, and orthopedic-reconstructive instrument specialists extending into plastic surgery suites. Consolidation pressures favor players with captive financing capabilities and bundled training certification programs. Geographic expansion through direct-to-clinic distribution and technology licensing for modular handpiece systems represent the dominant competitive vectors.
Within the diversified medical technology tier, AbbVie Inc. (Allergan) and Johnson & Johnson Services, Inc. occupy positions anchored by injectables heritage and premium device portfolios across North American and European clinics. Stryker Corporation exemplifies the orthopedic-reconstructive extension archetype, with supply relationships concentrated in academic medical centers that bypass traditional distributor markups. These three entities represent contrasting strategic postures: pharmaceutical-device convergence, diversified healthcare conglomeration, and surgical infrastructure specialization.
| Leading Market Players |
|---|
| AbbVie Inc. (Allergan) |
| Zimmer Biomet Holdings Inc. |
| Integra LifeSciences Corporation |
| Stryker Corporation |
| B. Braun Melsungen AG |
| KLS Martin Group |
| KARL STORZ SE & Co. KG |
| Johnson & Johnson Services, Inc. |
| BMT Medizintechnik GmbH |
| Others |
Supply & Pricing Matrix
Undercapacity in Seoul's Gangnam district laser assembly operations is driving premium pricing for multi-wavelength platforms while compressing margins for standard-tier manufacturers. This utilization asymmetry shapes supplier prioritization toward high-volume aesthetic centers and forces smaller clinics into extended financing terms.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating premium multi-wavelength systems from standard radiofrequency platforms and economy-tier LED devices. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Cost compression in the standard tier is intensifying because clinic buying committees are unbundling service contracts from capital purchases. Group purchasing organizations serving individual practitioner offices exhibit highest price sensitivity, while academic medical centers with captive financing structures show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculations for precision optical assemblies and electrosurgical handpieces. Manufacturing concentrates in Germany, South Korea, and the United States for laser resonator components, radiofrequency generators, and cryolipolysis cooling modules. Production draws from specialized optical glass, medical-grade aluminum, and semiconductor laser diodes. Single-source vulnerability persists for 10,600 nm CO2 laser tubes sourced from Baden-Württemberg precision manufacturers. Distribution runs through direct manufacturer partnerships with high-volume aesthetic centers, bypassing traditional medical device distributors in Seoul and São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement groups in Brazil's private clinic corridor and South Korea's Gangnam district, fragmenting individual clinic negotiating leverage against manufacturers.
For Market Incumbents: Entrench supply relationships with academic medical centers through captive financing structures that bypass distributor markups. Deepen backward integration into handpiece consumable production to defend margin pools against unbundling pressure from clinic procurement teams. Prioritize ISO 13485 certification investment under EU MDR post-market surveillance obligations to maintain CE-marked product positioning. For New Entrants and Emerging Players: Build out microneedling attachment capabilities for radiofrequency equipment to capture combination therapy revenue streams in North American and European clinics. Target post-traumatic restoration applications in outpatient settings as the most penetrable segment with underinvested reconstructive correction volume. Pursue direct-to-clinic distribution partnerships with wellness centers in São Paulo's Jardins corridor as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because device architecture convergence around modular handpiece systems favors integrated manufacturers with bundled training certification programs. Acquire pure-play energy-based equipment manufacturers lacking captive financing capabilities. Watch clinic capital expenditure cycle compression as the inflection indicator for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways for laser wavelengths tighten equivalence demonstration requirements under FDA scrutiny. |
| CE Marking Pathway | EU MDR clinical evidence obligations extend 15 years beyond product discontinuation for CE-marked aesthetic devices. |
| Hospital System Partnership | Academic medical center supply relationships bypass traditional distributor markups and anchor reconstructive instrument demand. |
| Software Companion Development | Modular handpiece systems enable procedure-specific customization without full system replacement, compressing capital refresh cycles. |
| Reimbursement Strategy | Private payer coverage denials for non-invasive aesthetic procedures reshape clinic capital expenditure cycles and device financing structures. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aesthetic center procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records. Bottom-up installed base analysis and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed demand projections across the analysis window, modeling conservative, baseline, and expansion cases for laser system, cryolipolysis device, and radiofrequency equipment adoption. Segmentation dimensions included product type, technology wavelength, application protocol, and end-user procurement authority. CAGRs derived from procedure volume trajectories, replacement cycle compression, and geographic expansion patterns. Forecast inputs incorporated clinic density metrics in Seoul's Gangnam district and São Paulo's Jardins corridor.
Stress conditions across FDA review timeline extension, EU MDR compliance cost inflation, and private payer reimbursement denial rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and capital expenditure cycle stability. Macroeconomic contraction, regulatory pathway disruption, or combination therapy protocol breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Electrical Stimulation Devices (Esds) Market