
 Embolization Coils Market | 2026-2036
Embolization Coils Market Size, Share, and Industry Trends Forecast 2026-2036
Embolization Coils Market Foresight
Asset-light leasing models for catheterization lab equipment are rewriting capital deployment across interventional centers, lowering barriers for mid-tier hospitals to offer embolization services. Boston Scientific Corporation leverages its endovascular portfolio breadth to sustain multi-procedure bundling power. Stryker Corporation anchors its position through neurovascular specialization, while Penumbra Inc. differentiates via aspiration-compatible coil platforms that integrate with stroke workflows.
Embolization coils are metallic implantable devices, typically platinum or platinum-tungsten alloy, designed to induce thrombosis within target vessels through mechanical obstruction and enhanced clotting surface area. Their primary purpose is permanent occlusion of abnormal vasculature including aneurysms, arteriovenous malformations, and hemorrhagic sites. Detachable coils command premium positioning due to controlled deployment precision in neurovascular applications, whereas pushable coils occupy cost-sensitive peripheral embolization segments where procedural volume offsets lower unit margins. Filled coils represent the fastest-growing product category as bioactive coatings accelerate thrombosis rates and reduce retreatment incidence.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) establish divergent compliance burdens, with European notified body capacity constraints currently extending market access timelines. Japan's PMDA maintains distinct clinical evidence requirements for neurovascular implants that filter non-domestic submissions. Stakeholders must monitor evolving real-world evidence mandates from these regulators to anticipate post-market surveillance obligations and adapt trial design strategies accordingly.
Market Dynamics
Detachable coil technology is compressing retreatment rates while bioactive coatings accelerate thrombosis timelines, reshaping how interventional radiology departments evaluate total procedural cost against device premium.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined premarket notification framework accelerates neurovascular device clearances, enabling faster commercialization timelines for coil innovations targeting cerebral aneurysm applications.
- Peripheral Artery Disease Burden:Rising procedural volumes in vascular surgery departments drive pushable coil adoption for lower-extremity embolization where cost sensitivity dominates purchasing decisions.
- Platinum-Tungsten Alloy Advances:Enhanced radiopacity and mechanical stability in next-generation coil materials improve fluoroscopic visualization precision during complex neurovascular interventions.
Market Restraints
- Platinum Price Volatility:Raw material cost fluctuations in precious metal markets compress manufacturer margins and complicate long-term contract pricing with hospital procurement.
- EU MDR Notified Body Bottlenecks:Capacity constraints at European conformity assessment organizations extend technical documentation review timelines by 12-18 months for new coil submissions.
- Flow Diverter Substitution:Intrasaccular flow disruption devices capture select wide-neck aneurysm cases previously reserved for dense coil packing strategies.
Strategic Opportunities
- Brazil ANVISA Alignment:Harmonized clinical evidence requirements with FDA standards reduce redundant trial costs for manufacturers pursuing Latin American market entry.
- Stroke Workflow Integration:Aspiration-compatible coil platforms that interface with mechanical thrombectomy systems capture share in comprehensive cerebrovascular service lines.
- Japan PMDA Real-World Evidence:Post-market surveillance data requirements create pathways for differentiated claims based on domestic registry outcomes in the world's second-largest neurovascular market.
Industry Challenges
- Interventional Neuroradiologist Scarcity:Fellowship-trained specialists capable of complex aneurysm embolization remain concentrated at academic medical centers, limiting procedural expansion to community hospitals.
- Catheterization Lab Capex Requirements:Biplane angiography systems and dedicated neurovascular imaging infrastructure demand capital allocations exceeding mid-tier hospital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embolization Coils Market |
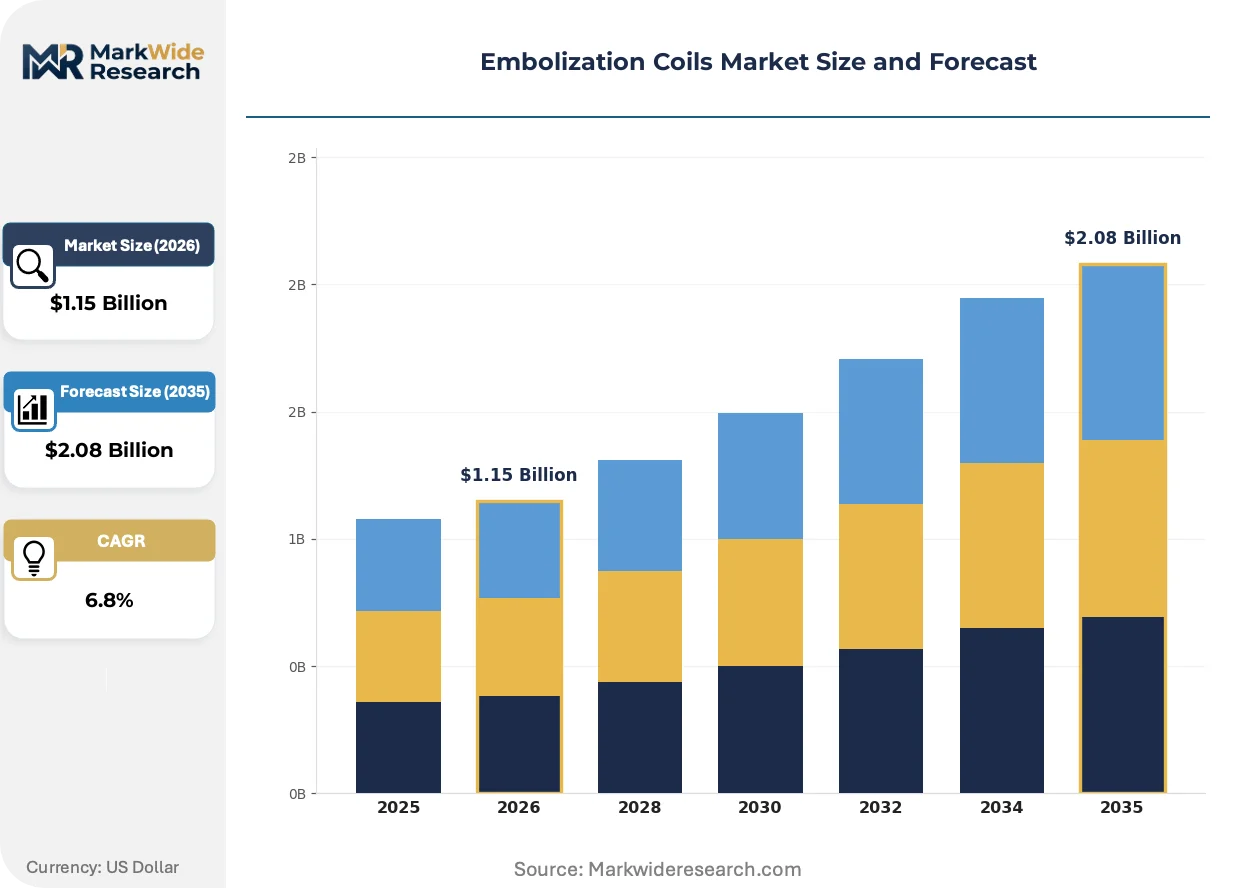
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detachable Coils, Pushable Coils, Filled Coils, Platinum Coils End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Procedure Type: Angiography, Peripheral Embolization, Uterine Artery Embolization, Gastrointestinal Bleeding Intervention Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Wholesale Suppliers |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, Stryker Corporation, Cook Medical, Terumo Corporation, Johnson & Johnson Services, Penumbra Inc., Abbott Laboratories, Merit Medical Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embolization Coils Market Shifts & Advancements
Bioactive surface engineering and deployment mechanism precision are converging to redefine performance benchmarks across both neurovascular and peripheral embolization segments.
Polymer-filled coil technology is hybridizing mechanical occlusion with pharmaceutical delivery, enabling localized thrombin release that accelerates aneurysm sac fibrosis. Academic medical centers in Germany and the United States are piloting these devices in unruptured aneurysm protocols. The structural consequence is a compression of follow-up imaging intervals and retreatment economics that previously sustained aftermarket revenue streams.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to reconstruct clinical evidence packages for legacy coil families previously cleared under the Medical Device Directive. Notified bodies in the Netherlands and Germany are prioritizing submissions with patient-level outcome registries. Neurovascular specialists report extended backorder periods for specific coil diameters as manufacturers stagger re-certification timelines.
Hospital value analysis committees are unbundling device procurement from procedure bundling, creating direct price transparency between coil manufacturers and interventional departments. This behavioral shift disrupts traditional distributor-mediated contracting in the United States. Integrated delivery networks in Texas and California are piloting consignment inventory models that transfer holding cost risk to suppliers while compressing unit pricing.
Embolization Coils Market Segmentation
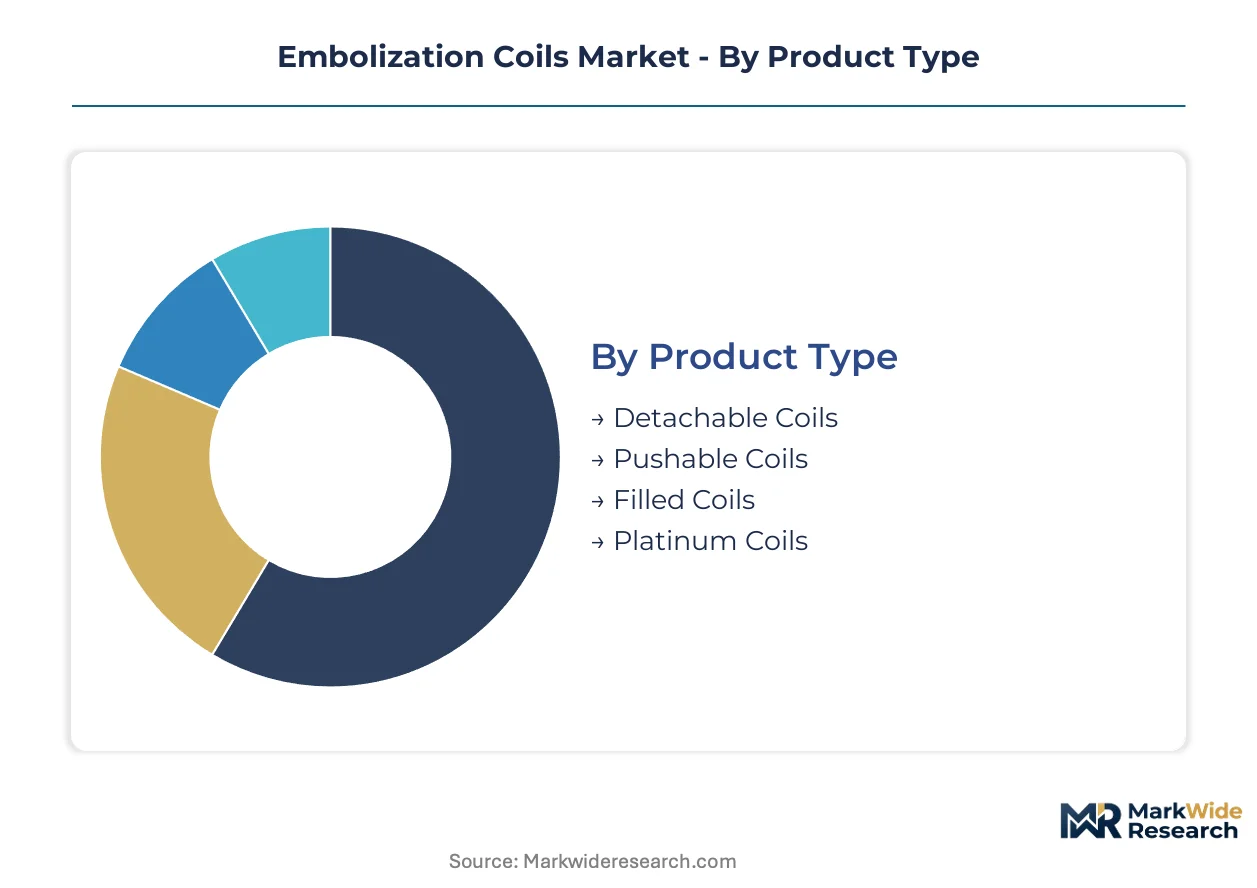
Coil embolization markets fragment across technical sophistication and care delivery settings, with detachable platforms commanding neurovascular premiums while pushable variants penetrate cost-sensitive peripheral segments. Understanding these divides reveals where procurement leverage concentrates and which innovation pathways alter reimbursement economics.
Product Type:
Mature mechanical platforms anchor established procedural workflows, yet bioactive surface engineering is accelerating thrombosis timelines and compressing retreatment incidence across next-generation formats.
- Detachable Coils:Platinum-tungsten alloy constructs with mechanical detachment mechanisms enable controlled deployment precision in cerebral aneurysm embolization. Academic medical centers in the United States and Germany concentrate demand here, driven by retreatment rate reduction mandates from hospital value analysis committees.
- Filled Coils:Polymer-filled lumens hybridize mechanical occlusion with localized pharmaceutical delivery, accelerating aneurysm sac fibrosis through thrombin release. Pilot protocols at German academic centers and select US stroke centers are compressing follow-up imaging intervals.
- Pushable Coils:Cost-optimized stainless steel or platinum constructs for peripheral vascular occlusion where procedural volume offsets lower unit economics.
- Platinum Coils:Pure platinum constructs prioritizing radiopacity in complex neurovascular interventions with extended fluoroscopic visualization requirements.
Detachable coils handle the majority of neurovascular throughput; filled coils are climbing the fastest on share as bioactive coatings reshape retreatment economics.
End User:
Capital deployment requirements and specialist availability stratify adoption across care delivery tiers, with catheterization lab infrastructure determining service line viability.
- Hospitals:Biplane angiography systems and fellowship-trained interventional neuroradiologists concentrate at academic medical centers and tier-one community hospitals. Texas and California integrated delivery networks are piloting consignment inventory models that transfer holding cost risk to suppliers.
- Ambulatory Surgical Centers:Asset-light leasing models for catheterization lab equipment are lowering barriers for mid-tier facilities to offer select embolization services.
- Specialty Clinics:Focused vascular intervention centers in metropolitan clusters handling high-volume peripheral embolization cases.
- Research Institutions:Pilot sites for polymer-filled coil protocols and next-generation bioactive surface engineering trials.
Hospitals absorb the dominant procedural volume; ambulatory surgical centers are expanding most quickly as equipment leasing models democratize access.
Procedure Type:
Imaging modality integration and anatomical complexity differentiate reimbursement tiers, with neurovascular applications commanding premium coding against peripheral standardization.
- Angiography:Diagnostic and interventional cerebral angiography with coil deployment for ruptured and unruptured aneurysms, requiring biplane fluoroscopy and specialized neurovascular catheter platforms.
- Peripheral Embolization:Lower-extremity and visceral vessel occlusion where pushable coil economics align with vascular surgery department cost sensitivity.
- Uterine Artery Embolization:Fibroid treatment protocols with distinct reimbursement pathways and gynecology-interventional radiology collaboration models.
- Gastrointestinal Bleeding Intervention:Emergency embolization for hemorrhagic control with compressed decision-to-treatment timelines.
Angiography generates the highest unit revenue per procedure; peripheral embolization scales through volume penetration in community hospital settings.
Distribution Channel:
Procurement pattern shifts are unbundling device purchasing from procedure bundling, creating direct price transparency between manufacturers and interventional departments.
- Direct Sales:Manufacturer field representatives contracting with integrated delivery networks and academic medical centers, bypassing traditional distributor markups.
- Medical Distributors:Regional inventory holding and logistics for mid-tier hospitals with limited procurement infrastructure.
- Online Sales:Emerging procurement portals for standardized pushable coil specifications and replenishment ordering.
- Wholesale Suppliers:Volume aggregation for multi-hospital systems with consolidated purchasing authority.
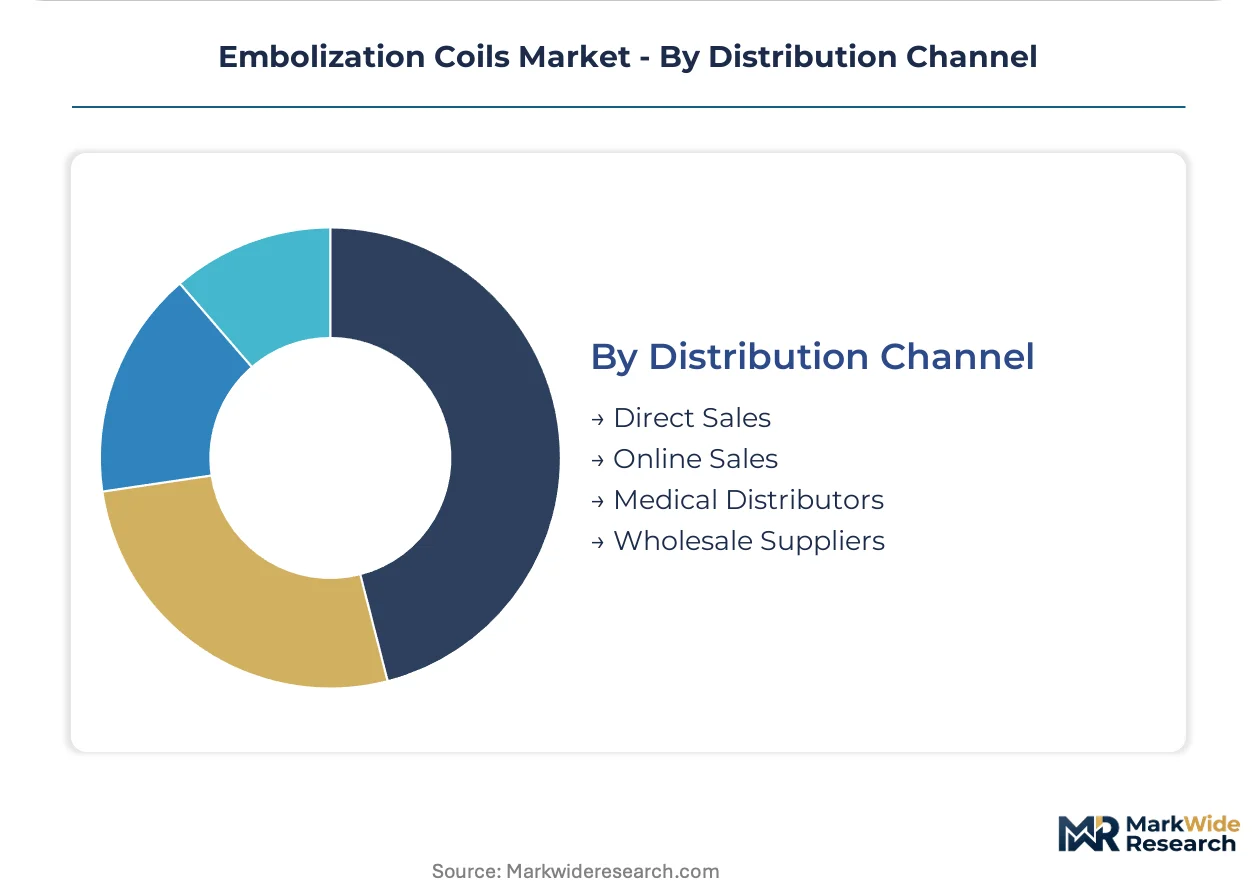
Direct sales capture the majority of neurovascular premium transactions; online channels are gaining share fastest in standardized peripheral segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in embolization coils tilt toward import dependence in emerging markets while established manufacturing hubs in the United States and Germany supply advanced neurovascular platforms to Asia-Pacific centers. Currency volatility and platinum price swings amplify procurement complexity for hospitals in price-sensitive regions.
United States
Integrated delivery networks in Texas and California consolidate purchasing power through consignment inventory models that transfer holding cost risk to suppliers. FDA 510(k) clearances for neurovascular devices accelerate commercialization timelines for domestic manufacturers. Academic medical centers in Boston and Houston concentrate fellowship-trained interventional neuroradiologists handling complex cerebral aneurysm cases.
Germany
Notified bodies in Germany and the Netherlands prioritize MDR recertification submissions with patient-level outcome registries, compressing review timelines for compliant manufacturers. EU MDR Article 10 technical documentation requirements force reconstruction of clinical evidence packages for legacy coil families. Academic centers in Munich and Heidelberg pilot polymer-filled coil protocols for unruptured aneurysm treatments.
Japan
PMDA maintains distinct clinical evidence requirements for neurovascular implants that filter non-domestic submissions and extend market access timelines. Real-world evidence mandates from post-market surveillance create pathways for differentiated claims based on domestic registry outcomes. Stroke centers in Tokyo and Osaka drive procedural volume for aspiration-compatible coil platforms integrated with mechanical thrombectomy workflows.
Brazil
ANVISA alignment with FDA clinical evidence standards reduces redundant trial costs for manufacturers pursuing Latin American market entry. Vascular surgery departments in São Paulo and Rio de Janeiro expand pushable coil adoption for lower-extremity embolization where cost sensitivity dominates purchasing decisions. Private hospital chains in southeastern states invest in biplane angiography infrastructure to capture neurovascular service line revenue.
China
NMPA regulatory pathways for Class III implantable devices require domestic clinical trials that extend registration timelines for foreign manufacturers. Provincial hospital procurement centralization in Jiangsu and Guangdong provinces compresses unit pricing through volume aggregation. Tertiary hospitals in Shanghai and Beijing concentrate complex neurovascular interventions while county-level facilities drive peripheral embolization volume.
Embolization Coils Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on materials and detachment mechanisms. The vendor base concentrates around diversified medical technology conglomerates with endovascular portfolio breadth, while mid-scale specialists anchor neurovascular niches. Three archetypes dominate: full-spectrum interventional platforms, neurovascular pure-plays, and peripheral embolization cost leaders. Consolidation through targeted acquisitions and strategic technology licensing agreements reshapes competitive boundaries.
Within the diversified platform tier, Medtronic Plc and Boston Scientific Corporation exemplify endovascular portfolio breadth that sustains multi-procedure bundling power. Stryker Corporation anchors the neurovascular specialization archetype through focused investment in stroke workflow integration. These three entities occupy positions that span detachable coil innovation, catheter platform compatibility, and hospital contracting scale.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Cook Medical |
| Terumo Corporation |
| Johnson & Johnson Services |
| Penumbra Inc. |
| Abbott Laboratories |
| Merit Medical Systems Inc. |
| Others |
Supply & Pricing Matrix
Minnesota and Massachusetts manufacturing clusters concentrate platinum-tungsten alloy processing capacity for neurovascular coil production, translating upstream materials dominance into pricing leverage for detachable coil tiers where retreatment economics justify premium positioning.
Pricing Analysis
Hospital value analysis committees anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on bioactive coating certification tiers and procedural volume commitments. Cost compression in pushable coil segments is intensifying because vascular surgery departments aggregate purchasing across multi-hospital systems. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with fellowship-trained specialists show lowest sensitivity due to retreatment rate mandates.
Supply Chain Analysis
Contract manufacturers in Ireland and Costa Rica hold specialized catheter assembly capacity for major device firms. Raw material feeds draw from South African platinum mines, German tungsten processing facilities, and Japanese precision wire drawing operations. Single-source vulnerability concentrates in platinum sponge refining where limited smelter capacity creates chokepoint exposure. Distribution runs through manufacturer field representatives for neurovascular tiers and regional medical distributors for standardized peripheral coils.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across Texas and California has shifted procurement leverage toward buyers, compressing unit pricing through consignment inventory models that transfer holding cost risk to suppliers.
For Market Incumbents: Build regulatory moats through simultaneous FDA 510(k) and EU MDR Article 10 submission strategies that exploit notified body capacity constraints to delay competitor entry. Deepen backward integration into platinum-tungsten alloy wire drawing to defend margins against precious metal volatility. Prioritize stroke workflow integration investments that lock in aspiration-compatible platform standards before flow diverter substitution accelerates. For New Entrants and Emerging Players: Build out peripheral embolization service lines at ambulatory surgical centers where asset-light catheterization lab leasing models lower capital barriers. Target Latin American markets through ANVISA-FDA harmonized clinical evidence pathways that reduce redundant trial costs. Pursue direct sales contracting with mid-tier hospital systems bypassing distributor markups in standardized pushable segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bioactive surface engineering specialists with polymer-filled coil platforms that compress retreatment economics. Five-to-ten year viability hinges on differentiation durability against flow diverter substitution and intrasaccular disruption devices. Watch for PMDA real-world evidence registry outcomes in Japan as signal for neurovascular claim durability and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates neurovascular device commercialization timelines for cerebral aneurysm applications. |
| EU MDR Recertification Investment | Patient-level outcome registry construction compresses notified body review timelines for legacy coil family renewals. |
| Hospital System Partnership | Consignment inventory models with Texas and California integrated delivery networks transfer holding cost risk to suppliers. |
| Software Companion Development | Deployment mechanism precision algorithms enhance fluoroscopic visualization during complex neurovascular interventions. |
| Reimbursement Strategy | Distinct coding pathways for angiography versus peripheral embolization protect premium neurovascular procedure economics. |
Research Methodology
Cross-validation between primary interviews with interventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data anchors the qualitative findings. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation calibrate market sizing across the analysis window.
Calibration against historical adoption curves for detachable versus pushable coil technologies and platinum price volatility indices refines projection accuracy. Segmentation dimensions span product type, end user facility tier, procedure complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for interventional neuroradiologist supply constraints and catheterization lab capital deployment rates.
Practitioners should monitor flow diverter substitution rates in wide-neck aneurysm cases and EU MDR notified body capacity expansion for early signals of coil demand trajectory revision. Quarterly review of platinum market futures and academic medical center fellowship program expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cryotherapy Market
Medical Devices
Medical Device Technologies Market
Medical Devices
General Surgical Devices Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Pathology Devices Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Electrocautery Devices Market
Medical Devices
EEG Electrodes Market
Medical Devices
Global Sperm Separation Devices Market