
 Global ECG Stress Test Market | 2026-2036
Global ECG Stress Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global ECG Stress Test Market Foresight
The EU Medical Device Regulation is pivoting the cost-of-entry calculus for ECG stress test systems, forcing manufacturers to rebuild clinical evidence portfolios. GE HealthCare leverages its installed base of diagnostic imaging to sustain service revenue attachments across European hospital networks. Koninklijke Philips N.V. anchors its cardiac monitoring franchise through integrated informatics platforms that span acute and ambulatory settings. NIHON KOHDEN dominates its home market with JIS-compliant electrocardiograph designs while competing selectively in Southeast Asian tenders.
An ECG stress test records cardiac electrical activity during controlled physical exertion, typically capturing twelve-lead configurations at sampling rates exceeding 500 Hz to detect transient ischemia or arrhythmia under metabolic load. Exercise ECG machines retain the largest installed footprint in hospital-based deployments where treadmill protocols remain standard for coronary artery disease screening. Ambulatory ECG systems represent the fastest-expanding segment as outpatient centers and mobile health units adopt patch-based monitors that transmit data through cellular networks to centralized reading services. Cardiology clinics command the deepest margin pools among end users due to recurring test volumes and preferential reimbursement positioning for diagnostic procedures.
The FDA maintains Class II device controls over exercise electrocardiograph systems, while the EU MDR demands notified body involvement for all active diagnostic monitors regardless of prior CE mark grandfathering. ISO 13485 quality system certification has become a de facto gate for supplier qualification by large hospital procurement consortia in North America and Western Europe. Stakeholders must monitor how FDA digital health pre-certification pilots and EUDAMED vigilance reporting convergence reshape competitive timelines for algorithm-enabled stress test interpretations.
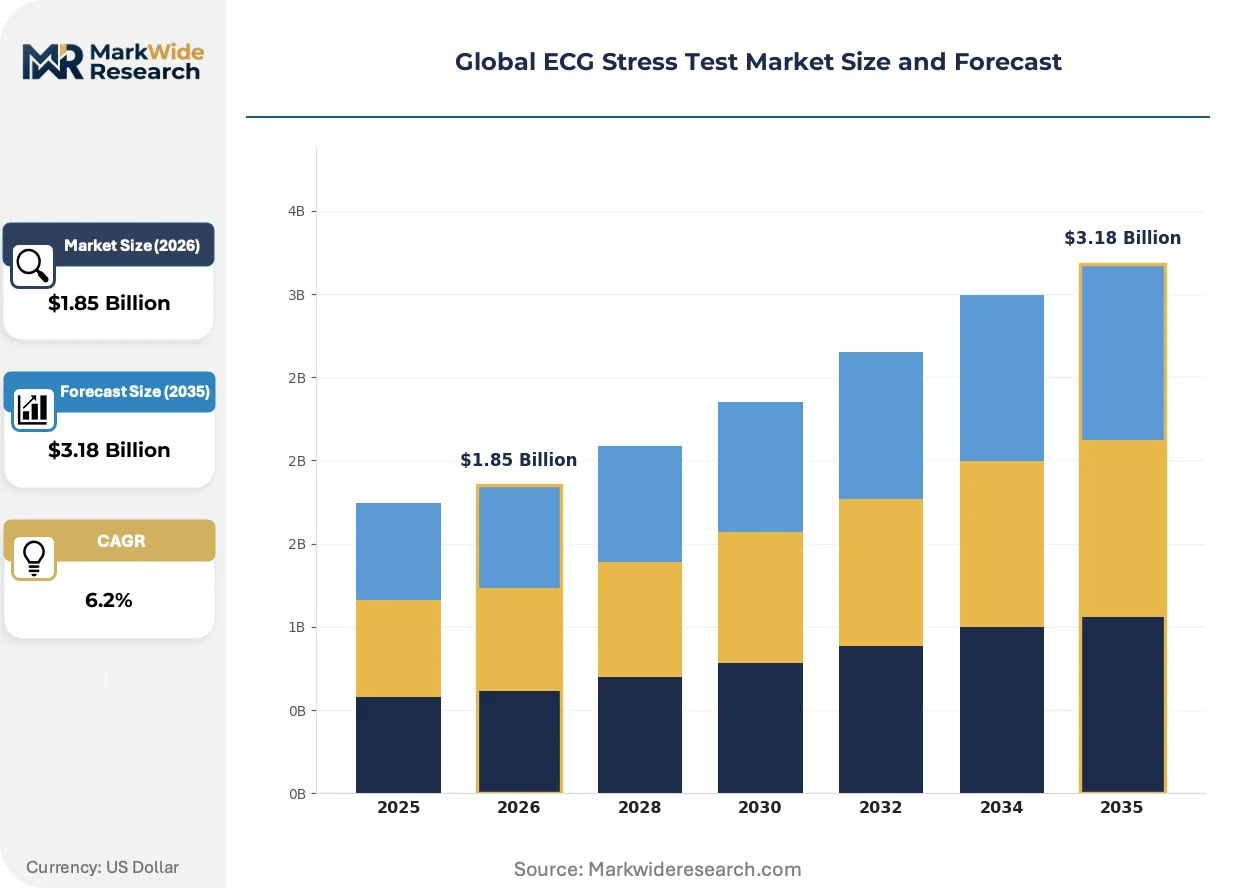
Market Dynamics
The EU MDR's clinical evidence requirements are compressing competitive timelines, forcing manufacturers to rebuild regulatory portfolios while cardiology clinics accelerate ambulatory system procurement ahead of grandfathering deadlines.
Growth Catalysts
- Ambulatory Monitoring Systems:Cardiology clinics across Germany and Japan are deploying patch-based ECG monitors that transmit data through cellular networks to centralized reading services, expanding test volumes beyond hospital walls.
- Hospital Infrastructure Renewal:Federal programs in the United States are replacing aging treadmill-based exercise ECG machines with integrated diagnostic platforms that support higher sampling rates and algorithm-enabled interpretation.
- EU MDR Compliance Windows:The transition period for legacy device recertification is creating concentrated procurement cycles as European hospital networks consolidate supplier relationships ahead of notified body capacity constraints.
Market Restraints
- Notified Body Bottlenecks:EU MDR implementation has reduced the number of designated conformity assessment bodies, extending certification timelines for active diagnostic monitors by twelve to eighteen months.
- Semiconductor Component Concentration:Analog front-end chips and high-resolution ADCs for ECG signal processing concentrate among Taiwanese and South Korean foundries, exposing supply chains to geopolitical friction.
- Reimbursement Compression:CMS physician fee schedule adjustments in the United States are narrowing margins for in-office stress testing, pressuring cardiology clinic capital expenditure cycles.
Strategic Opportunities
- Remote Patient Monitoring Integration:Cellular-enabled ambulatory ECG systems are converging with telehealth platforms, creating recurring revenue streams through subscription-based reading services.
- Southeast Asian Tender Markets:Public hospital procurement in Thailand and Vietnam is expanding diagnostic cardiology capacity, offering entry points for JIS-compliant and ISO 13485-certified manufacturers.
- FDA Digital Health Pre-Certification:The pilot program for algorithm-enabled stress test interpretation is creating accelerated pathways for software-as-a-medical-device business models.
Industry Challenges
- Clinical Evidence Generation:EU MDR technical documentation requirements for equivalence claims are forcing manufacturers to conduct new prospective studies, straining R&D budgets and regulatory affairs staffing.
- Legacy System Interoperability:Hospital information system integration for twelve-lead ECG data formats remains fragmented across vendor-specific protocols, complicating enterprise-wide deployments.
- Biomedical Engineering Talent Scarcity:The specialized skill set combining signal processing, IEC 60601-1 safety standards, and cardiovascular physiology is concentrating among a limited pool of experienced practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ECG Stress Test Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous ECG Monitors, Holter ECG Devices, Exercise ECG Machines, Ambulatory ECG Systems Application: Cardiac Arrhythmia Detection, Ischemic Heart Disease Assessment, Heart Rate Variability Analysis, Blood Pressure Monitoring End User: Cardiology Clinics, Diagnostic Laboratories, Research Institutes, Sports Medicine Facilities Deployment: Hospital-Based, Outpatient Centers, Home Care Settings, Mobile Health Units |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., SIEMENS Healthineers, NIHON KOHDEN, Baxter, Fukuda Denshi, Schiller AG, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Mortara Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ECG Stress Test Market Shifts & Advancements
Algorithm-enabled interpretation and wireless form factors are displacing conventional exercise ECG architectures, while regulatory data requirements are reshaping how manufacturers structure clinical validation programs.
Artificial intelligence-based arrhythmia detection is integrating with cloud-based ECG analysis platforms to reduce false-positive rates in stress test interpretation. Cardiology clinics in the United States and Germany are adopting these systems to address radiologist and cardiologist staffing constraints. The technology is integrating diagnostic workflow automation that compresses report turnaround times from hours to minutes, shifting competitive advantage toward software-enabled service models.
The EU MDR's post-market surveillance requirements are mandating systematic collection of real-world performance data for active diagnostic devices. Manufacturers must now maintain EUDAMED vigilance reporting infrastructure and periodic safety update reports across their entire European installed base. This regulatory shift most affects mid-tier device producers with limited post-market clinical follow-up capabilities, driving consolidation toward vertically integrated suppliers with dedicated pharmacovigilance departments.
Hospital procurement consortia are consolidating supplier relationships through multi-year managed service agreements that bundle hardware, software, and remote technical support. These arrangements displace traditional capital purchase models for exercise ECG systems, particularly among integrated delivery networks in the United States. The shift is most visible in cardiology clinic chains seeking to standardize device fleets and reduce internal biomedical engineering overhead across distributed sites.
Global ECG Stress Test Market Segmentation
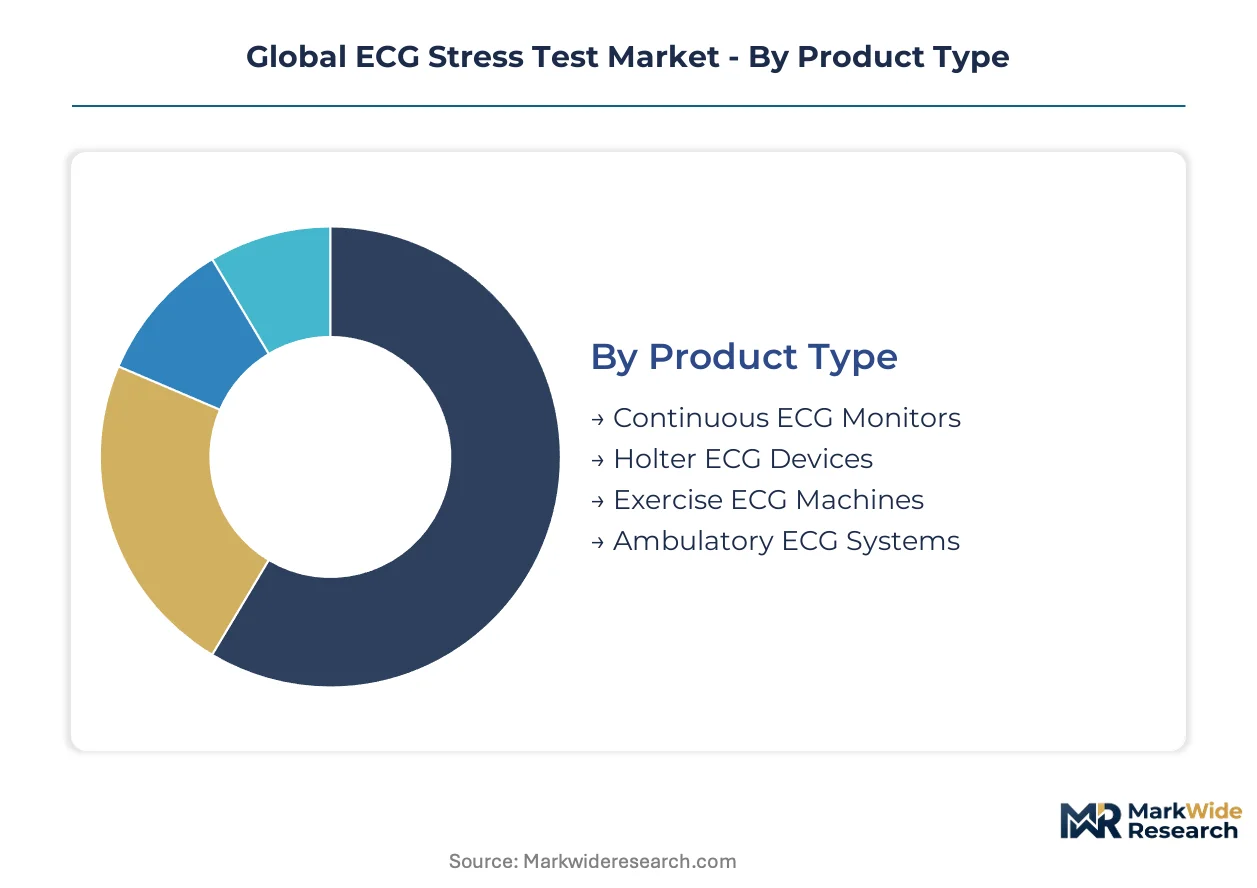
ECG stress test equipment segments diverge sharply in capital requirements and regulatory pathways. Product architecture determines whether manufacturers compete on hardware margins, software subscriptions, or integrated service contracts.
Product Type:
Exercise ECG machines demand the heaviest upfront manufacturing investment due to treadmill integration and IEC 60601-1 safety certification for moving mechanical components.
- Exercise ECG Machines:Treadmill-integrated systems with twelve-lead acquisition and automated Bruce protocol execution dominate hospital-based coronary artery disease screening. German and United States hospital networks are replacing legacy units with platforms supporting sampling rates above 500 Hz and algorithm-enabled ischemia detection.
- Ambulatory ECG Systems:Patch-based wireless monitors with cellular telemetry enable outpatient test volume expansion without fixed infrastructure. Cardiology clinics in Japan are deploying these for multi-day arrhythmia monitoring to address cardiologist staffing constraints.
- Holter ECG Devices:Continuous 24-48 hour recorders with solid-state memory remain the standard for intermittent symptom correlation.
- Continuous ECG Monitors:Bedside systems with real-time ST-segment analysis support intensive care and perioperative monitoring.
Exercise ECG machines absorb the bulk of installed capacity; ambulatory ECG systems are expanding most quickly.
Application:
Ischemic heart disease assessment commands premium pricing due to reimbursement alignment with coronary intervention pathways, while arrhythmia detection scales through volume-based ambulatory contracts.
- Ischemic Heart Disease Assessment:Exercise-induced ST-segment depression monitoring with automated METs calculation guides revascularization decisions. United States integrated delivery networks bundle these tests with catheterization lab referrals, creating margin pools that sustain equipment refresh cycles.
- Cardiac Arrhythmia Detection:Extended monitoring for atrial fibrillation and ventricular ectopy leverages patch-based form factors with cloud-based algorithm interpretation. Diagnostic laboratories in Germany are outsourcing reading services to address technician shortages.
- Heart Rate Variability Analysis:Autonomic function assessment for diabetic neuropathy and post-MI risk stratification.
- Blood Pressure Monitoring:Automated cuff integration with exercise protocols for hypertension evaluation.
Ischemic heart disease assessment generates the deepest revenue per test; cardiac arrhythmia detection is climbing the fastest.
End User:
Cardiology clinics concentrate procurement authority for high-margin diagnostic procedures, while research institutes drive adoption of investigational algorithm platforms.
- Cardiology Clinics:Outpatient facilities with direct patient referral networks and preferential CMS reimbursement positioning for stress echocardiography and nuclear imaging coordination. These sites prioritize systems with bidirectional EMR integration and automated report generation.
- Diagnostic Laboratories:Centralized reading services processing ambulatory ECG data from distributed collection points. United States laboratory chains are consolidating supplier relationships through multi-year managed service agreements covering hardware, connectivity, and interpretation.
- Sports Medicine Facilities:Pre-participation screening and athletic performance monitoring.
- Research Institutes:Clinical trial endpoints and algorithm validation cohorts.
Cardiology clinics control the largest share of capital deployment; diagnostic laboratories are gaining share fastest.
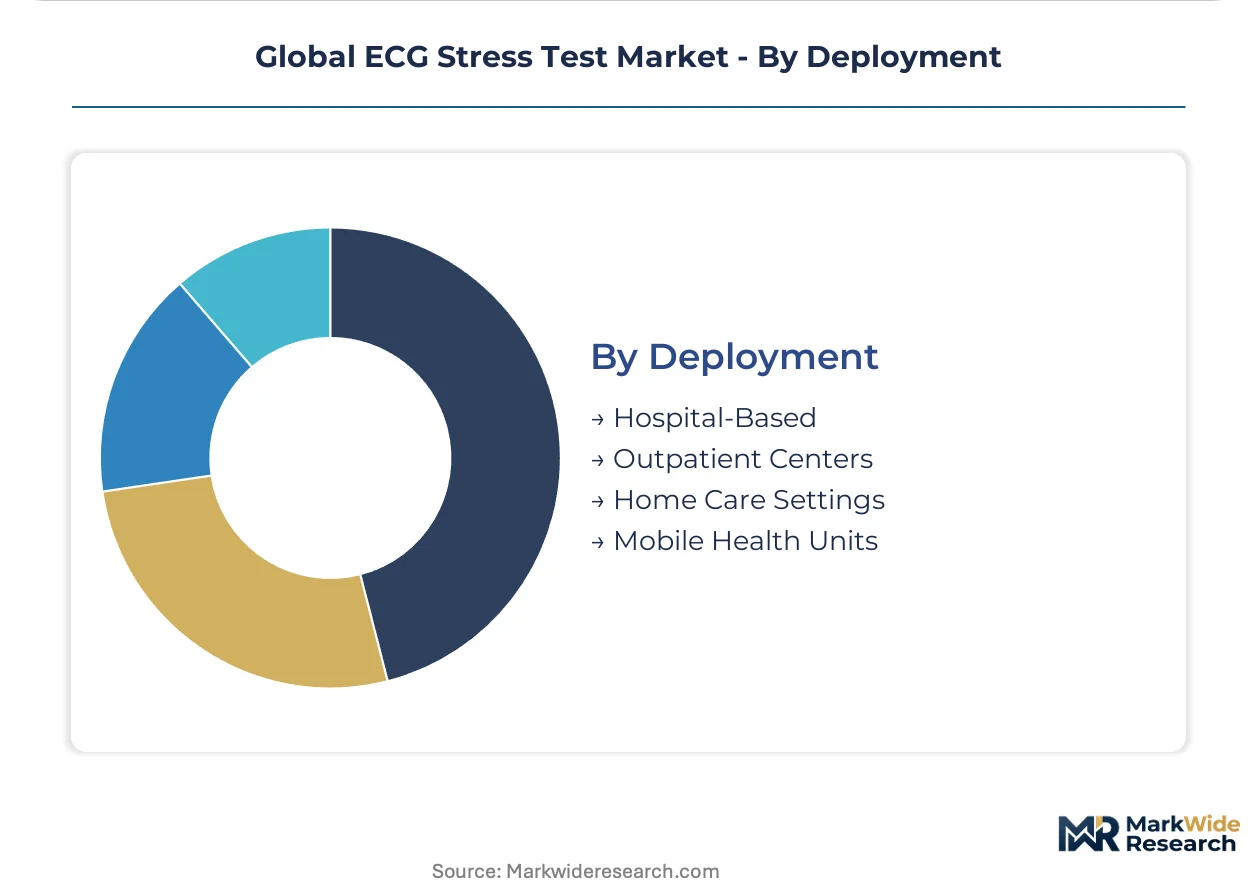
Deployment:
Hospital-based installations retain the highest equipment specification requirements, while home care settings are forcing miniaturization and patient-operated design priorities.
- Hospital-Based:Fixed treadmill systems with central monitoring stations and crash cart proximity for emergency response. These deployments require hardwired network integration and biomedical engineering maintenance contracts.
- Outpatient Centers:Freestanding cardiology clinics with dedicated stress testing suites and same-day reporting workflows. Japan's hospital infrastructure renewal programs are expanding these capacities outside tertiary centers.
- Mobile Health Units:Vehicle-mounted exercise ECG systems for rural screening programs.
- Home Care Settings:Patient-applied patch monitors with smartphone-guided application.
Hospital-based deployments anchor the installed base; outpatient centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech special economic zones in Costa Rica and Malaysia are concentrating diagnostic device manufacturing for North American and Asian hospital networks respectively.
United States
Federal hospital infrastructure renewal programs and integrated delivery network consolidation are replacing aging treadmill systems. FDA Class II device controls and digital health pre-certification pilots are accelerating algorithm-enabled stress test platforms. The Minneapolis medical device cluster hosts concentrated R&D operations for ambulatory ECG telemetry systems.
Germany
Cardiology clinic chains are deploying patch-based monitors to address technician shortages and expand outpatient test volumes. EU MDR notified body involvement requirements and EUDAMED vigilance reporting are compressing supplier certification timelines. The Baden-Württemberg industrial corridor anchors precision manufacturing for twelve-lead acquisition systems.
Japan
Hospital infrastructure renewal programs are expanding outpatient stress testing capacity beyond tertiary centers. PMDA and JIS-compliant electrocardiograph standards dominate procurement specifications for domestic tenders. The Tokyo-Osaka corridor concentrates headquarters operations for major device manufacturers serving Southeast Asian export markets.
China
Domestic medical device procurement policies are prioritizing local suppliers for hospital diagnostic equipment. NMPA regulatory pathways and GB standards compliance are gating market access for imported exercise ECG systems. The Yangtze River Delta manufacturing belt hosts contract production facilities for analog front-end components and wireless telemetry modules.
India
Private hospital networks in metropolitan centers are importing refurbished European exercise ECG machines to manage capital expenditure constraints. CDSCO medical device rules and BIS certification requirements are tightening quality system expectations for active diagnostic monitors. The Maharashtra-Gujarat pharmaceutical and medical device corridor is attracting contract manufacturing investments from multinational diagnostic suppliers.
Global ECG Stress Test Market Competitive Landscape
United States and German producers anchor the premium-tier equipment segment; Japanese and Chinese specialists hold positions in cost-optimized and regionally compliant product categories. The vendor structure concentrates among diversified health technology conglomerates with installed base service revenue attachments and dedicated cardiac monitoring pure-plays with informatics integration capabilities. Three archetypes dominate: imaging-system incumbents leveraging diagnostic platform synergies, cardiac-focused device specialists with algorithm-enabled interpretation software, and emerging Asian manufacturers competing on JIS and GB standards compliance. Competitive dynamics center on multi-year managed service agreements displacing capital purchase models and EU MDR-driven consolidation toward vertically integrated suppliers with dedicated pharmacovigilance infrastructure.
Within the diversified health technology tier, GE HealthCare and Koninklijke Philips N.V. occupy positions sustained by service revenue attachments across European and North American hospital networks. NIHON KOHDEN exemplifies the regionally dominant specialist archetype, anchoring its home market through JIS-compliant designs while competing selectively in Southeast Asian public tenders. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the emerging Asian manufacturer category, positioned around domestic procurement preferences and cost-optimized production configurations.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| SIEMENS Healthineers |
| NIHON KOHDEN |
| Baxter |
| Fukuda Denshi |
| Schiller AG |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Mortara Instrument |
| Others |
Supply & Pricing Matrix
Analog front-end semiconductor costs cascade through three pricing tiers for ECG stress test systems, with Taiwanese foundry output feeding premium-tier exercise machines while South Korean ADC suppliers anchor mid-market ambulatory configurations.
Pricing Analysis
Short lead-time premiums separate emergency procurement from scheduled fleet replacements across hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and bundled service contract depth. Price differentiation centers on algorithm-enabled interpretation modules and EMR integration sophistication. Cost compression in economy-tier Holter devices is intensifying because of CMS reimbursement schedule adjustments. Diagnostic laboratories exhibit highest price sensitivity due to volume-based procurement consortia, while research institutes show lowest sensitivity tied to grant-funded investigational platforms.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese analog foundries supplying high-resolution ADCs for twelve-lead acquisition systems. Component sourcing draws from South Korea for wireless telemetry modules and Germany for precision mechanical treadmill assemblies. Raw material dependencies span medical-grade copper for electrode leads, lithium polymer cells for patch-based monitors, and specialized shielding alloys for EMC compliance. Tariff exposure runs through semiconductor import channels into North American assembly facilities. Distribution runs through hospital procurement consortia and GPO contracts dominating United States and German acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into cellular telemetry module production represents the decisive upstream lever as manufacturers seek captive supply chains for ambulatory ECG platforms.
For Market Incumbents: Anchor service revenue attachments through multi-year managed service agreements covering hardware, connectivity, and remote interpretation. Consolidate supplier relationships ahead of EU MDR notified body capacity constraints to defend against mid-tier competitors lacking pharmacovigilance infrastructure. Prioritize backward integration into algorithm development for cloud-based arrhythmia detection. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass established GPO gatekeepers and accelerate patch-based monitor adoption. Southeast Asian public hospital tenders in Thailand and Vietnam offer the most penetrable entry points for JIS-compliant manufacturers. Target diagnostic laboratory outsourcing contracts with subscription-based reading service models. For Investors and Strategic Acquirers: FDA digital health pre-certification pilot program expansion is the leading indicator that software-as-a-medical-device valuations will decouple from traditional hardware multiples. Five-to-ten year viability favors vertically integrated suppliers with dedicated regulatory affairs and post-market surveillance capabilities. Watch for EU MDR recertification deadline clustering as consolidation trigger.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments compress competitive timelines for active diagnostic monitors. |
| Hospital System Partnership | Integrated delivery network consolidation creates multi-year managed service contract opportunities. |
| Software Companion Development | Algorithm-enabled stress test interpretation shifts margin capture toward recurring SaaS revenue. |
| Reimbursement Strategy | CMS physician fee schedule navigation determines cardiology clinic capital expenditure cycles. |
| Supply Chain Localization | Domestic component sourcing mitigates geopolitical exposure in analog front-end procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists combined with FDA 510(k) databases, EUDAMED vigilance reports, CMS Medicare claims data, and ISO certification registries. Bottom-up equipment shipment tracking and top-down healthcare expenditure triangulation validated market sizing across the analysis window.
Data-stream reconciliation between ambulatory monitor deployment tallies and exercise ECG replacement cycles established the forecast foundation. Segmentation dimensions spanned product architecture, application purpose, end-user category, and deployment setting throughout the forecast period. CAGRs derived from installed base growth rates, replacement cycle compression, and ambulatory system penetration curves. Industry-specific inputs included EU MDR transition timelines and FDA digital health pilot program scope.
The model holds under stable regulatory implementation schedules; deviation in notified body capacity constraints or semiconductor supply disruptions would shift competitive positioning. Forecasts reflect documented assumptions regarding reimbursement stability and hospital infrastructure renewal program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market