
 Electroretinogram Market | 2026-2036
Electroretinogram Market Size, Share, and Industry Trends Forecast 2026-2036
Electroretinogram Market Intelligence
EU MDR is consolidating the cost-of-entry calculus for electroretinogram manufacturers seeking CE-marked distribution. Diopsys leverages its vertical integration in visual electrophysiology to sustain premium positioning across European ophthalmology networks. LKC Technologies anchors its competitive stance through specialized pattern ERG protocols that dominate academic research procurement. Konan Medical USA competes on portable form-factor engineering for point-of-care deployment.
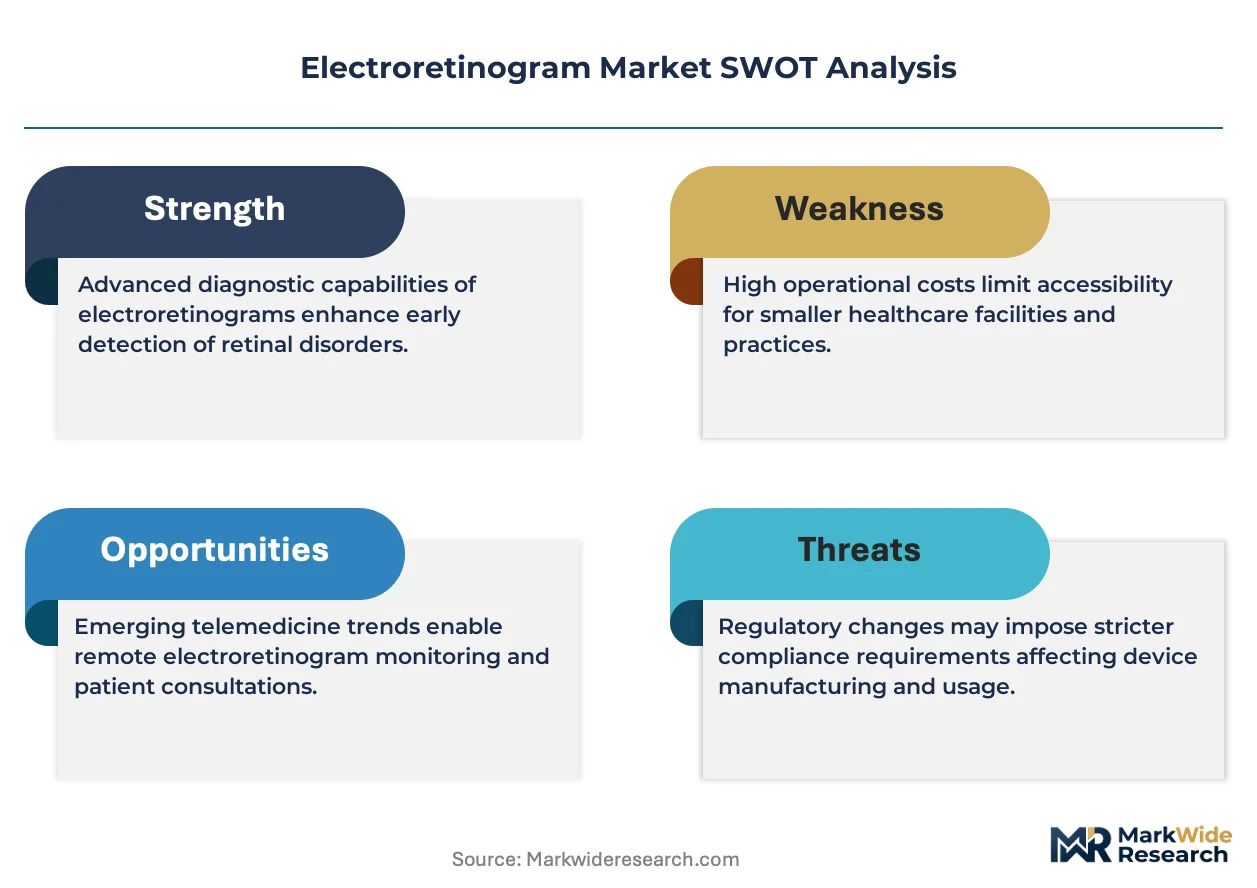
An electroretinogram measures retinal electrical responses to controlled light stimuli through corneal electrodes, capturing photoreceptor and inner retinal cell function with microvolt precision to diagnose inherited retinal dystrophies, glaucoma progression, and diabetic retinopathy. Flash ERG systems remain the mature revenue base while multi-electrode array technology represents the fastest-growing segment as pharmaceutical sponsors adopt high-throughput retinal screening for gene therapy trials. Tabletop systems still occupy the largest installed base in hospitals, though portable devices are capturing margin pools in ambulatory settings where space constraints and throughput flexibility command pricing premiums.
FDA 510(k) pathways and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for electroretinogram devices entering commercial distribution. Japan's PMDA enforces JIS-compliant electrical safety standards that filter non-domestic suppliers from hospital tenders. Stakeholders must monitor how ophthalmology clinic consolidation and payer coverage determinations for diagnostic electrophysiology reshape procurement concentration and service contract structures.
Market Dynamics
Portable electroretinogram systems are compressing the installed base economics of hospital-based tabletop devices, while EU MDR conformity assessments extend product launch timelines and reshape vendor competitive calculus.
Growth Catalysts
- EU MDR implementation:Tightened electrophysiological equipment standards in Europe are filtering marginal competitors and consolidating procurement toward certified manufacturers with established quality management systems.
- Gene therapy pipelines:Pharmaceutical sponsors are scaling multi-electrode array screening infrastructure to support inherited retinal dystrophy trials, creating dedicated demand for high-throughput ERG protocols.
- Germany:Specialized eye care centers and university hospitals in Bavaria and Baden-Württemberg are replacing aging flash ERG systems, driving replacement cycles in premium diagnostic segments.
Market Restraints
- Precious metal electrode costs:Silver-silver chloride electrode price volatility constrains margin expansion for disposable component suppliers serving high-volume screening programs.
- Technical standardization gaps:Inconsistent ISCEV protocol implementation across clinical sites limits multicenter trial data comparability and complicates pharmaceutical sponsor site qualification.
- Optical coherence tomography substitution:OCT angiography advances in glaucoma progression monitoring are displacing some functional electrophysiology indications in primary diagnosis workflows.
Strategic Opportunities
- Telemedicine integration:Cloud-native ERG data platforms enable remote specialist interpretation, opening ambulatory settings previously excluded by on-site electrophysiologist requirements.
- Diabetic retinopathy screening mandates:National diabetes management programs in several European countries are expanding reimbursed diagnostic protocols to include functional retinal assessment.
- Artificial intelligence convergence:Machine learning waveform classification algorithms are reducing interpretation variability and enabling technician-operated systems in optometry chains.
Industry Challenges
- Electrophysiologist training pipelines:Fellowship program capacity constraints limit the specialist workforce available to operate and interpret complex pattern ERG protocols in community settings.
- Legacy device interoperability:Proprietary data formats from installed tabletop systems obstruct seamless integration with emerging cloud-based practice management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroretinogram Market |
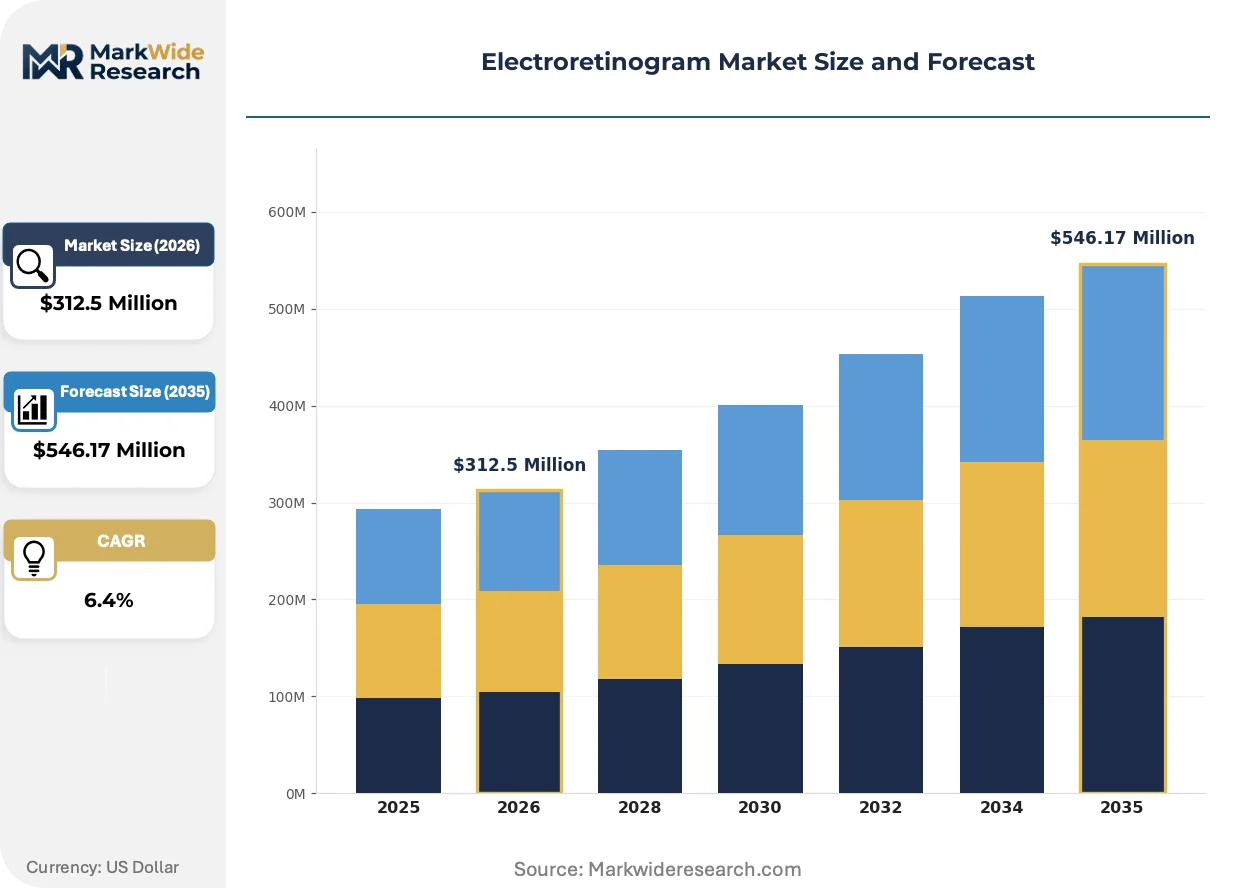
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Tabletop Systems, Software Solutions, Accessories End User: Ophthalmology Clinics, Research Laboratories, Hospitals, Academic Institutions Technology: Flash ERG, Pattern ERG, Full-Field ERG, Multi-Electrode Array Application: Diagnosis, Research, Screening, Clinical Trials |
| Companies Covered | Diopsys, CSO, LKC Technologies, Konan Medical USA, Roland Consult, Diagnosys, Metrovision, M&S Technologies, Electro-Diagnostic Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroretinogram Market Strategic Shifts & Innovations
Electroretinogram technology trajectories center on miniaturization, algorithmic interpretation, and regulatory harmonization pressures that are compressing traditional equipment lifecycle assumptions.
Multi-electrode array technology is decentralizing retinal electrophysiology from centralized hospital laboratories toward distributed pharmaceutical screening sites and contract research organizations. Gene therapy sponsors are adopting these high-density recording platforms to accelerate preclinical safety pharmacology workflows. The shift is compressing equipment procurement cycles and favoring vendors with scalable software architectures over hardware-centric legacy suppliers.
EU MDR technical documentation requirements for electrophysiological devices are extending conformity assessment timelines and forcing manufacturers to rebuild clinical evidence packages. Notified body capacity constraints are creating queuing bottlenecks that delay CE-marked product launches by 12-18 months. German and French ophthalmology networks are responding by consolidating procurement toward established suppliers with proven MDR transition track records.
Service unbundling is fragmenting traditional capital equipment sales models as buyers preference subscription-based waveform interpretation and remote technical support. Independent optometry chains and mobile screening operators are displacing hospital-centered service structures. This pattern is most visible in Spain and Italy, where regional health system budget constraints favor operational expenditure models over capital-intensive device ownership.
Electroretinogram Market Segmentation
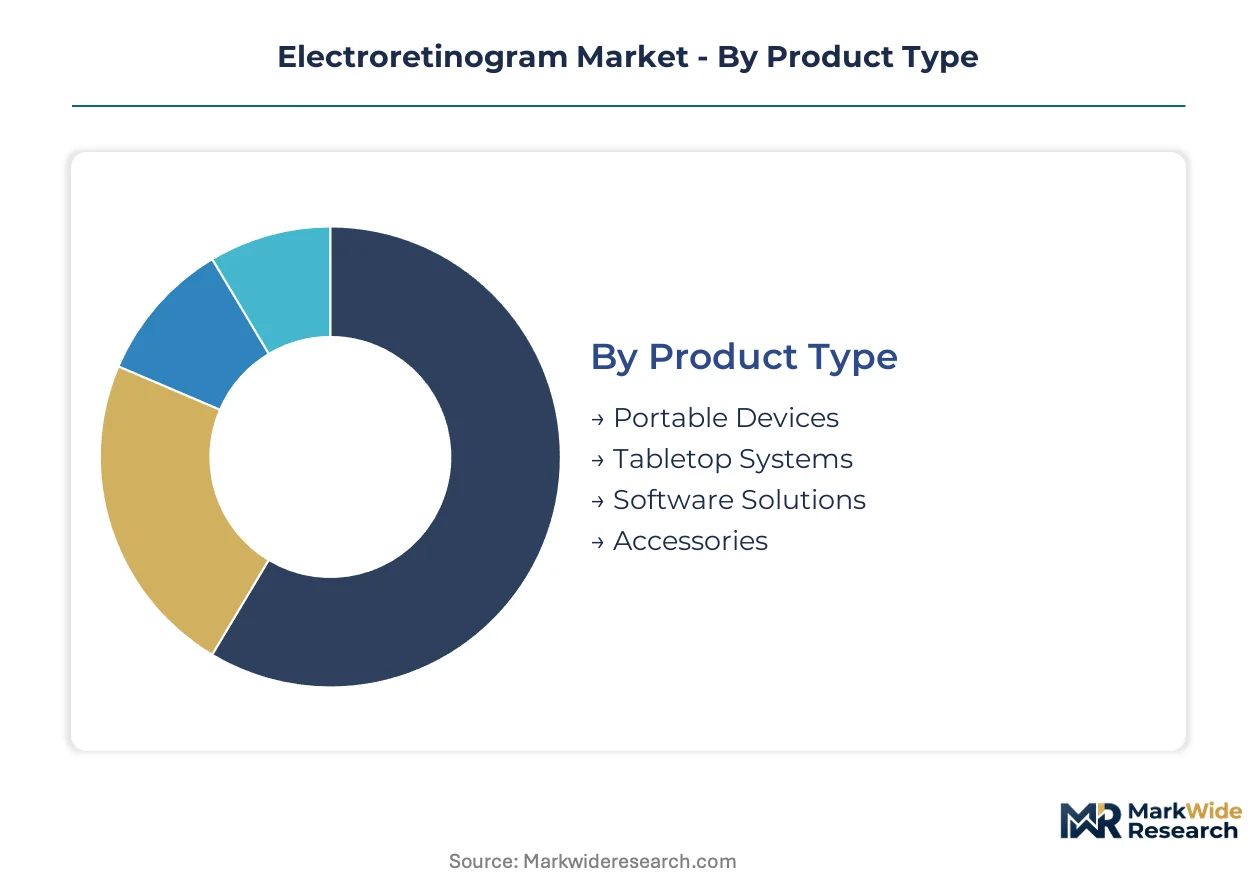
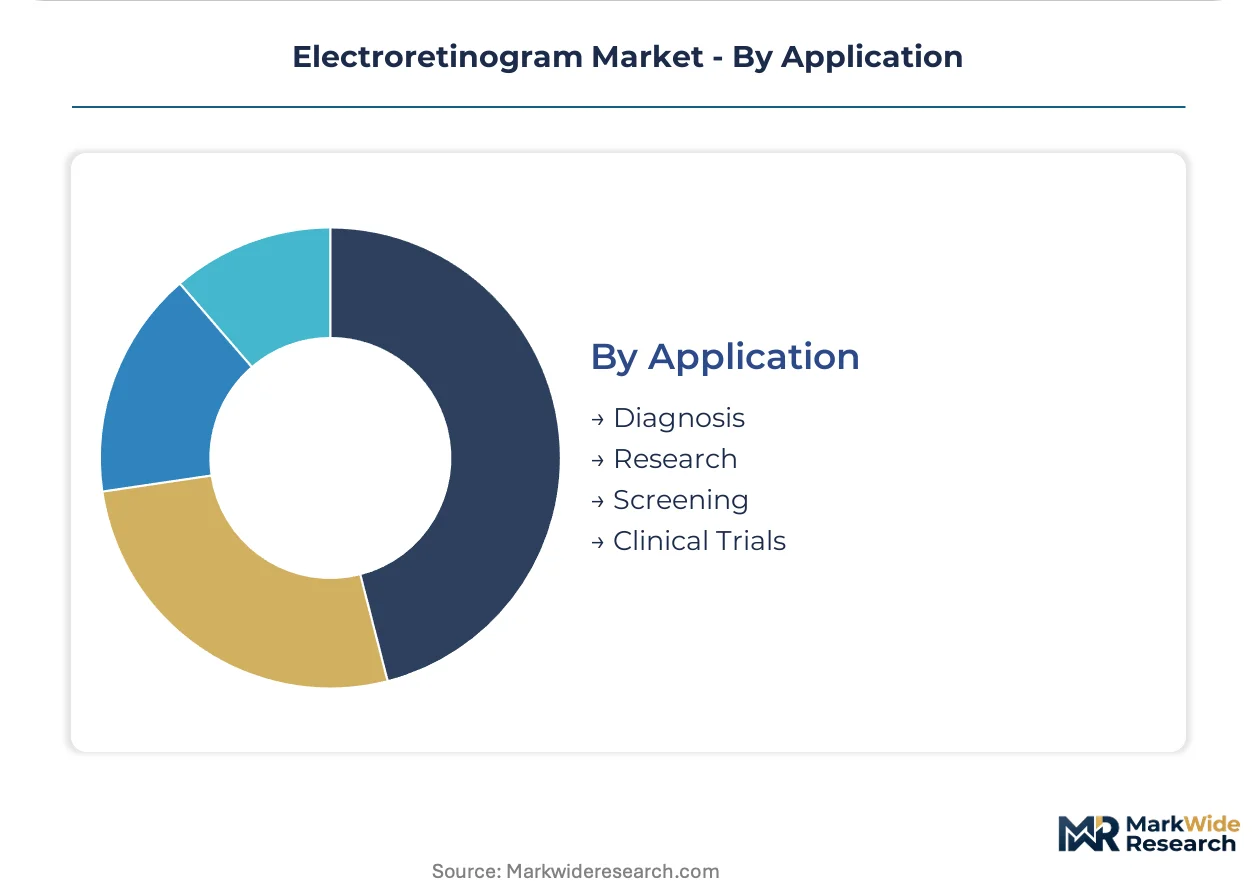
Electroretinogram market segmentation reflects divergent equipment requirements across clinical workflows, research protocols, and pharmaceutical screening operations. Each axis—product form factor, end-user setting, recording technology, and application purpose—carries distinct procurement criteria, regulatory pathways, and service contract structures that reshape vendor competitive positioning.
Product Type:
Physical configuration determines installation logistics, capital deployment models, and service revenue potential across ambulatory and institutional settings.
- Portable Devices:Battery-powered units with wireless data transmission enable point-of-care deployment in mobile diabetic retinopathy screening programs and satellite ophthalmology clinics. German ambulatory networks and Spanish regional health authorities are prioritizing these systems to circumvent electrophysiologist staffing constraints in rural catchment areas.
- Tabletop Systems:Stationary platforms with integrated stimulus generators and Faraday cage shielding dominate hospital electrophysiology laboratory installations. Bavarian university hospitals and Baden-Württemberg specialized eye centers are driving replacement cycles as aging flash ERG infrastructure reaches end-of-service life.
- Software Solutions:Cloud-native waveform analysis platforms with ISCEV-compliant automated reporting.
- Accessories:Disposable silver-silver chloride electrodes, calibration phantoms, and patient interface consumables.
Tabletop systems lead on scale; portable devices lead on momentum.
End User:
Procurement concentration varies sharply by institutional budget authority, reimbursement coding, and specialist workforce availability.
- Ophthalmology Clinics:Independent practice groups and chain-affiliated centers purchase compact systems for glaucoma progression monitoring and inherited retinal dystrophy workups. Italian and Spanish private clinic networks are expanding functional electrophysiology service lines as OCT reimbursement compresses.
- Hospitals:Academic medical centers and community hospital systems operate centralized electrophysiology laboratories serving multiple specialties. These installations require multi-modal capabilities combining flash ERG, pattern ERG, and VEP protocols under single platform management.
- Research Laboratories:Contract research organizations and pharmaceutical sponsor sites conducting gene therapy safety pharmacology.
- Academic Institutions:University ophthalmology departments with fellowship training programs and investigator-initiated trial portfolios.
Hospitals anchor procurement volume; ophthalmology clinics are expanding most quickly.
Technology:
Recording methodology selection constrains diagnostic indication range, operator training requirements, and equipment cost structures.
- Multi-Electrode Array:High-density recording platforms with 60+ electrodes capture spatially resolved retinal responses for preclinical toxicology screening and inherited retinal dystrophy phenotyping. Pharmaceutical sponsors are scaling these systems across distributed screening sites to accelerate gene therapy candidate selection timelines.
- Flash ERG:Full-field light stimulus protocols measuring combined rod and cone system function remain the clinical standard for pediatric retinal dystrophy diagnosis and intraoperative monitoring. Mature installed base across European hospital networks generates substantial recurring service contract revenue.
- Pattern ERG:Contrast-reversing grating stimuli isolating ganglion cell function for glaucoma progression assessment.
- Full-Field ERG:Standardized ISCEV protocols with dark-adapted and light-adapted phases for comprehensive photoreceptor evaluation.
Flash ERG commands installed base dominance; multi-electrode array climbs the fastest.
Application:
Functional purpose reshapes equipment specification, regulatory classification, and commercial terms.
- Diagnosis:Clinical ERG for inherited retinal dystrophy confirmation, glaucoma functional assessment, and diabetic retinopathy staging drives the largest equipment procurement volumes. Reimbursement coding availability in Germany, France, and Italy determines site-level adoption economics.
- Clinical Trials:Protocol-driven electrophysiology endpoints for pharmaceutical sponsors require validated systems with audit trail documentation and central laboratory data transfer capabilities. Gene therapy pipelines are expanding dedicated screening infrastructure demand.
- Research:Investigator-initiated studies and mechanistic retinal physiology investigations.
- Screening:Population-scale diabetic retinopathy detection programs and occupational health monitoring.
Diagnosis generates absolute revenue; clinical trials show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electrophysiologists and ophthalmology fellowship programs concentrate in university hospital clusters across Germany, the United States, Japan, and select Western European markets, anchoring regional demand for advanced diagnostic infrastructure.
Germany
Bavarian and Baden-Württemberg university hospitals drive replacement cycles for aging flash ERG systems while specialized eye care centers expand pattern ERG protocols for glaucoma monitoring. EU MDR conformity assessments extend CE-marked product timelines, filtering procurement toward established quality management systems. The Munich-Stuttgart corridor hosts dense concentrations of ophthalmology research hospitals upgrading to multi-electrode array platforms for inherited retinal dystrophy phenotyping.
United States
Academic medical centers and contract research organizations scale high-throughput screening infrastructure to support gene therapy safety pharmacology workflows. FDA 510(k) pathways shape clinical evidence requirements for electrophysiological devices entering commercial distribution. The Boston-Cambridge biotechnology cluster and Baltimore-Washington corridor concentrate pharmaceutical sponsor demand for validated ERG endpoints with audit trail documentation.
Japan
PMDA enforcement of JIS-compliant electrical safety standards filters non-domestic suppliers from hospital tenders, protecting incumbent positions in electrophysiology laboratory procurement. University ophthalmology departments in Tokyo and Osaka maintain fellowship training pipelines that sustain demand for comprehensive diagnostic platforms. The Kanto region anchors installed base maintenance for flash ERG systems serving pediatric retinal dystrophy diagnosis.
France
Parisian university hospital networks and regional academic centers consolidate procurement toward MDR-transitioned suppliers with proven technical documentation track records. ANSM oversight of electrophysiological equipment safety influences conformity assessment strategies for vendors seeking national reimbursement eligibility. The Île-de-France ophthalmology research corridor drives adoption of cloud-native waveform analysis platforms for multicenter trial coordination.
Italy
Regional health system budget constraints in Lombardy and Veneto favor operational expenditure models over capital-intensive device ownership, accelerating service unbundling trends. Independent optometry chains expand functional electrophysiology service lines as OCT reimbursement compresses diagnostic margins. Milan and Bologna anchor private clinic network procurement of portable systems for ambulatory glaucoma progression monitoring.
Electroretinogram Market Key Industry Players
The competitive structure tilts toward specialized electrophysiology vendors with vertical control over visual electrophysiology protocols. Three to five established manufacturers with multi-decade ISCEV standardization involvement dominate hospital laboratory procurement, while portable form-factor specialists capture ambulatory margin pools. Strategic archetypes include full-stack diagnostic platform suppliers, pattern ERG protocol specialists, and point-of-care miniaturization engineers. Competitive moves center on MDR transition completion timelines and cloud-native service architecture deployment.
Among North American diagnostic specialists, Diopsys and LKC Technologies exemplify contrasting archetypes in visual electrophysiology positioning. Diopsys occupies the integrated platform tier with vertical control over stimulus generation and waveform analysis. LKC Technologies anchors the specialized protocol segment through pattern ERG standardization that dominates academic research procurement. Konan Medical USA sits within the portable engineering tier, competing on battery-powered form factors for space-constrained ambulatory deployment.
| Leading Market Players |
|---|
| Diopsys |
| CSO |
| LKC Technologies |
| Konan Medical USA |
| Roland Consult |
| Diagnosys |
| Metrovision |
| M&S Technologies |
| Electro-Diagnostic Imaging |
| Others |
Cost & Logistics Intelligence
German university hospitals and Bavarian specialized eye care centers anchor procurement volume for electroretinogram systems, locking in premium pricing for MDR-certified manufacturers while squeezing margins on legacy tabletop replacements. Their consolidated purchasing power favors subscription-based service models over capital-intensive device ownership, reshaping how vendors structure recurring revenue streams.
Pricing Analysis
The bundled-versus-unbundled service split defines electroretinogram pricing architecture across European ophthalmology networks. Three-tier pricing structure across premium, standard, and economy levels separates MDR-transitioned platforms with cloud-native analytics from legacy tabletop systems and technician-operated portable units. Price differentiation centers on ISCEV protocol certification grade and after-sales technical support bundling. Cost compression in the portable device tier is intensifying because Spanish and Italian regional health authorities favor operational expenditure models. Independent optometry chains exhibit highest price sensitivity; pharmaceutical sponsors demonstrate lowest sensitivity due to gene therapy trial endpoint requirements.
Supply Chain Analysis
Electrophysiologist training pipeline constraints in Germany and France limit manufacturing workforce availability for precision electrode assembly and calibration phantom production. Component sourcing draws from Japan for JIS-compliant electrical safety modules, the United States for FDA-registered stimulus generation hardware, and Germany for precision optical assemblies. Silver-silver chloride electrode supply rests on precious metal commodity volatility. Single-source vulnerability concentrates in high-density multi-electrode array substrates. Distribution runs through specialized medical device distributors serving hospital electrophysiology laboratories and direct-to-clinic channels for portable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electroretinogram market functions as a regulatory compounder where EU MDR conformity assessment timelines extend product launch windows and consolidate procurement toward certified incumbents. This regulatory milestone drives replacement demand as aging flash ERG systems reach end-of-service life ahead of notified body capacity constraints.
For Market Incumbents: Cement MDR transition completion as the primary defensive moat by accelerating technical documentation packages for electrophysiological equipment. Prioritize backward integration into disposable electrode manufacturing to offset silver price volatility. Channel control through exclusive service contracts with Bavarian university hospitals blocks portable-specialist encroachment. For New Entrants and Emerging Players: Mobile diabetic retinopathy screening operators in Spain and Italy represent the most penetrable buyer archetype currently underserved by hospital-centric vendors. Telemedicine-integrated cloud platforms for remote specialist interpretation open ambulatory settings previously excluded by electrophysiologist staffing requirements. Partner with regional health authorities on operational expenditure pilot programs. For Investors and Strategic Acquirers: Pharmaceutical sponsors with gene therapy pipelines are the most active acquirer in this space, seeking validated ERG endpoint capabilities. Five-to-ten year viability hinges on multi-electrode array technology adoption for high-throughput screening infrastructure. Watch for FDA 510(k) clearance acceleration for AI-powered waveform classification algorithms as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Acceleration | Notified body queuing bottlenecks in Germany and France favor early filers with complete clinical evidence packages. |
| Cloud-Native Waveform Platform Launch | Remote interpretation capabilities unlock Italian and Spanish optometry chains excluded by on-site specialist requirements. |
| Multi-Electrode Array Manufacturing Scale-Up | Gene therapy sponsors in the Boston-Cambridge cluster demand validated high-throughput screening infrastructure. |
| Disposable Electrode Backward Integration | Captive silver-silver chloride supply hedges precious metal price volatility constraining margin expansion. |
| AI Waveform Classification FDA Submission | Machine learning algorithms reduce interpretation variability for technician-operated systems in community settings. |
Research Approach
Coverage spans Germany, the United States, Japan, France, and Italy, with primary inputs from each market's ophthalmology stakeholder ecosystem. Electrophysiologists, hospital purchasing committees, biomedical engineers, GPO contracts managers, and pharmaceutical sponsor clinical operations directors provided structured interviews. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement records, and ISCEV standardization committee proceedings. Bottom-up equipment unit economics triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition anchored the forecast framework through technology adoption curves and replacement cycle modeling. Segmentation dimensions included product form factor, end-user setting, recording technology, and application purpose, with additional modeling of regulatory pathway cluster effects. CAGRs derived from weighted average of historical replacement patterns and pharmaceutical pipeline expansion trajectories. Gene therapy trial enrollment projections and EU MDR transition completion timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; portable device adoption rates and multi-electrode array pharmaceutical procurement carry tighter precision than legacy tabletop replacement forecasting. Projections reflect assumptions about notified body capacity constraints, silver commodity price bands, and OCT substitution effects in glaucoma monitoring. Material deviation in FDA AI algorithm clearance timelines or EU MDR implementation delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Global ECG Stress Test Market