
 Global HLA Typing Market | 2026-2036
Global HLA Typing Market Size, Share, and Industry Trends Forecast 2026-2036
Global HLA Typing Market Foresight
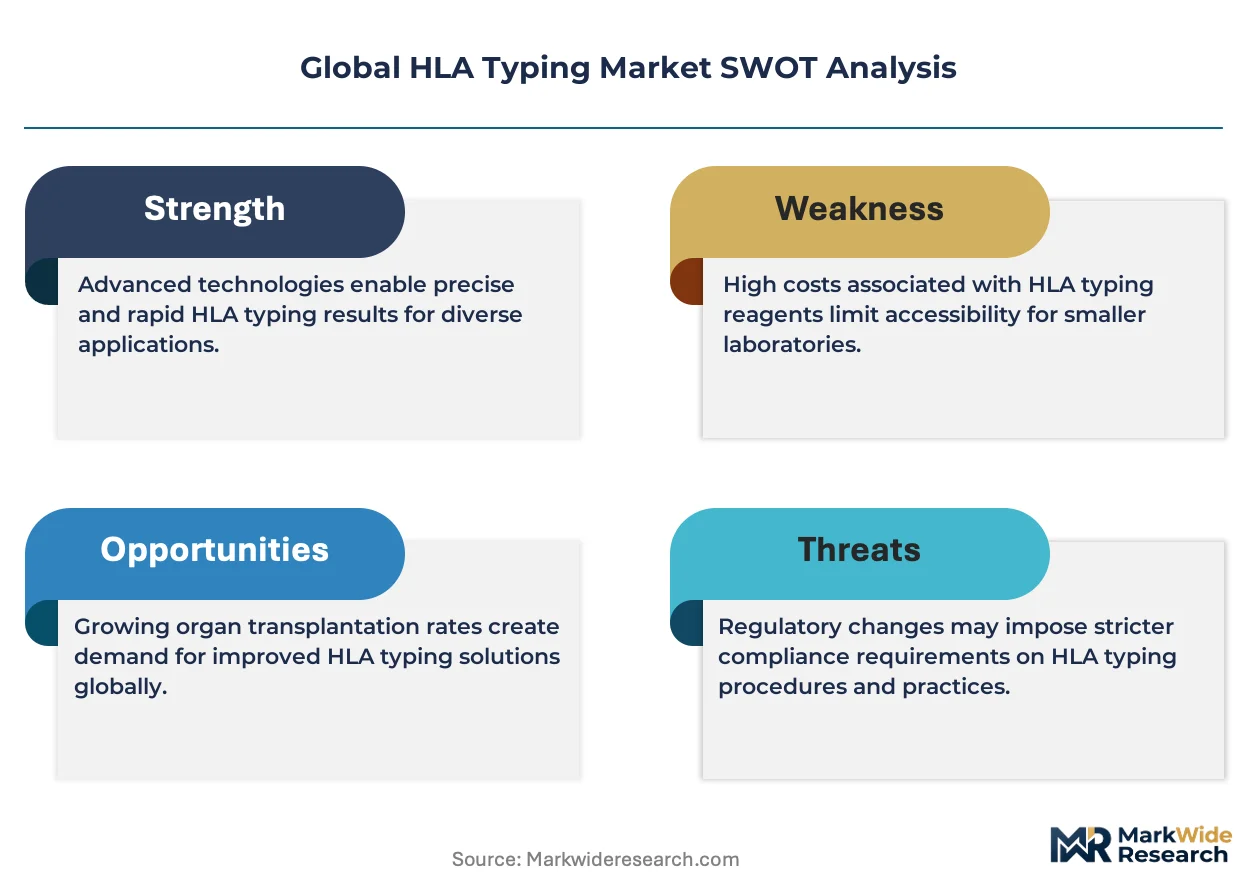
A global shortage of certified histocompatibility laboratory directors is collapsing throughput at mid-sized transplant programs. Thermo Fisher Scientific leverages its end-to-end NGS workflow portfolio to anchor supply relationships with hospital-based labs. Illumina dominates instrument placements at reference laboratories through its NovaSeq ecosystem. QIAGEN competes in sample-prep automation, sustaining recurring reagent pull-through across European and Asian accounts.
Human leukocyte antigen typing identifies polymorphic proteins on chromosome six to determine tissue compatibility between donor and recipient, with modern assays detecting single-nucleotide variants at resolutions below one percent allele frequency. The primary commercial purpose is preventing graft rejection in allogeneic transplantation and guiding platelet transfusion support. Next-generation sequencing captures the fastest expansion as laboratories retire Sanger-based protocols, while serological typing occupies a shrinking but still-mandated niche for pre-transplant crossmatch verification. Sequence-based typing commands premium pricing in unrelated-donor registries where four-digit resolution is compulsory.
FDA oversight of laboratory-developed tests shapes validation requirements for clinical HLA assays, while the European Union's In Vitro Diagnostic Regulation imposes new conformity burdens on CE-marked kits sold into member-state transplant networks. ISO 15189 accreditation drives capital investment in quality-management systems at hospital labs. Stakeholders must monitor how reimbursement shifts toward value-based transplant outcomes will reshape testing economics at independent reference laboratories.
Market Dynamics
The migration from serological to next-generation sequencing platforms is compressing turnaround times while elevating resolution requirements at transplant centers worldwide.
Growth Catalysts
- UNOS Mandates:The United Network for Organ Sharing mandates high-resolution HLA typing for unrelated donor matching, forcing volume expansion at US academic medical centers.
- Solid-Organ Waitlist Expansion:Germany, Japan, and the United States report lengthening queues for kidney and liver transplants, amplifying molecular matching protocol adoption.
- NGS Workflow Integration:Automated library preparation and cloud-based variant calling are collapsing per-sample labor hours in high-throughput histocompatibility laboratories.
Market Restraints
- Reagent Supply Concentration:Specialty oligonucleotide synthesis for HLA primer panels concentrates among three European suppliers, exposing labs to allocation risk during demand spikes.
- ISO 15189 Compliance Burden:Accreditation mandates for hospital-based labs require sustained capital deployment into quality-management infrastructure without direct reimbursement uplift.
- Serological Crossmatch Persistence:Pre-transplant cytotoxicity testing retains regulatory standing as a confirmatory step, preventing full retirement of lower-margin legacy workflows.
Strategic Opportunities
- India Transplant Infrastructure:The country's expanding organ allocation networks lack mature histocompatibility capacity, creating first-mover positioning for NGS platform vendors.
- Platelet Transfusion Support:HLA-matched platelet protocols are penetrating oncology centers as refractory patient identification protocols standardize.
- EU IVDR Transition:The In Vitro Diagnostic Regulation's 2027 enforcement deadline is compressing CE-marked kit validation timelines, rewarding early registrants with incumbent status in member-state tender processes.
Industry Challenges
- Histocompatibility Director Shortage:ASHI-certified laboratory director availability constrains throughput expansion at mid-sized transplant programs in the United States and Canada.
- Legacy LIS Integration:Next-generation sequencing data pipelines require middleware development to interface with entrenched laboratory information systems at hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HLA Typing Market |
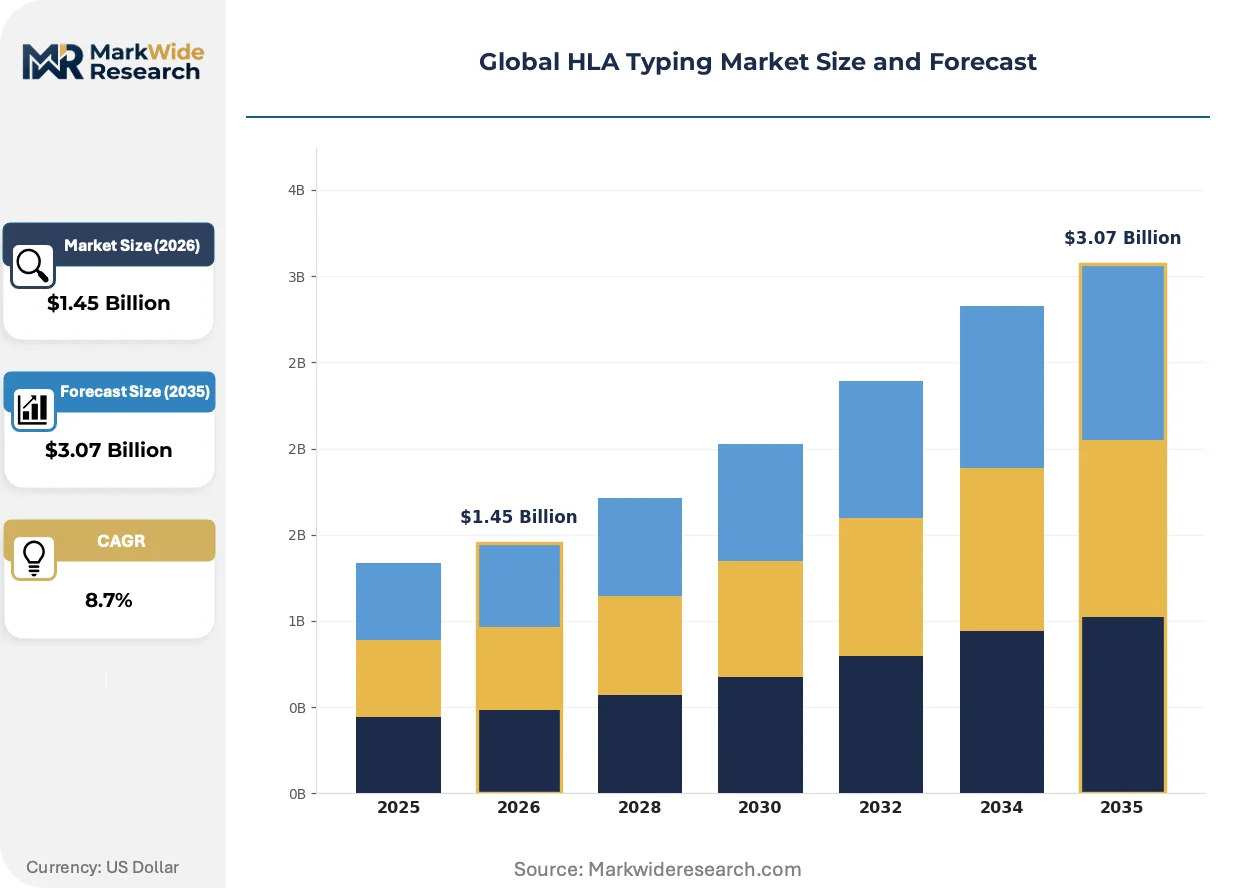
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequence-Based Typing, Polymerase Chain Reaction, Serological Typing, Next-Generation Sequencing, Microarray Application: Transplant Compatibility, Disease Association, Pharmacogenomics, Population Genetics, Immune Response Evaluation End User: Clinical Laboratories, Research Institutes, Diagnostic Centers, Biotechnology Firms, Organ Transplant Centers Technology: Flow Cytometry, Sanger Sequencing, Real-Time PCR, Digital PCR, Mass Spectrometry |
| Companies Covered | F. Hoffmann-La Roche Ltd, CareDx, Thermo Fisher Scientific, Immucor, Becton, Dickinson and Company, QIAGEN, Bio-Rad Laboratories, Werfen, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HLA Typing Market Shifts & Advancements
Instrumentation footprints are shrinking while regulatory data requirements expand, forcing vendors to recalibrate hardware-software bundles for constrained laboratory spaces.
Third-generation sequencing chemistries are miniaturizing. Oxford Nanopore's portable platforms enable point-of-care HLA typing for emergency solid-organ procurement scenarios. Transplant coordinators at German and Japanese retrieval hospitals are piloting these devices for donor-site rapid screening. The technology is compressing cold ischemia time windows by eliminating courier transport to centralized labs.
The European Union's In Vitro Diagnostic Regulation imposes new post-market surveillance obligations on HLA assay manufacturers. CE-marked kits now require annual performance reporting and variant database updates. Reference laboratories in France and Germany are consolidating supplier relationships to reduce validation multiplicity, favoring vendors with established notified body partnerships.
Academic medical centers are unbundling after-sales service contracts from instrument procurement. Procurement officers at US transplant centers now negotiate reagent supply agreements separately from maintenance and bioinformatics support. This pattern is most visible at high-volume UNOS-designated programs where annual test volumes exceed fifty thousand samples.
Global HLA Typing Market Segmentation
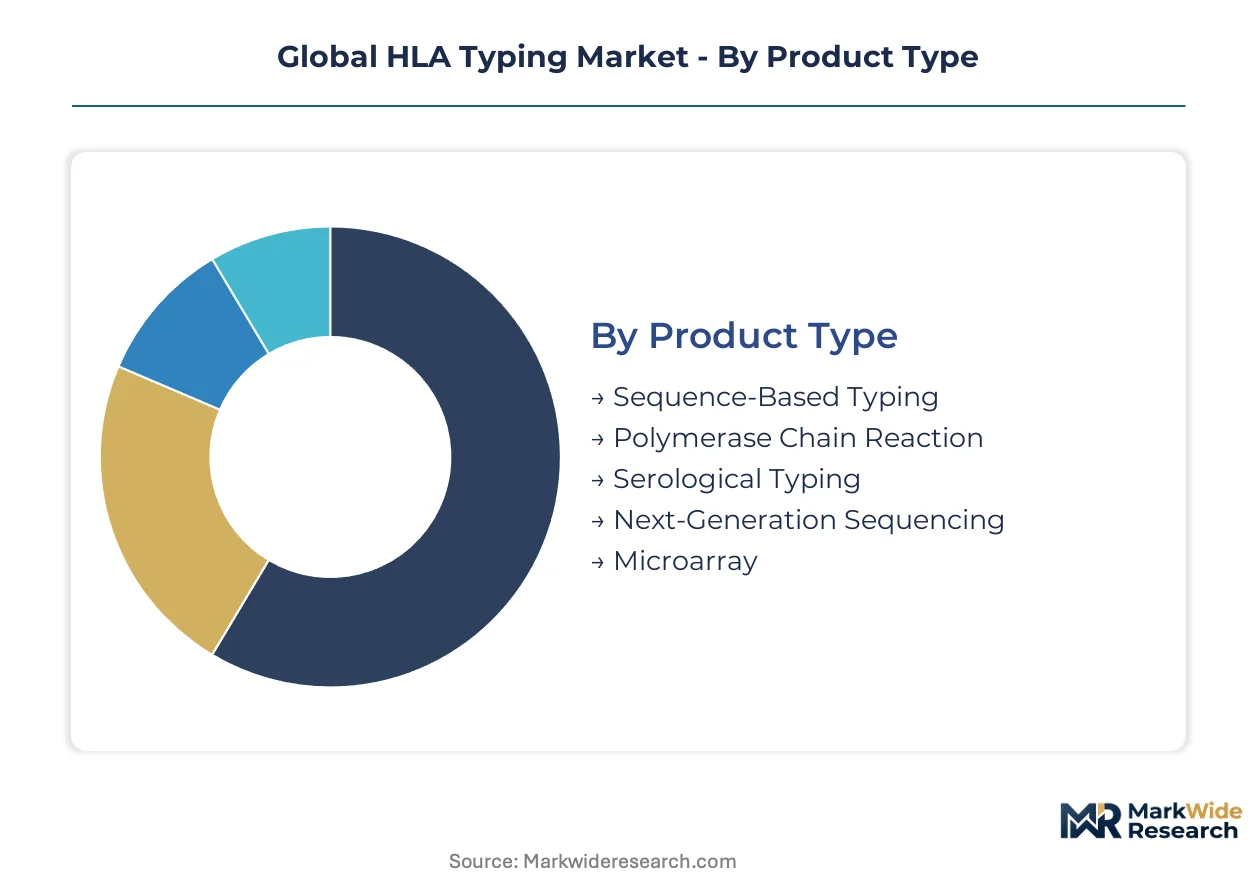
HLA typing segmentation reflects divergent technical maturity and reimbursement economics across molecular platforms. Laboratories select methods based on resolution requirements, sample throughput, and regulatory compliance burdens specific to transplant versus research applications.
Product Type:
Margin pools concentrate in high-resolution molecular platforms where reagent pull-through and service contracts generate recurring revenue.
- Next-Generation Sequencing:Parallel sequencing of HLA loci delivers four-digit resolution for unrelated-donor registries. United States academic medical centers under UNOS mandates are displacing Sanger protocols as cloud-based variant calling reduces per-sample labor.
- Sequence-Based Typing:Targeted amplicon sequencing with allele-specific primers remains the reference standard for confirmatory testing. German and Japanese transplant networks specify this method for related-donor verification, sustaining premium kit pricing despite longer turnaround times.
- Polymerase Chain Reaction:SSP and SSOP methods dominate low-volume hospital labs with limited capital budgets. ISO 15189 accreditation requirements are compressing margins as labs upgrade to sequence-based alternatives.
- Serological Typing:Complement-dependent cytotoxicity testing retains regulatory standing for pre-transplant crossmatch verification. Mid-sized US programs maintain legacy workflows despite shrinking reimbursement.
- Microarray:Solid-phase antibody detection platforms support platelet transfusion matching in oncology centers. Refractory patient identification protocols are standardizing demand at European hematology units.
Next-Generation Sequencing holds installed capacity. Sequence-Based Typing is rotating up the share rankings.
Application:
Volume concentrates in transplant compatibility testing where regulatory mandates and clinical urgency create inelastic demand.
- Transplant Compatibility:Donor-recipient matching for kidney, liver, heart, and lung transplantation drives test volumes at UNOS-designated programs. Solid-organ waitlist expansion across Germany, the United States, and Japan is amplifying molecular matching protocol adoption.
- Pharmacogenomics:HLA-B*57:01 screening for abacavir hypersensitivity and HLA-B*15:02 for carbamazepine reactions guides therapy selection. Clinical laboratories in the United States are integrating these assays into preemptive genotyping panels.
- Disease Association:HLA-DRB1 typing for rheumatoid arthritis risk stratification and HLA-DQ2/DQ8 for celiac disease support diagnostic workups. Research institutes in France and Germany leverage these applications for population cohort studies.
- Population Genetics:Allele frequency mapping supports donor registry recruitment and anthropological research. Biotechnology firms contract reference laboratories for large-scale genotyping projects.
- Immune Response Evaluation:Vaccine trial immunogenicity assessment and infectious disease susceptibility profiling occupy niche research applications. Academic medical centers deploy these assays for NIH-funded investigation protocols.
Transplant Compatibility commands volume leadership. Pharmacogenomics is climbing the fastest as precision medicine protocols expand.
End User:
Procurement authority and capital deployment capacity vary sharply across institutional categories.
- Organ Transplant Centers:UNOS-mandated testing volumes at high-throughput academic medical centers drive platform consolidation. These sites negotiate unbundled reagent supply agreements separate from instrument maintenance contracts.
- Clinical Laboratories:Hospital-based histocompatibility labs face ISO 15189 accreditation burdens without direct reimbursement uplift. Mid-sized programs in the United States and Canada constrain throughput expansion due to ASHI-certified director shortages.
- Research Institutes:Grant-funded investigators prioritize flexibility over regulatory compliance, favoring open-platform NGS workflows. European molecular anthropology consortia represent concentrated demand for population-scale genotyping.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time and price for transplant center outsourcing contracts. EU IVDR transition timelines are compressing supplier validation choices.
- Biotechnology Firms:Cell therapy developers require HLA typing for autologous and allogeneic product characterization. CDMOs in the United States are building captive histocompatibility capacity to support IND submissions.
Organ Transplant Centers anchor capital deployment. Clinical Laboratories are gaining procurement sophistication.
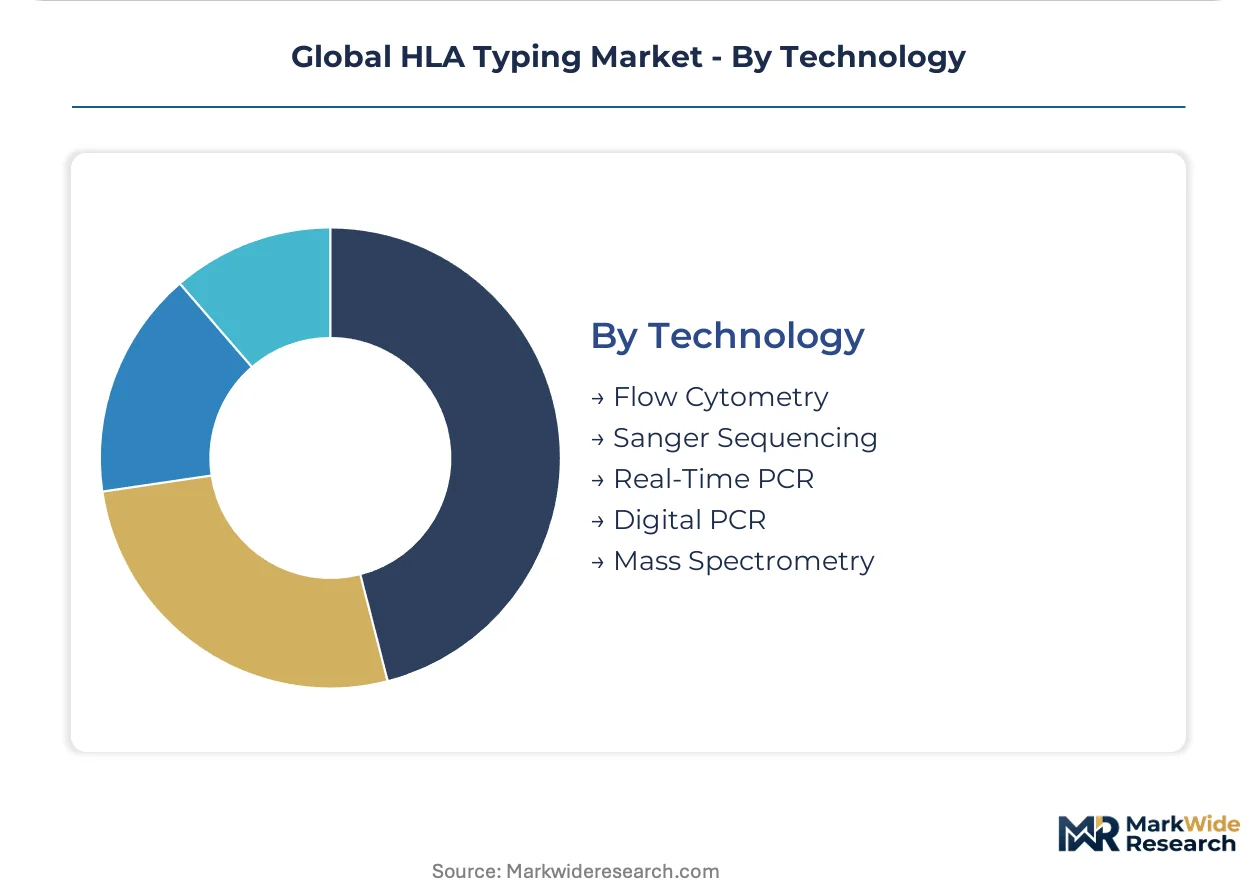
Technology:
Instrument placement reflects the tradeoff between resolution depth and operational simplicity.
- Real-Time PCR:Quantitative amplification with fluorescent probe detection supports HLA allele quantification in chimerism monitoring. Post-transplant engraftment surveillance at German university hospitals sustains installed base.
- Sanger Sequencing:First-generation capillary electrophoresis retains application for single-gene confirmatory testing. Reference laboratories maintain capacity for regulatory submissions requiring orthogonal validation.
- Flow Cytometry:Single-antigen bead assays detect donor-specific antibodies in sensitized transplant candidates. Japanese transplant networks specify this technology for virtual crossmatch protocols.
- Digital PCR:Absolute quantification without standard curves enables rare allele detection in mixed chimerism samples. Research applications predominate as clinical validation timelines extend.
- Mass Spectrometry:MALDI-TOF platforms identify HLA peptides for immunopeptidome research. Academic proteomics core facilities represent the primary installed base.
Real-Time PCR maintains procedural familiarity. Flow Cytometry is expanding fastest in antibody detection applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of laboratory-developed tests shapes validation requirements for clinical HLA assays in the United States, while transplant networks across Germany, Japan, and India drive regional demand patterns through distinct regulatory and infrastructure frameworks.
United States
UNOS mandates for high-resolution HLA typing at academic medical centers generate concentrated test volumes. The FDA's LDT oversight framework imposes validation burdens on hospital-based histocompatibility laboratories. Major transplant clusters in Boston, Houston, and Los Angeles anchor platform consolidation as procurement officers negotiate unbundled reagent agreements.
Germany
Lengthening solid-organ waitlists for kidney and liver transplants amplify molecular matching protocol adoption. The EU IVDR transition compresses CE-marked kit validation timelines for member-state tender processes. Transplant coordinators at retrieval hospitals in Bavaria and North Rhine-Westphalia pilot rapid donor-site screening technologies.
Japan
Virtual crossmatch protocols specify flow cytometry for donor-specific antibody detection in sensitized candidates. PMDA regulatory pathways shape assay approval timelines for commercial kit vendors. The Kansai region around Osaka hosts concentrated histocompatibility laboratory capacity serving national transplant networks.
India
Expanding organ allocation networks lack mature histocompatibility infrastructure, creating positioning opportunities for NGS platform vendors. CDSCO oversight of IVD imports affects kit availability at emerging transplant centers. Metropolitan clusters in Maharashtra and Karnataka represent priority deployment targets for first-mover equipment vendors.
United Kingdom
NHS Blood and Transplant procurement frameworks consolidate supplier relationships for molecular typing services. MHRA post-Brexit regulatory autonomy reshapes conformity assessment pathways for CE-UK dual-marked assays. London and Manchester anchor reference laboratory capacity for unrelated-donor registry matching.
Global HLA Typing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the HLA typing market. The upper tier combines instrument manufacturing with reagent supply and bioinformatics support, while mid-sized players concentrate on sample-prep automation or antibody detection platforms. Strategic archetypes include end-to-end workflow providers, component specialists, and service-oriented reference laboratories. Competitive moves center on unbundling procurement contracts and consolidating supplier relationships ahead of EU IVDR enforcement deadlines.
Among integrated life science conglomerates, Thermo Fisher Scientific and Illumina occupy positions spanning instrumentation and consumables. Thermo Fisher Scientific exemplifies the end-to-end workflow archetype through its NGS platform portfolio. Illumina anchors the sequencing instrument tier with placements at high-throughput reference laboratories. QIAGEN sits within the sample-prep automation specialist tier, sustaining recurring reagent pull-through across European and Asian accounts.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| CareDx |
| Thermo Fisher Scientific |
| Immucor |
| Becton, Dickinson and Company |
| QIAGEN |
| Bio-Rad Laboratories |
| Werfen |
| Illumina |
| Others |
Supply & Pricing Matrix
ISO 15189 accreditation gates both vendor qualification and price stratification in the HLA typing market, forcing mid-sized hospital labs to absorb quality-management infrastructure costs without reimbursement uplift while tiering assay pricing by resolution depth and regulatory certification level.
Pricing Analysis
Price spreads widen between UNOS-designated academic medical centers in the United States and mid-sized transplant programs in Canada and Europe. Three-tier pricing structure across premium, standard, and economy levels separates high-resolution NGS workflows with full bioinformatics support from basic SSP kits and legacy serological panels. Cost compression in the economy tier is intensifying because ISO 15189 compliance mandates force capital diversion into quality systems rather than assay procurement. Independent reference laboratories exhibit highest price sensitivity; major academic centers with unbundled procurement authority negotiate least.
Supply Chain Analysis
Inventory buffers for HLA primer oligonucleotides stretch to sixteen weeks at European and Asian reference laboratories. Specialty synthesis concentrates in Germany, Switzerland, and the United States, with sequencing reagents drawing from Illumina's San Diego manufacturing and Thermo Fisher's Carlsbad production. Single-source vulnerability pervades the primer panel tier where three European suppliers dominate. Distribution runs through direct vendor-to-lab contracts for high-volume accounts, with regional distributors serving fragmented hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HLA typing market functions as a service-attach opportunity where cloud-based variant calling and annual performance reporting contracts expand faster than instrument hardware placements, particularly under EU IVDR post-market surveillance obligations.
For Market Incumbents: Shield installed base relationships by embedding bioinformatics support into multi-year reagent supply agreements before EU IVDR enforcement compresses supplier switching windows. Deepen backward integration into primer synthesis to reduce allocation exposure during demand spikes. Anchor procurement officers at UNOS-designated programs with unbundled service contracts that separate instrument maintenance from consumable pricing.
For New Entrants and Emerging Players: Differentiate on point-of-care portability for emergency donor-site screening, targeting transplant coordinators at German and Japanese retrieval hospitals where cold ischemia time compression commands premium positioning. Penetrate India's emerging transplant infrastructure through NGS platform leasing models that bypass capital-constrained hospital procurement cycles. Pursue CDSCO import pathway partnerships with established IVD distributors to accelerate kit registration.
For Investors and Strategic Acquirers: Carve-out targets emerge from academic medical center spin-outs and cell therapy CDMO captive histocompatibility units where IND submission timelines force capability build-or-buy decisions. Long-term viability hinges on recurring revenue attachment rates exceeding hardware depreciation cycles. Monitor ASHI-certified director vacancy rates at mid-sized US programs as throughput constraint indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Early Registration | CE-marked kit validation ahead of enforcement deadline secures incumbent status in member-state tenders. |
| Cloud-Based Variant Calling Deployment | Software companion development reduces per-sample labor hours at high-throughput UNOS-designated programs. |
| Primer Synthesis Backward Integration | Captive oligonucleotide production mitigates allocation risk from European specialty suppliers. |
| Point-of-Care Platform Miniaturization | Oxford Nanopore portable sequencing enables donor-site rapid screening at German retrieval hospitals. |
| ASHI Certification Pipeline Investment | Laboratory director training programs address throughput constraints at mid-sized US transplant centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with histocompatibility laboratory directors, transplant procurement officers, and IVD regulatory affairs specialists; and secondary validation against FDA 510(k) filings, EUDAMED CE-marking records, UNOS testing volume reports, and ISO 15189 accreditation databases. Bottom-up instrument placement counts and top-down transplant center expenditure estimates were triangulated to anchor market sizing.
Across the projection horizon, the analytical framework modeled segmentation by molecular platform type, application category, and end-user institutional tier alongside geographic regulatory cluster. CAGRs were derived from installed base growth trajectories and per-sample pricing trends. Forecast inputs incorporated UNOS mandate expansion timelines, EU IVDR transition schedules, and solid-organ waitlist projections from national transplant registries.
The analysis sits within stated boundaries; outcomes outside sustained FDA LDT oversight stability or accelerated EU IVDR enforcement would require recalibration. Forecasts reflect documented assumptions regarding reimbursement policy continuity and certified director supply elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Blood Platelet Market