
 US Mobile MRI Services Market | 2026-2036
US Mobile MRI Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Mobile MRI Services Market Intelligence
The gap between high-field closed systems and lower-field open platforms is consolidating as reimbursement rates diverge and clinical expectations harden. RAYUS Radiology leverages its national fleet footprint to sustain density advantages across secondary markets. Shared Medical Services anchors its position through long-term partnerships with critical access hospitals in the Upper Midwest. RadNet, Inc. competes by integrating mobile capacity with its fixed-site network, creating referral continuity that pure fleet operators cannot replicate.
Mobile MRI services deploy self-contained diagnostic imaging systems mounted within specialized vehicles, typically operating at 1.5 Tesla or 3.0 Tesla field strength with active shielding and cryogen management systems designed for transit stability. These units serve healthcare providers requiring on-demand neurovascular, orthopedic, or abdominal imaging without permanent infrastructure investment. Closed MRI systems dominate revenue contribution due to superior image resolution and broader insurance coverage, while open MRI configurations occupy a specialized niche serving bariatric and claustrophobic patient populations where comfort constraints override throughput priorities. Scheduled scans generate the steadiest utilization rates, though emergency services command premium pricing when hospitals face magnet downtime or patient overflow.
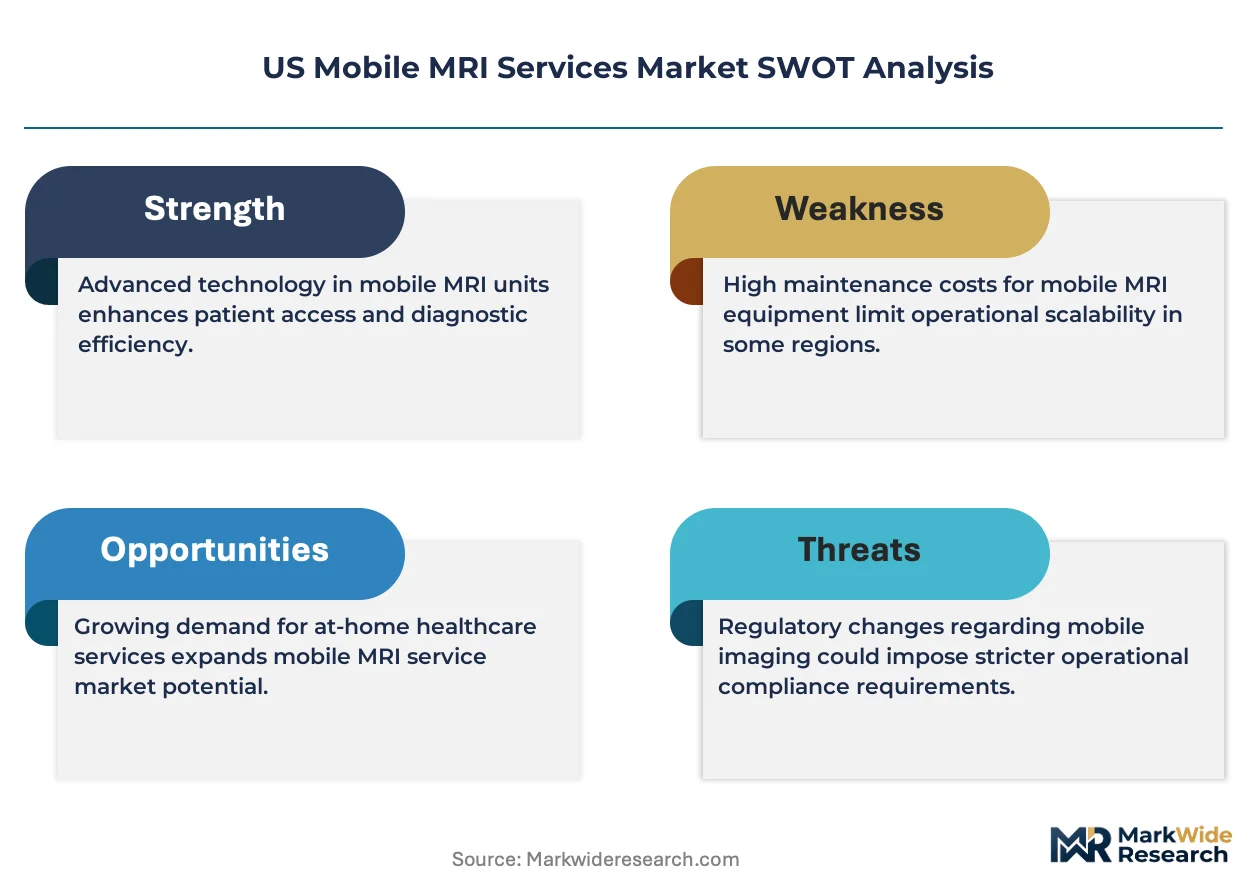
FDA 510(k) clearance requirements govern each mobile unit's imaging hardware, while CMS reimbursement codes directly shape provider economics for both hospital-based and freestanding imaging. OSHA workplace safety standards apply to technologist exposure and vehicle ergonomics, creating compliance costs that favor larger operators with dedicated regulatory staff. Stakeholders must monitor whether state-level certificate-of-need reforms expand addressable markets or intensify fleet saturation in already competitive corridors.
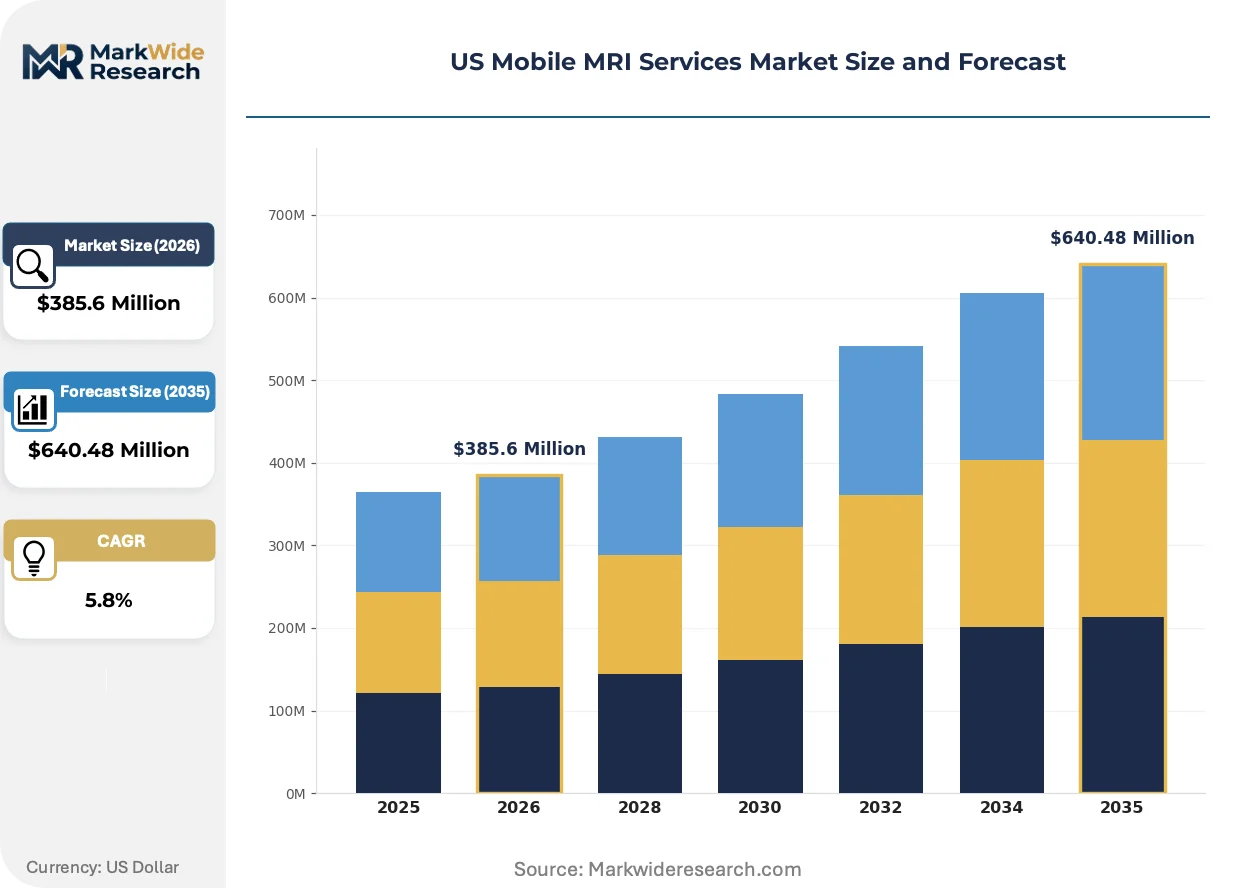
Market Dynamics
CMS reimbursement compression for diagnostic imaging is forcing rural hospitals toward fleet-based MRI partnerships rather than capital-intensive fixed installations. This structural shift concentrates purchasing power among national fleet operators while fragmenting local service provision across secondary markets.
Growth Catalysts
- Critical Access Hospital Demand:Rural facilities in Texas, Florida, and Ohio are replacing aging in-house scanners with flexible mobile arrangements to preserve capital for core clinical services.
- CMS Reimbursement Codes:Outpatient imaging reimbursement adjustments favor scheduled mobile scans over emergency department utilization, aligning fleet economics with hospital budget constraints.
- Magnet Downtime Coverage:Fixed-site hospitals facing planned or unplanned scanner outages increasingly contract mobile units to maintain surgical schedules and patient throughput.
Market Restraints
- Cryogen Supply Volatility:Helium price fluctuations and supply chain disruptions constrain mobile unit operational continuity, particularly for 3.0 Tesla systems requiring larger cryogen volumes.
- Fleet Operator Concentration:National providers control the majority of available mobile MRI capacity in the Upper Midwest, limiting competitive pricing pressure in underserved corridors.
- OSHA Workplace Standards:Technologist exposure limits and vehicle ergonomic requirements impose compliance costs that disadvantage smaller regional operators lacking dedicated regulatory staff.
Strategic Opportunities
- Ambulatory Surgery Center Expansion:Outpatient facilities in the Southeast are integrating mobile MRI into pre-operative workflows, creating dedicated scheduling arrangements that improve unit utilization rates.
- Open MRI Niche Penetration:Bariatric and claustrophobic patient populations in underserved metropolitan areas present white space for lower-field open configurations where comfort constraints override throughput priorities.
- State CON Reform Momentum:Certificate-of-need liberalization in select states is expanding addressable markets for fleet deployment without fixed-site capital requirements.
Industry Challenges
- Technologist Workforce Scarcity:Specialized MRI technologist shortages in rural markets constrain fleet expansion velocity and force wage premiums that compress operator margins.
- FDA 510(k) Clearance Timelines:Mobile unit hardware modifications require individual regulatory submissions, creating deployment delays that limit fleet reconfiguration flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mobile MRI Services Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up MRI, Closed MRI, Open MRI, Extremity MRI Service Type: Patient Transport, On-Site Imaging, Scheduled Scans, Emergency Services End User: Hospitals, Outpatient Centers, Imaging Facilities, Rehabilitation Centers Technology: Digital Imaging, Wireless Integration, Software Solutions, Advanced Scanning |
| Companies Covered | RAYUS Radiology, Shared Medical Services, DMS Health, KMG, RadNet, Inc., Front Range Mobile Imaging, Inc., Meridian Group International, Probo Medical, Akumin Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mobile MRI Services Market Strategic Shifts & Innovations
Artificial intelligence integration and remote diagnostic capabilities are compressing the traditional service model for mobile imaging. Fleet operators now compete on algorithm-enabled throughput rather than hardware specifications alone.
AI-powered image reconstruction software is unifying quality assurance protocols across dispersed mobile units. Critical access hospitals in the Upper Midwest are adopting these platforms to match fixed-site diagnostic confidence without permanent magnet investment. This technology is unifying previously fragmented service standards across independent imaging facilities and hospital networks.
FDA equipment safety oversight for mobile MRI hardware is intensifying documentation requirements for transit-stability validation and cryogen management systems. The agency's expanded 510(k) review scope is lengthening deployment timelines for fleet operators introducing upgraded field strength configurations. Mobile providers serving Texas and Florida markets are responding by front-loading regulatory submissions and standardizing platform architectures across their deployed base.
Subscription-based fleet access contracts are displacing traditional per-scan pricing in hospital procurement. Rural facilities in Ohio and surrounding states are negotiating multi-year partnerships that bundle scheduled capacity with emergency overflow guarantees. This purchasing pattern shift is most visible among independent imaging facilities seeking budget predictability amid CMS reimbursement uncertainty.
US Mobile MRI Services Market Segmentation
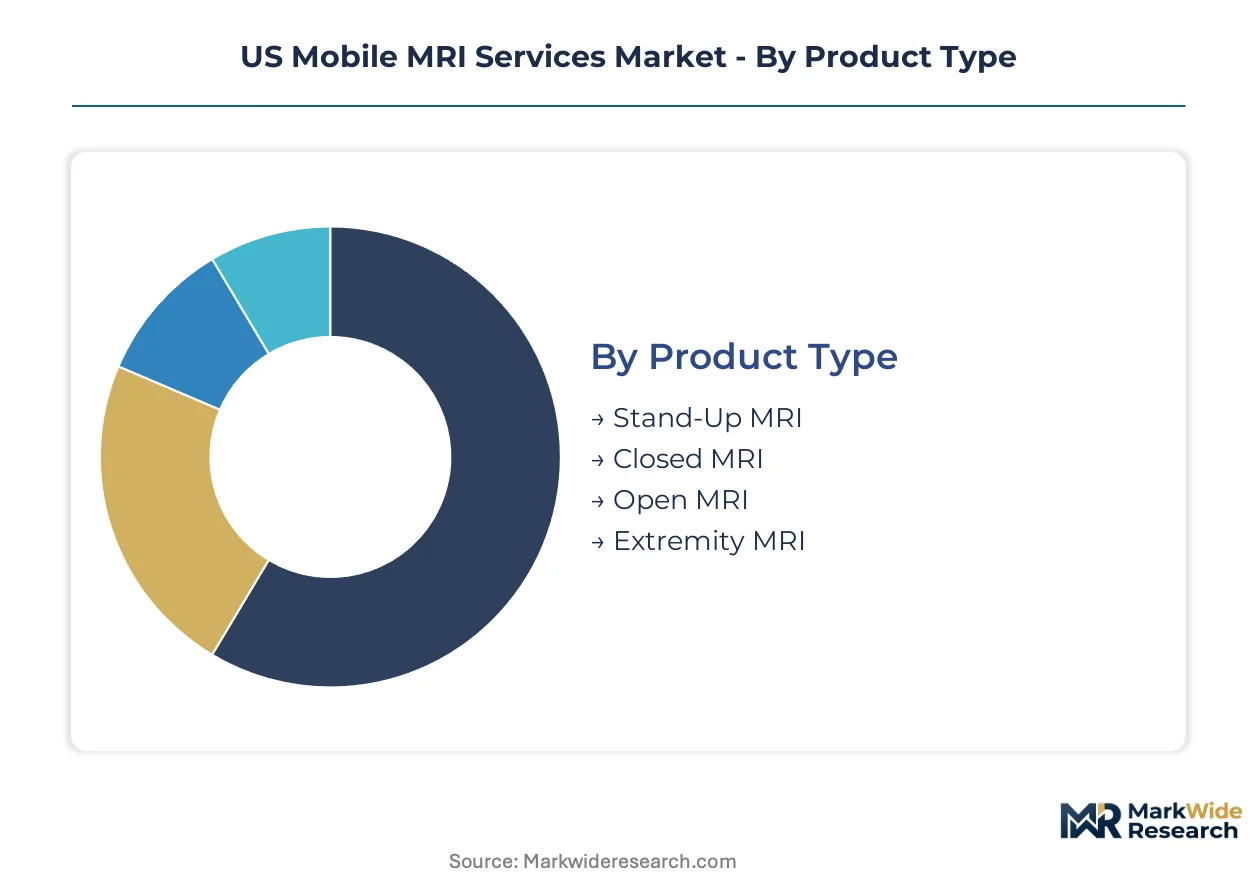
Mobile MRI fleet operators configure their deployed assets across four distinct dimensions to match reimbursement economics with site-specific clinical requirements. Each segmentation layer reveals where capital concentrates and where service innovation unlocks contracting advantages.
Product Type:
Supply concentration in high-field closed systems shapes fleet procurement patterns across Texas, Florida, and Ohio corridors.
- Stand-Up MRI:Vertical-field configurations accommodate patients unable to recline, utilizing 0.5 Tesla to 0.6 Tesla magnets with specialized RF coils for spine and joint imaging. Demand concentrates in rehabilitation centers across the Southeast where weight-bearing diagnostics support orthopedic surgical planning, though reimbursement codes limit widespread adoption.
- Closed MRI:1.5 Tesla and 3.0 Tesla cylindrical-bore systems deliver diagnostic-grade resolution for neurovascular and abdominal protocols. Hospital systems in the Upper Midwest anchor long-term fleet contracts around these units, prioritizing throughput and insurance coverage breadth over patient comfort accommodations.
- Open MRI:C-shaped or double-doughnut magnet geometries eliminate enclosed bore constraints for bariatric and claustrophobic populations. These units occupy specialized niches in metropolitan outpatient markets where patient satisfaction metrics influence referral patterns.
- Extremity MRI:Compact dedicated systems image hands, wrists, feet, and ankles without full-body magnet requirements. Sports medicine clinics and orthopedic surgery centers in Texas deploy these for high-volume joint assessments with reduced per-scan operational costs.
Closed MRI absorbs the bulk of installed capacity; Stand-Up MRI is expanding most quickly among rehabilitation-focused providers.
Service Type:
Procurement patterns are shifting from per-scan pricing toward bundled arrangements that guarantee capacity access.
- Patient Transport:Coordinated logistics services move non-ambulatory patients between facilities and mobile units, requiring specialized lift equipment and clinical escort protocols. Critical access hospitals in rural Ohio leverage these services to extend diagnostic reach without fixed-site investment.
- On-Site Imaging:Mobile units park at healthcare facility premises for multi-day deployments with dedicated technologist staffing. Ambulatory surgery centers in Florida favor this model for pre-operative workflow integration, securing predictable scheduling blocks.
- Scheduled Scans:Pre-booked appointment sequences maximize unit utilization rates and align with CMS outpatient reimbursement codes. Independent imaging facilities in the Upper Midwest negotiate quarterly capacity commitments to stabilize revenue forecasting.
- Emergency Services:Unplanned deployments address magnet downtime or patient overflow with premium pricing structures. Hospital networks in Texas maintain these arrangements as surgical schedule insurance against fixed-scanner maintenance windows.
Scheduled Scans absorb the bulk of contracted revenue; Emergency Services command the steepest premium differentials.
End User:
Customer concentration among hospital systems creates purchasing power asymmetries that squeeze regional fleet operators.
- Hospitals:Acute care facilities contract mobile capacity to supplement fixed-site installations or serve overflow demand. Rural hospitals across the Midwest and Southeast are replacing aging in-house scanners entirely with flexible fleet partnerships to preserve capital for core clinical services.
- Outpatient Centers:Freestanding surgical and diagnostic facilities integrate mobile MRI into pre-operative workflows without permanent infrastructure. Facilities in Florida and Ohio are driving adoption of subscription-based access contracts with multi-year terms.
- Imaging Facilities:Independent diagnostic centers utilize mobile units to extend service menus without magnet capital expenditure. These operators in Texas concentrate demand for high-field closed systems to maintain competitive parity with hospital-based competitors.
- Rehabilitation Centers:Post-acute and long-term care facilities deploy mobile services for musculoskeletal and neurological assessments. Stand-Up MRI configurations serve this segment's functional imaging requirements for weight-bearing spine and joint evaluation.
Hospitals absorb the bulk of fleet capacity; Outpatient Centers are gaining share fastest amid ambulatory surgery expansion.
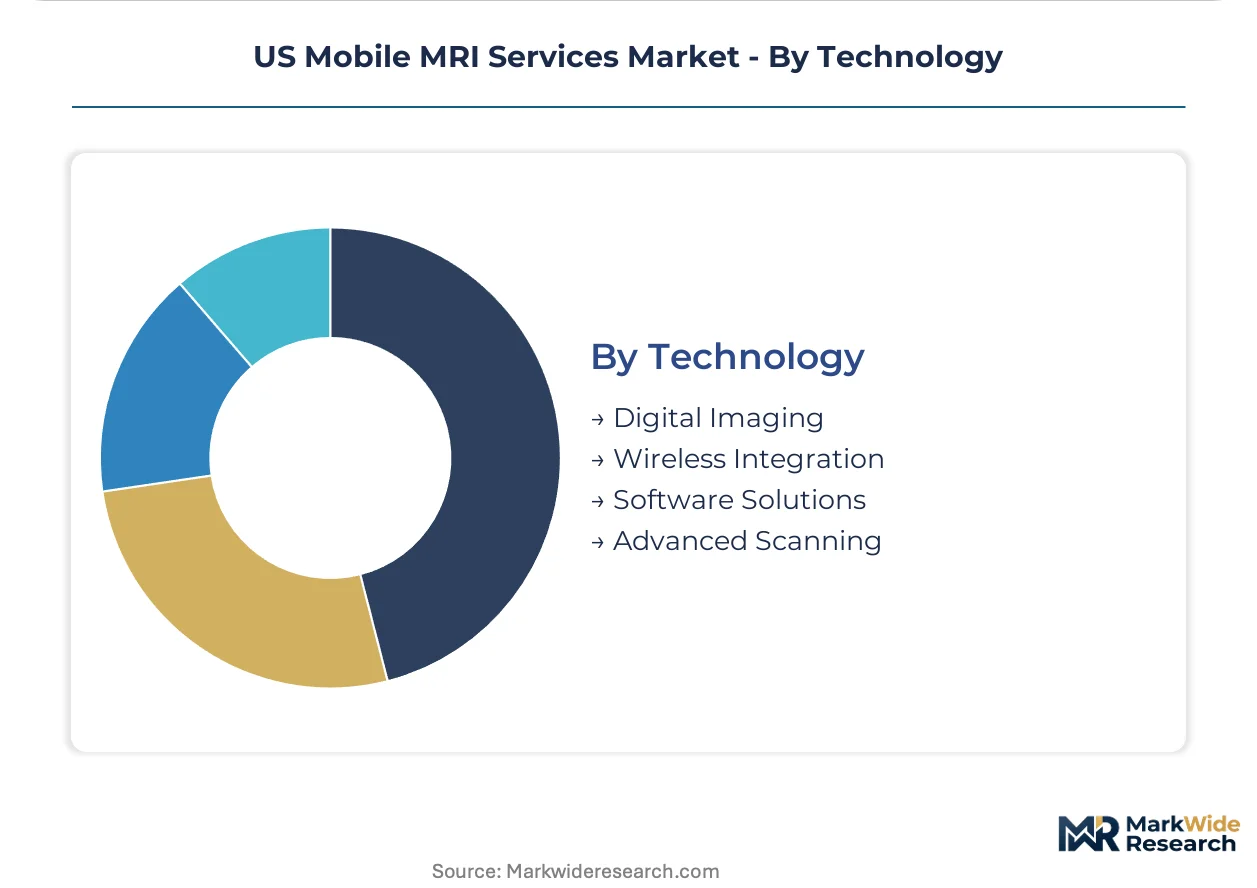
Technology:
Margin compression in hardware provision is redirecting competitive investment toward software-enabled service differentiation.
- Digital Imaging:High-resolution acquisition protocols with PACS integration enable remote radiologist interpretation. Critical access hospitals adopt these platforms to match fixed-site diagnostic confidence without permanent magnet investment.
- Wireless Integration:Real-time data transmission between mobile units and hospital information systems streamlines workflow coordination. Fleet operators deploy these capabilities to reduce turnaround times for emergency service contracts.
- Software Solutions:AI-powered image reconstruction and quality assurance tools standardize output across dispersed mobile deployments. National fleet operators leverage these systems to maintain consistent diagnostic standards across secondary markets.
- Advanced Scanning:Specialized sequences for cardiac, breast, and prostate imaging extend mobile unit clinical utility. These capabilities support premium pricing in metropolitan markets where subspecialty referral patterns concentrate.
Digital Imaging absorbs the bulk of technology investment; Software Solutions are climbing the fastest as AI integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the densest concentration of mobile MRI fleet operations, with Texas hospitals driving subscription-based contracting models that bundle scheduled capacity with emergency overflow guarantees.
Texas
Independent imaging facilities in Dallas-Fort Worth and Houston concentrate demand for high-field closed systems to maintain competitive parity with hospital-based competitors. FDA 510(k) clearance timelines for mobile unit hardware modifications create deployment delays that limit fleet reconfiguration flexibility. The Texas Medical Center corridor sustains the highest emergency service contract density, with hospital networks maintaining surgical schedule insurance against fixed-scanner maintenance windows.
Florida
Ambulatory surgery centers across the Tampa and Orlando metros integrate mobile MRI into pre-operative workflows, securing predictable scheduling blocks through multi-year partnerships. CMS reimbursement code adjustments for outpatient imaging favor scheduled mobile scans over emergency department utilization. The Southeast Florida corridor from Miami to West Palm Beach drives adoption of subscription-based access contracts among independent imaging facilities seeking budget predictability.
Ohio
Critical access hospitals in rural Ohio leverage patient transport services to extend diagnostic reach without fixed-site investment, replacing aging in-house scanners entirely with flexible fleet arrangements. OSHA workplace safety standards for technologist exposure and vehicle ergonomics impose compliance costs that disadvantage smaller regional operators. The Cleveland-Akron corridor anchors long-term fleet contracts with hospital systems prioritizing throughput and insurance coverage breadth.
Illinois
Rehabilitation centers in the Chicago metro deploy Stand-Up MRI configurations for weight-bearing spine and joint evaluation, serving functional imaging requirements for orthopedic surgical planning. State-level certificate-of-need reforms expand addressable markets for fleet deployment without fixed-site capital requirements. The Peoria-Springfield corridor concentrates critical access hospital demand for mobile capacity to supplement fixed-site installations or serve overflow demand.
Michigan
Hospital networks in Detroit and Grand Rapids contract mobile units to maintain surgical schedules during planned or unplanned fixed-scanner outages, with premium pricing structures for emergency deployments. Helium price fluctuations and supply chain disruptions constrain mobile unit operational continuity, particularly for 3.0 Tesla systems requiring larger cryogen volumes. The Upper Peninsula sustains specialized demand for open MRI configurations serving bariatric and claustrophobic patient populations where comfort constraints override throughput priorities.
US Mobile MRI Services Market Key Industry Players
Capital-heavy fleet operators compete with asset-light service coordinators across the US mobile MRI landscape. National providers control the majority of available capacity in the Upper Midwest, limiting competitive pricing pressure in underserved corridors. Three strategic archetypes dominate: integrated imaging networks combining mobile and fixed-site assets, pure-play fleet operators maximizing geographic coverage density, and equipment-focused specialists leveraging manufacturer relationships. Consolidation through long-term hospital partnerships and technology-enabled service differentiation represent the dominant competitive vectors reshaping operator economics.
Within the national fleet tier, RAYUS Radiology exemplifies scale-driven density advantages across secondary markets, while Shared Medical Services anchors its position through critical access hospital relationships in the Upper Midwest. RadNet, Inc. occupies a hybrid position integrating mobile capacity with fixed-site network referral continuity. These three operators represent contrasting strategic postures: pure fleet scale, partnership depth, and vertical integration between mobile and stationary assets.
| Leading Market Players |
|---|
| RAYUS Radiology |
| Shared Medical Services |
| DMS Health |
| KMG |
| RadNet, Inc. |
| Front Range Mobile Imaging, Inc. |
| Meridian Group International |
| Probo Medical |
| Akumin Inc. |
| Others |
Cost & Logistics Intelligence
Subscription-based fleet access contracts are displacing traditional per-scan pricing as rural hospitals in Ohio and surrounding states negotiate multi-year partnerships that bundle scheduled capacity with emergency overflow guarantees, forcing national operators to restructure cost allocation across their deployed base and compress margins on standalone emergency deployments.
Pricing Analysis
Throughput-based pricing anchors mobile MRI contracting, with scheduled scan blocks commanding lower per-unit rates than emergency overflow deployments due to utilization predictability. Price differentiation separates premium-tier 3.0 Tesla configurations from standard 1.5 Tesla units based on field strength and cryogen volume requirements. Cost compression in emergency service tiers is intensifying because hospital networks are consolidating purchasing power through multi-year subscription agreements. Critical access hospitals in the Upper Midwest exhibit highest price sensitivity, while Texas hospital systems maintain lowest sensitivity due to surgical schedule insurance value.
Supply Chain Analysis
Single-source vulnerability sits with helium suppliers concentrated in Qatar, Russia, and the United States, where geopolitical disruptions constrain cryogen availability for superconducting magnet cooling. Mobile MRI hardware draws from specialized manufacturers in Germany, Japan, and the United States for gradient coil assemblies and RF subsystems. Tariff exposure on European-sourced magnet components creates procurement cost volatility for fleet operators. Distribution runs through regional service hubs that position units within four-hour drive times of contracted hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance timelines and OSHA workplace safety standards create a cost-of-compliance moat that favors established fleet operators with dedicated regulatory staff and disadvantages smaller regional entrants lacking specialized compliance infrastructure.
For Market Incumbents: Anticipate margin compression from AI-enabled image reconstruction commoditization by deepening partnerships with critical access hospitals in the Upper Midwest and securing exclusive multi-year subscription contracts before reimbursement uncertainty hardens procurement timelines. Prioritize backward integration into cryogen logistics to mitigate helium supply volatility. For New Entrants and Emerging Players: AI-powered remote diagnostic platforms offer a technology-first wedge into underserved metropolitan outpatient markets where open MRI configurations serve bariatric and claustrophobic populations. Target ambulatory surgery centers in Florida's Tampa-Orlando corridor with pre-operative workflow integration and dedicated scheduling block guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid operators combining mobile fleet density with fixed-site referral networks given CMS reimbursement code adjustments favoring integrated service delivery. Long-term viability hinges on technology-enabled service differentiation rather than pure asset scale. Monitor state-level certificate-of-need reform momentum as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Strategy | Front-loaded regulatory submissions compress deployment timelines for upgraded field strength configurations in Texas and Florida markets. |
| Critical Access Hospital Partnership | Long-term contracts with rural Ohio facilities replace aging in-house scanners and secure predictable revenue baselines. |
| AI Image Reconstruction Integration | Algorithm-enabled throughput standardization matches fixed-site diagnostic confidence without permanent magnet investment. |
| Cryogen Supply Agreement | Helium logistics partnerships mitigate operational continuity risks for 3.0 Tesla systems requiring larger cryogen volumes. |
| Ambulatory Surgery Center Workflow Integration | Pre-operative scheduling blocks in Florida metros improve unit utilization rates and align with CMS outpatient reimbursement codes. |
Research Approach
Document review covered FDA 510(k) filings, CMS reimbursement code databases, and OSHA workplace safety standards, complemented by interviews with fleet operations directors, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and state-level certificate-of-need regulatory filings. Bottom-up unit deployment counts were triangulated against top-down market size estimates derived from operator revenue disclosures.
Historical utilization patterns were cross-referenced against panel input from fleet operators and hospital administrators to establish baseline assumptions across the projection horizon. Segmentation modeling incorporated product type, service configuration, end-user category, and technology tier dimensions. CAGRs were derived from weighted average growth trajectories across state-level demand clusters, with helium price volatility and technologist wage inflation incorporated as sensitivity inputs.
Several conditions sit outside the modeled scope, including unanticipated FDA equipment safety oversight expansion, disruptive magnet technology transitions, and radical certificate-of-need liberalization beyond currently observed reform momentum. Forecasts reflect documented assumptions about reimbursement stability and cryogen supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
APAC Machine Vision Systems Market
Others
North America Printed Signage Market
Others
GCC Shisha Tobacco Market
Others
Automotive Smart Lighting Market
Others
Cremation Furnace Market
Others
Middle East and Africa Surface Analysis Market
Others
Prunes Market
Others
Cashew Kernel Market
Others
Hotel Wardrobe Market
Others
Liquid Density Meters Market
Others
Internet of Things Testing Market
Others
Canada 3D Printing Construction Market
Others
Europe Virtual Reality Gaming Market
Others
Fenoxanil Market
Others
Aircraft Exterior Lighting Market
Others
Global Injectable Nanomedicine Market