
 Cremation Furnace Market | 2026-2036
Cremation Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Cremation Furnace Market Analysis
Refractory ceramic fiber is consolidating its position as the dominant lining material in new furnace builds, displacing traditional brick linings and reducing thermal cycling costs by extending chamber life. Matthews Environmental Solutions leverages in-house refractory production to control input costs across its installed base. The Facultatieve Group anchors its European operations with specialized gas-cleaning integration that meets Dutch and German emission thresholds. Therm-Tec dominates the North American aftermarket through a replacement-parts distribution network spanning U.S. and Canadian service territories.
A cremation furnace is a thermally insulated combustion chamber engineered to sustain temperatures between 760°C and 1150°C, utilizing refractory materials and secondary afterburners to ensure complete combustion of organic matter and particulate destruction. Its primary purpose is to reduce human or animal remains to bone fragments through controlled high-temperature oxidation, with exhaust scrubbing systems mandated for mercury and dioxin abatement. Natural gas technology leads installed capacity due to infrastructure maturity and operational familiarity, while electric technology captures fastest-growing interest where grid decarbonization and renewable energy penetration reshape lifecycle emissions profiles. Eco-friendly furnaces concentrate margin pools as municipalities and corporate funeral operators face Scope 3 reporting obligations and public sustainability scrutiny.
EPA Maximum Achievable Control Technology standards govern mercury capture and particulate limits in the United States, forcing retrofits and accelerating replacement cycles for pre-2010 installations. The European Union F-Gas Regulation and associated Best Available Techniques reference documents constrain fluorinated greenhouse gas use in refrigeration-based mercury recovery systems, redirecting capital toward alternative emission-control architectures. Stakeholders must monitor evolving crematorium siting ordinances in dense urban jurisdictions, as zoning liberalization in Japan and tightening in parts of Germany create divergent deployment pathways.
Market Dynamics
EPA Maximum Achievable Control Technology standards and the European Union F-Gas Regulation are compressing replacement cycles for aging installations while redirecting capital toward emission-control architectures that satisfy mercury capture mandates.
Growth Catalysts
- Cremation rate normalization:Urban density in Japan and Germany accelerates crematorium siting approvals as municipal planners prioritize land-efficient disposition methods over traditional burial.
- Refractory ceramic fiber substitution:The material is displacing traditional brick linings by extending chamber life and reducing thermal cycling maintenance burdens for furnace operators.
- Scope 3 reporting obligations:Corporate funeral operators face sustainability disclosure mandates that favor electric furnace technology where grid decarbonization supports lifecycle emission reductions.
Market Restraints
- Refractory supply concentration:Specialized ceramic fiber production clusters in select manufacturing regions create input cost volatility for furnace builders without captive supply arrangements.
- Grid infrastructure dependency:Electric technology adoption stalls in jurisdictions where utility capacity constraints prevent reliable 1150°C sustained operation.
- Mercury recovery system complexity:The European Union F-Gas Regulation constrains fluorinated greenhouse gas use in refrigeration-based recovery, forcing costly architectural pivots.
Strategic Opportunities
- Aftermarket service unbundling:Independent parts distributors can capture margin pools currently held by original equipment manufacturers across the United States and Canadian service territories.
- Gas-cleaning integration specialization:Dutch and German emission thresholds create demand for bundled furnace-scrubber systems that exceed baseline regulatory floors.
- Renewable-powered electric installations:Grid decarbonization in jurisdictions with high wind and solar penetration enables zero-operational-emission positioning for municipal procurement.
Industry Challenges
- Refractory installation craft scarcity:Specialized chamber lining expertise concentrates with aging technicians, constraining new build and retrofit velocity.
- Multi-jurisdictional certification timelines:Furnace operators face divergent siting ordinances between Japanese zoning liberalization and German tightening that fragment deployment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cremation Furnace Market |
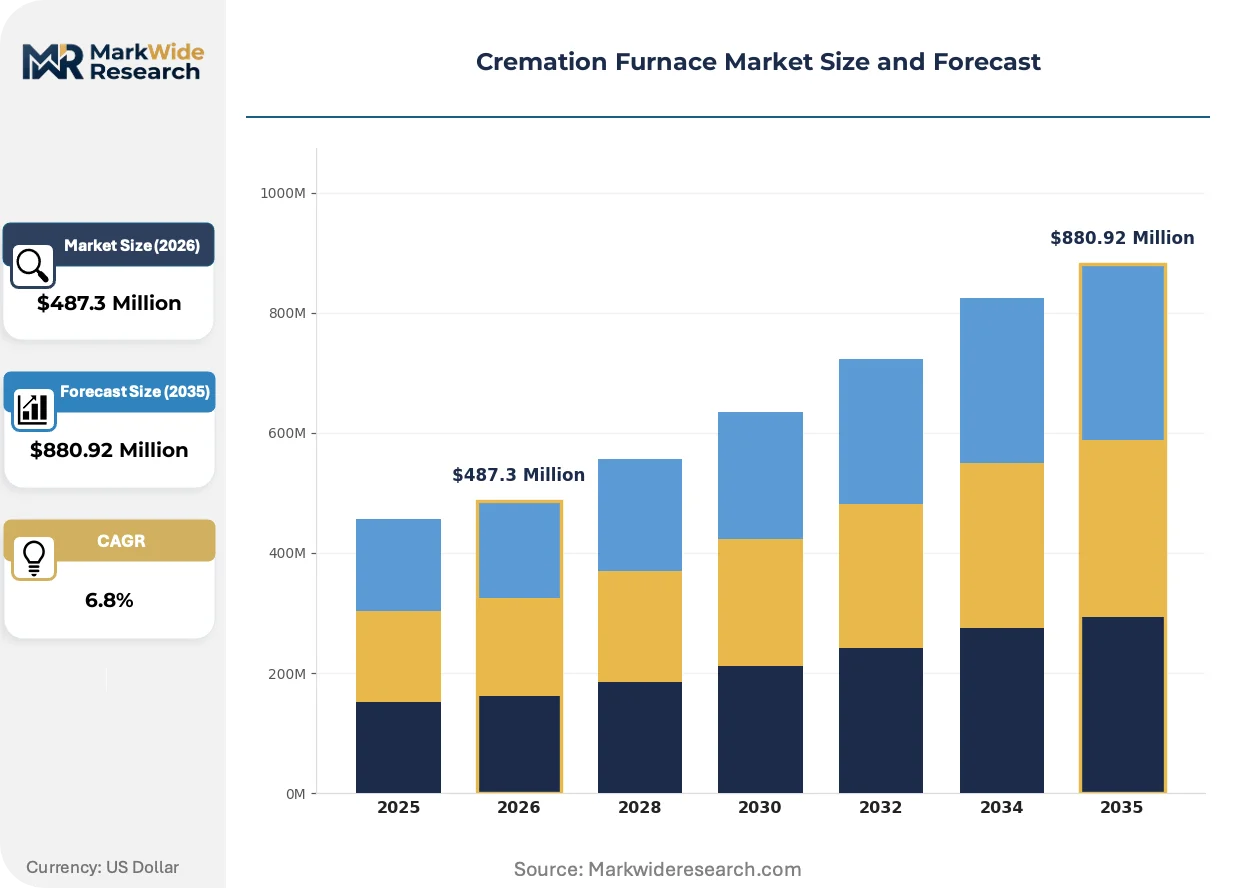
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Furnaces, Mini Furnaces, Mobile Furnaces, Eco-Friendly Furnaces End User: Funeral Homes, Cemeteries, Animal Crematoria, Municipalities Technology: Electric, Natural Gas, LPG, Biomass Installation Type: Fixed, Portable, In-Ground, Above Ground |
| Companies Covered | Therm-Tec, The Facultatieve Group, Matthews Environmental Solutions, National Incinerator Inc, American Incinerators, B&L Cremation Systems, American Crematory Equipment Co., DFW Europe, Armil CFS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cremation Furnace Market Emerging Trajectories
Control systems and emission monitoring architectures are converging to reshape how crematorium operators manage combustion precision and regulatory compliance documentation.
Automated combustion control systems are automating temperature modulation and oxygen trimming to sustain optimal oxidation conditions without manual intervention. Funeral home operators in high-throughput municipal facilities are adopting these systems fastest, driven by labor cost pressures and consistency requirements. The technology is automating operator judgment, compressing training burdens and reducing thermal excursion incidents that damage refractory linings.
The European Union F-Gas Regulation and associated Best Available Techniques reference documents are constraining fluorinated greenhouse gas deployment in mercury recovery refrigeration loops. Equipment suppliers are redirecting research and development toward dry sorbent injection and activated carbon capture architectures that bypass regulated substances. German and Dutch furnace installations face the most acute compliance deadlines, accelerating partnership activity between furnace builders and specialized gas-cleaning integrators.
Service contract unbundling is fragmenting the traditional bundled purchase-maintenance model that dominated North American procurement. Independent distributors are capturing replacement parts volume by offering faster turnaround and localized inventory positioning. This shift concentrates margin pressure on original equipment manufacturers while expanding addressable market access for specialized component suppliers across United States and Canadian territories.
Cremation Furnace Market Segmentation
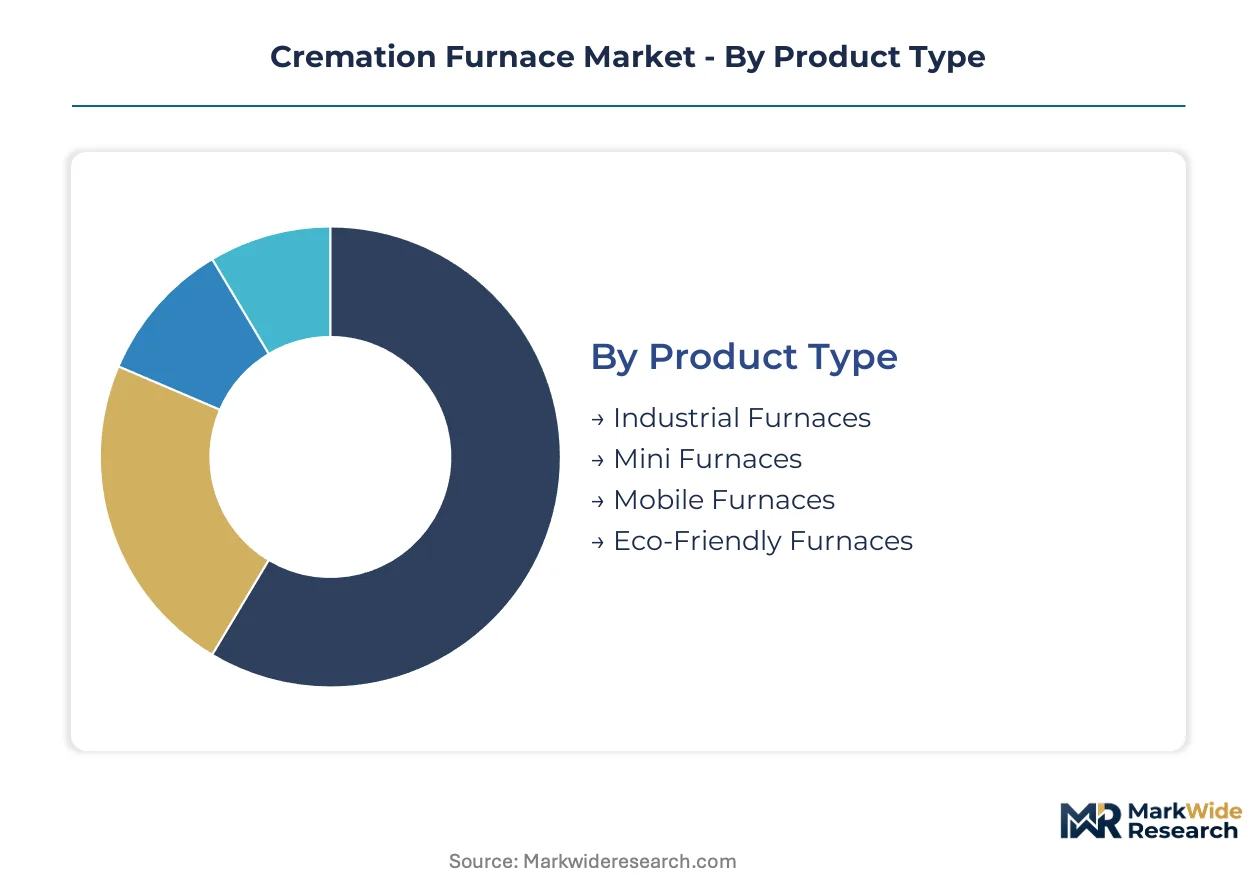
Cremation furnace procurement varies sharply across operator types, with municipal buyers prioritizing emission compliance documentation while funeral homes weigh throughput against footprint constraints. Certification burdens fall unevenly across segments, reshaping vendor qualification requirements and installation timelines.
Product Type:
EPA Maximum Achievable Control Technology standards and EU F-Gas Regulation impose divergent certification pathways—industrial units face stack monitoring mandates, while eco-friendly variants trigger additional lifecycle emissions verification protocols.
- Industrial Furnaces:These units sustain continuous operation at 1150°C with multi-chamber configurations and automated loading systems for high-throughput municipal facilities. Demand concentrates in Germany and Japan where urban density forces centralized crematorium consolidation and regulators mandate mercury capture retrofit deadlines.
- Eco-Friendly Furnaces:Electric and hybrid combustion architectures reduce operational emissions through grid-tied renewable integration and advanced exhaust scrubbing. Municipalities in the Netherlands and select Japanese prefectures prioritize these units for Scope 3 reporting compliance and public sustainability commitments.
- Mini Furnaces:Compact single-retort designs serve low-volume funeral homes and rural cemeteries with limited installation footprints.
- Mobile Furnaces:Trailer-mounted units enable disaster response and temporary deployment where fixed infrastructure is unavailable.
Leading the category by volume: Industrial Furnaces. Growing fastest: Eco-Friendly Furnaces.
End User:
Customer procurement sophistication spans three distinct cost tiers—municipal RFP processes emphasize total cost of ownership, while independent funeral homes prioritize equipment financing flexibility.
- Funeral Homes:Independent and corporate operators drive replacement cycles for aging natural gas installations, with consolidation trends favoring standardized fleet specifications across multi-site operators. United States funeral home chains are unbundling service contracts to reduce captive maintenance costs.
- Municipalities:City and county governments operate high-throughput facilities with dedicated maintenance staff and capital budget cycles tied to election calendars. German municipalities face accelerated replacement deadlines under federal emission threshold reductions.
- Cemeteries:Hybrid burial-cremation operators seek equipment that preserves historical site aesthetics while expanding service revenue.
- Animal Crematoria:Veterinary chains and pet memorial services require smaller retort dimensions with specialized odor control systems.
Funeral homes command the largest installed base. Municipal procurement is climbing the fastest amid infrastructure centralization policies.
Technology:
Technology selection tracks regional grid maturity and pipeline infrastructure density, with electric adoption stalled where utility capacity cannot sustain thermal load profiles.
- Natural Gas:Mature burner technology dominates existing installed capacity across North American funeral homes and German municipal facilities. Operational familiarity and pipeline accessibility sustain preference despite emission control retrofit requirements.
- Electric:Resistance and induction heating architectures eliminate stack emissions at point of use, enabling zero-operational-emission positioning where renewable penetration supports grid decarbonization claims. Japanese utilities in wind-rich prefectures are piloting dedicated industrial rate structures for crematorium loads.
- LPG:Tank-fed systems serve rural and mobile applications beyond natural gas pipeline reach.
- Biomass:Experimental pilot installations explore syngas and pellet combustion for carbon-neutral positioning in Nordic sustainability demonstration projects.
Natural gas retains dominant share. Electric technology is gaining share fastest on lifecycle emission accounting.
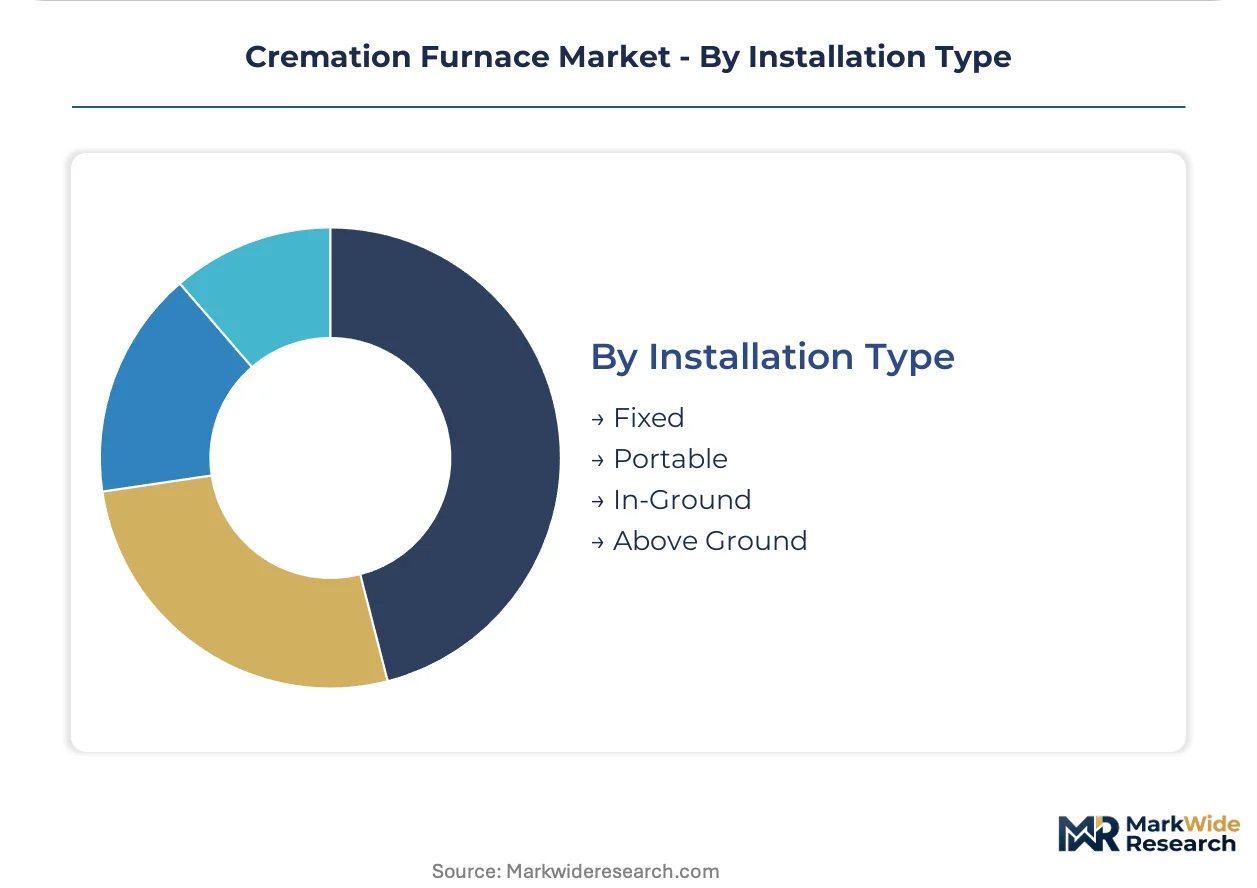
Installation Type:
Physical configuration determines siting flexibility and regulatory jurisdiction, with in-ground installations triggering specialized groundwater protection reviews.
- Fixed:Permanent concrete-pad installations with dedicated stack and emission control infrastructure serve high-throughput municipal and corporate funeral facilities. German zoning tightening is constraining new fixed-site approvals in dense urban districts.
- Above Ground:Modular building-integrated systems reduce construction timelines and enable relocation if zoning conditions shift. Japanese zoning liberalization is accelerating above-ground approvals in Tokyo and Osaka metropolitan areas.
- Portable:Skid-mounted units deploy for disaster response, military operations, and temporary population surges.
- In-Ground:Subsurface chamber designs minimize visual impact for cemetery-adjacent installations with strict aesthetic requirements.
Fixed installations anchor the category by unit count. Above-ground configurations are expanding most quickly on zoning flexibility advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where aging demographics and urban density accelerate crematorium investment. Municipal planners in these markets prioritize land-efficient disposition methods over traditional burial. Regulatory divergence between EPA emissions standards and EU F-Gas Regulation reshapes equipment procurement across jurisdictions.
United States
Funeral home chains drive replacement cycles for aging natural gas installations as cremation rates climb past traditional burial preferences. EPA Maximum Achievable Control Technology standards govern mercury capture and particulate limits, forcing retrofits for pre-2010 installations. Texas and Florida municipal facilities concentrate procurement volume where population growth strains existing crematorium capacity.
Germany
Federal emission threshold reductions compress replacement deadlines for municipal operators in dense urban districts. The EU F-Gas Regulation constrains fluorinated greenhouse gas use in refrigeration-based mercury recovery systems, redirecting capital toward alternative emission-control architectures. North Rhine-Westphalia crematoria face the most acute compliance timelines, accelerating partnership activity between furnace builders and specialized gas-cleaning integrators.
Japan
Tokyo and Osaka metropolitan areas benefit from zoning liberalization that accelerates above-ground crematorium approvals. METI industrial rate structures in wind-rich prefectures pilot dedicated utility pricing for electric furnace loads. Kanto region facilities concentrate investment in grid-tied renewable integration to support zero-operational-emission positioning.
Netherlands
Municipal procurement prioritizes eco-friendly furnace variants for Scope 3 reporting compliance and public sustainability commitments. Dutch emission thresholds exceed baseline EU regulatory floors, creating demand for bundled furnace-scrubber systems. Randstad urban clusters concentrate investment where land scarcity forces centralized crematorium consolidation.
United Kingdom
Crematorium siting ordinances tighten in Greater London while regional municipalities expand capacity to reduce cross-border service dependence. CE marking and associated Best Available Techniques reference documents constrain equipment certification pathways. Southeast England facilities concentrate aftermarket service demand as aging installed base requires replacement parts and refractory maintenance.
Cremation Furnace Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers capturing municipal procurement while independent fabricators serve funeral home replacement cycles. The vendor base organizes around three strategic archetypes: refractory-integrated builders controlling input costs, gas-cleaning specialists bundling emission-control systems, and aftermarket distributors unbundling service contracts. Consolidation pressure concentrates among North American funeral home chains standardizing fleet specifications. Competitive moves center on captive refractory supply arrangements and geographic expansion into Japanese and German compliance-driven replacement cycles.
Within the refractory-integrated tier, Matthews Environmental Solutions represents builders leveraging in-house ceramic fiber production to manage thermal cycling costs. The Facultatieve Group anchors European positioning through specialized gas-cleaning integration that satisfies Dutch and German emission thresholds. Therm-Tec occupies the North American aftermarket vector through replacement-parts distribution spanning United States and Canadian service territories. These three exemplify how competitive positioning tracks regulatory geography rather than product differentiation alone.
| Leading Market Players |
|---|
| Therm-Tec |
| The Facultatieve Group |
| Matthews Environmental Solutions |
| National Incinerator Inc |
| American Incinerators |
| B&L Cremation Systems |
| American Crematory Equipment Co. |
| DFW Europe |
| Armil CFS |
| Others |
Supply Flow & Price Mechanics
Captive refractory production anchors both supply security and pricing power for furnace builders with in-house ceramic fiber capabilities, insulating them from input cost volatility that compresses margins for outsourced competitors. This integration pattern concentrates margin pools with Matthews Environmental Solutions while forcing price competition among distributors dependent on spot refractory markets.
Pricing Analysis
Volume concentrates in industrial furnace tiers while margin pools shift toward eco-friendly electric variants with bundled emission-control architectures. Three-tier pricing structure across premium certified, standard compliant, and economy retrofit levels tracks EPA MACT and EU F-Gas certification burdens. Pricing pressure stems from refractory supply concentration as specialized ceramic fiber production clusters in select manufacturing regions. Municipal buyers exhibit lowest price sensitivity given capital budget cycles and compliance deadlines, while independent funeral homes negotiate aggressively on financing terms and aftermarket service unbundling.
Supply Chain Analysis
CE marking and EPA certification requirements gate supplier qualification, extending procurement timelines for non-integrated builders. Refractory ceramic fiber production concentrates in the United States, Germany, and Japan where technical expertise and emission-control integration capabilities cluster. Supply chains draw from specialized refractory minerals, high-grade steel alloys for chamber fabrication, and mercury recovery system components. Single-source vulnerability runs through European gas-cleaning integrators serving Dutch and German compliance deadlines. Distribution runs through original equipment manufacturer networks and independent aftermarket distributors across North American service territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cremation furnace market sits in a technology-transition phase as electric resistance and induction heating architectures displace legacy natural gas combustion systems in jurisdictions with grid decarbonization momentum.
For Market Incumbents: Acquire specialized gas-cleaning integration capabilities to capture municipal procurement in Germany and the Netherlands where EU F-Gas Regulation deadlines compress replacement cycles. Deepen backward integration into refractory ceramic fiber production to defend margin position against supply cost volatility. Prioritize certification investment for above-ground modular configurations benefiting from Japanese zoning liberalization in Tokyo and Osaka metropolitan areas.
For New Entrants and Emerging Players: Digital aftermarket platforms offer the fastest route to capture unbundled service contract volume across United States and Canadian funeral home chains. Target independent parts distribution white space currently held by original equipment manufacturers through localized inventory positioning and faster turnaround commitments. Pursue partnership-based go-to-market positioning with specialized refractory installation craft providers to overcome technician scarcity constraints.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated environmental solutions conglomerates seeking emission-control technology portfolios. Long-term viability favors builders with captive refractory supply and certified electric product architectures as grid decarbonization reshapes procurement criteria. Watch METI industrial rate structure expansion across Japanese prefectures as the inflection signal for electric technology adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Production | Matthews Environmental Solutions controls input costs across its installed base through captive ceramic fiber manufacturing. |
| Gas-Cleaning System Partnership | The Facultatieve Group anchors European positioning by bundling furnace-scrubber systems exceeding Dutch and German emission thresholds. |
| Aftermarket Distribution Expansion | Therm-Tec captures replacement parts margin pools across United States and Canadian service territories through localized inventory. |
| Electric Technology Certification Investment | Municipal procurement in wind-rich Japanese prefectures prioritizes zero-operational-emission positioning for Scope 3 compliance. |
| Above-Ground Modular Configuration Development | Tokyo and Osaka zoning liberalization accelerates approvals for building-integrated systems with relocation flexibility. |
Methodological Framework
Trade association filings, customs and import records, and regulatory submission databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with crematorium operators, furnace maintenance directors, municipal procurement officers, and refractory installation technicians combined with secondary validation to triangulate demand patterns. Bottom-up unit economics and top-down sector expenditure analysis converged on volume and value estimates across the analysis window.
Historical trendline analysis of cremation rate trajectories, replacement cycle timing, and regulatory compliance deadlines informed the projection framework. Segmentation modeling incorporated product type, end-user archetype, technology platform, and installation configuration dimensions across the projection horizon. CAGRs derived from fitted growth curves adjusted for EPA MACT retrofit deadlines and EU F-Gas Regulation phase-out timelines. Forecast inputs included utility rate structure evolution, zoning ordinance changes, and refractory supply capacity expansion.
The model holds under stable regulatory enforcement timelines and grid infrastructure investment continuity; deviation in emission threshold acceleration or utility capacity constraints would shift technology adoption trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sunflower Husk Pellets Market
Others
Football Sportswear Market
Others
Global Pregnancy Tracker Apps Market
Others
Biopharma Plastics Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Signal Transformer Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
US Tablet Market
Others
Voice Controlled Devices Market
Others
Printing Machines Market
Others
North America Industrial Wearable Devices Market
Others
Mobile Retina Services Market
Others
Gesture Recognition for Smart TV Market
Others
Global Smart Home Installation Service Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Japan 3D Printing Construction Market