
 Prunes Market | 2026-2036
Prunes Market Size, Share, and Industry Trends Forecast 2026-2036
Prunes Market Analytics
California is tilting global prune supply through sustained orchard investment and processing infrastructure expansion. Sunsweet Growers leverages integrated packing and marketing operations across the Sacramento Valley. Mariani Packing Company anchors its position through multi-generational farming relationships and controlled-atmosphere storage networks. Le Prunier differentiates via organic certification and direct-to-retailer channel control in European markets.
Prunes are dried plums, typically from Prunus domestica cultivars, processed to moisture levels between 15% and 20% through hot-air dehydration or natural sun-drying methods that preserve sorbitol and dietary fiber content for digestive health applications and natural sweetening in food manufacturing. The dried product category dominates volume throughput due to established industrial baking demand, while organic grades command margin premiums as clean-label formulations expand across European and North American retail channels. Online retail distribution is accelerating fastest among channels, though supermarkets still occupy the largest revenue pool through private-label and branded shelf-stable placements.
The USDA grades prune shipments through its Agricultural Marketing Service, enforcing size and defect standards that determine export eligibility and price tiering. EFSA maximum residue limits for dried fruits shape EU import compliance costs and supplier qualification thresholds for non-European exporters. Stakeholders must monitor evolving organic equivalency agreements between the USDA National Organic Program and third-country certifiers, as these bilateral frameworks determine market access breadth for premium-grade suppliers without triggering redundant audit burdens.
Market Dynamics
California's Central Valley dominates prune production through consolidated orchard ownership and captive dehydration infrastructure, creating supply-side leverage that propagates through global pricing tiers and shapes procurement strategies for European nutraceutical formulators.
Growth Catalysts
- EFSA contaminant limit tightening:The EU's updated maximum residue limits for dried fruits are accelerating supplier consolidation as smaller exporters face disqualification costs, concentrating qualified volume with integrated California packers.
- Functional food formulation:Nutraceutical manufacturers are expanding prune powder and concentrate procurement for digestive health positioning in clean-label snack bars and beverage applications.
- Sorbitol preservation standards:Hot-air dehydration technology with controlled moisture targeting is enabling consistent 15-20% moisture grades that meet industrial baking specifications for natural sweetening substitution.
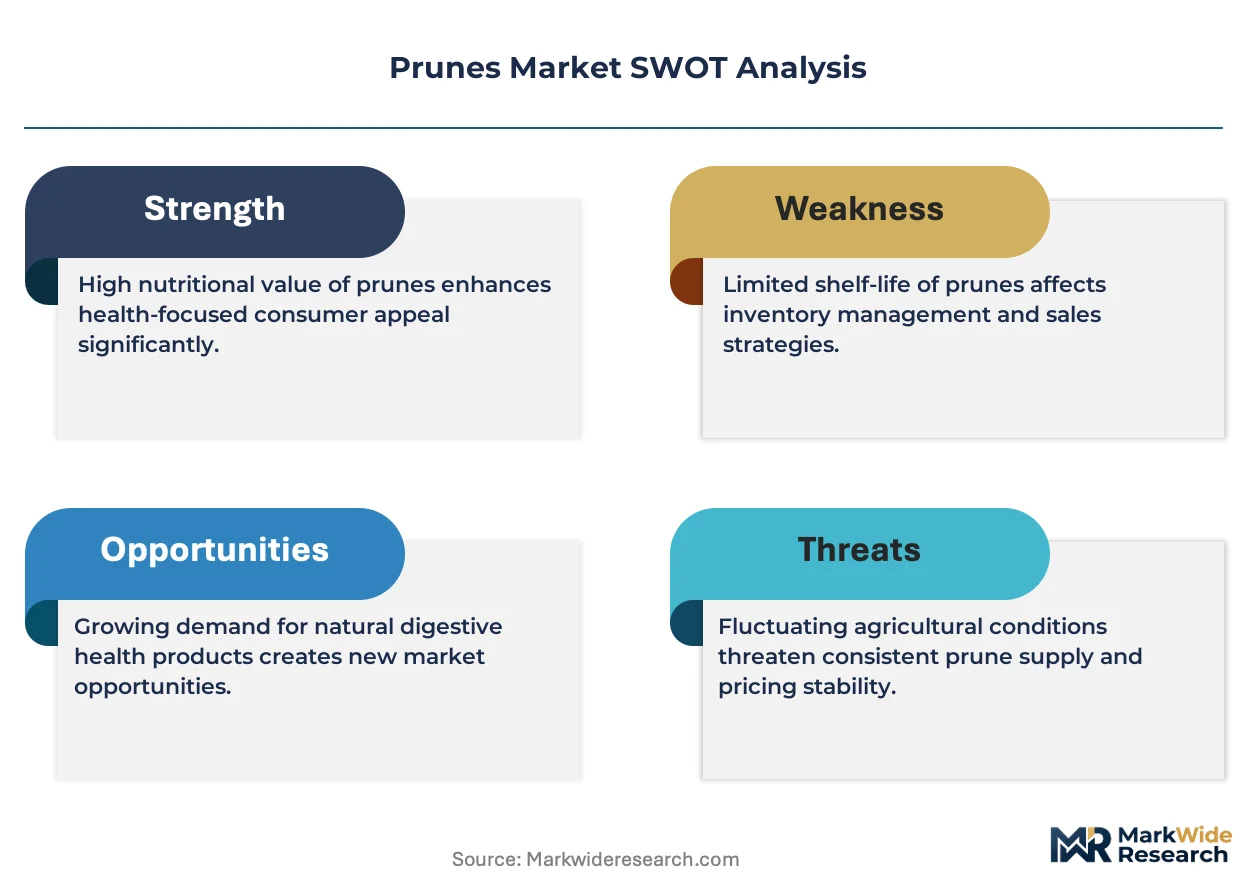
Market Restraints
- Single-orchard geography risk:California's Sacramento and San Joaquin valleys account for the majority of global prune supply, exposing buyers to drought, frost, and labor availability shocks without geographic diversification.
- Natural sugar substitute competition:Monk fruit extract and allulose are capturing clean-label sweetening share in bakery applications, compressing prune concentrate volume growth in industrial segments.
- Organic certification cost inflation:USDA National Organic Program compliance and third-country equivalency audits are raising entry barriers for new suppliers seeking premium-grade positioning.
Strategic Opportunities
- Direct-to-retailer channel expansion:Controlled-atmosphere storage investments enable bypass of traditional wholesale layers, capturing margin through private-label and branded shelf-stable placements with European supermarket chains.
- Digestive health clinical substantiation:Expanding peer-reviewed research on prune fiber and phenolic compounds supports health claim petitions with EFSA and FDA, opening fortified food and medical nutrition applications.
- Controlled fermentation processing:Emerging biotechnology applications for prune-derived prebiotic substrates are creating white space in synbiotic supplement formulations targeting gut microbiome modulation.
Industry Challenges
- Skilled dehydration technician scarcity:Hot-air tunnel operation and moisture monitoring require specialized expertise that is aging out of the Central Valley workforce without sufficient apprenticeship pipeline replacement.
- Legacy equipment integration friction:Orchard-to-packer traceability systems for EFSA compliance must interface with decades-old grading and packing infrastructure, delaying real-time data capture deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prunes Market |
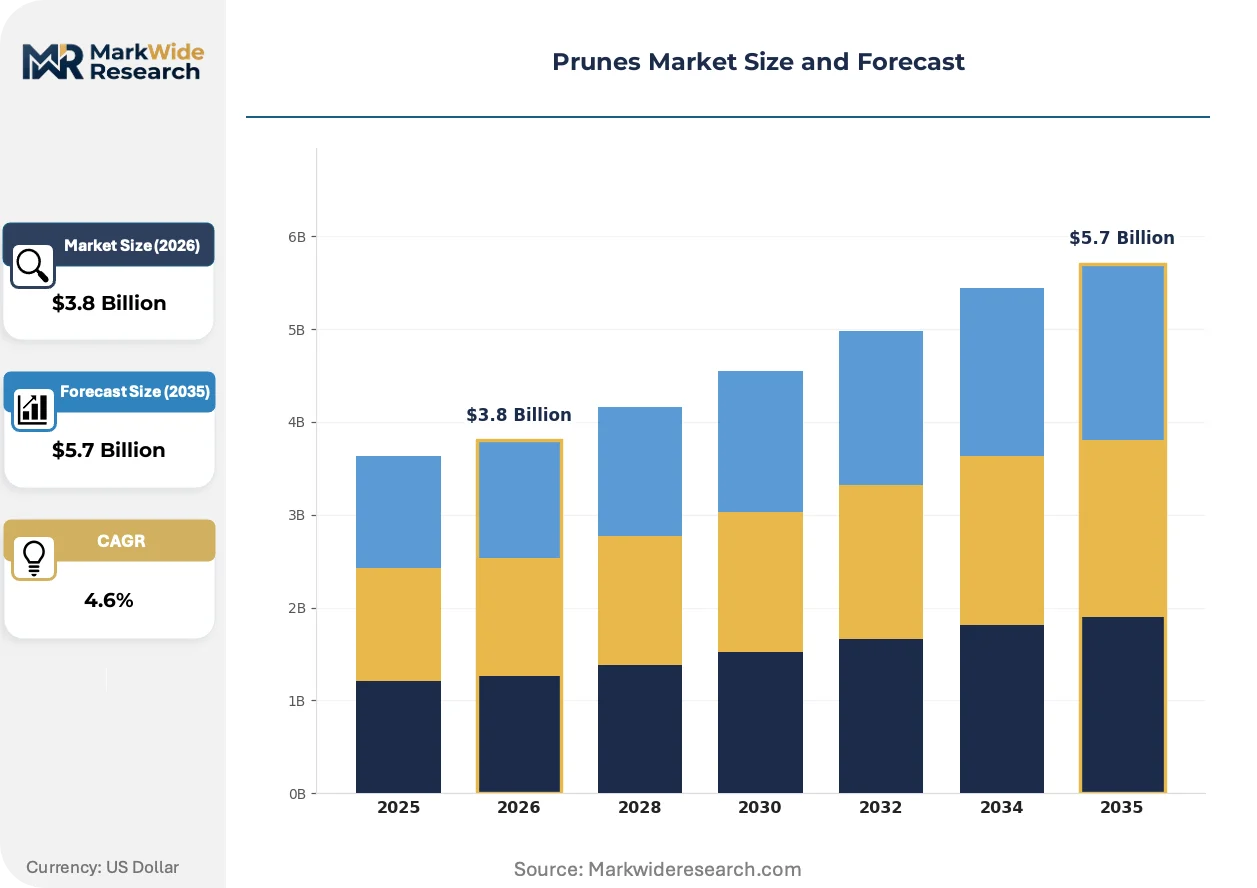
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried, Organic, Conventional, Pitted Grade: USDA Grade A, Grade B, Extra Fancy, Fancy Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale End Use: Baking, Snacking, Cereal, Beverage |
| Companies Covered | California Prune Board, Celina Prunes, Taylor Brothers Farms, National Prune Cooperative, Dried Fruit and Nut Company, Sunsweet Growers, Frutera, Le Prunier, Mariani Packing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prunes Market Evolving Landscape
Processing technology and regulatory architecture are compressing traditional supply tiers while channel disintermediation rewards integrated operators with direct retail relationships and traceable provenance credentials.
Controlled-atmosphere storage with nitrogen flushing and temperature modulation is rendering obsolete conventional cold storage dependency for year-round supply stability. European retail chains and North American private-label programs are adopting this infrastructure at accelerated capex cycles. The technology is compressing seasonal price volatility and enabling just-in-time contract structures that displace speculative inventory positions.
REACH substance registration requirements and EFSA contaminant monitoring protocols are tightening import documentation burdens for non-European dried fruit suppliers. Industrial buyers are responding by consolidating qualified supplier lists and demanding third-party laboratory certification at origin. California integrated packers with in-house testing capacity are capturing disproportionate share of EU food manufacturing procurement.
Clean-label procurement teams at multinational bakery and snack manufacturers are substituting prune concentrate for refined sugar and artificial sweeteners in formulation pipelines. This specification shift is most visible in German and Dutch industrial baking clusters, where reformulation mandates from retail chain sustainability commitments are accelerating ingredient substitution timelines. Direct supplier relationships are displacing traditional ingredient distributor intermediaries in these procurement workflows.
Prunes Market Segmentation
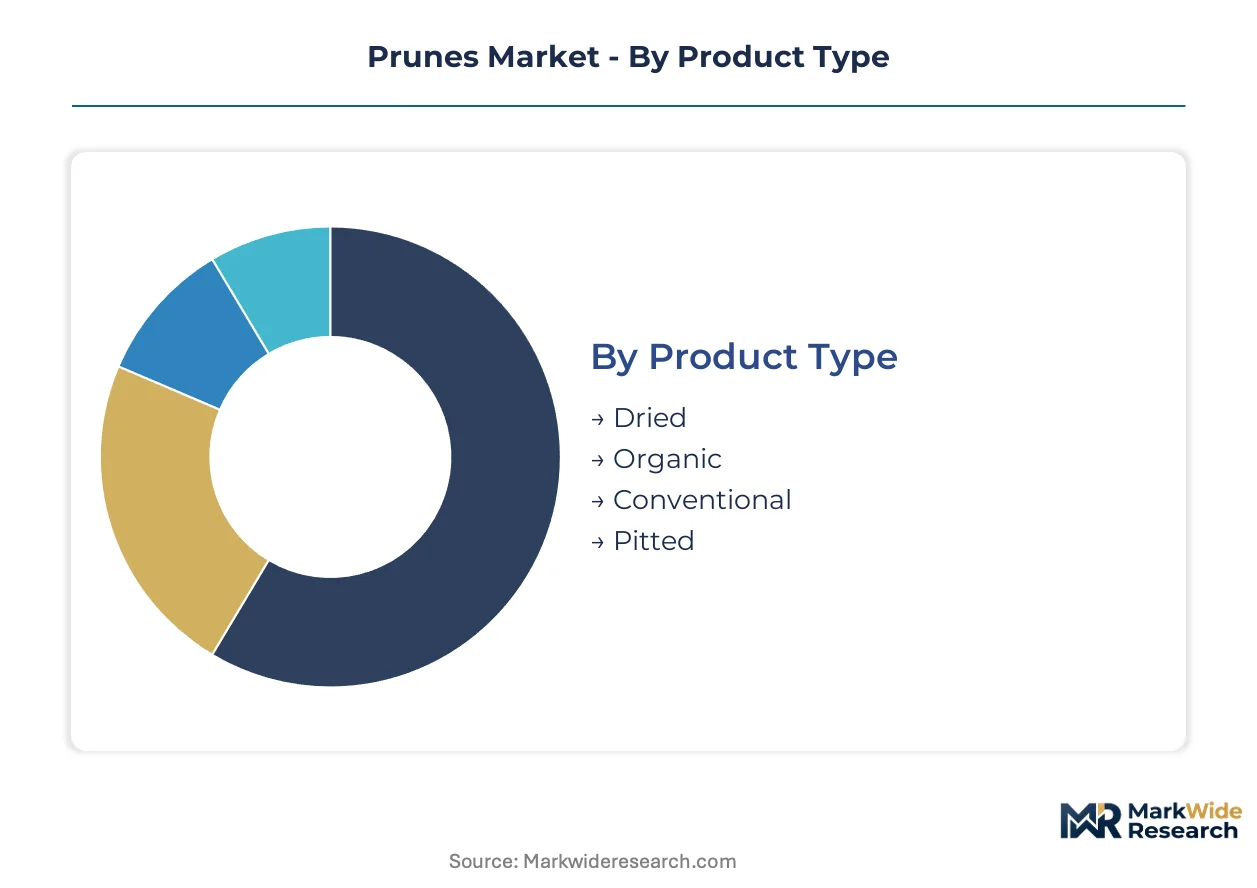
Prune procurement strategies diverge sharply across product specifications and channel structures. Industrial buyers prioritize moisture consistency and defect thresholds for baking applications, while retail-facing segments emphasize organic certification and direct-to-consumer logistics infrastructure.
Product Type:
After-sales service intensity varies dramatically across product categories, with organic and pitted formats requiring specialized cold-chain handling and certification documentation support that conventional dried grades do not demand.
- Dried:Hot-air dehydrated to 15-20% moisture with sorbitol preservation for industrial baking specifications. California packers dominate throughput for German and Dutch industrial clusters reformulating around natural sweetening mandates.
- Organic:USDA National Organic Program certified with third-country equivalency documentation for EFSA compliance. Premium positioning accelerates in European retail channels where clean-label procurement teams bypass conventional wholesale layers.
- Conventional:Standard orchard grades without certification premiums serve volume-driven private-label supermarket programs.
- Pitted:Mechanical stone removal enables ready-to-eat snacking applications with controlled-atmosphere packaging requirements.
Dried holds the largest share; momentum sits with organic.
Grade:
Cost tier stratification determines export eligibility and price realization, with premium grades capturing disproportionate margin in direct-retail channel structures while standard grades flow through consolidated wholesale networks.
- USDA Grade A:Maximum 5% defects by count with uniform size distribution for retail shelf-stable placement. EFSA contaminant limit tightening concentrates qualified volume with integrated California packers possessing in-house testing capacity.
- USDA Grade B:Permits 10% defects for food manufacturing ingredient applications where visual uniformity matters less than fiber and sugar content consistency.
- Extra Fancy:Premium sizing and color specifications command private-label positioning with European supermarket chains.
- Fancy:Mid-tier grade bridges retail and industrial segments with flexible packaging specifications.
USDA Grade A commands the revenue pool; Grade B climbs fastest on industrial reformulation demand.
Distribution Channel:
Volume concentration shapes infrastructure investment patterns, with supermarket procurement consolidating around year-round supply guarantees while online retail demands fractional fulfillment capabilities that legacy packers struggle to provision.
- Online Retail:Direct-to-consumer fulfillment with nitrogen-flushed portion packaging. Channel expansion accelerates fastest as clean-label snack subscription services bypass traditional wholesale markups.
- Supermarkets:Private-label and branded shelf-stable placements still occupy the largest revenue pool through centralized procurement and controlled-atmosphere storage contracts.
- Health Food Stores:Specialty retail with organic certification verification and small-batch sourcing relationships.
- Wholesale:Industrial ingredient distribution to bakery and cereal manufacturers with bulk tote specifications.
Supermarkets anchor volume; online retail gains share fastest on direct-channel margin capture.
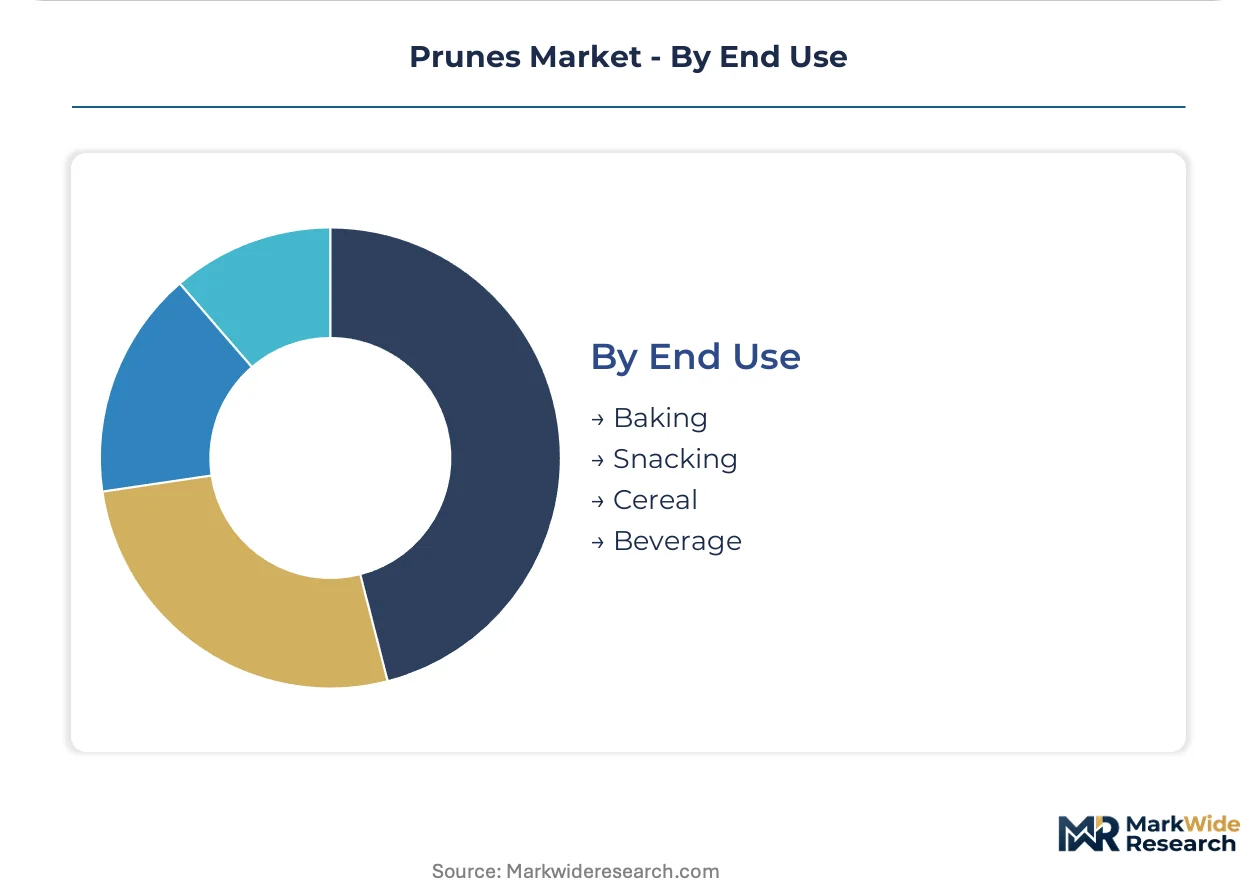
End Use:
Application maturity determines specification rigidity, with baking maintaining entrenched moisture and defect standards while beverage applications experiment with concentrate formats that challenge traditional grading frameworks.
- Baking:Industrial procurement with precise moisture targeting for natural sweetening substitution in German reformulation pipelines. REACH substance registration and EFSA documentation burdens consolidate qualified supplier lists around California integrated packers.
- Snacking:Ready-to-eat pitted formats with convenience packaging for North American retail channels.
- Cereal:Diced and extruded applications requiring low-water-activity specifications for extended shelf stability.
- Beverage:Concentrate and puree formats for functional drink formulations targeting digestive health positioning.
Baking retains the largest application share; beverage expands most quickly on nutraceutical formulation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley holds overwhelming prune production dominance through consolidated orchard ownership and captive dehydration infrastructure, creating supply-side leverage that propagates through global pricing tiers. This geographic concentration shapes procurement strategies for European nutraceutical formulators and Asian food manufacturers alike.
United States
Sunsweet Growers and Mariani Packing Company anchor processing capacity across the Sacramento and San Joaquin valleys. USDA Agricultural Marketing Service grading standards enforce size and defect thresholds that determine export eligibility and price tiering. Yuba City and surrounding Sutter County municipalities concentrate hot-air tunnel dehydration facilities with controlled moisture targeting for industrial baking specifications.
France
Le Prunier commands organic certification premiums through direct-to-retailer channel control in European markets. EFSA maximum residue limits for dried fruits shape import compliance costs and supplier qualification thresholds for non-European exporters. The Aquitaine region maintains traditional prune cultivation around Agen, though volume remains fractional against California throughput.
Germany
Industrial baking clusters in North Rhine-Westphalia and Bavaria drive reformulation demand around natural sweetening substitution. REACH substance registration requirements tighten import documentation burdens for dried fruit suppliers. Cologne and Munich metropolitan procurement teams consolidate qualified supplier lists around California integrated packers with in-house testing capacity.
Netherlands
Rotterdam port infrastructure handles transshipment volume for German and Belgian food manufacturing demand. EFSA contaminant monitoring protocols accelerate supplier consolidation as smaller exporters face disqualification costs. The Randstad logistics corridor enables just-in-time contract structures that displace speculative inventory positions for European retail chains.
Japan
Functional food manufacturers expand prune powder procurement for digestive health positioning in clean-label applications. METI standards on food additive specifications influence import acceptance criteria for concentrate and puree formats. Tokyo and Osaka metropolitan markets concentrate demand for pitted ready-to-eat snacking formats with controlled-atmosphere packaging requirements.
Prunes Market Competitive Landscape
Vertically integrated packers and specialty organic operators split the market through divergent channel strategies and certification positioning. Consolidated orchard ownership in California creates supply-side leverage that propagates through global pricing tiers. Three archetypes dominate: integrated valley packers with captive dehydration infrastructure, multi-generational family operators with controlled-atmosphere storage networks, and organic-certified specialists with direct European retail relationships. Competitive moves center on backward integration into orchard assets and bypass of traditional wholesale layers through supermarket direct contracts.
Among Central Valley-integrated operators, Sunsweet Growers exemplifies the scale-driven archetype through Sacramento Valley packing and marketing consolidation. Mariani Packing Company represents multi-generational farming relationship models with established controlled-atmosphere infrastructure. Le Prunier occupies the organic-specialist position with European channel control and certification-premium capture. These three anchors illustrate the strategic divergence between volume throughput and margin-focused positioning in prune procurement.
| Leading Market Players |
|---|
| California Prune Board |
| Celina Prunes |
| Taylor Brothers Farms |
| National Prune Cooperative |
| Dried Fruit and Nut Company |
| Sunsweet Growers |
| Frutera |
| Le Prunier |
| Mariani Packing Company |
| Others |
Value Network & Pricing Analysis
California's Central Valley orchard consolidation concentrates upstream supply control, directing margin capture toward integrated packers with captive dehydration infrastructure and downstream channel command in European retail procurement.
Pricing Analysis
EFSA maximum residue limits dictate the pricing tier structure for dried fruit imports into European markets. Three-tier pricing structure across premium organic, standard certified, and economy conventional grades separates suppliers by testing capacity and certification documentation depth. Cost compression in standard grades is intensifying because smaller exporters face disqualification from tightened contaminant thresholds. Industrial baking procurement teams in Germany and the Netherlands show highest price sensitivity, while organic-certified direct-to-retailer contracts with French supermarket chains exhibit lowest elasticity.
Supply Chain Analysis
Extended payment terms from European retail chains are reshaping working capital requirements for California packers. Supply draws from California, France, and Chile for dried plum throughput. Raw material inputs center on Prunus domestica cultivars, natural gas for hot-air tunnel operation, and nitrogen for controlled-atmosphere packaging. Single-orchard geography risk in California's Sacramento and San Joaquin valleys exposes buyers to drought and labor availability shocks. Distribution runs through Rotterdam port infrastructure for German and Belgian food manufacturing demand, with direct-to-retailer contracts displacing wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prunes market represents an early-cycle expansion story as functional food manufacturers accelerate prune powder and concentrate procurement for digestive health positioning in clean-label applications.
For Market Incumbents: Build regulatory compliance moats through in-house EFSA testing capacity and USDA National Organic Program certification infrastructure. Consolidate qualified supplier status with German and Dutch industrial baking clusters reformulating around natural sweetening mandates. Defend against monk fruit extract and allulose substitution threats by deepening clinical substantiation for prune fiber health claims.
For New Entrants and Emerging Players: Build out organic certification capabilities with third-country equivalency documentation for European market access. Target beverage concentrate applications where nutraceutical formulation trends create white space outside established industrial baking procurement relationships. Pursue direct-to-retailer channel structures with nitrogen-flushed portion packaging for online retail subscription services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-atmosphere storage infrastructure as European retail chains accelerate capex cycles for year-round supply stability. Long-term viability favors integrated valley packers with backward integration into orchard assets and captive dehydration capacity. Watch for inflection signals in organic equivalency agreement negotiations between USDA and third-country certifiers that would expand premium-grade market access breadth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive supply of Prunus domestica cultivars secures volume throughput for EFSA-compliant export eligibility. |
| Controlled-Atmosphere Storage Expansion | Nitrogen-flushed infrastructure enables just-in-time contracts with Rotterdam-port-dependent European retail chains. |
| Direct-to-Retailer Channel Development | Bypassing wholesale layers captures margin through private-label placements with German supermarket procurement teams. |
| Organic Certification Investment | USDA National Organic Program compliance with third-country equivalency opens premium positioning in French retail channels. |
| Clinical Research Partnership | Peer-reviewed substantiation of prune fiber benefits supports EFSA health claim petitions for medical nutrition applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and secondary validation across published sources. Primary fieldwork engaged dehydration facility managers at Central Valley packers, procurement leads at German industrial baking clusters, regulatory affairs specialists navigating EFSA contaminant protocols, and category buyers at French supermarket chains. Secondary sources included USDA Agricultural Marketing Service grading standards, EFSA maximum residue limit documentation, REACH substance registration requirements, customs and trade flow data, and SEC filings from integrated food manufacturing companies. Bottom-up volume modeling triangulated against top-down market sizing across product type, grade, distribution channel, and end use segmentation.
Forecast inputs considered orchard yield assumptions, dehydration capacity utilization rates, and channel shift trajectories across the projection horizon. Segmentation dimensions modeled include product format, certification tier, distribution structure, and application maturity. CAGRs derived from regression analysis against historical volume trends and forward-looking procurement intent signals from nutraceutical formulators. Industry-specific inputs encompassed EFSA regulatory timeline probabilities and organic equivalency agreement negotiation status between USDA and third-country certifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by monk fruit extract suppliers or allulose producers would shift outcomes. Macroeconomic deviation in agricultural labor availability, regulatory acceleration in contaminant limits, or breakthroughs in prebiotic fermentation processing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Air Separation Module Kit Market
Others
Badminton Apparel Market
Others
Europe Military 4D Printing Market
Others
Egg Market
Others
India Home Automation Market
Others
Digital Transformation of Maritime Freight Market
Others
Smart Doorbell Market
Others
Radar Speed Signs Market
Others
Global Magnetic Flow Meters Market
Others
Agitation System Market
Others
Roasted Wheat Market
Others
Europe Street Lighting Market
Others
Textile Composites Market
Others
Wearable Translator Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Performance Testing Tools Market