
 Middle East and Africa Surface Analysis Market | 2026-2036
Middle East and Africa Surface Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surface Analysis Market Foresight
Buyer concentration among aerospace component manufacturers is consolidating across the Gulf Cooperation Council states. Thermo Fisher Scientific Inc leverages its regional distribution network to sustain instrument availability in Dubai and Riyadh. Bruker Corporation anchors its position through specialized X-ray photoelectron spectroscopy systems calibrated for high-temperature alloy analysis. JEOL Ltd competes by extending electron microscopy capabilities tailored to semiconductor wafer inspection demands from Abu Dhabi-based fabs.
Surface analysis encompasses the characterization of material topographies, chemical compositions, and mechanical properties at interfaces ranging from nanometer-scale thin films to micrometer-level coatings, employing techniques such as secondary ion mass spectrometry with detection limits below one part per million. Its primary purpose is to validate adhesion strength, corrosion resistance, and functional performance across manufactured components subjected to extreme thermal or mechanical stress. Coating Solutions currently dominates product-type revenue as oil and gas operators specify thicker protective layers for downhole equipment. Nanotechnology within the technology dimension represents the fastest-expanding segment, driven by graphene-based anti-corrosive formulations requested by Saudi Aramco suppliers. Electroplating retains mature, price-competitive positioning for automotive parts applications across Morocco and Egypt.
Saudi Food and Drug Authority (SFDA) equipment registration requirements and UAE Ministry of Health and Prevention (MOHAP) quality certifications shape instrument import protocols and service-level obligations for foreign vendors. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces coating performance standards on mining and construction machinery sold domestically. Stakeholders must monitor evolving local-content thresholds in Gulf state procurement frameworks and calibrate partnership strategies with accredited regional service providers accordingly.
Market Dynamics
Aerospace component manufacturers across the Gulf Cooperation Council are consolidating procurement power, forcing instrument vendors to localize service capabilities and recalibrate pricing structures around long-term coating validation contracts rather than equipment sales alone.
Growth Catalysts
- Turbine blade thermal barrier coatings:Saudi Arabian and UAE aerospace suppliers require X-ray photoelectron spectroscopy validation for high-temperature alloy performance, creating sustained instrument demand.
- SFDA equipment registration protocols:Saudi Food and Drug Authority mandates for analytical instrument traceability compel foreign vendors to establish accredited regional calibration facilities.
- Graphene-based anti-corrosive formulations:Nanotechnology adoption for downhole equipment protection in Saudi Aramco's supplier network accelerates secondary ion mass spectrometry deployment.
Market Restraints
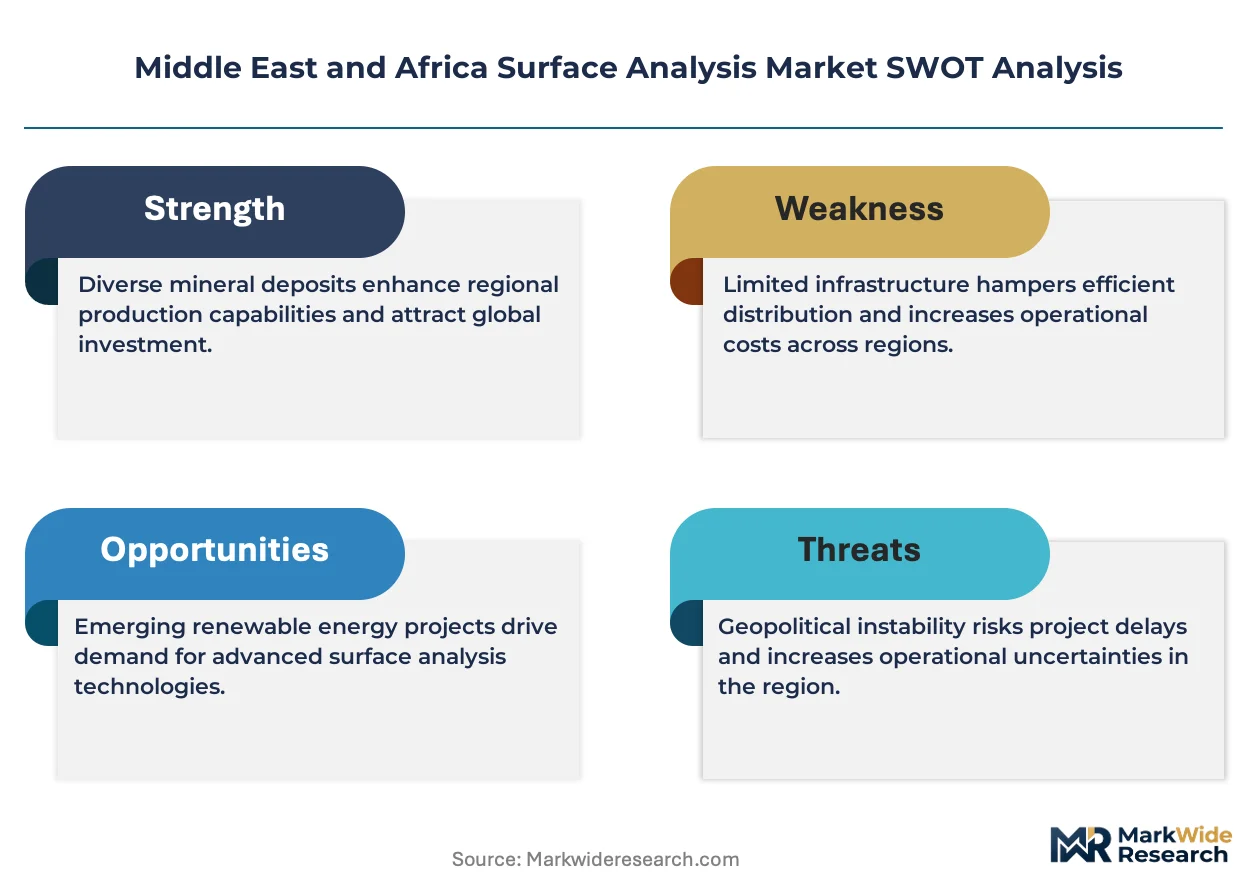
- Helium supply concentration:Regional dependence on Qatari helium for cryogenic electron microscopy systems creates input cost volatility and allocation risk during supply disruptions.
- Technical limitation in high-temperature in-situ analysis:Current XPS systems cannot characterize coatings above 800°C under operational pressure conditions, constraining real-time process monitoring.
- Substitution threat from computational materials modeling:Finite element analysis software for coating lifetime prediction reduces physical testing frequency among cost-sensitive Moroccan automotive parts manufacturers.
Strategic Opportunities
- Underpenetrated Egyptian market:Cairo-based automotive electroplating facilities lack access to localized Auger electron spectroscopy services, creating white space for mobile analytical units.
- UAE Ministry of Health and Prevention quality certifications:MOHAP's expanding scope for medical device surface biocompatibility testing mandates creates regulatory tailwind for secondary ion mass spectrometry providers.
- Technology convergence of Raman spectroscopy with atomic force microscopy:Combined chemical-mechanical mapping systems address semiconductor wafer inspection demands from Abu Dhabi fabrication facilities.
Industry Challenges
- Surface analysis physicist shortage:Gulf universities produce insufficient graduates trained in ultra-high vacuum system maintenance and spectral interpretation, forcing vendors to import technicians on renewable visas.
- NRCS certification timeline compression:South Africa's National Regulator for Compulsory Specifications requires 18-month coating performance validation cycles that delay mining equipment market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surface Analysis Market |
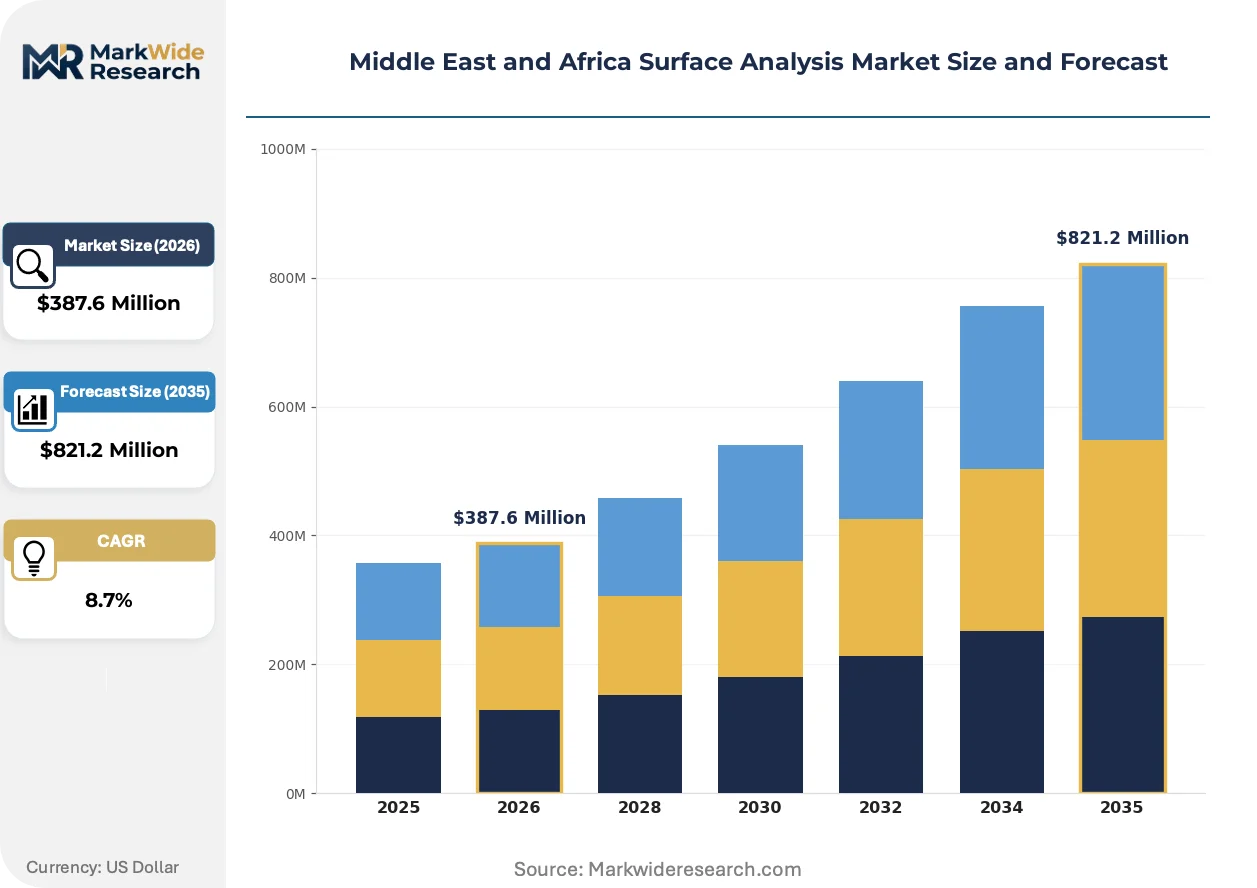
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coating Solutions, Surface Modifiers, Treatments, Adhesives Application: Automotive Parts, Electronics, Aerospace Components, Industrial Machinery End User: Manufacturers, Construction Firms, Technology Companies, Energy Sector Technology: Nanotechnology, Chemical Vapor Deposition, Plasma Treatment, Electroplating |
| Companies Covered | Shimadzu Corporation, Thermo Fisher Scientific Inc, Bruker Corporation, HORIBA Group, JEOL Ltd, Physical Electronics, Inc., Eurofins Scientific, Agilent Technologies, Inc., Oxford Instruments plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surface Analysis Market Shifts & Advancements
Instrument architectures are fragmenting between centralized laboratory systems and distributed field-deployable units, while regulatory mandates for local content and data sovereignty reshape vendor business models across the Middle East and Africa.
Time-of-flight secondary ion mass spectrometry is converging with machine learning-based spectral deconvolution to automate coating defect identification in real time. Saudi Aramco suppliers are adopting these integrated systems for pipeline corrosion monitoring. The technology is converging with predictive maintenance platforms, compressing the traditional separation between quality control laboratories and operational field teams.
South Africa's National Regulator for Compulsory Specifications is enforcing coating performance standards on mining and construction machinery sold domestically. Equipment importers must demonstrate surface treatment durability through accredited third-party analysis. Mining OEMs operating in Gauteng and the Northern Cape are responding by embedding surface analysis capabilities within their in-house metallurgical laboratories.
Service unbundling is separating hardware ownership from analytical output contracts. Oil and gas operators in the UAE now specify coating validation deliverables rather than instrument procurement, with vendors retaining equipment ownership. This model concentrates in Dubai's free trade zones where foreign vendors maintain operational control without local equity requirements.
Middle East and Africa Surface Analysis Market Segmentation
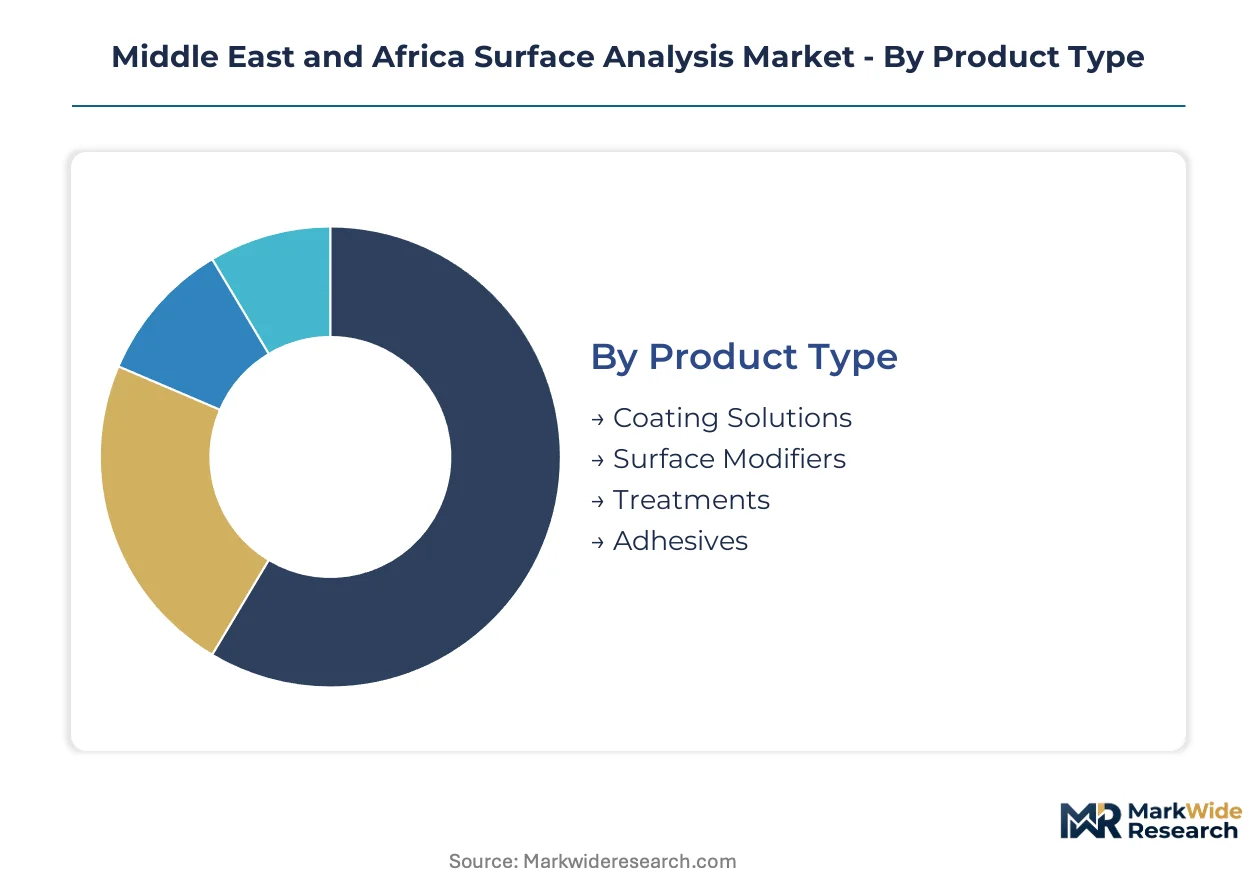
Surface analysis procurement patterns diverge sharply across the Middle East and Africa based on whether buyers prioritize coating validation for extreme environments or routine quality assurance for mass production. Segmentation reveals how aerospace suppliers in the Gulf, mining operators in South Africa, and automotive electroplaters in North Africa allocate analytical budgets across fundamentally different technology platforms.
Product Type:
Cost tier separates buyers seeking commodity-grade surface treatments from those requiring precision-engineered coating architectures.
- Coating Solutions:Multi-layer protective systems combining ceramic-metal matrices for thermal barrier and corrosion resistance applications. Oil and gas operators in Saudi Arabia and the UAE specify thicker protective layers for downhole equipment, driving sustained demand for validation of adhesion strength and wear performance under high-pressure hydrogen sulfide environments.
- Surface Modifiers:Functionalization chemistries that alter interfacial energy, wettability, or biocompatibility without adding substantial material thickness. Medical device manufacturers serving MOHAP-certified facilities in Dubai require surface modifier validation for implantable device biocompatibility, creating specialized demand for X-ray photoelectron spectroscopy protocols.
- Treatments:Thermal and mechanical processes including shot peening, laser glazing, and ion implantation that modify substrate properties directly.
- Adhesives:Structural bonding agents requiring surface pretreatment validation to ensure interfacial strength in composite assemblies.
Coating Solutions leads volumes today; Surface Modifiers is gaining share fastest.
Application:
Volume concentration tracks the capital intensity of end-use manufacturing bases across the region's industrial clusters.
- Aerospace Components:Turbine blades, engine casings, and airframe structures subjected to thermal cycling and oxidative degradation. Saudi Arabian and UAE aerospace suppliers require X-ray photoelectron spectroscopy validation for high-temperature alloy performance, with SFDA-aligned traceability mandates compeling instrument vendors to maintain accredited regional calibration facilities.
- Automotive Parts:Powertrain components, body panels, and electrical connectors requiring corrosion protection and decorative finishing. Moroccan and Egyptian electroplating facilities lack localized Auger electron spectroscopy access, constraining quality assurance for export-bound parts destined for European OEM supply chains.
- Electronics:Semiconductor wafers, printed circuit boards, and connector systems demanding nanometer-scale contamination control.
- Industrial Machinery:Mining equipment, construction implements, and process vessels requiring wear-resistant surface architectures.
Aerospace Components commands premium pricing; Automotive Parts shows steepest expansion trajectory.
End User:
Customer type determines whether surface analysis is performed in-house through captive laboratories or outsourced to third-party service providers.
- Energy Sector:Oil and gas operators, petrochemical producers, and renewable energy developers requiring corrosion monitoring and coating lifetime prediction. Saudi Aramco suppliers are adopting time-of-flight secondary ion mass spectrometry integrated with machine learning for pipeline corrosion monitoring, compressing traditional boundaries between quality control laboratories and field operations.
- Manufacturers:Discrete goods producers across automotive, consumer products, and capital equipment categories. Mining OEMs in Gauteng and South Africa's Northern Cape are embedding surface analysis capabilities within in-house metallurgical laboratories to satisfy NRCS coating performance validation requirements.
- Construction Firms:Infrastructure developers requiring structural steel protection and concrete admixture performance verification.
- Technology Companies:Semiconductor fabricators and electronics assemblers demanding contamination-free manufacturing environments.
Manufacturers dominate current procurement; Energy Sector is climbing the fastest.
Technology:
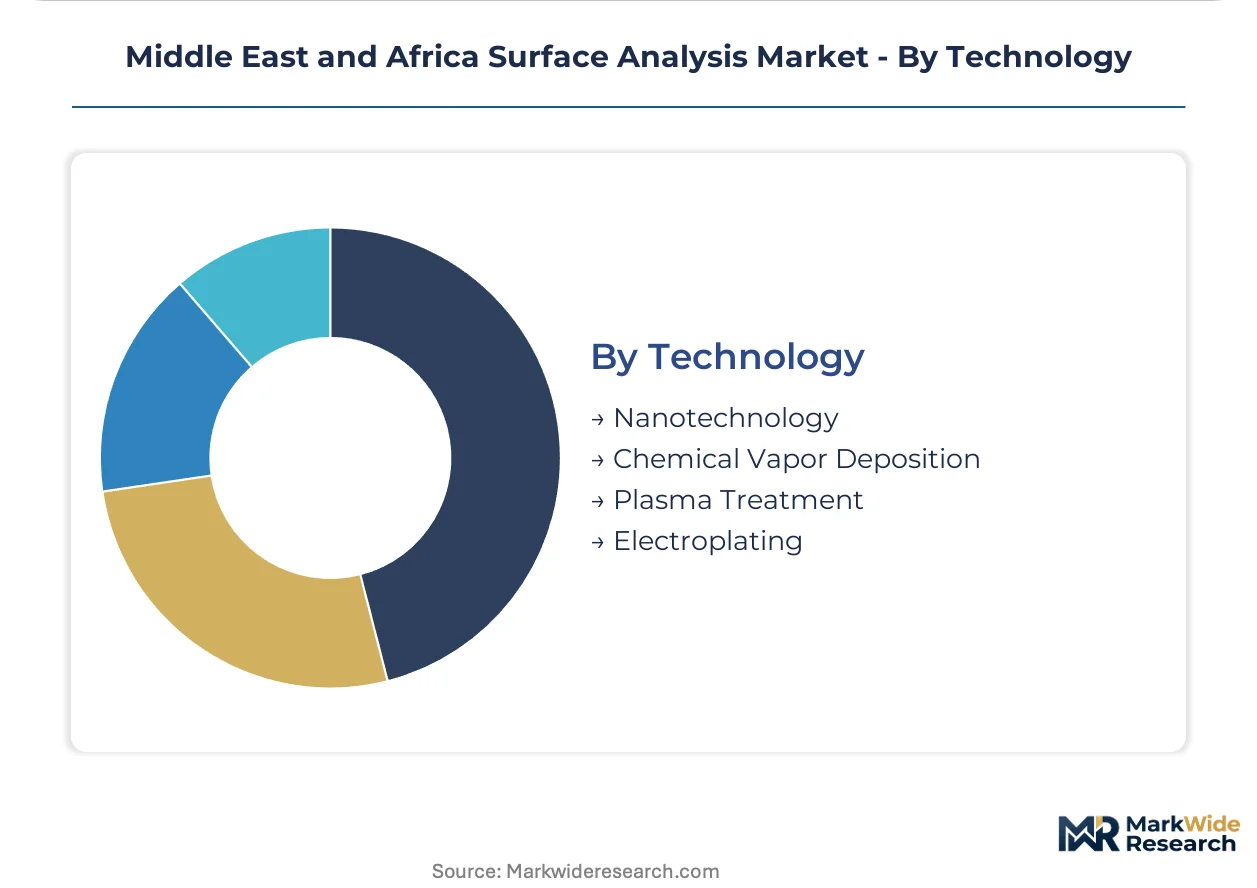
Maturity gradient separates established electroplating infrastructure from emerging nanotechnology platforms requiring advanced analytical validation.
- Nanotechnology:Graphene-based anti-corrosive formulations, carbon nanotube-reinforced coatings, and atomic layer deposition systems. Saudi Aramco's supplier network accelerates secondary ion mass spectrometry deployment for nanometer-scale coating characterization, with graphene formulations requested specifically for downhole equipment protection in high-salinity reservoirs.
- Electroplating:Mature aqueous and non-aqueous deposition processes for decorative and functional metal finishes. Moroccan and Egyptian automotive parts applications retain price-competitive positioning, though substitution pressure from computational materials modeling reduces physical testing frequency among cost-sensitive manufacturers.
- Chemical Vapor Deposition:Gas-phase thin film growth for semiconductor, optical, and protective coating applications.
- Plasma Treatment:Low-temperature surface activation and coating processes for temperature-sensitive substrates.
Electroplating retains volume leadership; Nanotechnology shows sharpest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands aerospace-driven instrument demand while South Africa anchors mining equipment validation, yet both face divergent regulatory pressures reshaping procurement timelines.
Saudi Arabia
Turbine blade thermal barrier coatings and downhole equipment protection drive X-ray photoelectron spectroscopy and secondary ion mass spectrometry demand. SFDA equipment registration protocols mandate analytical instrument traceability and compel foreign vendors to establish accredited regional calibration facilities. Riyadh-based aerospace suppliers require high-temperature alloy validation, creating sustained service-level obligations for instrument providers.
United Arab Emirates
Semiconductor wafer inspection from Abu Dhabi fabrication facilities and medical device biocompatibility testing reshape technology requirements. MOHAP quality certifications expand scope for surface analysis in implantable device validation, creating regulatory tailwind for specialized service providers. Dubai's free trade zones concentrate service-unbundling models where vendors retain equipment ownership and deliver coating validation outcomes.
South Africa
Mining equipment wear-resistant surface treatments and construction machinery coating performance standards dominate procurement. NRCS enforces 18-month coating performance validation cycles that delay market entry for imported equipment. Mining OEMs in Gauteng and the Northern Cape embed surface analysis capabilities within in-house metallurgical laboratories to satisfy domestic certification requirements.
Egypt
Automotive electroplating for European OEM supply chains lacks localized Auger electron spectroscopy access, constraining quality assurance. General functional descriptors for national industrial standards apply to import protocols for analytical instruments. Cairo-based facilities present white space for mobile analytical units serving cost-sensitive manufacturers with limited capital expenditure capacity.
Morocco
Automotive parts electroplating retains price-competitive positioning though computational materials modeling reduces physical testing frequency. General functional descriptors for national automotive sector regulations shape coating validation requirements. Industrial clusters serving European export markets balance cost pressures against quality certification demands from downstream customers.
Middle East and Africa Surface Analysis Market Competitive Landscape
Japanese and American producers anchor one tier; European specialists hold differentiated positions in spectroscopy and electron microscopy systems. Market structure concentrates around instrument vendors with established regional service networks and calibration capabilities. Three archetypes dominate: diversified analytical conglomerates, precision spectroscopy specialists, and electron microscopy pure-plays. Competitive moves center on service localization partnerships and long-term coating validation contracts displacing equipment-centric sales.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc and Agilent Technologies, Inc. exemplify scale-driven positioning through extensive distribution networks. Bruker Corporation occupies a specialized position among spectroscopy-focused providers. Japanese electron microscopy specialists including JEOL Ltd and Shimadzu Corporation represent precision-instrument archetypes with tailored capabilities for semiconductor and materials science applications.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Thermo Fisher Scientific Inc |
| Bruker Corporation |
| HORIBA Group |
| JEOL Ltd |
| Physical Electronics, Inc. |
| Eurofins Scientific |
| Agilent Technologies, Inc. |
| Oxford Instruments plc |
| Others |
Supply & Pricing Matrix
Helium procurement from Qatari sources feeds directly into cryogenic electron microscopy operating costs, with regional instrument vendors passing through input volatility across three-tier pricing structures separating premium XPS systems from standard SEM platforms and economy-grade optical profilers.
Pricing Analysis
Capacity additions in the UAE and Saudi Arabia are reshaping price floors for surface analysis services as Dubai-based vendors deploy mobile analytical units. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Cost compression in the electroplating tier is intensifying because Moroccan automotive parts manufacturers substitute computational modeling for physical testing. Automotive electroplaters in North Africa exhibit highest price sensitivity; aerospace component manufacturers in the Gulf show lowest.
Supply Chain Analysis
Local-content thresholds in Saudi Arabia and the UAE are reshaping sourcing patterns for instrument vendors serving government-linked aerospace and energy buyers. Supply concentration centers on Germany, Japan, and the United States for electron microscopy and spectroscopy systems. Raw material dependencies include helium from Qatar, high-purity rare earth elements for detector components, and specialized vacuum-grade ceramics. Single-source vulnerability runs through Qatari helium allocation protocols. Distribution runs through Dubai's free trade zones where foreign vendors retain operational control without local equity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Saudi Aramco suppliers and UAE aerospace manufacturers shift specifications toward nanotechnology-validated coating architectures with traceable SFDA and MOHAP documentation.
For Market Incumbents: Anchor regional service capabilities through accredited calibration facilities in Riyadh and Dubai to defend against emerging mobile analytical unit providers. Deepen backward integration into helium recycling systems to mitigate Qatari supply concentration. Prioritize certification investment for SFDA equipment registration protocols. For New Entrants and Emerging Players: Launch via mobile analytical service models targeting Cairo-based automotive electroplating facilities lacking localized Auger electron spectroscopy access. White space concentrates in Egyptian quality assurance for European OEM supply chains. Penetrate through outcome-based coating validation contracts rather than capital equipment sales. For Investors and Strategic Acquirers: Consolidation pressure builds where NRCS certification timelines compress market entry for imported mining equipment and service-unbundling models concentrate vendor ownership in Dubai free zones. Long-term viability favors precision spectroscopy specialists with regional calibration accreditation. Acquisition target archetype: electron microscopy pure-plays with UAE MOHAP service contracts. Signal to watch: SFDA local-content threshold adjustments for government procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Service Unbundling Model | Separates hardware ownership from analytical deliverables for UAE oil and gas operators. |
| Accredited Regional Calibration Facility | Satisfies SFDA equipment registration protocols for Riyadh-based aerospace suppliers. |
| Mobile Analytical Unit Deployment | Addresses white space in Cairo automotive electroplating quality assurance. |
| Helium Recycling System Investment | Mitigates Qatari supply concentration for cryogenic electron microscopy operations. |
| Machine Learning Integration | Automates coating defect identification for Saudi Aramco pipeline corrosion monitoring. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each sub-region combining interviews with instrument vendor service directors, aerospace component manufacturer quality leads, mining OEM metallurgical laboratory managers, and oil and gas operator procurement officers. Secondary validation draws from SFDA equipment registration databases, NRCS coating performance standards, UAE Ministry of Health and Prevention certification records, and customs import data for analytical instruments. Bottom-up segment sizing triangulates against top-down industry expenditure estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type tier, application capital intensity, end-user captive versus outsourced laboratory structure, and technology maturity gradient. CAGRs derive from fitted growth curves anchored to disclosed procurement patterns and regulatory milestone timelines. Industry-specific inputs incorporate SFDA registration velocity and NRCS certification cycle compression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios or accelerated substitution from computational materials modeling. Forecasts reflect documented assumptions regarding regulatory timeline adherence and local-content threshold evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Profiling Floats Market
Others
Durian Fruit Market
Others
Triathlon Clothing Market
Others
Global Pregnancy Tracker Apps Market
Others
Wearable Translator Market
Others
Construction Fabrics Market
Others
Workstation Desktops Market
Others
Augmented Reality in BFSI Market
Others
AI in Precision Medicine Market
Others
GCC Health and Wellness Market
Others
LAMEA Astrology Market
Others
Foldable Smartphone Market
Others
Synthetic Leather Market
Others
PC As a Service Market
Others
Printed Leather Market
Others
Dried Fruit Extracts Market