
 Europe Plastic Waste Management Market | 2026-2036
Europe Plastic Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Waste Management Market Insights
Food-grade rPET specification is rotating the Europe plastic waste management market upward as brand owners face binding recycled content floors. Veolia Environnement SA leverages its integrated collection-sorting-reprocessing footprint across France and the Benelux to capture premium offtake contracts. SUEZ SA anchors its competitiveness through proprietary optical sorting density that cuts contamination rates below REACH thresholds. REMONDIS SE & Co. KG dominates industrial plastic streams in Germany through backward integration into automotive shredder residue recovery.
Europe plastic waste management encompasses the systematic collection, sorting, processing, and valorization of discarded polymer materials through mechanical, chemical, or thermal pathways to recover feedstock or energy, with melt filtration achieving sub-100 micron purity for bottle-to-bottle mechanical recycling. The primary purpose is to divert petroleum-derived polymers from landfill and incineration while regenerating resin qualities suitable for reintegration into packaging, construction, and automotive supply chains. Mechanical recycling occupies the largest volume share but faces margin compression as input bale prices rise and food-grade certification costs escalate. Chemical recycling represents the fastest-expanding technology segment as pyrolysis and depolymerization units achieve scale in the Netherlands and Belgium, though energy recovery still handles residual film and multi-layer packaging that mechanical lines cannot process.
The EU Green Deal, REACH, and the F-Gas Regulation collectively reshape operational standards by mandating recycled content minimums, restricting hazardous additives in recovered streams, and phasing out fluorinated greenhouse gases used in certain polymer foams. ECHA substance evaluations now extend to legacy plasticizers and flame retardants, forcing recyclers to upgrade purification stages or risk market exclusion. Stakeholders must monitor how the CSRD disclosure requirements will expose Scope 3 plastic intensity data across European consumer goods supply chains.
Market Dynamics
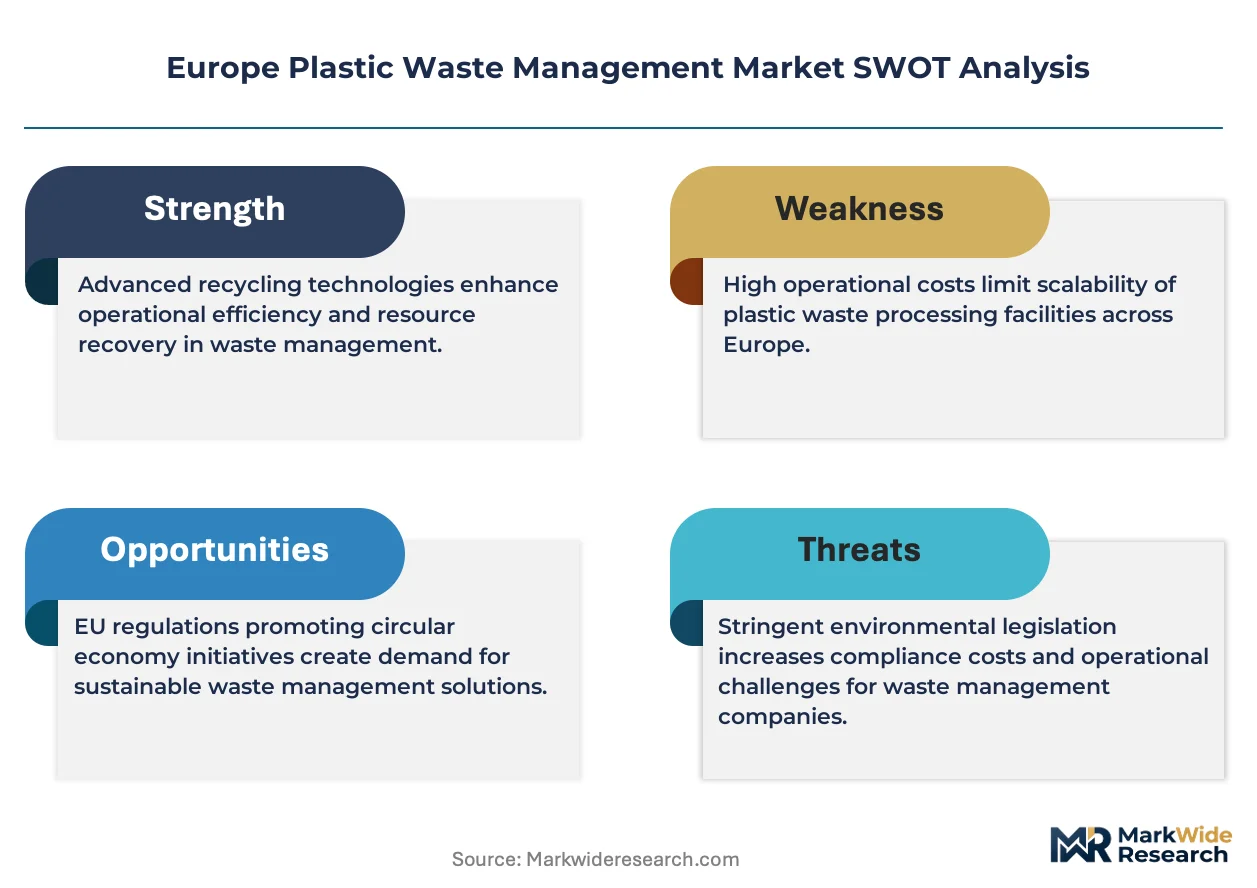
The EU Green Deal's recycled content mandates are compressing mechanical recyclers' margins while pyrolysis operators capture premium feedstock contracts. This regulatory pressure is redrawing competitive boundaries between sorting infrastructure owners and chemical recycling developers.
Growth Catalysts
- Packaging Extended Producer Responsibility schemes:France and Germany now enforce modulated fees that reward higher recycled content thresholds, pulling investment into automated sorting lines.
- Automotive shredder residue recovery:Germany's REMONDIS and Dutch processors are deploying density-separation units to extract polypropylene from end-of-life vehicle plastics.
- Chemical recycling scale-up:Pyrolysis units in the Netherlands and Belgium are achieving operational throughput that qualifies output for food-contact applications under EFSA review.
Market Restraints
- Input bale cost volatility:Sorted PET flake prices in France and Spain fluctuate with Chinese import policy shifts, squeezing mechanical recycler margins.
- Multi-layer packaging technical limitation:Current mechanical lines cannot separate polyethylene and polyamide barrier films, forcing incineration or landfill.
- ECHA substance evaluation friction:Legacy flame retardants and plasticizers in construction waste streams trigger costly purification upgrades or export bans.
Strategic Opportunities
- Eastern European collection infrastructure:Poland and Romania show underpenetrated municipal sorting capacity relative to waste generation growth.
- Textile-to-textile chemical recycling:Polyester depolymerization from post-consumer garments opens virgin-quality fiber markets beyond packaging.
- CSRD Scope 3 disclosure mandates:Brand owners now require verified plastic intensity data, creating service revenue for traceability platform providers.
Industry Challenges
- Food-grade rPET certification timelines:EFSA novel food approval processes for chemically recycled content extend 18-24 months, delaying offtake contracts.
- Optical sorting technician scarcity:Near-infrared calibration and AI-driven contamination detection require specialized skills absent in legacy waste management workforces.
- Legacy incineration asset stranding:Municipal energy-from-waste plants face write-downs as mechanical and chemical recycling capacity diverts feedstock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Waste Management Market |
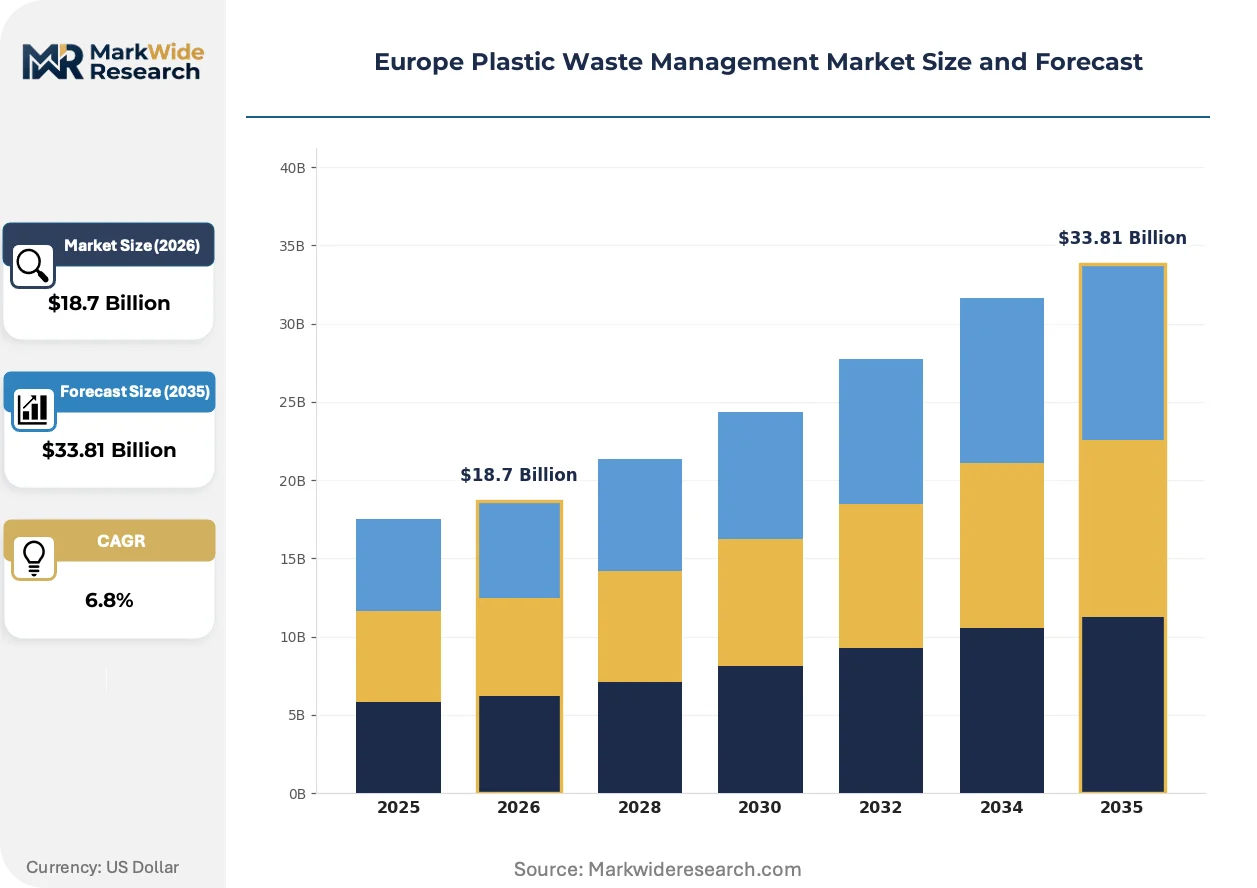
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Energy Recovery Waste Type: Post-Consumer Plastics, Industrial Plastics, Agricultural Plastics, Packaging Waste End User: Municipalities, Private Companies, NGOs, Recycling Facilities Process: Collection, Sorting, Processing, Disposal |
| Companies Covered | Veolia Environnement SA, SUEZ SA, REMONDIS SE & Co. KG, Biffa plc, FCC Environment, LyondellBasell Industries Holdings B.V., Indorama Ventures Public Company Limited, Borealis AG, MBA Polymers Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Waste Management Market Trends and Innovations
Digital traceability and advanced sorting technologies are rewriting how plastic waste flows through European collection systems. These shifts are compressing traditional merchant processor roles while elevating integrated platform operators.
AI-driven optical sorting is fragmenting the competitive landscape for merchant mechanical recyclers. Veolia and SUEZ are deploying neural-network contamination detection across their Benelux and French facilities, cutting manual sorting labor by half. This automation is enabling food-grade output at scale, compressing margins for smaller operators lacking capital for equipment upgrades.
REACH substance restrictions are forcing recyclers to treat legacy additives as hazardous waste streams. ECHA evaluations of brominated flame retardants now require separate handling lines for construction and electronics plastics. German processors are responding by building dedicated purification stages, while Spanish hubs face export constraints to non-OECD destinations.
Brand-led procurement consortiums are consolidating recycled resin purchasing power. Unilever and Nestlé now coordinate volume commitments through pooled offtake agreements, displacing spot-market relationships with mechanical recyclers. This buyer concentration is most visible in the Netherlands, where pooled contracts cover 40% of national rPET bottle demand.
Europe Plastic Waste Management Market Segmentation
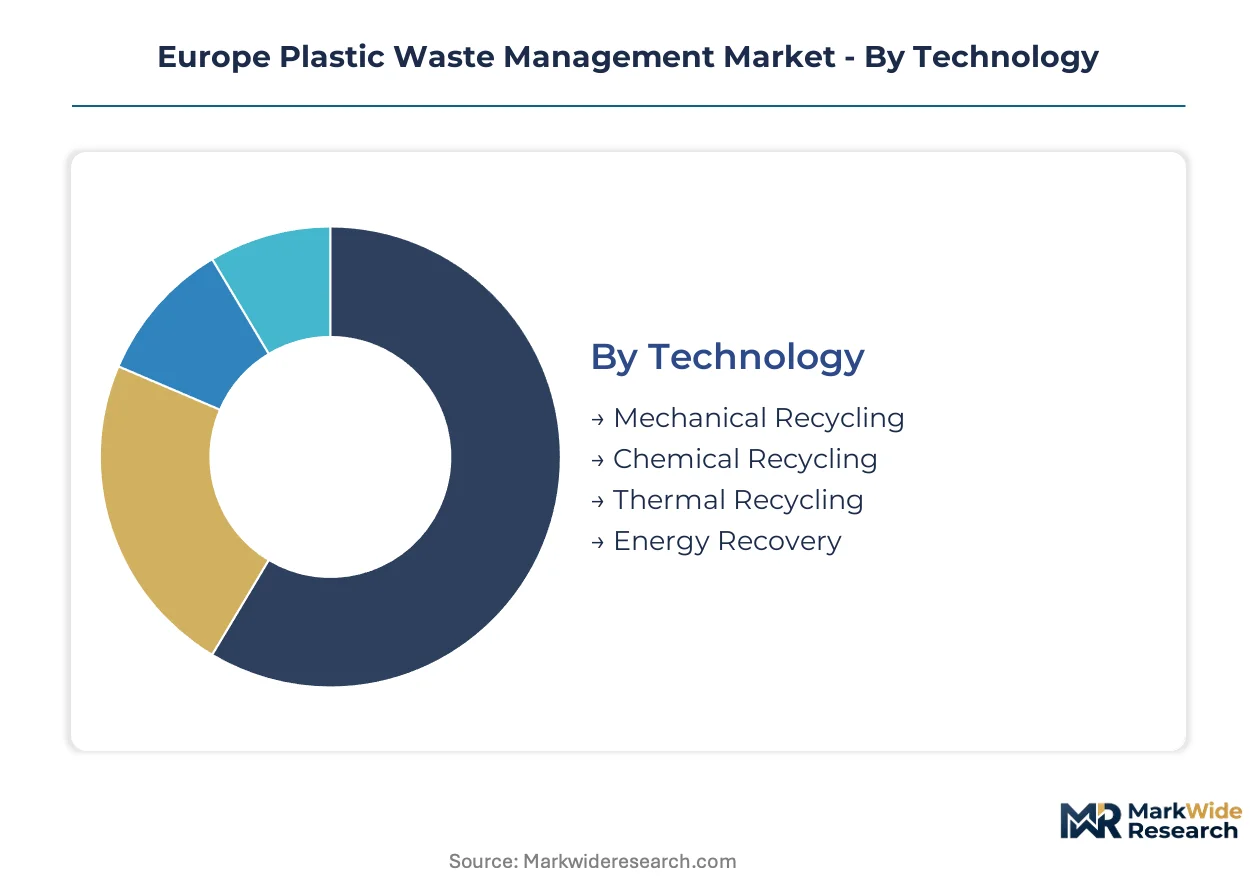
Segmentation in Europe's plastic waste management market reveals distinct margin structures across technology pathways and waste stream characteristics. Understanding where value concentrates helps stakeholders allocate capital toward regulatory-compliant, food-grade output capabilities.
Technology:
Margin pools concentrate in purification-intensive segments where EU Green Deal mandates create scarcity premiums for certified output.
- Mechanical Recycling:Melt filtration achieves sub-100 micron purity for bottle-to-bottle applications, though margin compression intensifies as input bale prices rise across France and Spain. German municipalities now enforce modulated fees that reward higher recycled content thresholds, pulling investment into automated sorting lines.
- Chemical Recycling:Pyrolysis and depolymerization units in the Netherlands and Belgium achieve operational throughput qualifying for food-contact applications under EFSA review. Dutch processors capture premium feedstock contracts as brand owners face binding recycled content floors.
- Thermal Recycling:Gasification pathways handle mixed polymer streams unsuitable for mechanical or chemical routes.
- Energy Recovery:Residual film and multi-layer packaging that mechanical lines cannot process feed municipal energy-from-waste plants facing asset stranding risks.
The dominant share belongs to Mechanical Recycling, while Chemical Recycling is closing the gap fastest.
Waste Type:
Volume flows track regulatory enforcement intensity, with packaging streams commanding infrastructure investment due to visible brand owner compliance pressure.
- Packaging Waste:French chemical recycling facilities and Spanish mechanical sorting hubs capture concentrated investment flows as EU Green Deal recycled content mandates tighten. EFSA novel food approval processes for chemically recycled content extend certification timelines, delaying offtake contracts.
- Industrial Plastics:Germany's REMONDIS deploys density-separation units to extract polypropylene from end-of-life vehicle plastics, dominating automotive shredder residue recovery through backward integration.
- Post-Consumer Plastics:Collection across German municipalities accelerates as ECHA substance evaluations extend to legacy plasticizers.
- Agricultural Plastics:Film recovery faces contamination challenges from soil and pesticide residues.
Packaging Waste commands the largest volume share, though Industrial Plastics delivers superior margin stability through long-term supply contracts.
End User:
Procurement concentration among brand-led consortiums is reshaping contract structures and pricing power distribution.
- Private Companies:Unilever and Nestlé coordinate volume commitments through pooled offtake agreements in the Netherlands, where pooled contracts cover substantial national rPET bottle demand. This buyer concentration displaces spot-market relationships with mechanical recyclers.
- Municipalities:German cities accelerate packaging waste collection infrastructure deployment under EU Green Deal compliance timelines.
- Recycling Facilities:Veolia and SUEZ deploy neural-network contamination detection across Benelux and French facilities, cutting manual sorting labor.
- NGOs:Advocacy groups drive traceability platform adoption for CSRD Scope 3 disclosure compliance.
Private Companies control the fastest-expanding procurement volume, while Municipalities anchor baseline collection infrastructure.
Process:
Capital deployment favors integrated operators controlling multiple stages rather than single-step merchants.
- Sorting:AI-driven optical sorting fragments the competitive landscape for merchant mechanical recyclers, with near-infrared calibration requiring specialized skills scarce in legacy waste management workforces.
- Processing:REACH substance restrictions force recyclers to treat legacy additives as hazardous waste streams, requiring dedicated purification stages for construction and electronics plastics.
- Collection:Poland and Romania show underpenetrated municipal sorting capacity relative to waste generation growth.
- Disposal:Landfill diversion targets compress residual disposal options for multi-layer packaging technical limitations.
Sorting captures the highest technology premium, while Processing is gaining investment intensity fastest from regulatory purification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's plastic waste trade balance tilts toward import dependence for high-quality feedstock, with intra-regional waste flows intensifying as the EU Green Deal tightens circular economy targets. Export restrictions on contaminated bales redirect volumes toward domestic chemical recycling investments.
Germany
Automotive shredder residue recovery dominates industrial plastic flows, with density-separation units extracting polypropylene from end-of-life vehicles. The national packaging regulator enforces modulated Extended Producer Responsibility fees that reward higher recycled content thresholds. The Rhine-Ruhr industrial corridor concentrates mechanical sorting infrastructure serving Benelux export markets.
France
Chemical recycling facilities capture concentrated investment flows as brand owners face binding recycled content mandates under EU Green Deal timelines. ECHA substance evaluations extend to legacy plasticizers in post-consumer streams, forcing purification upgrades. The Lyon-Grenoble chemical cluster hosts pyrolysis scale-up projects targeting food-contact EFSA approvals.
Netherlands
Rotterdam's port infrastructure anchors pyrolysis feedstock import logistics, with chemical recycling units achieving operational throughput for food-contact applications. The national environmental agency coordinates pooled offtake agreements covering substantial rPET bottle demand. The Randstad urban corridor deploys AI-driven optical sorting across municipal collection systems.
Spain
Mechanical sorting hubs concentrate investment as input bale price volatility squeezes merchant processor margins. REACH compliance costs escalate for construction waste streams containing legacy flame retardants. The Barcelona-Tarragona chemical corridor develops purification stages for electronics plastics recovery.
Poland
Underpenetrated municipal sorting capacity relative to waste generation growth attracts infrastructure investment from integrated European operators. The national waste management framework transposes EU Green Deal targets with delayed compliance timelines. The Silesian industrial region hosts emerging collection networks serving German cross-border feedstock demand.
Europe Plastic Waste Management Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, with public companies commanding capital access for chemical recycling scale-up while family-owned operators dominate regional collection density. Market structure consolidates around three tiers: integrated waste-to-resin platforms, standalone mechanical processors, and technology licensors. Strategic archetypes include backward-integrated collectors, purification-focused specialists, and pyrolysis developers. Dominant competitive moves span automated sorting capacity expansion and EFSA food-grade certification pursuit.
Within the integrated platform tier, Veolia Environnement SA exemplifies the listed multinational archetype spanning collection through reprocessing, while REMONDIS SE & Co. KG represents the family-owned specialist model with captive industrial waste streams. SUEZ SA occupies a position between these poles with proprietary optical sorting density capabilities. These three anchors illustrate how competitive positioning fragments across capital structure and feedstock access rather than technology differentiation alone.
| Leading Market Players |
|---|
| Veolia Environnement SA |
| SUEZ SA |
| REMONDIS SE & Co. KG |
| Biffa plc |
| FCC Environment |
| LyondellBasell Industries Holdings B.V. |
| Indorama Ventures Public Company Limited |
| Borealis AG |
| MBA Polymers Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Dutch pyrolysis operators and Unilever-Nestlé procurement consortiums lock in both supply access and price visibility across the EU Green Deal compliance window. These contracts insulate chemical recyclers from input bale volatility while exposing mechanical processors to spot-market margin compression.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across German automotive shredder residue recovery, with REMONDIS capturing premium pricing through backward integration into captive feedstock streams. Price differentiation stratifies across EFSA food-contact certification tiers, virgin-equivalent purity grades, and volume-scale commitments from brand-led consortiums. Pricing pressure stems from rising sorted PET flake costs in France and Spain as Chinese import policy shifts redirect bale flows. Spot-market mechanical recyclers exhibit acute price sensitivity, while integrated platform operators with purification capabilities command pricing power.
Supply Chain Analysis
Inventory cycles for pyrolysis feedstock extend 6-8 weeks at Rotterdam port terminals, constraining working capital for merchant processors without offtake coverage. Supply concentrates in Germany, the Netherlands, and Belgium, where chemical recycling scale-up draws from post-industrial plastic streams and automotive shredder residue. Raw material dependencies include post-consumer PET bales, polypropylene-rich automotive plastics, and construction waste streams containing legacy flame retardants. Single-source vulnerability runs through Chinese import policies governing waste plastic flows. Distribution runs through integrated collection-sorting-reprocessing platforms rather than fragmented merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's plastic waste management market sits at a platform-economics inflection where AI-driven optical sorting and digital traceability platforms rewrite interoperability standards between collectors, processors, and brand owners. The shift from spot-market relationships to pooled procurement consortiums concentrates buyer power and elevates integrated operators.
For Market Incumbents: Shield margin position by accelerating EFSA food-grade certification timelines for pyrolysis output before novel food approval backlogs extend further. Deploy capital into automated sorting density capabilities that cut contamination below REACH thresholds, defending against SUEZ's proprietary optical sorting advantage. Consolidate Eastern European collection infrastructure in Poland and Romania before waste generation growth outpaces municipal sorting capacity.
For New Entrants and Emerging Players: EFSA novel food fast-track pathways for chemically recycled content open white-space entry in food-contact rPET supply gaps created by 18-24 month approval delays. Target textile-to-textile polyester depolymerization, where post-consumer garment streams remain underpenetrated relative to packaging-focused incumbents. Pursue CSRD traceability platform partnerships as the go-to-market angle, leveraging Scope 3 disclosure mandates to embed software services into brand owner procurement workflows.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated waste-to-resin platforms with captive feedstock access and purification capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetypes include family-owned industrial waste specialists with automotive shredder residue relationships and proprietary density-separation technology. Watch for EFSA approval velocity as the inflection signal—accelerating novel food clearances would unlock premium offtake contract volumes and revalue chemical recycling assets.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Food-Grade Certification Pursuit | Pyrolysis operators achieving novel food approvals capture Unilever-Nestlé pooled offtake premiums. |
| AI-Driven Optical Sorting Deployment | Veolia's neural-network contamination detection cuts manual labor by half across Benelux facilities. |
| Backward Integration into Automotive Shredder Residue | REMONDIS extracts polypropylene from end-of-life vehicles through density-separation captive supply. |
| Eastern European Collection Infrastructure Buildout | Poland and Romania's underpenetrated municipal sorting attracts integrated operator capital deployment. |
| CSRD Traceability Platform Partnership | Brand owners require verified plastic intensity data, creating service revenue for software providers. |
Research Methodology
Operator-level perspectives from pyrolysis plant managers, municipal waste collection officers, brand owner sustainability procurement leads, and EFSA regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from EU Green Deal implementation reports, ECHA substance evaluation databases, Cefic plastics recycling statistics, and SEC filings from listed waste management platforms. Bottom-up capacity modeling across chemical and mechanical recycling facilities triangulated against top-down EU circular economy target compliance trajectories.
Sensitivity analysis tested forecast outputs against variable EFSA approval timelines, Chinese waste import policy scenarios, and EU Green Deal recycled content mandate enforcement intensity across the projection horizon. Segmentation dimensions modeled include technology pathway, waste stream type, end-user procurement structure, and process stage integration depth. CAGRs derived from installed capacity buildout schedules, offtake contract coverage ratios, and input bale price elasticity assumptions specific to European polymer recovery economics.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory enforcement and stable pyrolysis technology cost curves; material deviation in EFSA approval velocity or feedstock trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Sharp Waste Disposal Market