
 Trash Pump Market | 2026-2036
Trash Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Pump Market Analytics
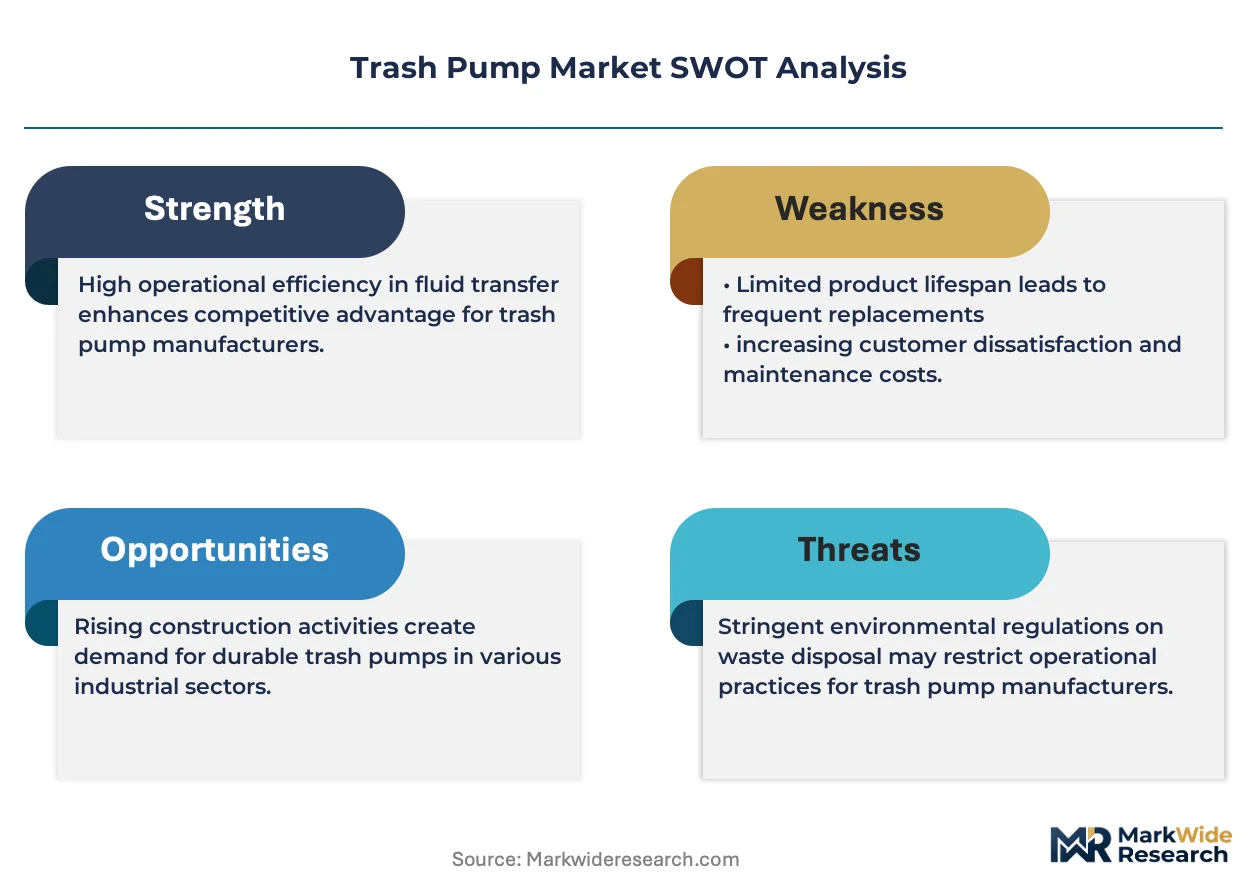
Chinese foundry capacity for cast-iron pump housings is decoupling from North American assembly lines, forcing OEMs to requalify secondary suppliers. Pentair leverages vertical integration in electric motor manufacturing to protect margin pools in the sub-10 HP range. Xylem sustains technology leadership through smart monitoring integrations that reduce unplanned downtime in municipal fleets. Grundfos anchors European demand with energy-efficient designs that comply with Ecodesign directives.
A trash pump is a centrifugal or submersible pumping device engineered with impeller clearances exceeding standard wastewater specifications, typically constructed from cast iron or stainless steel housings with hardened volutes to pass solids up to three inches in diameter without clogging. Its primary purpose is to transfer liquids containing suspended debris, slurry, or fibrous material across construction dewatering, municipal bypass, and agricultural drainage operations. Diesel-powered units dominate rental fleet deployments due to portability and torque characteristics, while electric variants capture permanent installations where grid connectivity supports continuous duty cycles. The flood control application segment commands premium pricing during seasonal demand spikes, whereas sludge handling generates recurring aftermarket revenue through impeller and seal replacements.
The EPA regulates effluent discharge limits under the Clean Water Act, compelling municipal buyers to specify pumps with enhanced sealing and material traceability. CE marking under the EU Machinery Directive and Ecodesign requirements shape export competitiveness for manufacturers serving European construction contractors. OSHA noise exposure standards influence portable gas-powered unit design, driving muffler and enclosure investments. Stakeholders must weigh EPA enforcement intensity against municipal budget cycles when forecasting replacement demand and inventory positioning.
Market Dynamics
Cast-iron foundry consolidation in China is severing traditional supply lines to North American assembly plants, forcing OEMs to requalify secondary forging sources and absorb extended lead times for pump housings and volutes.
Growth Catalysts
- EPA Clean Water Act enforcement:Municipal wastewater departments across the American Midwest and Southeast corridor must replace aging bypass pumps with sealed, traceable units to meet discharge limits.
- Flood control infrastructure:Seasonal storm intensity drives rental fleet deployment of diesel-powered portable units for emergency dewatering operations.
- Ecodesign Directive compliance:European municipal buyers specify energy-efficient impeller geometries that reduce lifecycle operating costs in continuous-duty installations.
Market Restraints
- Scrap metal price volatility:Cast-iron and stainless steel input costs swing with commodity markets, compressing margin pools for housing fabricators.
- Single-source foundry dependence:Chinese capacity concentration creates supply vulnerability when export quotas or shipping disruptions interrupt billet flow.
- Electric motor substitution:Permanent-magnet synchronous motors threaten conventional induction motor architectures in sub-10 HP permanent installations.
Strategic Opportunities
- Smart monitoring convergence:IoT-enabled vibration and temperature sensors bundled with predictive maintenance contracts create recurring revenue streams.
- Rural agricultural drainage:Underpenetrated farming regions in India and Brazil present volume potential for cost-optimized diesel units.
- OSHA noise standard alignment:Muffler and acoustic enclosure upgrades position rental fleets for stricter workplace exposure limits.
Industry Challenges
- Wet-end engineering talent scarcity:Specialized hydraulics designers capable of optimizing non-clogging impeller profiles command premium compensation.
- CE marking timeline compression:EU Machinery Directive conformity assessments delay product launches by four to six months.
- Legacy fleet integration friction:Smart pump retrofits must interface with SCADA systems installed during prior decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Pump Market |
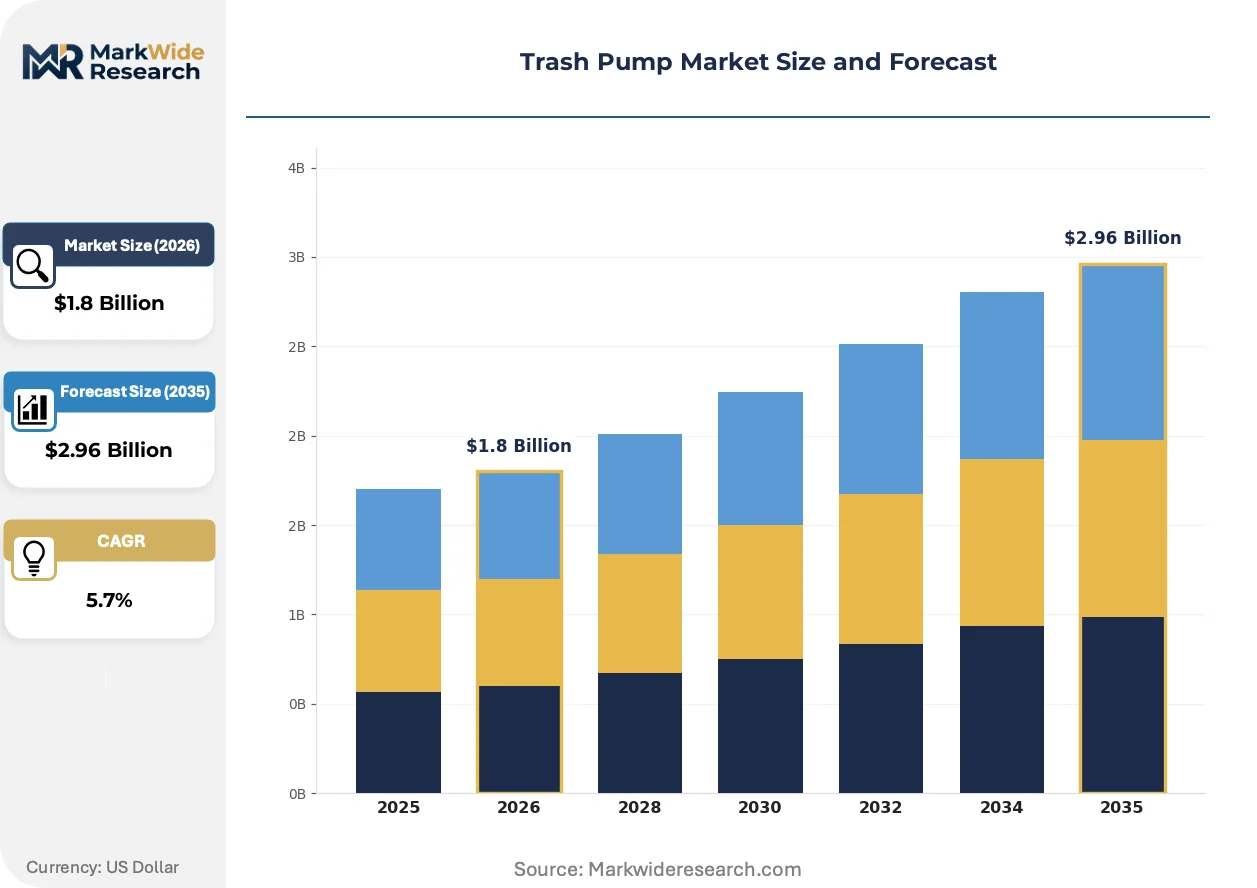
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Diesel, Hydraulic End User: Construction, Agriculture, Municipal, Industrial Application: Flood Control, Water Transfer, Sewage, Sludge Size: 1 Inch, 2 Inch, 3 Inch, 4 Inch |
| Companies Covered | Pentair, Xylem, Grundfos, Franklin Electric, Tsurumi Pump, Wacker Neuson, Gorman-Rupp, Sulzer, Liberty Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Pump Market Evolving Landscape
Digital instrumentation and predictive analytics are embedding intelligence into traditionally mechanical pumping systems, shifting value capture from hardware sales toward service-enabled recurring revenue models.
Variable frequency drive technology paired with permanent-magnet motors is expanding into municipal permanent installations where energy consumption dominates total cost of ownership calculations. Water treatment authorities in Germany and the Netherlands specify these configurations for continuous sludge transfer duties. The technology is expanding into mid-sized utility fleets that previously standardized on across-the-line induction motor starts.
REACH substance restrictions on chromium VI in surface coatings are compelling housing manufacturers to shift toward trivalent chrome or ceramic-lined alternatives. European OEMs face reformulation costs for corrosion-resistant volutes previously dependent on hexavalent treatments. Export-oriented suppliers serving EU construction contractors must maintain dual coating inventories or absorb certification delays.
Rental fleet operators now unbundle after-sales service from equipment leases, charging separately for impeller inspection and seal replacement. This model compresses switching costs for municipal procurement officers evaluating multi-year bypass contracts. The shift is most visible in the American Southeast where hurricane-driven demand spikes reward flexible fleet scaling over owned asset bases.
Trash Pump Market Segmentation
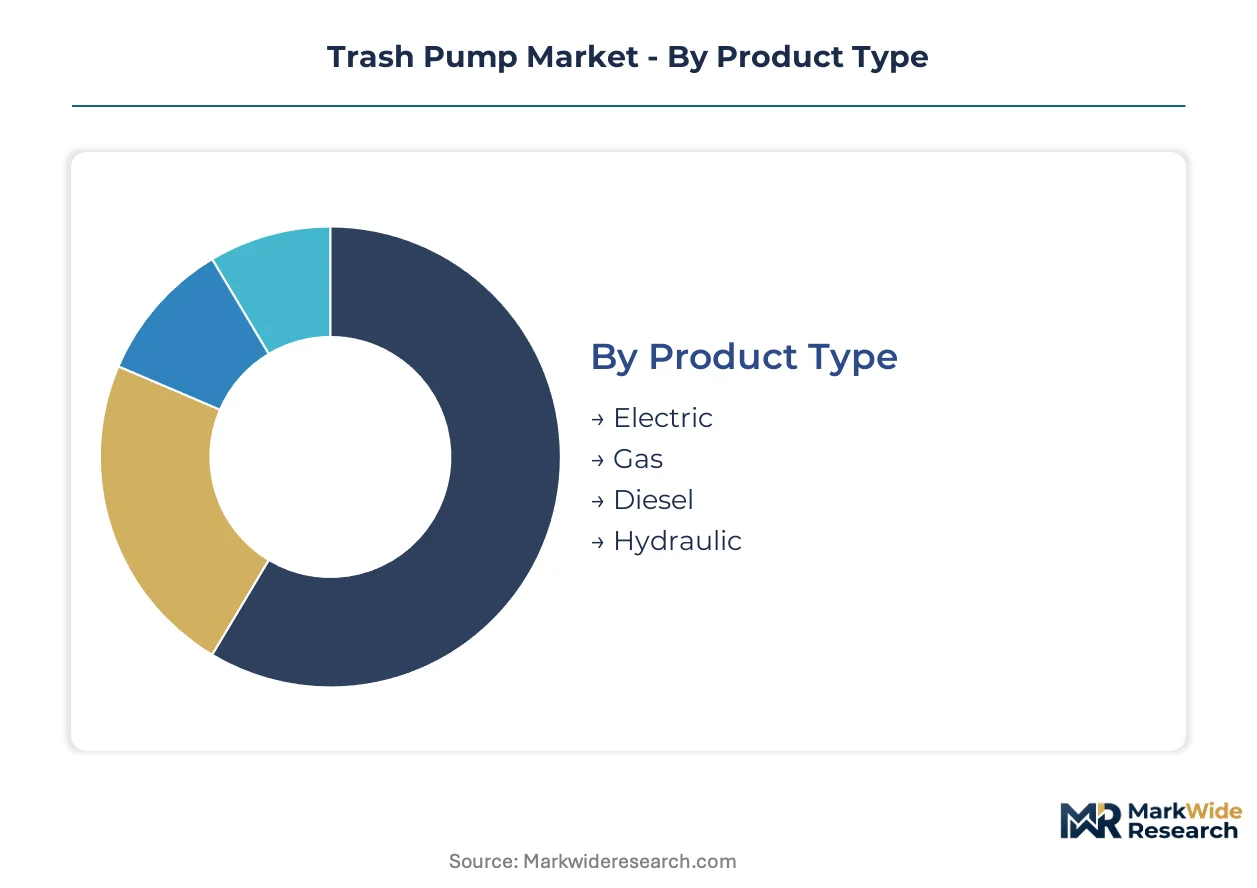
Trash pump procurement patterns diverge sharply between emergency rental deployments and permanent infrastructure installations. Understanding these segment boundaries clarifies why diesel units command rental premiums while electric variants capture municipal lifecycle contracts.
Product Type:
Diesel and electric variants split the market between portable premium deployments and fixed-cost efficiency plays.
- Diesel:Compression-ignition engines deliver torque curves optimized for high-solids slurry handling at variable heads. Midwest and Southeast municipal fleets specify these for EPA-mandated bypass operations where grid independence proves critical during storm events.
- Electric:Induction and emerging permanent-magnet synchronous architectures dominate continuous-duty installations with grid connectivity. German and Dutch water authorities favor these configurations for Ecodesign-compliant sludge transfer where energy consumption drives total cost of ownership.
- Gas:Spark-ignition portability serves construction dewatering crews needing rapid deployment without fuel logistics complexity.
- Hydraulic:Power-take-off integration with heavy equipment enables tracked excavator-mounted pumping for mining and trenching applications.
Today's leader: Diesel. Tomorrow's challenger: Electric.
End User:
Customer archetypes range from price-sensitive seasonal renters to specification-bound municipal engineers.
- Municipal:Wastewater departments in the American Midwest and Southeast corridor drive replacement cycles tied to EPA Clean Water Act enforcement timelines. These buyers prioritize sealed designs with material traceability over upfront cost.
- Construction:General contractors and specialty dewatering firms rent portable units for site drainage, creating demand spikes aligned with building seasonality and regional precipitation patterns.
- Agriculture:Farm operations in India and Brazil present volume potential for cost-optimized diesel units addressing seasonal field drainage and irrigation tailwater recovery.
- Industrial:Manufacturing facilities and mining operations specify heavy-duty configurations for process water handling and pit dewatering with extended duty cycles.
Municipal specifications set the performance ceiling. Construction rental demand sets the volume floor.
Application:
Use-case severity determines material specifications and aftermarket revenue potential.
- Flood Control:Emergency dewatering commands premium pricing during seasonal demand spikes, with rental fleets scaling capacity ahead of hurricane and monsoon windows.
- Sludge:Continuous handling of high-solids content generates recurring aftermarket revenue through impeller wear and seal replacement cycles.
- Sewage:Municipal bypass operations require hardened volutes and enhanced sealing to pass fibrous debris without clogging under EPA discharge scrutiny.
- Water Transfer:Lower-solids applications in construction and agriculture permit standard impeller clearances with reduced maintenance intervals.
Flood control captures episodic premiums. Sludge handling builds annuity streams.
Size:
Port diameter correlates with solids passage capability and deployment mobility trade-offs.
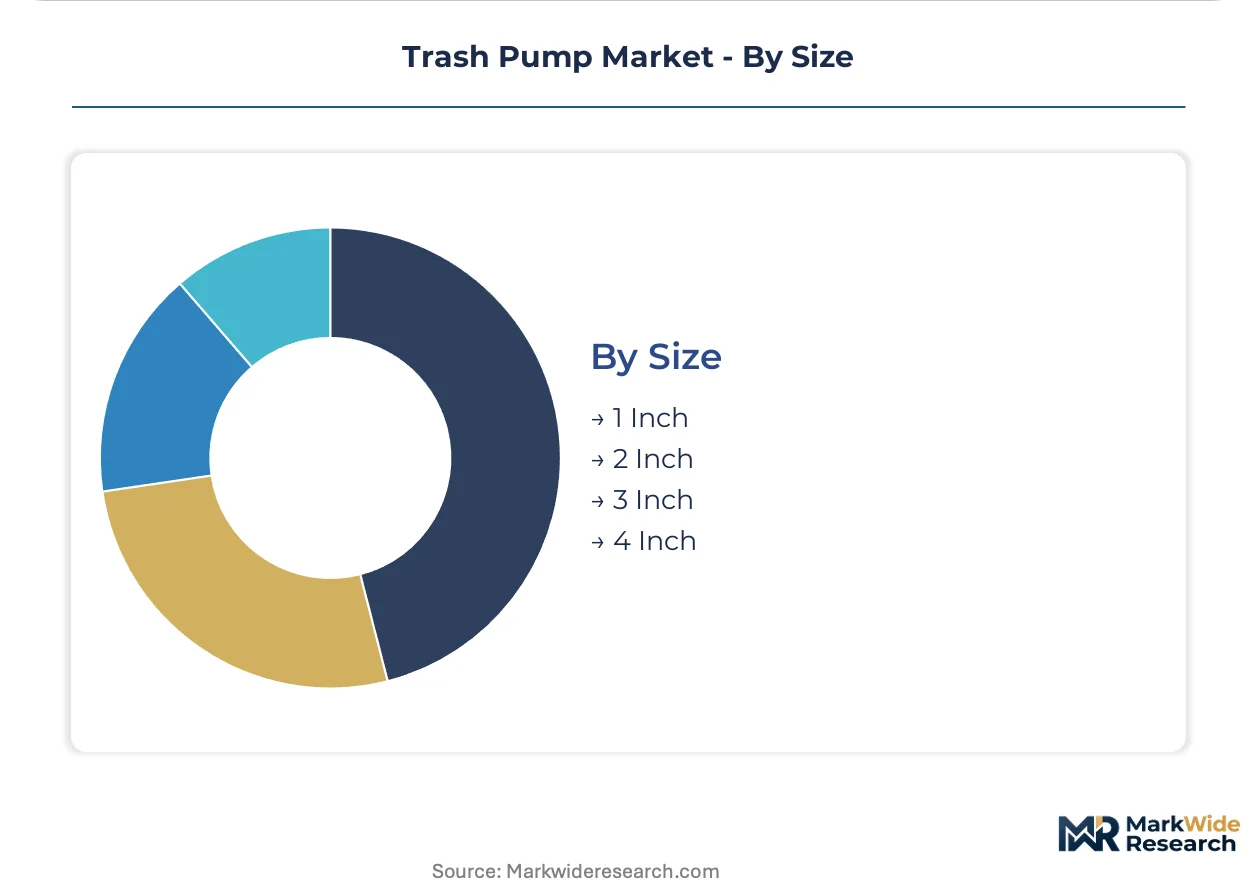
- 3 Inch:Balanced throughput and portability makes this the workhorse specification for municipal bypass and construction dewatering where three-inch solids passage handles typical debris loads.
- 4 Inch:Maximum solids handling for industrial sludge and flood control applications where flow volume outweighs mobility constraints.
- 2 Inch:Compact deployments suit confined-space construction sites and light agricultural drainage with limited head requirements.
- 1 Inch:Specialized utility applications including residential sump and basement drainage where minimal solids content permits reduced impeller clearances.
Three-inch specifications anchor current procurement. Four-inch configurations gain share in climate-adaptive infrastructure planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States municipal fleets outpace German water authorities in diesel-powered bypass procurement, while Chinese foundry output reshapes housing supply economics for both markets.
United States
Midwest and Southeast wastewater departments drive replacement cycles tied to EPA Clean Water Act enforcement timelines. FEMA flood mitigation grants accelerate diesel rental fleet scaling ahead of hurricane seasons. Houston-Galveston corridor contractors command premium pricing for emergency dewatering deployments during storm events.
Germany
Ruhr Valley water treatment authorities specify energy-efficient permanent-magnet configurations for continuous sludge transfer duties. Ecodesign Directive compliance mandates shape municipal procurement specifications across North Rhine-Westphalia. Stuttgart industrial pump clusters develop variable frequency drive integrations for mid-sized utility fleets.
China
Foundry capacity concentration in Hebei and Shandong provinces supplies cast-iron housings to global assembly lines. MEE discharge standards tighten traceability requirements for export-bound pump manufacturers. Yangtze River Delta OEMs requalify secondary forging sources as traditional supply lines sever.
India
Maharashtra and Gujarat agricultural operations present volume potential for cost-optimized diesel units addressing seasonal field drainage. CEA rural electrification gaps sustain compression-ignition preference in permanent installations. Tamil Nadu textile belt industrial users specify hardened volutes for process water handling with extended duty cycles.
Brazil
São Paulo state mining contractors deploy hydraulic power-take-off configurations for pit dewatering applications. ANVISA industrial equipment registration timelines delay product launches for European OEMs. Minas Gerais iron ore operations generate aftermarket revenue through impeller wear replacement cycles in sludge handling.
Trash Pump Market Competitive Landscape
United States producers anchor one tier; Danish and Japanese specialists hold differentiated positions in energy-efficient and submersible categories. The vendor base stratifies across three tiers: integrated multinational pump groups, regional foundry-assembly operations, and rental fleet service providers. Strategic archetypes include backward-integrated motor manufacturers, smart monitoring platform developers, and wet-end engineering boutiques. Capacity expansion and technology licensing represent the dominant competitive moves as supply chain reconfiguration accelerates.
Among integrated multinational groups, Pentair, Xylem, and Grundfos occupy positions spanning hardware manufacturing and service-enabled recurring revenue models. Pentair exemplifies the backward-integrated archetype through captive electric motor production. Xylem represents the smart monitoring convergence strategy with predictive maintenance platform development. Grundfos anchors European energy-efficient positioning through Ecodesign-compliant impeller geometries. These three entities collectively illustrate how competitive advantage is migrating from pure manufacturing scale toward bundled service contracts and regulatory anticipation.
| Leading Market Players |
|---|
| Pentair |
| Xylem |
| Grundfos |
| Franklin Electric |
| Tsurumi Pump |
| Wacker Neuson |
| Gorman-Rupp |
| Sulzer |
| Liberty Pumps |
| Others |
Value Network & Pricing Analysis
Diesel-electric performance bifurcation separates rental premium tiers from fixed-installation efficiency plays, with EPA-compliant sealed units commanding material traceability premiums while commodity cast-iron configurations absorb scrap metal volatility in margin compression. This divergence manifests in procurement patterns where municipal bypass contracts prioritize lifecycle sealing integrity over upfront capital outlay, whereas construction rental fleets optimize for portable deployment economics and seasonal utilization rates.
Pricing Analysis
Distributor margins layer atop OEM factory gate pricing with regional service bundling determining net landed cost to municipal procurement officers. Three-tier pricing structure across premium EPA-certified, standard industrial-grade, and economy rental-fleet tiers reflects impeller hardness ratings and seal specification differentials. Pricing pressure stems from Chinese foundry output fluctuations transmitting volatility into cast-iron housing costs. Construction rental operators exhibit highest price sensitivity due to fleet utilization uncertainty, while municipal wastewater departments prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Atlanta maintain hub-and-spoke patterns to serve hurricane-season demand spikes and Midwest bypass operations. Manufacturing concentration rests on Hebei and Shandong foundry clusters for cast-iron housings, with German motor winding facilities and Japanese bearing suppliers completing assembly ecosystems. Single-source vulnerability concentrates in Chinese billet supply lines subject to export quota disruptions. Distribution runs through authorized dealer networks for municipal specifications and direct rental fleet procurement for portable diesel units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service bundling and smart monitoring subscription layers, as hardware commoditization in standard diesel units pushes value capture toward predictive maintenance contracts and seal replacement annuities.
For Market Incumbents: Extend predictive maintenance platform penetration into existing municipal fleet installed bases before permanent-magnet motor substitution accelerates in sub-10 HP continuous-duty segments. Deepen backward integration into electric motor manufacturing to protect margin pools against commodity housing cost swings. Prioritize EPA discharge standard anticipation ahead of enforcement timeline accelerations in Southeast corridor states.
For New Entrants and Emerging Players: Launch via rental fleet service partnerships targeting underpenetrated agricultural drainage districts in Maharashtra and Gujarat where CEA electrification gaps sustain diesel preference. Focus initial volume capture on cost-optimized 3-inch portable configurations for seasonal field drainage applications. Leverage acoustic enclosure upgrades as differentiation lever against OSHA noise standard tightening.
For Investors and Strategic Acquirers: Consolidation pressure builds where wet-end engineering talent scarcity meets fragmented regional foundry-assembly operations lacking smart monitoring capabilities. Five-to-ten year viability favors targets with captive impeller design expertise and established municipal specification relationships. Monitor FEMA flood mitigation grant allocation velocity as inflection signal for rental fleet expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Monitoring Platform Integration | IoT-enabled predictive maintenance contracts shift revenue from transactional hardware to recurring service layers. |
| Backward Integration into Motor Manufacturing | Captive electric motor production protects margin pools against commodity input volatility in sub-10 HP ranges. |
| Secondary Foundry Requalification | Hebei and Shandong supply line diversification reduces single-source vulnerability for cast-iron housing procurement. |
| Acoustic Enclosure Upgrade Programs | OSHA noise standard alignment positions rental fleets for stricter workplace exposure limit enforcement. |
| Rural Agricultural Distribution Partnerships | Maharashtra and Gujarat dealer networks unlock volume potential in underpenetrated seasonal drainage markets. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down foundry output tracking forms the analytical core of this study. Primary interviews with wastewater department engineers, rental fleet operations managers, OEM procurement directors, and aftermarket service heads combined with secondary validation from EPA enforcement disclosures, FEMA grant allocation databases, customs trade data for cast-iron billet flows, and SEC filings from publicly traded pump manufacturers. Triangulation across these sources ensures demand-side replacement cycle timelines align with supply-side capacity constraints.
Historical trendline analysis of diesel-electric technology substitution rates and seasonal flood control deployment patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include power source architecture, end-user procurement archetype, application severity tier, and port diameter specification. CAGRs derived from weighted average of replacement demand schedules and infrastructure investment trajectories. Industry-specific forecast inputs incorporated Ecodesign Directive compliance timelines and REACH substance restriction phase-ins affecting surface coating formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese export quota disruptions or accelerated EPA enforcement intensity. Forecasts reflect documented assumptions regarding municipal budget cycle continuity and scrap metal price band stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Construction Waste Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market