
 Asia-Pacific Industrial Waste Management Market | 2026-2036
Asia-Pacific Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Waste Management Market Insights
China's dual carbon goals is broadening the cost-of-entry calculus for industrial waste operators across the Asia-Pacific. Veolia Environnement S.A. leverages its integrated treatment network to capture complex hazardous waste contracts from chemical manufacturers. Daiseki Co., Ltd. anchors its position through deep specialization in solvent recycling and industrial wastewater recovery systems. China Everbright Environment Group Ltd dominates municipal-industrial hybrid projects where state-backed procurement favors domestic technology providers.
Asia-Pacific industrial waste management encompasses the collection, transportation, treatment, recycling, and final disposal of solid, liquid, and gaseous by-products generated by manufacturing, energy production, and construction activities, with treatment protocols varying by toxicity level, calorific value, and material recoverability. The service ecosystem spans collection logistics, thermal treatment, chemical stabilization, and landfill engineering designed to isolate contaminants from groundwater and atmospheric release. Recycling services command expanding margin pools as circular economy mandates in Japan and South Korea create structured demand for metal, solvent, and plastic recovery from industrial feedstocks. Hazardous waste treatment absorbs disproportionate capital allocation due to permitting complexity and the technical specificity of detoxification processes for heavy metals and persistent organic pollutants.
Japan's METI enforces strict industrial waste manifest tracking that elevates compliance costs for cross-border waste movements within the region. China's MEE administers discharge permit trading and carbon intensity benchmarks that directly shape investment priorities for on-site versus outsourced waste handling. Australia's TGA and state-level EPA frameworks impose landfill levies that accelerate adoption of alternative treatment technologies. Stakeholders must monitor how bilateral waste trade agreements between Southeast Asian nations and China reshape regional logistics networks and treatment capacity deployment.
Market Dynamics
China's dual carbon goals are compressing the timeline for industrial waste infrastructure upgrades, forcing manufacturing clusters to outsource complex hazardous treatment rather than rely on aging on-site facilities. This structural pivot toward third-party specialists is redrawing contract economics across the region.
Growth Catalysts
- Dual carbon goals:China's emission intensity benchmarks under MEE oversight are compelling chemical and electronics manufacturers to abandon marginal on-site treatment. Specialized contractors capture this displaced volume through long-term service agreements.
- Circular economy mandates:Japan's METI-enforced material recovery quotas for solvents and rare metals create structured offtake demand. Recycling operators secure premium margins from closed-loop contracts with automotive and semiconductor fabs.
- Electronics manufacturing concentration:Eastern Chinese provinces generate concentrated hazardous waste streams from PCB etching and electroplating. Cluster density justifies dedicated incineration and chemical stabilization facilities.
Market Restraints
- Permitting complexity:Hazardous waste treatment licenses in China require multi-year environmental impact assessments. This procedural friction caps the speed at which new thermal treatment capacity enters service.
- Specialized equipment import dependency:Advanced pyrolysis and plasma arc systems for persistent organic pollutants rely heavily on German and Japanese suppliers. Currency volatility and shipping constraints amplify capex uncertainty.
- Cross-border manifest friction:Japan's METI tracking requirements and ASEAN's inconsistent bilateral waste protocols fragment regional logistics. Transporters face compliance cost stacking on multi-country routes.
Strategic Opportunities
- Vietnam's industrial zone expansion:Northern provinces around Hai Phong are attracting electronics assembly investment. Early-mover waste contractors can anchor integrated treatment parks before regulatory frameworks mature.
- Digital waste tracking platforms:Blockchain-enabled manifest systems are penetrating South Korean and Australian markets. Operators deploying these tools capture compliance-premium contracts from multinationals with Scope 3 disclosure obligations.
- Industrial symbiosis parks:China's pilot eco-industrial zones mandate waste heat and by-product exchange between co-located manufacturers. Engineering firms with park-design expertise secure decade-long O&M retainers.
Industry Challenges
- Chemical process engineering talent scarcity:Plasma gasification and supercritical water oxidation require specialized operators. Training pipelines in Southeast Asia lag facility deployment timelines by three to five years.
- Legacy landfill liability:Australia's state EPA frameworks impose retroactive groundwater monitoring on closed sites. Remediation reserves consume capital that would otherwise fund alternative treatment R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Waste Management Market |
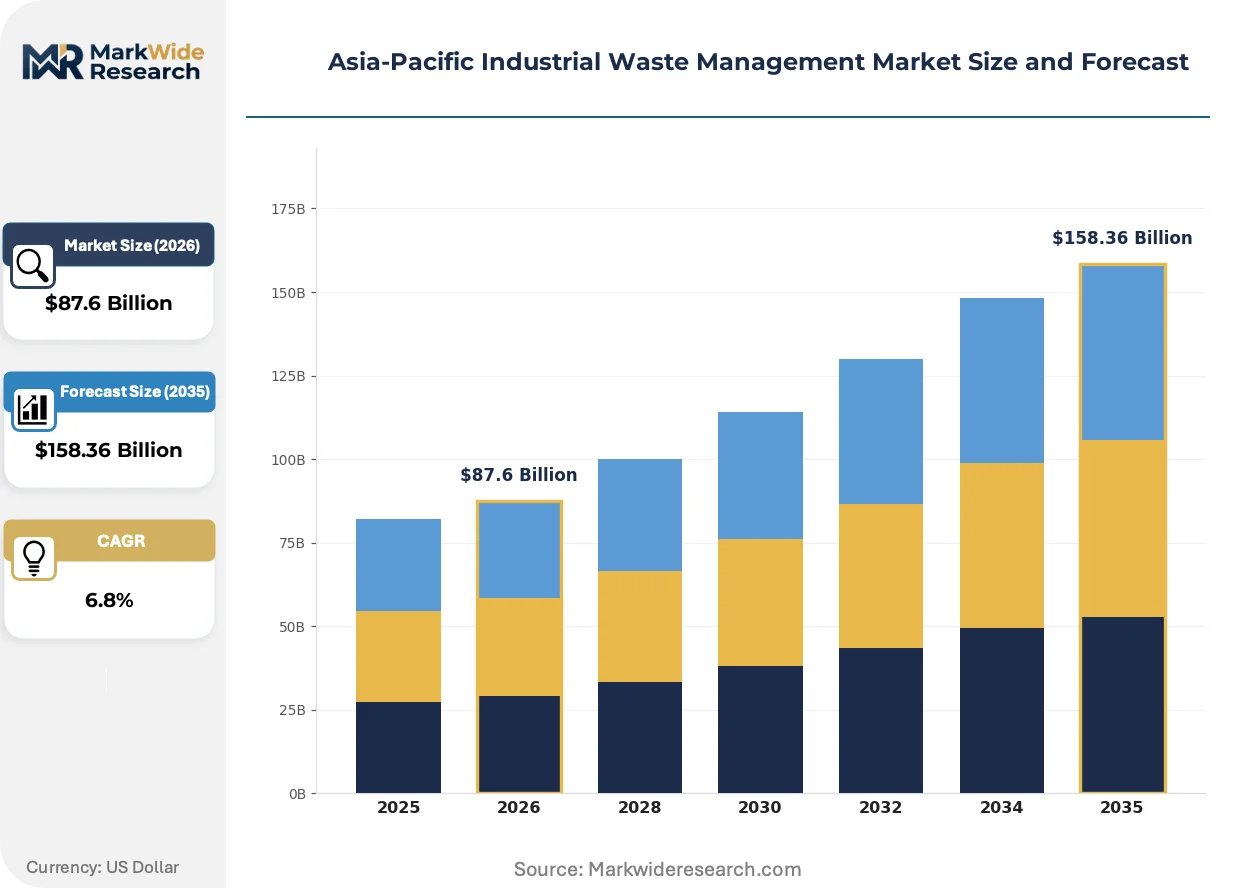
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Treatment, Disposal End User: Manufacturing, Construction, Energy, Food Processing Waste Type: Hazardous, Non-Hazardous, Electronic, Organic Technology: Incineration, Anaerobic Digestion, Landfilling, Composting |
| Companies Covered | Veolia Environnement S.A., Daiseki Co., Ltd., China Everbright Environment Group Ltd, Sembcorp Industries Ltd, Hitachi Zosen Corporation, Covanta Holding Corp., Waste Management, Inc., Clean Harbors, Inc., Remondis SE & Co. KG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Waste Management Market Trends and Innovations
Plasma gasification systems are displacing conventional rotary kiln incineration for the most toxic industrial residues. This technology shift is compressing residue volumes and opening new revenue streams from vitrified slag offtake.
Supercritical water oxidation is absorbing capital allocation from chemical manufacturers in Japan and South Korea. Electronics fabs facing solvent waste accumulation are adopting these systems to eliminate secondary waste generation. The technology is absorbing market share previously held by solvent recovery distillation, particularly where feedstock contamination exceeds 15 percent.
Australia's state-level EPA frameworks are tightening landfill levy escalators to accelerate thermal treatment adoption. Queensland and New South Wales impose annual indexation above inflation, forcing waste generators to model alternative disposal economics. Chemical and metallurgical sectors in these states are responding with accelerated pyrolysis project development.
Third-party logistics providers are fragmenting the traditional integrated operator model in Southeast Asia. Specialized haulers with hazardous cargo certifications are capturing collection margins that incumbants previously internalized. This unbundling is most visible in Thailand's Eastern Economic Corridor, where electronics assemblers now contract separately for transport, treatment, and final disposal.
Asia-Pacific Industrial Waste Management Market Segmentation
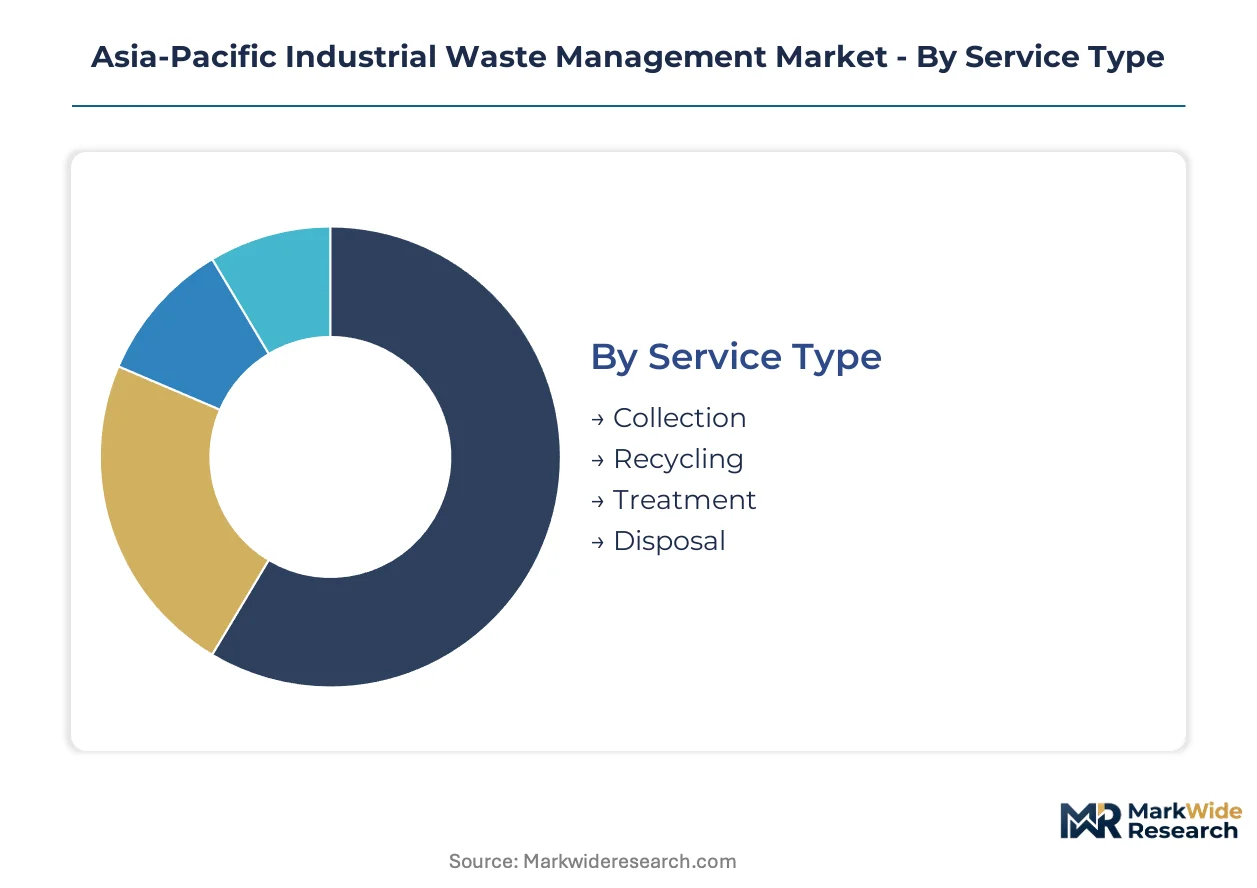
Industrial waste management operators across the Asia-Pacific configure service portfolios around four interlocking dimensions. Each segmentation axis carries distinct margin profiles, capital requirements, and regulatory exposure that shape competitive positioning.
Service Type:
Supply concentration in thermal treatment infrastructure favors operators with integrated service stacks over pure-play collectors.
- Collection:Specialized haulers with hazardous cargo certifications capture margin pools in China's eastern manufacturing clusters. Fleet density around Shanghai and Suzhou determines contract win rates for electronics and chemical generators.
- Recycling:Closed-loop solvent and rare metal recovery commands premium pricing from Japan's automotive and semiconductor fabs. METI-enforced material recovery quotas create structured offtake demand with decade-long contract visibility.
- Treatment:Plasma gasification and chemical stabilization facilities concentrate in China's chemical manufacturing heartland.
- Disposal:Landfill engineering for hazardous residues requires multi-year permitting in Australia under state EPA frameworks.
Treatment absorbs the bulk of installed capacity; recycling is expanding most quickly.
End User:
Cost tier differentiation separates high-compliance sectors willing to pay for audit-ready documentation from price-sensitive construction generators.
- Manufacturing:Electronics and chemical producers in Jiangsu and Guangdong provinces generate concentrated hazardous waste streams requiring specialized incineration infrastructure. MEE discharge permit trading directly shapes outsourcing economics.
- Construction:Demolition debris and contaminated soil recovery dominates Australia's urban renewal corridors. Queensland landfill levy escalators above inflation accelerate alternative treatment adoption.
- Energy:Coal ash and scrubber residue management concentrates around China's northern power bases.
- Food Processing:Organic waste volumes in Southeast Asia's agro-industrial zones support anaerobic digestion project development.
Manufacturing anchors revenue concentration; construction is gaining share fastest.
Waste Type:
Application-driven complexity separates hazardous streams requiring detoxification protocols from bulk non-hazardous flows.
- Hazardous:Heavy metals and persistent organic pollutants from PCB etching and electroplating demand plasma arc or supercritical water oxidation systems. Permitting complexity in China caps new thermal treatment capacity entry.
- Non-Hazardous:Industrial packaging and process scrap supports metal and plastic recovery operations across South Korea's manufacturing belt.
- Electronic:End-of-life circuit boards and battery modules concentrate treatment demand near China's recycling technology clusters.
- Organic:Food processing and agricultural residues feed biogas recovery projects in Vietnam's emerging industrial zones.
Hazardous waste commands the steepest capital allocation; electronic waste is climbing the fastest.
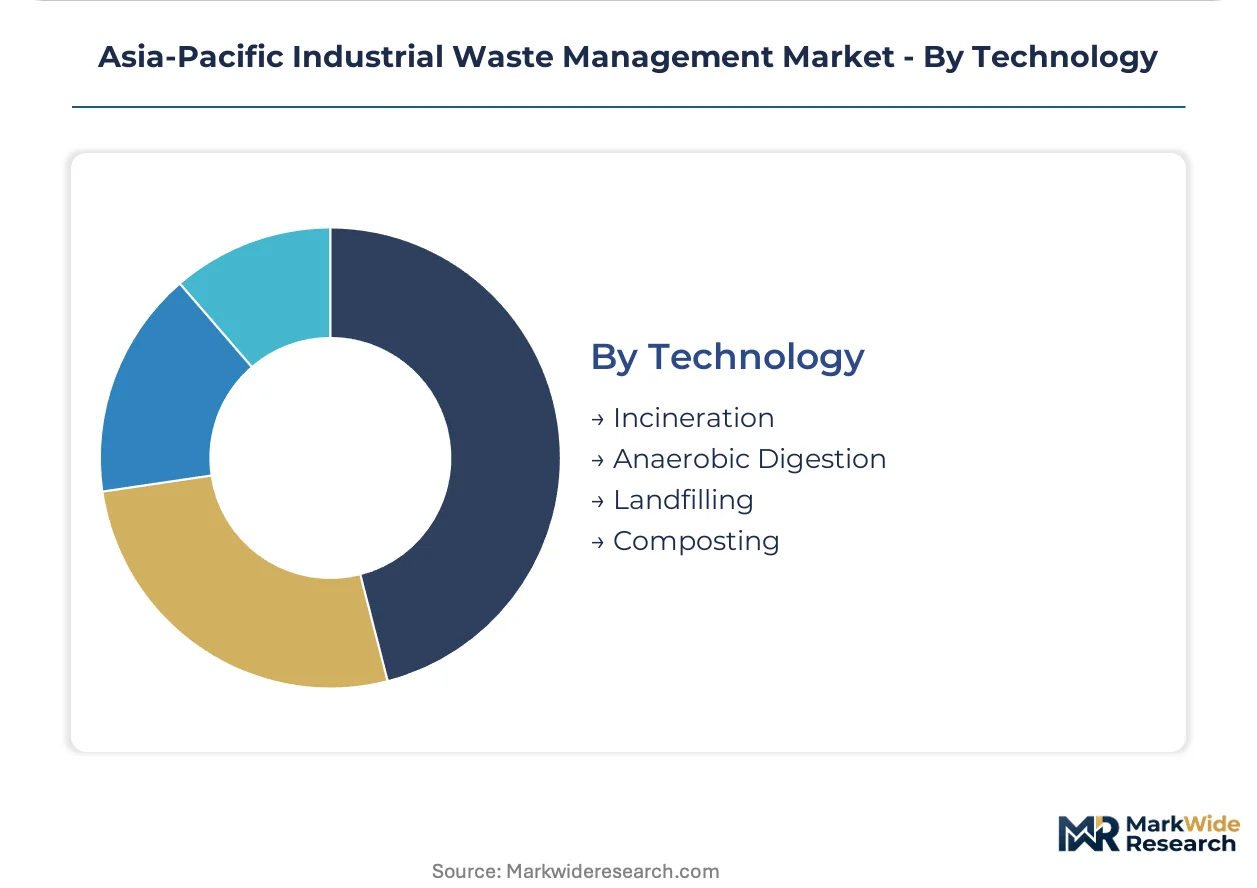
Technology:
Customer type segmentation separates multinationals requiring Scope 3 disclosure compliance from domestic generators prioritizing unit cost.
- Incineration:Rotary kiln systems face displacement from plasma gasification for the most toxic residues. Vitrified slag offtake creates secondary revenue streams from construction aggregate markets.
- Anaerobic Digestion:Biogas capture from food processing and agricultural waste concentrates in Thailand's Eastern Economic Corridor. Third-party logistics unbundling lets generators contract separately for transport and digestion.
- Landfilling:Australia's state EPA frameworks impose retroactive groundwater monitoring liability on closed sites.
- Composting:Organic waste stabilization serves agricultural offtake markets in Indonesia's palm oil processing regions.
Incineration retains the largest installed base; anaerobic digestion is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in eastern China generate the densest hazardous waste volumes, while Japan's strict METI manifest tracking and Australia's landfill levy escalators reshape competitive economics across the region.
China
Chemical and electronics production in Jiangsu and Guangdong provinces drives concentrated demand for plasma gasification and chemical stabilization infrastructure. MEE discharge permit trading and carbon intensity benchmarks under dual carbon goals force manufacturers to outsource complex treatment to third-party specialists. The Yangtze River Delta around Shanghai anchors the region's largest integrated waste treatment park development.
Japan
Automotive and semiconductor fabs generate structured demand for solvent recycling and rare metal recovery under METI-enforced material recovery quotas. Strict industrial waste manifest tracking elevates compliance costs for cross-border movements, favoring domestic operators with integrated logistics networks. The Kansai region around Osaka concentrates closed-loop recycling contracts with premium margin visibility.
Australia
State EPA frameworks in Queensland and New South Wales impose landfill levy escalators above inflation, accelerating thermal treatment adoption in chemical and metallurgical sectors. Retroactive groundwater monitoring liability on closed sites consumes capital that would otherwise fund alternative technology R&D. Urban renewal corridors in Sydney and Melbourne drive demolition debris and contaminated soil recovery demand.
South Korea
Electronics manufacturers facing solvent waste accumulation adopt supercritical water oxidation systems to eliminate secondary waste generation. Blockchain-enabled manifest platforms penetrate procurement requirements from multinationals with Scope 3 disclosure obligations. The Seoul Capital Area anchors biogas capture projects from food processing and agricultural waste streams.
Vietnam
Northern provinces around Hai Phong attract electronics assembly investment, creating early-mover opportunities for integrated treatment park development before regulatory frameworks mature. Agro-industrial zones in the Mekong Delta support anaerobic digestion project economics. Third-party logistics unbundling lets generators contract separately for transport, treatment, and final disposal.
Asia-Pacific Industrial Waste Management Market Competitive Landscape
Japanese and Chinese operators anchor one tier; European and Singaporean specialists hold contract positions in premium hazardous treatment segments. The market structure tiers around integrated service depth, with full-stack incumbents commanding long-term O&M retainers against unbundled transport and treatment specialists. Three archetypes dominate: state-backed domestic champions capturing municipal-industrial hybrid projects, Japanese precision specialists monetizing solvent recovery quotas, and European multinationals leveraging cross-border technology licensing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with operators securing decade-long service agreements ahead of regulatory tightening.
Within the precision-specialist tier, Daiseki Co., Ltd. exemplifies solvent recycling and industrial wastewater recovery positioning, while Veolia Environnement S.A. occupies a position reflecting integrated treatment network breadth. China Everbright Environment Group Ltd represents the state-backed domestic champion archetype in municipal-industrial hybrid procurement environments.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Daiseki Co., Ltd. |
| China Everbright Environment Group Ltd |
| Sembcorp Industries Ltd |
| Hitachi Zosen Corporation |
| Covanta Holding Corp. |
| Waste Management, Inc. |
| Clean Harbors, Inc. |
| Remondis SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
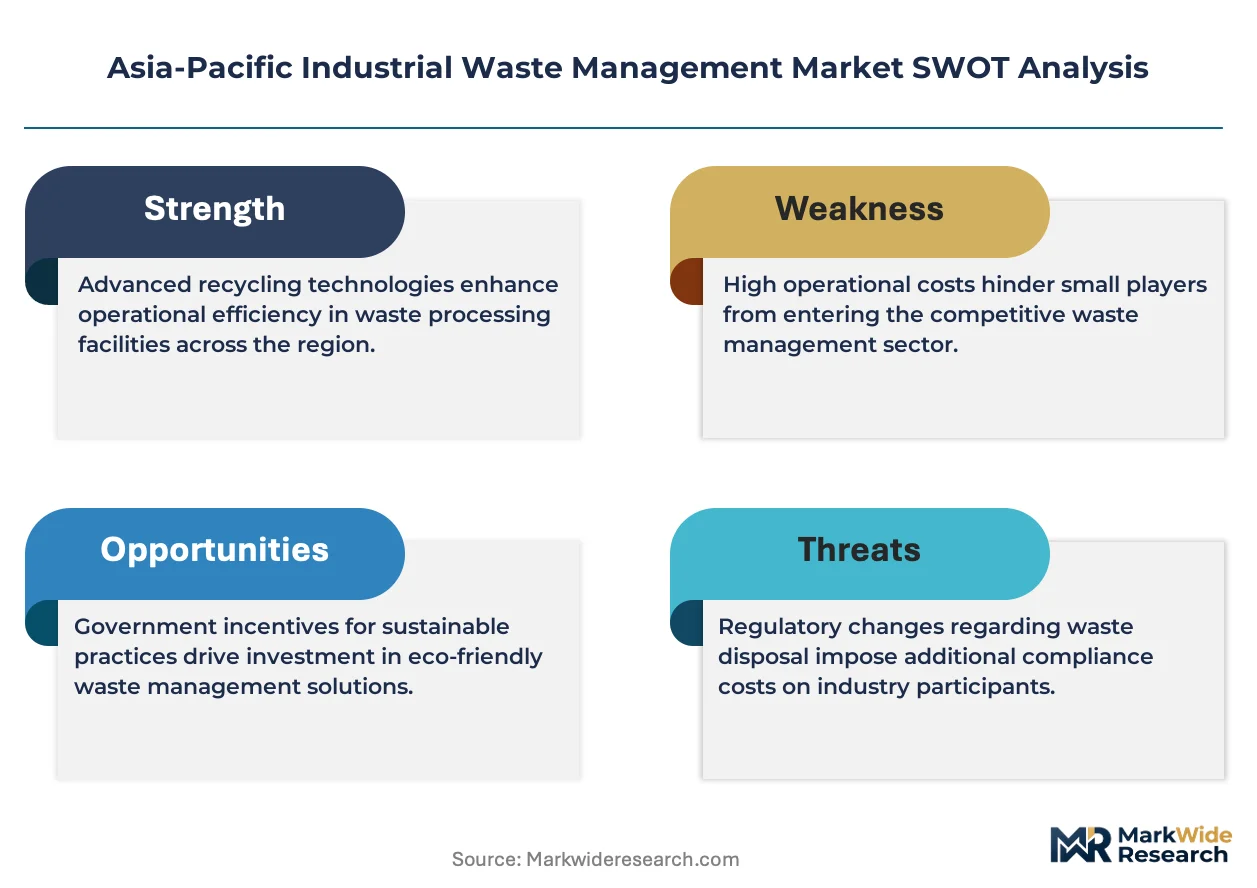
Outsourced treatment integration anchors both supply positioning and pricing power across Asia-Pacific industrial waste markets. China's MEE discharge permit trading compresses margins for aging on-site facilities while rewarding third-party specialists with long-term service agreements.
Pricing Analysis
Volume-based contracts dominate low-margin collection tiers while premium treatment commands fixed-fee structures with decade-long visibility. Price differentiation rests on MEE certification tiers and hazardous cargo handling licenses from Japan's METI. Cost compression in standard thermal treatment intensifies as plasma gasification displaces rotary kiln capacity. Electronics manufacturers in Jiangsu province exhibit highest price sensitivity; pharmaceutical and semiconductor fabs accept premium pricing for audit-ready documentation.
Supply Chain Analysis
Direct-to-manufacturer contracts handle hazardous waste flows from chemical and electronics clusters in eastern China. Equipment supply draws from German pyrolysis specialists and Japanese plasma arc system providers. Feedstock concentration around Shanghai and Suzhou creates single-source vulnerability for specialized haulers. Distribution runs through state-backed domestic champions for municipal-industrial hybrid projects and European multinationals for cross-border technology licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma gasification systems are displacing conventional incineration, compressing residue volumes and opening vitrified slag revenue streams. This technology transition rewards operators with advanced thermal treatment capabilities and penalizes legacy rotary kiln dependent portfolios.
For Market Incumbents: Acquire plasma gasification and supercritical water oxidation assets before MEE permitting caps new thermal capacity entry. Consolidate solvent recycling capabilities in Japan's Kansai region to capture METI-enforced material recovery quota demand. Defensive positioning requires backward integration into hazardous cargo fleets around Shanghai and Suzhou manufacturing clusters. For New Entrants and Emerging Players: Electronics assembly contractors in Vietnam's northern provinces around Hai Phong represent the most penetrable channel partner type for integrated treatment park development. White-space concentration in blockchain-enabled manifest platforms serves South Korean and Australian multinationals with Scope 3 disclosure obligations. Early-mover positioning before regulatory framework maturation secures decade-long O&M retainers. For Investors and Strategic Acquirers: Exit pathways concentrate in state-backed domestic champions capturing municipal-industrial hybrid procurement and Japanese precision specialists monetizing closed-loop recycling contracts. Long-term viability favors operators with hazardous waste treatment licenses in China's chemical manufacturing heartland. The signal to monitor is MEE discharge permit trading volume as an indicator of outsourcing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Capacity Buildout | Captures premium hazardous waste contracts from PCB etching and electroplating clusters in Jiangsu province. |
| Backward Integration into Hazardous Transport Fleets | Secures collection margins previously fragmented to third-party logistics providers in Thailand's Eastern Economic Corridor. |
| Blockchain-Enabled Manifest Platform Deployment | Captures compliance-premium contracts from multinationals with Scope 3 disclosure obligations in South Korea. |
| Industrial Symbiosis Park Design Expertise | Locks in decade-long O&M retainers from China's pilot eco-industrial zones mandating by-product exchange. |
| Solvent Recycling Facility Expansion | Monetizes METI-enforced material recovery quotas from automotive and semiconductor fabs in Japan's Kansai region. |
Research Methodology
Document review covered MEE discharge permit databases, METI industrial waste manifest records, and state EPA landfill levy frameworks, complemented by interviews with thermal treatment plant managers, hazardous waste logistics operators, chemical manufacturer procurement leads, and circular economy compliance officers. Secondary validation drew from customs trade data for pyrolysis equipment imports, SEC filings for publicly listed operators, and industry association capacity surveys. Bottom-up facility-level capacity estimates were triangulated against top-down regional waste generation projections.
Segmentation outputs reflect service type, end-user industry, waste toxicity classification, and treatment technology deployed across the modeling period. CAGRs were derived from facility deployment timelines, regulatory phase-in schedules, and contract renewal patterns. Forecast inputs incorporated MEE carbon intensity benchmark trajectories and METI material recovery quota enforcement intensity.
Caveats apply where MEE permitting delays, currency volatility for German and Japanese equipment imports, or retroactive groundwater monitoring liability in Australia could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Europe Medical Waste Management Market