
 Waste Compactor Bins Market | 2026-2036
Waste Compactor Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Compactor Bins Market Insights
Chinese steel-fabrication clusters is broadening output capacity for heavy-gauge compactor housings. Wastequip leverages its North American distribution network to anchor regional service density. Marathon Equipment Company sustains engineering intensity in high-force hydraulic systems. PTR Baler & Compactor differentiates through vertical integration into custom control panels.
Waste compactor bins are enclosed steel or polymer vessels with integrated hydraulic plungers that reduce refuse volume by ratios typically exceeding four-to-one, serving commercial and municipal generators seeking lower haulage frequency. Stationary compactors dominate installed base economics where permanent waste streams justify concrete pad foundations, while mobile compactors capture growth in event-driven and construction-site applications. Steel construction commands premium positioning in food processing and hazardous-adjacent streams, whereas high-density polyethylene penetrates educational institutions and hospitality settings where corrosion resistance and lower tare weight matter.
EPA landfill rules and OSHA ergonomic standards shape product design mandates and site-permitting pathways in the United States, while EU Green Deal circular-economy targets and REACH material-compliance obligations constrain polymer sourcing and end-of-life recovery pathways across European supply chains. Stakeholders must monitor evolving extended-producer-responsibility frameworks and their downstream effects on bin-leasing versus ownership models.
Market Dynamics
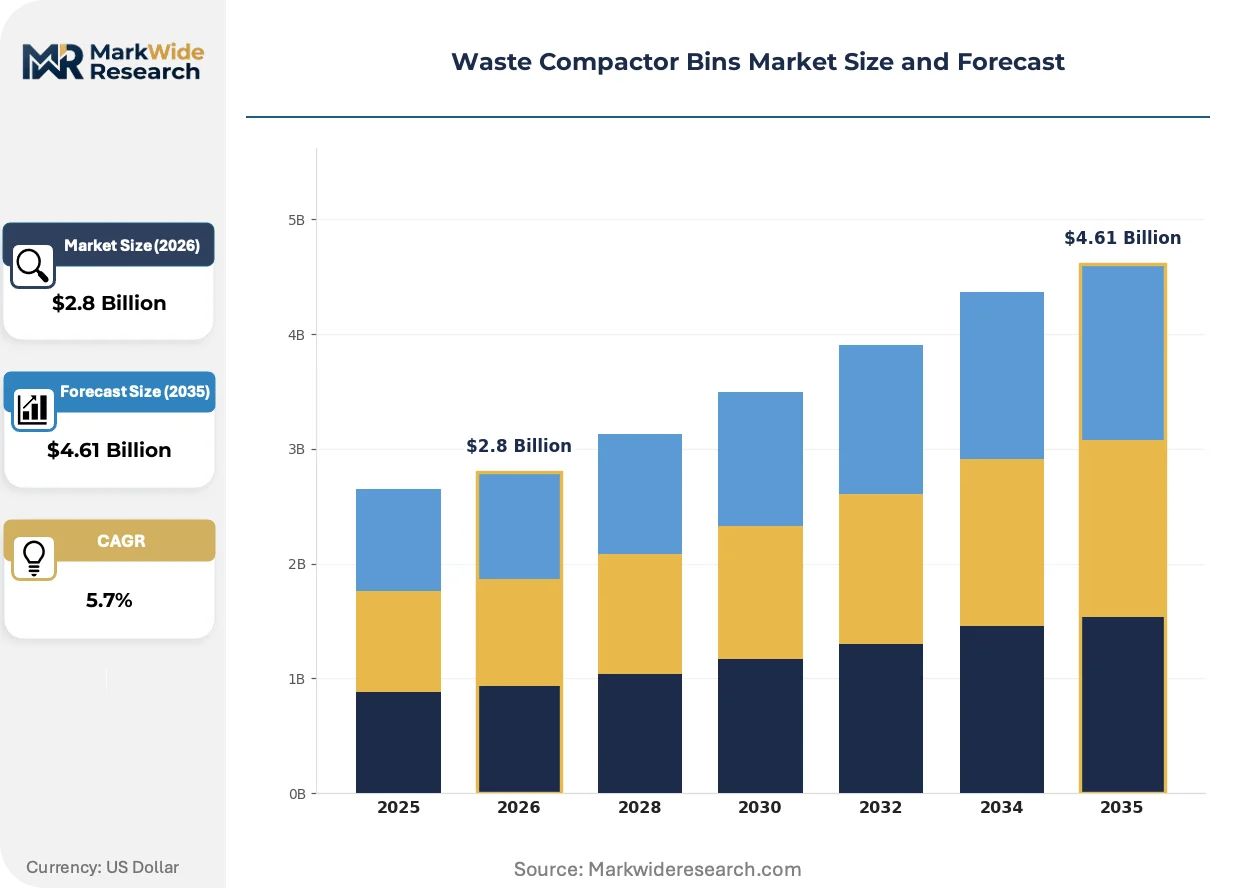
EU landfill diversion mandates are compressing collection cycles and forcing municipalities toward higher-density compaction infrastructure, while Chinese steel capacity expansion reshapes global supply economics for heavy-gauge housings.
Growth Catalysts
- EU Green Deal circular-economy targets:Germany's municipal waste agencies are accelerating stationary compactor procurement under tightened landfill diversion rules, creating sustained demand for concrete-pad foundation units.
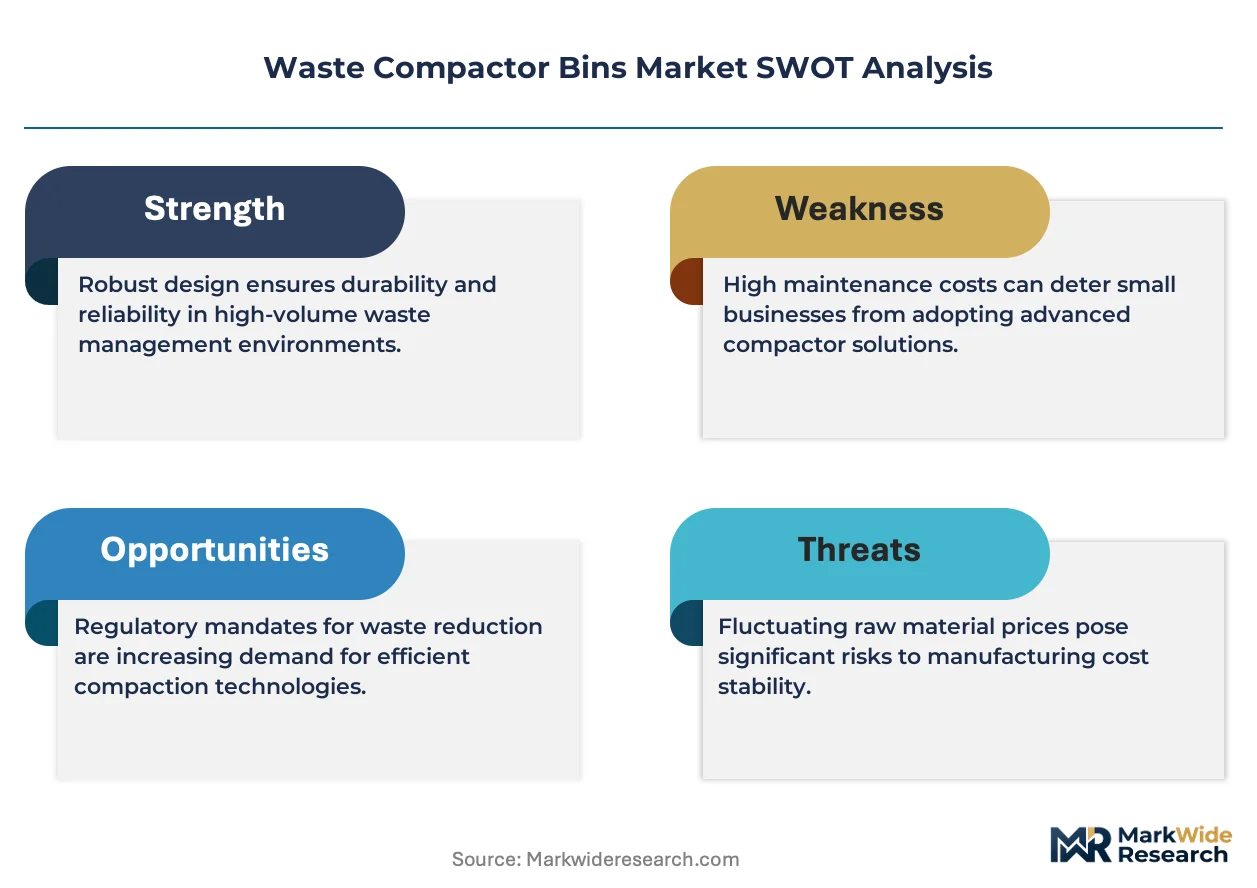
- Food processing sector corrosion requirements:Steel-bodied compactors command premium positioning in hazardous-adjacent waste streams where polymer degradation risks exceed operational tolerance thresholds.
- Japan's dense urban corridors:Mobile compactor orders concentrate in Tokyo and Osaka metropolitan zones where space constraints and event-driven waste surges favor portable hydraulic solutions.
Market Restraints
- High-gauge steel input volatility:Chinese steel-fabrication cluster output fluctuations transmit directly to compactor housing production costs, compressing margin stability for OEMs.
- REACH material-compliance obligations:European polymer sourcing faces constrained end-of-life recovery pathways, limiting high-density polyethylene penetration in circular-economy jurisdictions.
- Stationary unit foundation requirements:Permanent concrete pad installation creates capital intensity barriers for small-scale commercial generators with intermittent waste streams.
Strategic Opportunities
- Construction-site waste surge:Mobile compactors capture growth in Japan's infrastructure renewal projects where temporary installation and rapid relocation dominate procurement specifications.
- Extended-producer-responsibility frameworks:EU member states are piloting bin-leasing versus ownership models that shift capital burden from generators to equipment financiers.
- IoT-hydraulic convergence:Sensor-integrated fill-level monitoring is enabling predictive haulage scheduling, reducing truck rolls and municipal fleet operating expenditures.
Industry Challenges
- Hydraulic systems engineering scarcity:High-force plunger design expertise concentrates among legacy equipment specialists, constraining new entrant R&D velocity.
- OSHA ergonomic compliance timelines:US facility operators face site-permitting pathway delays when retrofitting existing waste handling infrastructure for operator safety mandates.
- Legacy control panel integration:Custom electronics from established vendors create proprietary lock-in effects that complicate third-party maintenance and software upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Compactor Bins Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Compactors, Mobile Compactors, Semi-Automatic Bins, Fully Automatic Bins, Portable Bins Material: Steel, High-Density Polyethylene, Stainless Steel, Aluminum, Composite Materials Application: Commercial Complexes, Municipal Waste Management, Hospitality Sector, Educational Institutions, Food Processing Units End User: Waste Collection Agencies, Manufacturing Facilities, Event Management Companies, Public Facilities, Logistics Providers |
| Companies Covered | Wastequip, Marathon Equipment Company, PTR Baler & Compactor, Harmony Enterprises, Compactors Inc., ACE Equipment Company, Sebright Products, Bergmann Direct, Pakawaste, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Compactor Bins Market Trends and Innovations
Connected compaction infrastructure is rewiring how waste generators optimize haulage economics, while material science advances and procurement model experimentation create parallel vectors of competitive differentiation.
Sensor-enabled fill monitoring is decentralizing route optimization authority from centralized fleet dispatchers to on-site equipment intelligence. Retail distribution centers and hospital complexes are adopting these systems fastest, with payback periods compressing below eighteen months for high-volume generators. The technology is decentralizing traditional waste broker intermediation by giving generators direct visibility into container status.
EPA landfill rules are tightening methane capture requirements for municipal disposal facilities, forcing upstream collection efficiency improvements. Industrial consequence includes accelerated replacement cycles for legacy compactors with suboptimal compression ratios. Food processing and pharmaceutical manufacturing facilities in the US Southeast face the steepest compliance cost escalation and are pre-purchasing next-generation hydraulic systems.
Leasing structures are displacing capital purchase for mid-scale commercial accounts. Equipment financiers are bundling maintenance and telemetry services into per-ton pricing, compressing traditional distributor margin pools. This shift is most visible in Germany's Mittelstand manufacturing belt and comparable industrial zones in the US Midwest where working capital sensitivity runs highest among family-owned operations.
Waste Compactor Bins Market Segmentation
Compactor bin procurement patterns diverge sharply across generator types and installation permanence. Material selection and mobility requirements create distinct margin pools that OEMs must navigate simultaneously.
Product Type:
Supply concentration among hydraulic system specialists favors stationary and mobile platforms over emerging automation tiers.
- Stationary Compactors:Fixed concrete-pad installations with high-force hydraulic plungers achieving compression ratios exceeding four-to-one. German municipal agencies under EU Green Deal mandates are expanding fleet procurement of these units for permanent waste streams.
- Mobile Compactors:Trailer-mounted or skid-based units with rapid relocation capability for temporary installations. Tokyo and Osaka metropolitan corridors concentrate orders where space constraints and event-driven surges dominate procurement specifications.
- Semi-Automatic Bins:Intermediate automation with partial hydraulic assist requiring manual loading initiation.
- Fully Automatic Bins:Sensor-triggered compression cycles with integrated fill-level monitoring for predictive haulage scheduling.
- Portable Bins:Lightweight manual or foot-pedal compression for small-scale commercial generators with intermittent waste streams.
Today's leader: Stationary Compactors. Tomorrow's challenger: Mobile Compactors.
Material:
Cost tier separation between corrosion-resistant premium grades and commodity steel shapes procurement behavior across end-use verticals.
- Steel:Heavy-gauge carbon steel housings dominate commercial demand in the United States for food processing and hazardous-adjacent streams where structural integrity commands premium positioning.
- High-Density Polyethylene:Corrosion-resistant polymer construction penetrates educational institutions and hospitality settings where lower tare weight and chemical resistance matter more than compression force tolerance.
- Stainless Steel:Medical-grade and pharmaceutical manufacturing applications requiring sterile handling protocols.
- Aluminum:Weight-sensitive mobile applications where transport efficiency overrides material cost premiums.
- Composite Materials:Emerging hybrid constructions combining fiber reinforcement with polymer matrices for specialized corrosion environments.
Steel commands current volume leadership. High-Density Polyethylene is climbing the fastest as REACH compliance constraints reshape European polymer sourcing economics.
Application:
Volume concentration in municipal and commercial channels leaves hospitality and education as margin expansion targets.
- Commercial Complexes:Retail distribution centers and hospital complexes adopt sensor-enabled fill monitoring fastest, with payback periods compressing below eighteen months for high-volume generators.
- Municipal Waste Management:Public sector procurement under EPA landfill rules and EU landfill diversion mandates drives replacement cycles for legacy compactors with suboptimal compression ratios.
- Hospitality Sector:Hotels and resorts prioritize corrosion-resistant materials for wet waste streams and aesthetic integration with facility design.
- Educational Institutions:K-12 and university campuses favor lower-tare polymer construction for student-operated collection points.
- Food Processing Units:USDA-inspected facilities require steel construction with sanitary welding standards for organic waste handling.
Municipal Waste Management anchors installed base economics. Commercial Complexes are gaining share fastest through IoT-hydraulic convergence.
End User:
Customer type fragmentation between capital-owning agencies and service-outsourced facilities creates divergent sales cycle dynamics.
- Waste Collection Agencies:Municipal and private haulers specifying equipment for generator lease programs under extended-producer-responsibility frameworks piloted in EU member states.
- Manufacturing Facilities:Germany's Mittelstand manufacturing belt and comparable US Midwest industrial zones show highest working capital sensitivity, driving leasing structure adoption.
- Event Management Companies:Temporary installation specialists favoring mobile compactors for rapid deployment and relocation.
- Public Facilities:Government-owned infrastructure with constrained capital budgets and extended procurement timelines.
- Logistics Providers:Distribution centers optimizing container utilization for reverse logistics and packaging waste consolidation.
Waste Collection Agencies dominate current procurement volume. Manufacturing Facilities represent the steepest expansion trajectory as equipment financiers bundle maintenance and telemetry into per-ton pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping compactor bin sourcing patterns as Chinese steel-fabrication clusters exploit REACH compliance gaps to capture housing production share from European fabricators facing constrained polymer recovery pathways.
United States
Steel-bodied stationary units dominate food processing procurement across the US Southeast where USDA sanitary welding standards intersect with EPA landfill methane capture rules. OSHA ergonomic compliance timelines are forcing site-permitting pathway delays for facility retrofits. Houston and Dallas-Fort Worth industrial corridors concentrate distributor service density for high-force hydraulic systems.
Germany
Municipal waste agencies under EU Green Deal circular-economy targets are accelerating stationary compactor fleet procurement for concrete-pad foundation installations. REACH material-compliance obligations constrain high-density polyethylene sourcing for circular-economy jurisdictions. Bavaria's Mittelstand manufacturing belt pilots bin-leasing versus ownership models that shift capital burden to equipment financiers.
China
Heavy-gauge carbon steel housing production concentrates in Yangtze River Delta fabrication clusters serving export demand for corrosion-resistant premium grades. The country's national environmental regulator enforces dual carbon goals that reshape foundry energy intensity standards. Shanghai and Ningbo port infrastructure enables containerized export of mobile compactor subassemblies.
Japan
Mobile compactor orders concentrate in Tokyo and Osaka metropolitan corridors where space constraints and event-driven waste surges favor portable hydraulic solutions. METI industrial efficiency standards compress collection cycles for dense urban generators. Kanto region construction-site waste from infrastructure renewal projects drives temporary installation specifications.
India
High-density polyethylene penetration accelerates in educational institutions and hospitality settings where lower tare weight reduces student-operated collection point hazards. BIS standards for waste handling equipment create certification barriers for imported steel housings. Maharashtra and Gujarat industrial zones concentrate domestic fabrication capacity for mid-scale commercial accounts.
Waste Compactor Bins Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT-hydraulic convergence and leasing-structure bundling to bypass incumbent service networks. The vendor base stratifies across legacy hydraulic specialists, steel-fabrication generalists, and telemetry-integrated challengers. Two dominant competitive moves are reshaping positioning: geographic expansion through distributor acquisition in North American secondary markets, and backward integration into custom control panel production to capture maintenance revenue streams.
Among North American equipment specialists, Wastequip, Marathon Equipment Company, and PTR Baler & Compactor represent distinct archetype positions. Wastequip anchors regional service density through distribution network control. Marathon Equipment Company exemplifies engineering intensity concentration in high-force hydraulic systems. PTR Baler & Compactor occupies a position defined by in-house production of custom control panels. These three firms collectively illustrate how competitive differentiation vectors split across physical infrastructure, technical specialization, and captive electronics supply.
| Leading Market Players |
|---|
| Wastequip |
| Marathon Equipment Company |
| PTR Baler & Compactor |
| Harmony Enterprises |
| Compactors Inc. |
| ACE Equipment Company |
| Sebright Products |
| Bergmann Direct |
| Pakawaste |
| Others |
Pricing and Supply Chain Analysis
Hydraulic systems engineering expertise concentrated in legacy equipment specialists across the US Midwest and German industrial zones drives labor-cost differentials that widen pricing-tier spreads between premium steel-bodied units and commodity polymer alternatives. Chinese steel-fabrication clusters exploit these skill premiums by exporting heavy-gauge housings at compressed cost bases, forcing OEMs to differentiate through bundled telemetry services rather than hardware margins alone.
Pricing Analysis
Distributor margin layers compress as equipment financiers bundle maintenance and telemetry into per-ton pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified steel units for food processing from REACH-constrained polymer alternatives and basic manual portable bins. Price differentiation hinges on compression ratio certification and after-sales service density. Cost compression in mid-scale commercial tiers is intensifying because leasing structures displace capital purchases among working-capital-sensitive family-owned operations. Small-scale commercial generators with intermittent waste streams exhibit highest price sensitivity; municipal waste agencies under EU Green Deal mandates demonstrate lowest.
Supply Chain Analysis
Heavy-gauge carbon steel supply rests on Yangtze River Delta fabrication clusters, German Ruhr industrial belt foundries, and US Great Lakes regional mills. Raw material dependencies include high-strength steel plate, hydraulic pump assemblies, and sensor-integrated control modules. Single-source vulnerability concentrates in Japanese specialty hydraulic component producers serving high-force plunger designs. Distribution runs through North American distributor networks anchored by regional service density, European equipment financiers piloting lease-bundling models, and Japanese construction-site rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste compactor bins function as a stable compounder anchored by landfill diversion mandates that perpetually refresh municipal replacement cycles regardless of macroeconomic cyclicality.
For Market Incumbents: Cement service network density in secondary North American markets through distributor acquisition before telemetry-integrated challengers establish footholds. Deepen backward integration into custom control panel production to capture maintenance revenue streams and complicate third-party software upgrade pathways for installed base lock-in. Hydraulic systems engineering scarcity constrains new entrant R&D velocity, creating defensive moats for legacy specialists.
For New Entrants and Emerging Players: Capture construction-site waste surge in Japan's Kanto region infrastructure renewal projects where temporary installation specifications favor rapid-deployment mobile compactors. Target India's educational institution segment where high-density polyethylene penetration accelerates among student-operated collection points with lower tare weight requirements. Pursue IoT-hydraulic convergence go-to-market angle with sensor-enabled fill monitoring that compresses payback periods below eighteen months for hospital complexes.
For Investors and Strategic Acquirers: Waste management equipment financiers are the most active acquirer in this space as extended-producer-responsibility frameworks shift capital burden from generators to lessors. Long-term viability frames around circular-economy infrastructure permanence rather than cyclical capital expenditure cycles. Acquisition target archetype: telemetry-integrated challengers with installed base in commercial complexes. Watch EU member state pilot programs for bin-leasing versus ownership model adoption rates as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Panels | Captures maintenance revenue streams from Wastequip and Marathon Equipment installed bases. |
| Sensor-Enabled Fill Monitoring Launch | Enables predictive haulage scheduling for retail distribution centers under EPA methane rules. |
| Mobile Compactor Capacity Expansion | Serves Tokyo construction-site waste from METI infrastructure renewal mandates. |
| Leasing Structure Bundling | Shifts capital burden to equipment financiers in Germany's Mittelstand manufacturing belt. |
| REACH-Compliant Polymer Sourcing | Unlocks circular-economy jurisdictions constrained by ECHA material-compliance obligations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from municipal procurement officers, waste hauler fleet managers, food processing plant engineers, equipment financier risk officers, and hydraulic systems maintenance directors. Secondary validation drew from EPA landfill rule filings, EU Green Deal implementation documents, ECHA REACH substance databases, and customs trade data for steel and polymer inputs. Bottom-up unit economics triangulated against top-down municipal expenditure forecasts.
Segment-weighting approach distributed value across stationary versus mobile product types, steel versus high-density polyethylene material tiers, and municipal versus commercial application channels. CAGRs derived from replacement cycle analysis under regulatory compliance timelines and infrastructure investment patterns. Forecast inputs included EU landfill diversion mandate enforcement schedules and Chinese steel capacity expansion trajectories.
Steel price volatility, REACH regulatory amendment timelines, and IoT-hydraulic convergence adoption curves are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology penetration rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market