
 US Influenza Vaccine Market | 2026-2036
US Influenza Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
US Influenza Vaccine Market Insights
Retail pharmacy distribution is narrowing as CVS Health and Walgreens consolidate seasonal vaccine purchasing power across thousands of US locations. Sanofi leverages its quadrivalent manufacturing scale to anchor supply contracts with major pharmacy networks. GlaxoSmithKline competes through adjuvanted formulations targeting adults aged sixty-five and older. CSL Seqirus specializes in cell-based production, differentiating its portfolio from egg-dependent alternatives.
The US Influenza Vaccine comprises immunological preparations designed to induce adaptive immunity against circulating influenza A and B virus strains, formulated annually based on WHO strain recommendations and manufactured through egg-based, cell culture, or recombinant protein platforms with standard doses containing fifteen micrograms of hemagglutinin antigen per strain. Its primary commercial purpose centers on reducing influenza-related morbidity, hospitalization, and mortality through population-level immunization programs administered prior to each respiratory virus season. Inactivated vaccines dominate volume due to decades of safety data and broad age indications, while recombinant formulations capture premium positioning through egg-free manufacturing and higher antigen content. Cell-based production occupies a growing niche as manufacturers seek supply resilience independent of embryonated egg supply chains.
FDA oversight through the Center for Biologics Evaluation and Research governs strain selection, potency testing, and lot release timelines, compressing the manufacturing window between February strain announcement and August distribution launch. CDC Advisory Committee on Immunization Practices recommendations directly shape reimbursement and provider stocking decisions through the Vaccines for Children program and Medicare Part B coverage determinations. OSHA bloodborne pathogen standards and state-level pharmacist immunization authority expansions further extend administration access beyond traditional physician offices. Stakeholders must monitor mRNA platform entrants from Moderna and Pfizer as these technologies threaten to displace conventional manufacturing economics within the seasonal flu procurement cycle.
Market Dynamics
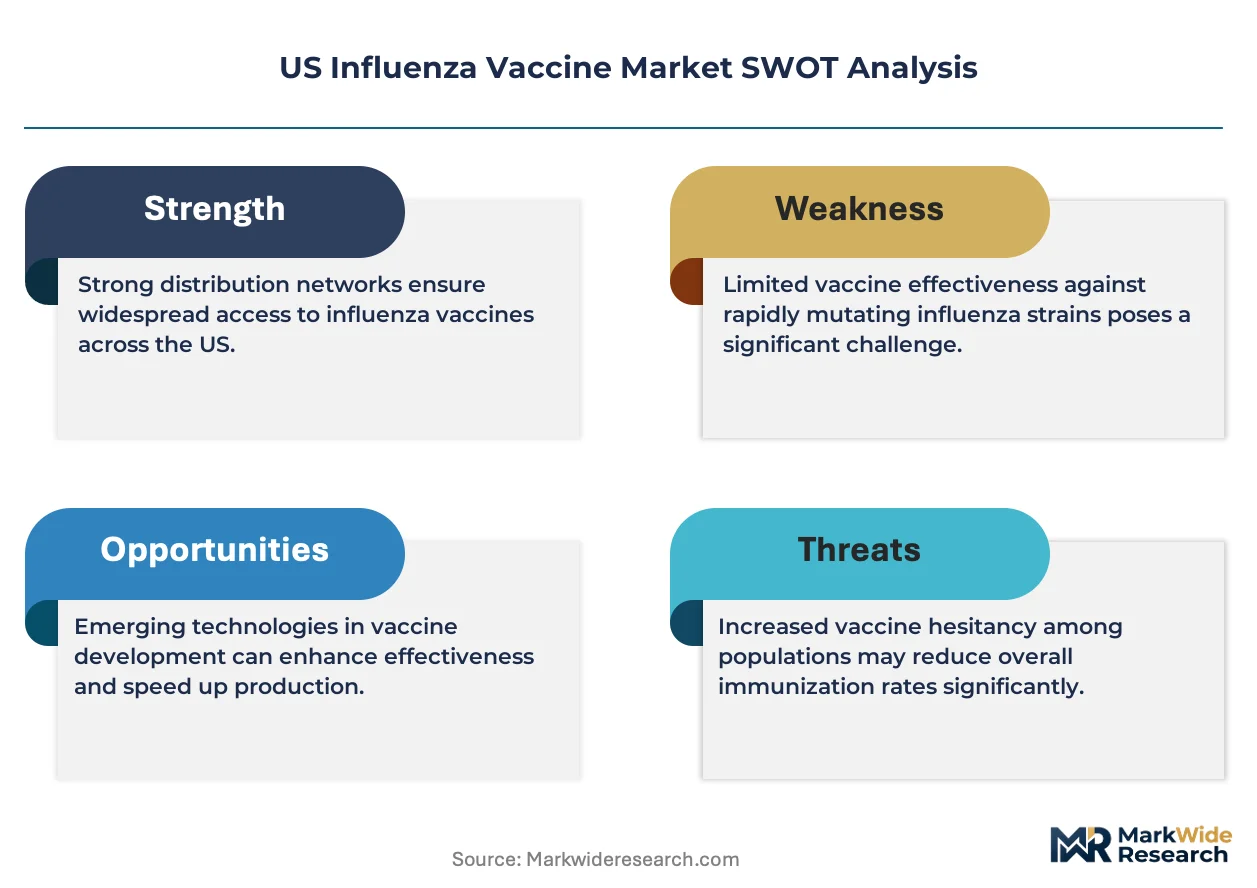
mRNA platform development is compressing traditional manufacturing timelines and threatening established egg-based production economics across seasonal flu procurement cycles.
Growth Catalysts
- OSHA bloodborne pathogen standards:Expanded pharmacist immunization authority in multiple states now permits vaccine administration outside traditional physician offices, broadening access points for working-age adults.
- Geriatric population concentration:Sun Belt states including Florida, Arizona, and Texas exhibit disproportionate demand for high-dose formulations among adults aged sixty-five and older, anchoring premium segment volume.
- Cell culture manufacturing:Production platforms independent of embryonated egg supply chains are gaining procurement preference from pharmacy networks seeking supply resilience against avian influenza disruptions.
Market Restraints
- Egg supply concentration:Domestic embryonated egg production remains geographically concentrated in specific agricultural regions, creating vulnerability to avian disease outbreaks that compress manufacturing windows.
- CMS reimbursement compression:Medicare Part B payment rates for seasonal influenza vaccines limit provider margin expansion despite rising antigen production costs.
- Strain mismatch risk:WHO strain selection occurs eight months before peak season circulation, creating inherent antigenic drift exposure that undermines vaccine effectiveness in mismatched years.
Strategic Opportunities
- Occupational health mandates:Large employer vaccination requirements in healthcare, education, and logistics sectors are creating institutional procurement channels with multi-year contract potential.
- Recombinant protein convergence:Combination vaccines pairing influenza with COVID-19 or RSV antigens are opening development pathways for differentiated annual immunization products.
- Retail clinic expansion:MinuteClinic and similar in-pharmacy healthcare delivery models are converting seasonal vaccine visits into longitudinal patient relationships with recurring revenue potential.
Industry Challenges
- Specialized biomanufacturing workforce:Cell-based and mRNA production platforms require fermentation and lipid nanoparticle expertise that remains scarce in traditional vaccine manufacturing labor pools.
- Lot release timeline compression:FDA potency testing and Center for Biologics Evaluation and Research release procedures create distribution bottlenecks during August-September launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Influenza Vaccine Market |
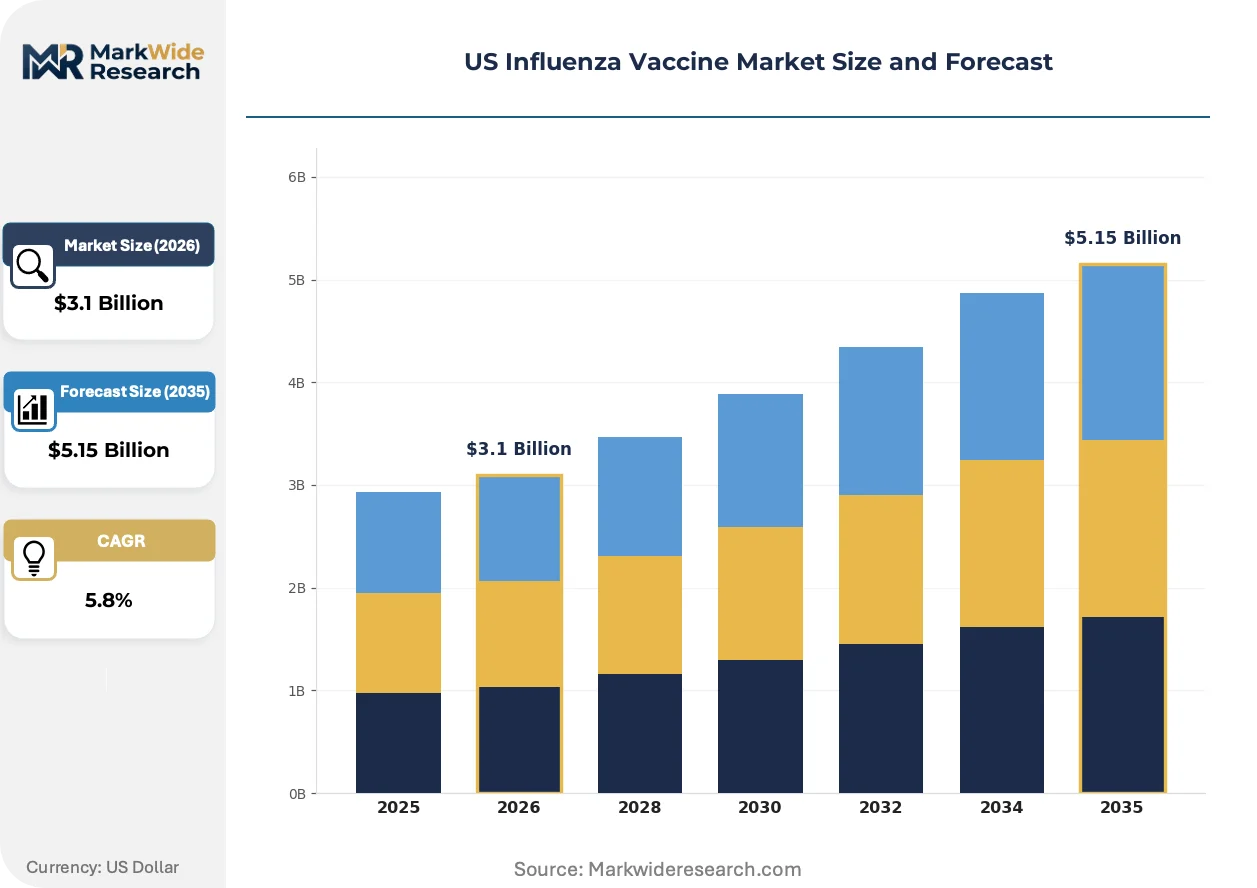
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Recombinant, Adjuvanted, Cell-Based Application: Seasonal Immunization, Pandemic Preparedness, Geriatric Vaccination, Pediatric Vaccination, Occupational Health End User: Hospitals, Clinics, Pharmacies, Occupational Health Providers, Community Health Centers Distribution Channel: Retail Pharmacy, Hospital Pharmacies, Government Immunization Programs, Direct Manufacturer Supply, Online Pharmacies |
| Companies Covered | Sanofi, GlaxoSmithKline, CSL Seqirus, AstraZeneca, Pfizer, Merck & Co, Moderna, Novavax, GSK PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Influenza Vaccine Market Trends and Innovations
Platform diversification is fragmenting manufacturing economics as mRNA entrants challenge decades of process optimization in egg-based and cell culture systems.
Recombinant hemagglutinin vaccines produced in insect cell lines are hybridizing the market by offering egg-free manufacturing with higher antigen content per dose. Pharmacy chains with quality-sensitive procurement policies are adopting these formulations for premium patient segments despite per-dose cost premiums. This technology is compressing the historical correlation between manufacturing scale and cost advantage that protected incumbent suppliers.
FDA accelerated approval pathways for novel platform influenza vaccines are shortening development timelines for mRNA-based seasonal candidates. The regulatory shift pressures established manufacturers to demonstrate non-inferior immunogenicity against new entrants while maintaining supply commitments. Adults aged fifty and older represent the segment most affected, as adjuvanted and high-dose formulations face direct competition from platform innovations.
Employer-sponsored vaccination programs are displacing individual retail purchases as the dominant procurement channel for working-age adults. Large occupational health contracts now concentrate demand among national pharmacy networks with multi-site administration capabilities. Texas and Florida manufacturing and logistics corridors exhibit the most visible shift, where seasonal workforce vaccination has become a standard liability management practice.
US Influenza Vaccine Market Segmentation
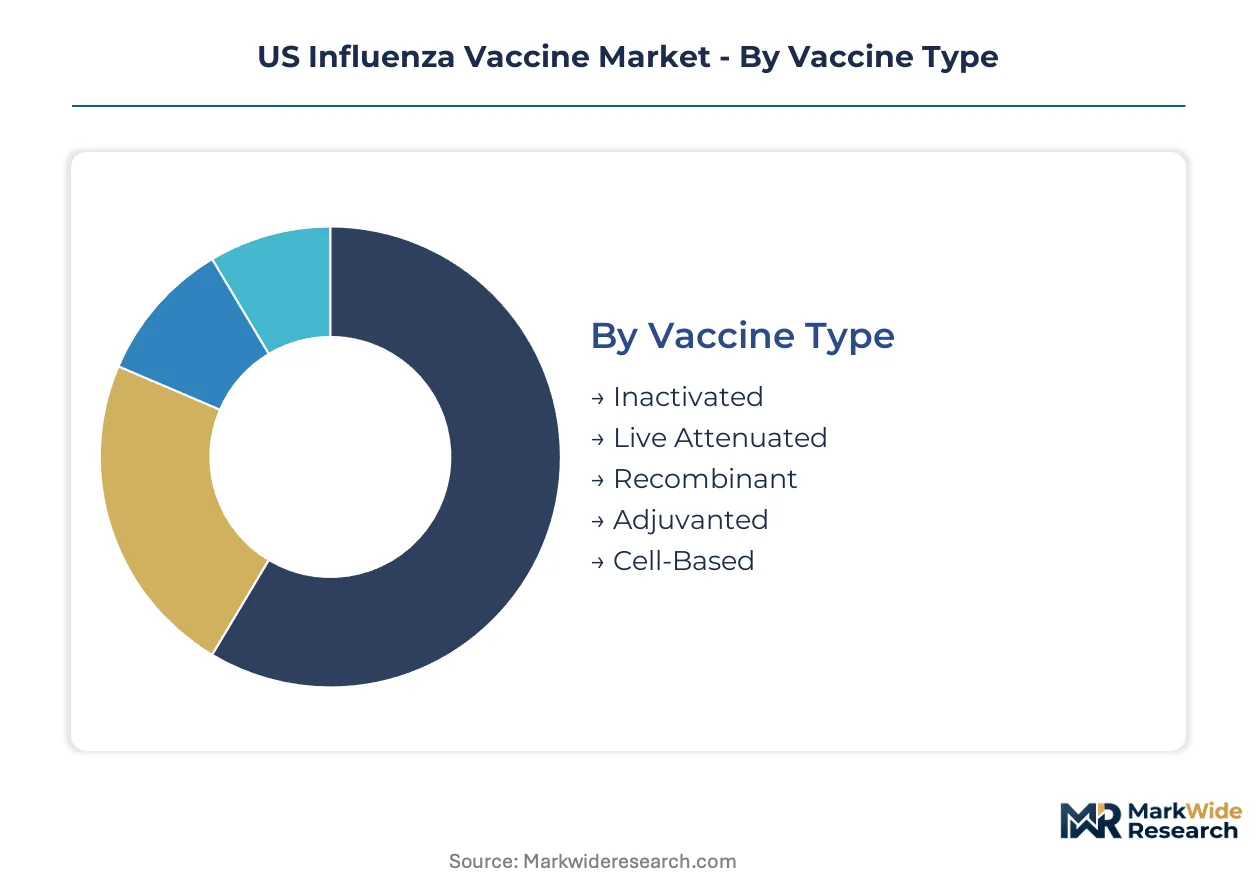
Platform diversity and patient-specific formulation requirements create distinct commercial segments across the US influenza vaccine landscape. Procurement patterns vary sharply between institutional buyers and retail channels, with reimbursement pathways further fragmenting demand by end-user type.
Vaccine Type:
Formulation technology determines manufacturing cost structure, cold chain requirements, and eligible patient populations across the use-case spectrum.
- Inactivated:Split-virus and subunit formulations containing fifteen micrograms of hemagglutinin per strain dominate volume through decades of safety documentation and broad age indications from six months upward. Demand concentrates in pediatric and standard adult segments where CDC guidelines prioritize established immunogenicity profiles, though egg-dependent production creates supply vulnerability during avian influenza outbreaks.
- Adjuvanted:MF59-containing formulations deliver enhanced antigen presentation for adults aged sixty-five and older, commanding premium reimbursement through Medicare Part B. Florida, Arizona, and Texas geriatric populations anchor demand as Sun Belt retirement migration concentrates high-dose eligible patients in pharmacy network territories.
- Live Attenuated:Intranasal delivery suits needle-averse patients aged two through forty-nine, with CDC recommendations restricting use in immunocompromised populations and pregnant women.
- Recombinant:Insect cell-derived hemagglutinin offers egg-free manufacturing with higher antigen content, attracting quality-sensitive procurement from premium pharmacy tiers.
- Cell-Based:Madin-Darby Canine Kidney cell culture production eliminates egg supply chain dependence, gaining preference from networks seeking pandemic resilience.
The dominant share belongs to Inactivated formulations, while Adjuvanted is closing the gap fastest through Medicare reimbursement expansion.
Application:
Programmatic funding and liability frameworks reshape volume concentration across immunization settings.
- Seasonal Immunization:Annual pre-season campaigns targeting circulating H1N1, H3N2, and B strains constitute the commercial core, with CDC strain selection in February compressing manufacturing windows. Pharmacy chains in Texas and Florida execute the bulk of administration through state pharmacist authority expansions.
- Geriatric Vaccination:Adults aged sixty-five and older receive preferential access to high-dose and adjuvanted formulations under Medicare Part B, with Sun Belt states exhibiting disproportionate per-capita consumption.
- Pandemic Preparedness:H5N1 and H7N9 stockpiling contracts through the Strategic National Stockpile provide revenue floors for cell-based and recombinant manufacturers.
- Pediatric Vaccination:Vaccines for Children program procurement supplies Medicaid-eligible populations through pediatrician offices and community health centers.
- Occupational Health:Healthcare, education, and logistics employer mandates create institutional procurement channels with multi-year contract structures.
Seasonal Immunization commands the volume base, though Occupational Health is expanding most quickly through employer liability management adoption.
End User:
Administration site determines reimbursement rate, patient throughput, and formulation mix.
- Pharmacies:CVS Health and Walgreens locations administer the majority of working-age adult doses, leveraging MinuteClinic and similar models to convert seasonal visits into longitudinal relationships.
- Hospitals:Inpatient and emergency department administration captures high-risk patients with comorbidities, with formulary committees prioritizing quadrivalent coverage.
- Clinics:Physician office administration remains dominant for pediatric and geriatric populations with established provider relationships.
- Occupational Health Providers:On-site vaccination programs for manufacturing and logistics workforces concentrate demand in Texas and Florida corridors.
- Community Health Centers:Federally qualified health centers serve uninsured and underinsured populations through sliding-scale reimbursement.
Pharmacies hold the dominant position, while Occupational Health Providers are gaining share fastest through corporate mandate expansion.
Distribution Channel:
Channel selection reflects cold chain capability, purchase scale, and regulatory compliance requirements.
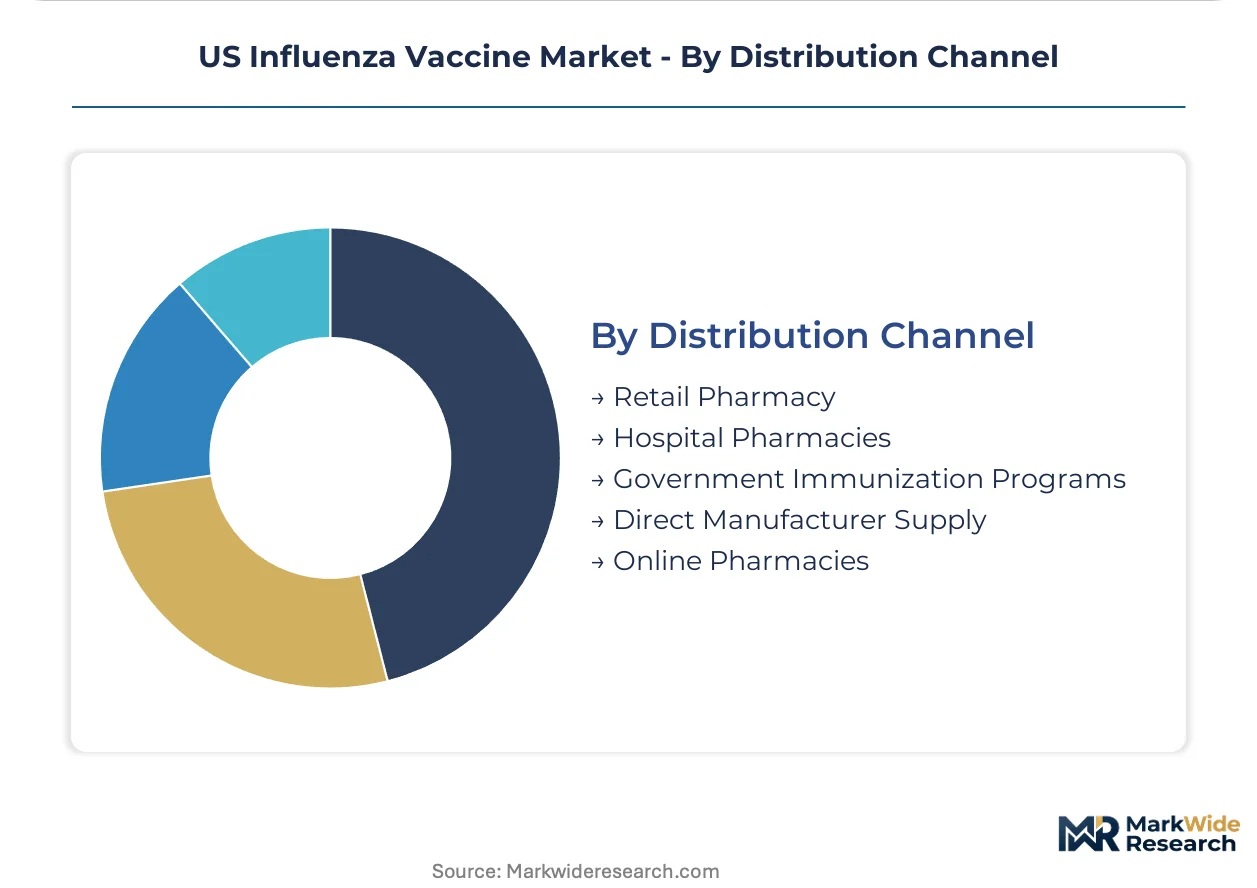
- Retail Pharmacy:Direct distribution from Sanofi, GSK, and CSL Seqirus to CVS Health and Walgreens distribution centers concentrates purchasing power and compresses wholesaler margins.
- Government Immunization Programs:CDC centralized purchasing through the Vaccines for Children program and Medicare Part B reimbursement frameworks set pricing benchmarks.
- Hospital Pharmacies:Group purchasing organization contracts aggregate demand from health system networks, with 340B pricing affecting eligible facilities.
- Direct Manufacturer Supply:Large occupational health contracts bypass wholesale tiers for national employers with multi-site administration needs.
- Online Pharmacies:Mail-order and digital pharmacy platforms serve rural populations and patients seeking home delivery convenience.
Retail Pharmacy dominates procurement volume, while Government Immunization Programs are expanding most quickly through Medicare reimbursement pathway growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command disproportionate pricing power through geriatric concentration and occupational health density, while Midwestern states face compressed margins due to fragmented provider networks and lower Medicare reimbursement intensity.
Texas
Manufacturing and logistics corridors anchor employer-mandated vaccination programs across Dallas-Fort Worth and Houston. OSHA compliance frameworks drive on-site occupational health contracts with multi-year structures. San Antonio and Austin pharmacy networks convert seasonal visits into longitudinal patient relationships through expanded pharmacist immunization authority.
Florida
Sun Belt retirement migration concentrates adults aged sixty-five and older in Miami-Dade, Broward, and Palm Beach counties. Medicare Part B reimbursement frameworks support premium adjuvanted and high-dose formulation procurement. Tampa and Orlando pharmacy chains execute bulk seasonal purchasing through consolidated distribution center contracts.
California
Los Angeles and San Francisco Bay Area occupational health programs serve technology and healthcare sector workforces with institutional procurement channels. State-level pharmacist authority expansions permit vaccine administration outside traditional physician offices. San Diego biomanufacturing clusters support cell-based production platform development.
New York Metro
Healthcare sector employer mandates concentrate demand in Manhattan and Brooklyn hospital networks with group purchasing organization contracts. CDC Vaccines for Children program procurement supplies Medicaid-eligible populations through community health centers. Long Island and Westchester retail pharmacy networks compete for working-age adult volume.
Illinois
Chicago metropolitan area hospital formulary committees prioritize quadrivalent coverage for high-risk patients with comorbidities. State-level reimbursement compression limits provider margin expansion despite rising antigen production costs. Peoria and Springfield community health centers serve uninsured populations through sliding-scale frameworks.
US Influenza Vaccine Market Competitive Landscape
Established vaccine manufacturers and mRNA platform entrants split the market between legacy manufacturing scale and accelerated development timelines. Sanofi, GlaxoSmithKline, and CSL Seqirus anchor supply contracts through decades of strain-matching expertise and quadrivalent portfolio breadth. Moderna and Pfizer represent the platform-innovation archetype, threatening incumbent economics through FDA accelerated approval pathways. Competitive moves center on manufacturing capacity reservation agreements and combination vaccine development partnerships.
Within the established-manufacturer tier, Sanofi leverages quadrivalent manufacturing scale to anchor pharmacy network contracts, while GlaxoSmithKline occupies a position in adjuvanted formulation segments targeting Medicare-eligible populations. CSL Seqirus exemplifies the cell-based specialization archetype, differentiating through production platforms independent of embryonated egg supply chains. Moderna and Pfizer represent the mRNA platform threat, compressing traditional strain-to-dose timelines and reshaping procurement expectations among pharmacy chains with quality-sensitive policies.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| CSL Seqirus |
| AstraZeneca |
| Pfizer |
| Merck & Co |
| Moderna |
| Novavax |
| GSK PLC |
| Others |
Pricing and Supply Chain Analysis
North Carolina biomanufacturing clusters anchor domestic influenza vaccine production capacity, with Sanofi and Seqirus facilities in Research Triangle Park translating fermentation scale into downstream pricing leverage against pharmacy network procurement teams.
Pricing Analysis
Configuration-to-order pricing for cell-based and recombinant formulations commands substantial premiums over standard egg-derived alternatives. Pricing stratifies across premium, standard, and economy tiers based on antigen content per dose and manufacturing platform certification level. Cost compression in standard inactivated segments is intensifying because CMS reimbursement rates lag antigen production cost inflation. Occupational health buyers exhibit lowest price sensitivity due to liability-driven mandate compliance, while uninsured retail patients face highest out-of-pocket exposure.
Supply Chain Analysis
Embryonated egg supply draws from concentrated agricultural regions in Iowa, Indiana, and Ohio, with SPF flock maintenance representing a critical upstream dependency. Madin-Darby Canine Kidney cell lines and insect cell culture media constitute alternative production inputs for platform-diversified manufacturers. Single-source vulnerability in embryonated egg supply creates pandemic disruption exposure against avian influenza outbreaks. Distribution runs through direct manufacturer-to-pharmacy contracts that bypass wholesale tiers for CVS Health and Walgreens network consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform entrants are accelerating an early-cycle expansion story in seasonal influenza immunization, with FDA accelerated approval pathways compressing development timelines and opening penetration gaps in adjuvanted formulation segments.
For Market Incumbents: Entrench quadrivalent manufacturing scale through capacity reservation agreements with pharmacy networks facing quality-sensitive procurement policies. Anchor supply contracts in Sun Belt geriatric corridors where Medicare Part B reimbursement supports premium formulation adoption. Defensive consolidation around cell-based production platforms mitigates egg supply chain vulnerability from avian influenza disruptions. For New Entrants and Emerging Players: Establish a beachhead in occupational health institutional procurement channels across Texas and Florida manufacturing corridors. Employer-mandated vaccination programs in logistics and healthcare sectors represent the most penetrable segment with multi-year contract structures. Pursue FDA accelerated approval pathway positioning to differentiate from decades of incumbent strain-matching expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to divest non-core vaccine manufacturing assets with stranded egg-based capacity. Long-term viability centers on platform diversification capability across mRNA, cell culture, and recombinant modalities. Watch for inflection signals in pharmacy network procurement policy shifts toward pandemic-resilient supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Platform Diversification | Cell-based and mRNA capacity reduces dependence on Iowa SPF egg supply chains. |
| Occupational Health Contract Expansion | Multi-year employer mandates in Texas logistics corridors anchor predictable revenue baselines. |
| Combination Vaccine Development | Pairing influenza with COVID-19 antigens opens differentiated annual immunization positioning. |
| Pharmacy Network Direct Supply | Bypassing wholesale tiers captures margin compression from CVS and Walgreens consolidation. |
| FDA Accelerated Approval Pathway | Compressed timelines for mRNA entrants reshape immunogenicity benchmarking expectations. |
Research Methodology
Operator-level perspectives from vaccine manufacturing executives, pharmacy procurement directors, CDC immunization program officers, and hospital formulary committee chairs anchored the qualitative base. Primary interview insights combined with secondary validation against FDA Center for Biologics Evaluation and Research filings, CDC Vaccines for Children program procurement databases, Medicare Part B reimbursement schedules, and American Hospital Association supply chain surveys. Bottom-up demand modeling and top-down production capacity triangulation cross-checked volume assumptions across the analysis window.
Scenario-bracketing framed the analytical approach across platform type, patient age segment, and regional regulatory cluster dimensions. CAGRs were derived from production capacity expansion timelines and procurement contract renewal patterns. Modeled inputs incorporated strain selection announcement-to-distribution compression effects, pharmacist immunization authority expansion trajectories, and employer mandate adoption curves in manufacturing and healthcare sectors.
Sensitivities concentrate around avian influenza outbreak probability, CMS reimbursement rate adjustments, and mRNA platform immunogenicity non-inferiority demonstration timing. Forecasts reflect documented assumptions regarding strain match effectiveness and pharmacy network purchasing consolidation. Quarterly review of FDA lot release timelines, CDC strain selection drift patterns, and occupational health contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market