
 Global Thrombin Market | 2026-2036
Global Thrombin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thrombin Market Foresight
Hospital purchasing of thrombin for cardiovascular procedures is shifting toward recombinant and human-derived formats as surgical volumes rise in aging populations. Pfizer Inc. leverages its biologics manufacturing scale to supply recombinant thrombin across North American and European hospital networks. Johnson & Johnson Services, Inc. anchors its position through Ethicon's surgical hemostasis portfolio and deep integration with operating room supply chains. Baxter competes on plasma-derived thrombin volume, sustaining cost advantages in emerging hospital systems through established fractionation infrastructure.
Thrombin is a serine protease enzyme that catalyzes the conversion of fibrinogen to fibrin, forming blood clots through a calcium-dependent enzymatic cascade with molecular weight approximately 36 kDa. Manufacturers produce it through plasma fractionation, bovine lung extraction, or recombinant DNA expression in mammalian cell cultures for topical and injectable hemostatic applications. Recombinant thrombin commands premium positioning due to eliminated viral and immunogenic risk from animal sources, while human-derived product maintains volume leadership in cost-sensitive hospital procurement. Delivery mode segmentation shows topical formulations dominating current surgical use, though powder and gel formats are capturing share in minimally invasive procedures where controlled application geometry matters.
FDA biologics licensing requirements and EMA plasma master file standards shape product registration timelines and manufacturing audit intensity for thrombin suppliers. ISO 13485 quality management and EU MDR device classification for combination hemostats further constrain market entry for new manufacturers. Stakeholders must monitor regulatory divergence between FDA's evolving guidance on recombinant blood proteins and China's NMPA pathway for imported plasma derivatives, as these frameworks will determine which production technologies achieve multi-regional commercial scale.
Market Dynamics
Recombinant DNA expression technologies are displacing plasma fractionation as the dominant thrombin production method, driven by FDA and EMA biosafety mandates eliminating animal-derived viral vectors from surgical hemostasis protocols.
Growth Catalysts
- EMA Plasma Master File Standards:European regulatory harmonization accelerates recombinant thrombin registration timelines, compressing hospital procurement cycles for biosafe hemostats.
- Cardiovascular Surgery Volume:Aging demographics in Germany, Japan, and the United States expand operative caseloads requiring topical thrombin for sternal and vascular closure.
- Mammalian Cell Culture Yield Improvements:Chinese hamster ovary expression systems achieve titer parity with plasma-derived sources, eroding cost premiums for recombinant formats.
Market Restraints
- Plasma Supply Concentration:North American and European fractionation infrastructure limits raw material availability for human-derived thrombin, creating geographic supply bottlenecks.
- ISO 13485 Compliance Burden:Quality management system certification for combination hemostat-device products extends manufacturing audit timelines by 12-18 months.
- Lyophilized Fibrin Sealant Substitution:Two-component sealant systems compete for identical surgical indications, pressuring standalone thrombin pricing in cost-sensitive hospital systems.
Strategic Opportunities
- China NMPA Import Pathway:Streamlined biologics licensing for recombinant blood proteins opens procurement access to tier-one hospitals in Shanghai and Beijing.
- Powder Format Minimally Invasive Surgery:Controlled-geometry application systems capture laparoscopic and robotic procedure volumes where liquid thrombin fails.
- EU MDR Device Classification:Combination product reclassification creates first-mover advantage for manufacturers with pre-certified quality systems.
Industry Challenges
- Biologics Process Engineering Talent:Scarcity of mammalian cell culture specialists constrains recombinant thrombin manufacturing scale-up.
- FDA BLA Documentation Burden:Biologics license application requirements for recombinant blood proteins demand 24-36 month preparation cycles.
- Legacy Plasma Fractionation Asset Stranding:Hospital procurement migration toward recombinant sources idles underutilized fractionation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thrombin Market |
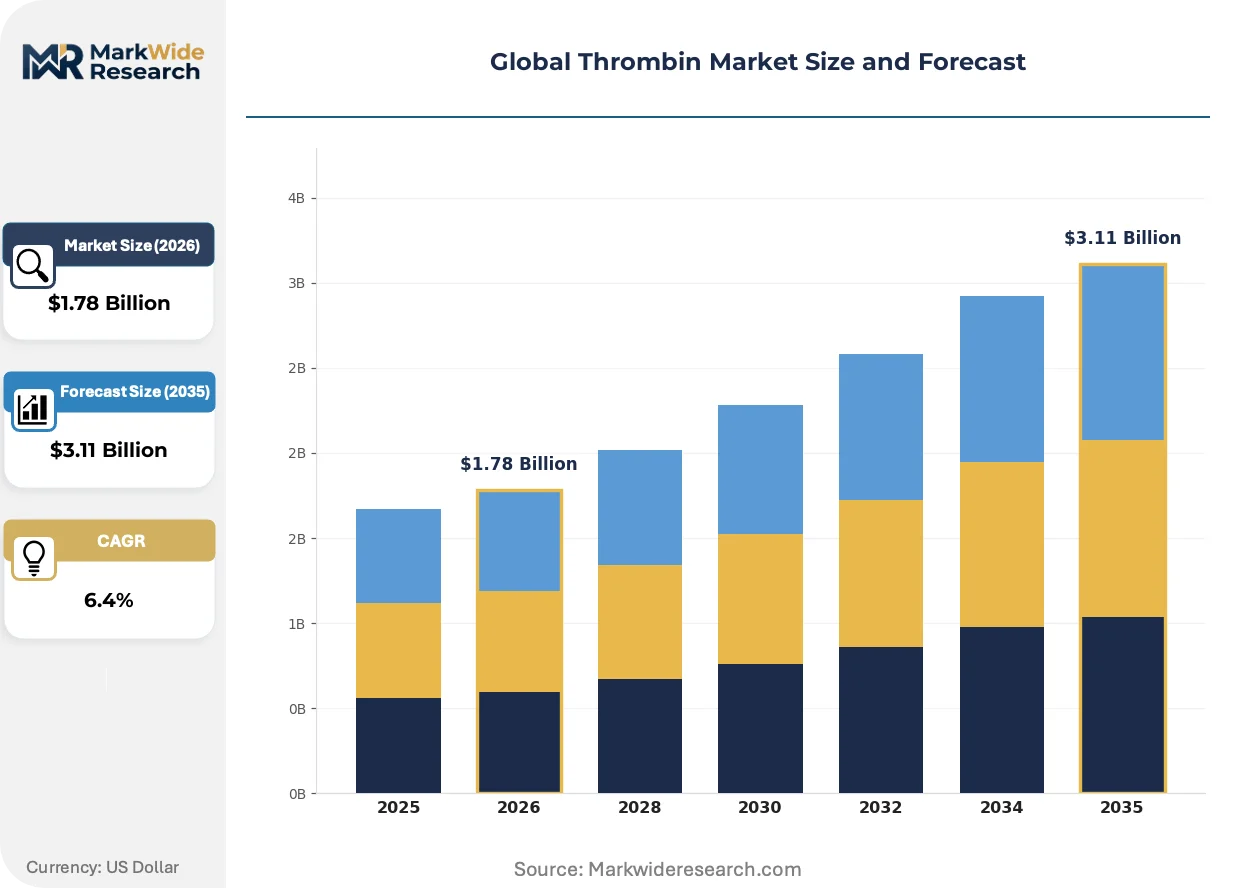
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human-derived, Bovine-derived, Recombinant, Synthetic Therapy Area: Cardiovascular Surgery, Orthopedic Surgery, Neurosurgery, Dental Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Delivery Mode: Topical, Injection, Gel, Powder, Solution |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., Baxter, Grifols, S.A., MOCHIDA PHARMACEUTICAL CO., LTD., Shanghai RAAS Blood Products Co., Ltd., BIOFAC A/S, Merck KGaA, Octapharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thrombin Market Shifts & Advancements
Electrospun fibrin matrices and synthetic polymer-thrombin composites are redefining surgical hemostasis application geometry. These material innovations compress operative time and reduce transfusion dependency in complex cardiovascular reconstruction.
Lyophilized recombinant thrombin powder is electrifying minimally invasive surgical workflows. The format enables precise delivery through laparoscopic ports and robotic instrument channels. Academic medical centers in the United States and Germany are standardizing powder protocols for video-assisted thoracic procedures. This technology is electrifying competitive positioning by decoupling hemostatic performance from open-surgical access requirements.
EMA's evolving guidance on recombinant blood protein immunogenicity monitoring tightens post-market surveillance obligations. Manufacturers must implement extended pharmacovigilance protocols for novel epitope detection. The regulation most affects recombinant thrombin suppliers seeking CE marking renewals under EU MDR. European notified bodies are demanding real-world evidence portfolios that exceed legacy plasma-derived product requirements.
Hospital value analysis committees now mandate total cost-of-ownership modeling for hemostatic agents. The purchasing behavior shift replaces unit-price negotiation with outcome-based contract structures. Integrated delivery networks in the United States are unbundling hemostat procurement from legacy vendor consignment agreements. This pattern concentrates most visibly in cardiovascular service lines where blood product utilization directly impacts episode reimbursement.
Global Thrombin Market Segmentation
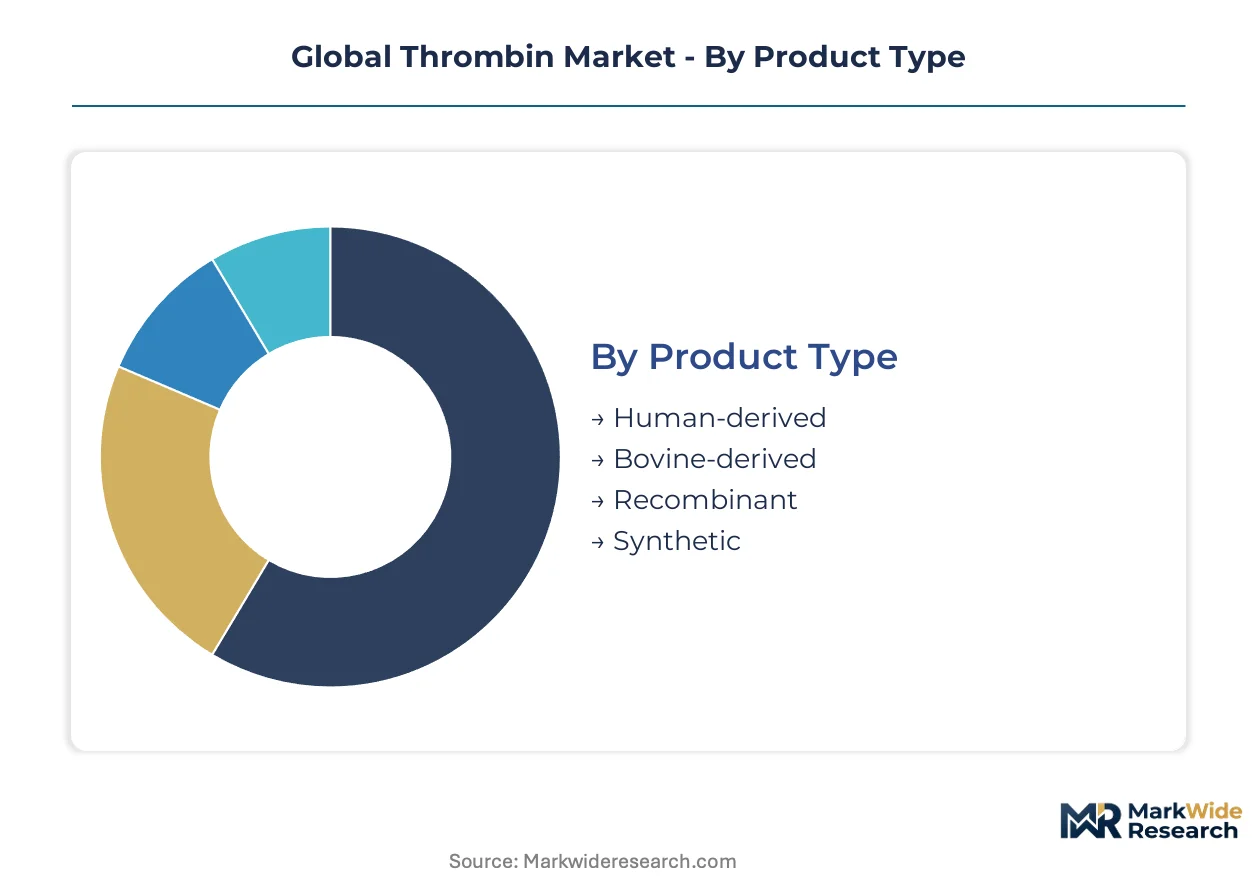
Thrombin market segmentation reveals divergent growth trajectories across production technologies and clinical applications. Product type and delivery mode splits expose where recombinant manufacturing investments concentrate versus where legacy formats retain procurement volume.
Product Type:
Volume leadership sits with established plasma-derived formats while premium positioning shifts toward biosafe recombinant alternatives.
- Human-derived:Plasma fractionation yields thrombin with native glycosylation patterns and established hemostatic efficacy. Hospital systems in Germany and Japan maintain procurement volume here due to cost-sensitive cardiovascular service line budgets and mature fractionation supply relationships.
- Recombinant:Chinese hamster ovary expression systems eliminate viral and immunogenic risks from animal sources. FDA and EMA biosafety mandates accelerate hospital adoption in the United States and European markets where surgical protocol liability drives preference for defined-source biologics.
- Bovine-derived:Lung extraction methods face regulatory pressure under EMA viral safety guidelines.
- Synthetic:Peptide-mimetic catalytic constructs remain experimental with limited commercial scale.
Today's leader: Human-derived. Tomorrow's challenger: Recombinant.
Therapy Area:
Application concentration follows operative caseload expansion in aging demographics across developed hospital systems.
- Cardiovascular Surgery:Sternotomy and vascular closure procedures consume thrombin for immediate hemostasis at suture lines. Academic medical centers in the United States standardize topical application protocols for coronary artery bypass and aortic reconstruction cases.
- Orthopedic Surgery:Arthroplasty and spine fusion applications demand controlled-geometry delivery for bone surface hemostasis. German hospital networks prioritize powder and gel formats for total joint replacement workflows.
- Neurosurgery:Intracranial procedures require ultra-pure recombinant sources to minimize immunogenic complications.
- Dental Procedures:Extraction site management drives modest volume through specialty clinic channels.
Cardiovascular commands current procurement spend. Orthopedic applications are climbing the fastest as arthroplasty volumes rise.
End User:
Customer type determines packaging scale, regulatory documentation depth, and supply chain service requirements.
- Hospitals:Integrated delivery networks negotiate enterprise hemostat contracts with outcome-based terms. United States health systems unbundle thrombin procurement from legacy vendor consignment agreements as value analysis committees mandate total cost-of-ownership modeling.
- Ambulatory Surgical Centers:Outpatient arthroscopy and cardiac catheterization labs drive single-use vial demand. Japanese day-surgery facilities favor pre-filled syringe formats for workflow efficiency.
- Specialty Clinics:Dental and dermatology practices purchase smaller lot sizes with distributor intermediation.
- Research Laboratories:Cell culture and coagulation assay applications require high-specific-activity research-grade material.
Hospital systems dominate current volume. Ambulatory Surgical Centers show the steepest expansion trajectory as procedural migration accelerates.
Delivery Mode:
Physical format selection determines application precision, operative time impact, and compatibility with minimally invasive access.
- Powder:Lyophilized recombinant thrombin enables controlled delivery through laparoscopic ports and robotic instrument channels. Academic medical centers in Germany and the United States standardize powder protocols for video-assisted thoracic procedures.
- Topical:Liquid and sponge-applied formats maintain volume leadership in open surgical workflows. Cost-sensitive hospital procurement in Japan continues favoring established topical presentations for routine cardiovascular closure.
- Injection:Parenteral administration serves specific interventional radiology applications.
- Gel:Viscous matrices target orthopedic and neurosurgical site geometry requirements.
- Solution:Reconstituted liquid presentations serve research and compounding pharmacy channels.
Topical formats hold present dominance. Powder delivery is gaining share fastest as minimally invasive surgical volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biopharmaceutical corridor anchors thrombin demand through dense cardiovascular surgery networks and recombinant protein manufacturing infrastructure. Hospital procurement patterns in this cluster shape North American pricing benchmarks. European and Asian markets follow divergent regulatory pathways that determine production technology adoption rates.
United States
Academic medical centers in Cleveland and Houston drive recombinant thrombin volume through standardized sternotomy protocols. FDA biologics licensing requirements compress registration timelines for mammalian cell culture-derived products. The Research Triangle Park concentration in North Carolina hosts contract manufacturing organizations scaling Chinese hamster ovary expression systems for surgical hemostasis supply.
Germany
University hospitals in Munich and Heidelberg prioritize powder-format thrombin for video-assisted thoracic surgery workflows. EMA plasma master file standards accelerate biosafe product registrations while tightening post-market surveillance obligations. The Frankfurt-Rhine-Main cluster concentrates fractionation infrastructure serving cost-sensitive cardiovascular service lines across Bavaria and Baden-Württemberg.
Japan
Aging demographics in Tokyo and Osaka expand coronary artery bypass caseloads requiring topical hemostatic agents. PMDA guidelines on recombinant blood protein immunogenicity monitoring shape manufacturer pharmacovigilance investments. The Kansai region's day-surgery facilities favor pre-filled syringe formats for outpatient arthroscopy efficiency.
China
Tier-one hospitals in Shanghai and Beijing accelerate recombinant thrombin procurement under streamlined NMPA biologics licensing pathways. Domestic plasma fractionation capacity in the Yangtze River Delta serves volume demand for human-derived formats. The government's dual carbon goals pressure manufacturers toward cell culture technologies reducing bovine supply chain dependency.
United Kingdom
NHS integrated care systems in London and Manchester unbundle hemostat procurement from legacy vendor agreements. MHRA alignment with EU MDR device classification creates transitional complexity for combination product registrations. The Cambridge-London biotech corridor attracts recombinant protein engineering talent from continental European pools.
Global Thrombin Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit mammalian cell culture lines for recombinant thrombin output. The vendor base stratifies across three tiers: multinational biopharmaceutical conglomerates with integrated fractionation infrastructure, mid-scale plasma processors serving regional hospital networks, and emerging cell culture specialists capturing minimally invasive surgery format share. Strategic archetypes include biosafety-focused premium positioners, cost-optimized volume suppliers, and technology licensors enabling geographic market entry. M&A activity concentrates on recombinant manufacturing assets, while strategic partnerships secure plasma supply agreements in concentrated fractionation geographies.
Among established biopharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson Services, Inc. occupy positions reflecting deep integration with North American and European hospital supply chains. Baxter and Grifols, S.A. exemplify plasma-derived specialists with sustained volume presence in cost-sensitive procurement environments. MOCHIDA PHARMACEUTICAL CO., LTD. represents Asia-Pacific market concentration through regulatory pathway expertise and regional distribution density. These anchors illustrate how geographic regulatory alignment and production technology selection determine competitive positioning across divergent hospital purchasing frameworks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Baxter |
| Grifols, S.A. |
| MOCHIDA PHARMACEUTICAL CO., LTD. |
| Shanghai RAAS Blood Products Co., Ltd. |
| BIOFAC A/S |
| Merck KGaA |
| Octapharma |
| Others |
Supply & Pricing Matrix
Recombinant-human-bovine product stratification creates distinct procurement tiers that propagate through both hospital contract structures and upstream manufacturing footprints. FDA and EMA biosafety mandates compress demand toward premium recombinant formats while plasma fractionation infrastructure in North America and Europe anchors volume supply for cost-sensitive cardiovascular service lines.
Pricing Analysis
Input-cost pass-through from mammalian cell culture media and plasma fractionation raw materials stratifies thrombin pricing across three certification-linked tiers. Premium recombinant formats command elevated positioning due to eliminated viral risk and BLA documentation investment, while human-derived products compete on scale economies in German and Japanese hospital procurement. Cost compression in bovine-derived segments intensifies as EMA viral safety guidelines accelerate format substitution. Ambulatory surgical centers exhibit highest price sensitivity due to episode-based reimbursement constraints, whereas academic medical centers prioritize outcome-based total cost-of-ownership models.
Supply Chain Analysis
Workforce availability for mammalian cell culture specialists concentrates manufacturing scale-up in the Research Triangle Park cluster and Boston-Cambridge corridor, with Frankfurt-Rhine-Main anchoring European fractionation capacity. Raw material supply draws from North American plasma collection networks, Chinese hamster ovary cell banks, and bovine lung extraction facilities in regulated jurisdictions. Single-source vulnerability in plasma-derived feedstock creates geographic supply bottlenecks when collection disruptions occur. Distribution runs through integrated delivery network consignment agreements and GPO contracts with tiered service level commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thrombin market compounds steadily as aging demographics in developed economies sustain cardiovascular surgery volumes requiring topical hemostasis. Regulatory biosafety mandates create durable preference migration toward recombinant manufacturing technologies.
For Market Incumbents: Anchor hospital system relationships through outcome-based contracting that bundles recombinant thrombin with surgical sealant portfolios. Defend against lyophilized fibrin sealant substitution by deepening powder-format capabilities for minimally invasive workflows. Invest in mammalian cell culture yield improvements to compress cost premiums versus plasma-derived alternatives. Secure plasma supply agreements in concentrated fractionation geographies to sustain volume positioning in cost-sensitive procurement segments. For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable buyer archetype as procedural migration accelerates outpatient arthroscopy and cardiac catheterization volumes. Target Chinese tier-one hospitals in Shanghai and Beijing through streamlined NMPA recombinant biologics pathways where domestic plasma capacity constraints create import dependency. Capture robotic surgery powder-format share by engineering controlled-geometry delivery systems compatible with laparoscopic instrument channels. Pursue technology licensing arrangements to bypass FDA BLA timeline barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mammalian cell culture manufacturing assets face scarcity constraints and recombinant production scale determines competitive viability. The market reads as a stable compounder over extended horizons, with acquisition value concentrating in cell culture specialists possessing pre-certified quality systems. Target mid-scale plasma processors with underutilized fractionation capacity that can pivot toward recombinant retrofit or serve as regional supply anchors. Watch FDA guidance evolution on recombinant blood protein immunogenicity monitoring as the signal indicating regulatory burden direction and post-market surveillance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Chinese hamster ovary expression system expansion in Research Triangle Park contract manufacturing organizations compresses recombinant cost premiums. |
| Regulatory Approval Pathway | Streamlined NMPA biologics licensing for recombinant blood proteins opens tier-one hospital procurement access in Shanghai and Beijing. |
| Hospital System Partnership | Integrated delivery network outcome-based contracting unbundles thrombin procurement from legacy vendor consignment agreements in United States cardiovascular service lines. |
| Product Format Innovation | Lyophilized powder development for laparoscopic and robotic instrument channels captures minimally invasive surgery volume migration. |
| CE Marking Pathway | EU MDR combination product reclassification creates first-mover advantage for manufacturers with pre-certified ISO 13485 quality systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster combined with secondary validation. Interviews with hospital procurement managers, cardiovascular surgeons, regulatory affairs leads at biopharmaceutical manufacturers, and plasma fractionation executives informed demand and supply dynamics. Secondary sources include FDA biologics licensing databases, EMA plasma master file submissions, hospital procurement contract disclosures, and GPO pricing benchmarks. Bottom-up surgical procedure volume modeling triangulated against top-down manufacturer capacity and revenue estimates.
Granularity-level framing applied production technology splits at the SKU level, therapy area segmentation by procedure code, and delivery mode differentiation by surgical access type across the projection horizon. CAGRs derived from trend extrapolation of recombinant adoption curves, plasma supply constraints, and regulatory pathway timeline compression. Forecast inputs incorporated PMDA immunogenicity monitoring guidance evolution and NHS integrated care system procurement unbundling patterns.
Underlying measurement precision varies by segment; recombinant product forecasts carry tighter precision than bovine-derived projections given regulatory discontinuity risk. Forecasts reflect assumptions on EMA and FDA biosafety mandate enforcement consistency, mammalian cell culture yield improvement trajectories, and hospital value analysis committee purchasing behavior standardization. Material deviation in plasma supply concentration, regulatory pathway streamlining, or minimally invasive surgery volume acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market