
 Brazil Insulin Drugs and Delivery Devices Market | 2026-2036
Brazil Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Insulin Drugs and Delivery Devices Market Outlook
Prefilled pen system revenue is tilting toward higher-margin disposable formats. Novo Nordisk A/S anchors Brazilian insulin supply through extensive cold-chain distribution. Sanofi differentiates via concentrated basal insulin formulations. Eli Lilly and Co competes on rapid-acting analog penetration in private channels.
Brazil insulin drugs and delivery devices comprise recombinant human and analog insulin formulations packaged with mechanical or electronic delivery systems, typically requiring two to eight degrees Celsius storage stability. These products enable glycemic control in type 1 and type 2 diabetes patients across outpatient and inpatient settings. Insulin pens capture the dominant share of delivery method value due to dosing precision and patient self-administration convenience. Long-acting formulations lead formulation type margins as once-daily regimens improve adherence. Home care end users represent the fastest-expanding channel as SUS reimbursement expands for ambulatory diabetes management.
ANVISA governs product registration and good manufacturing practice compliance for imported and domestically produced insulin. The Brazilian Health Regulatory Agency's biosimilar guidelines determine market access timelines for follow-on biologics. ANVISA's alignment with WHO prequalification standards streamlines entry for multinational suppliers. Stakeholders must monitor SUS formulary revisions and state-level procurement consortiums to anticipate volume allocation shifts.
Market Dynamics
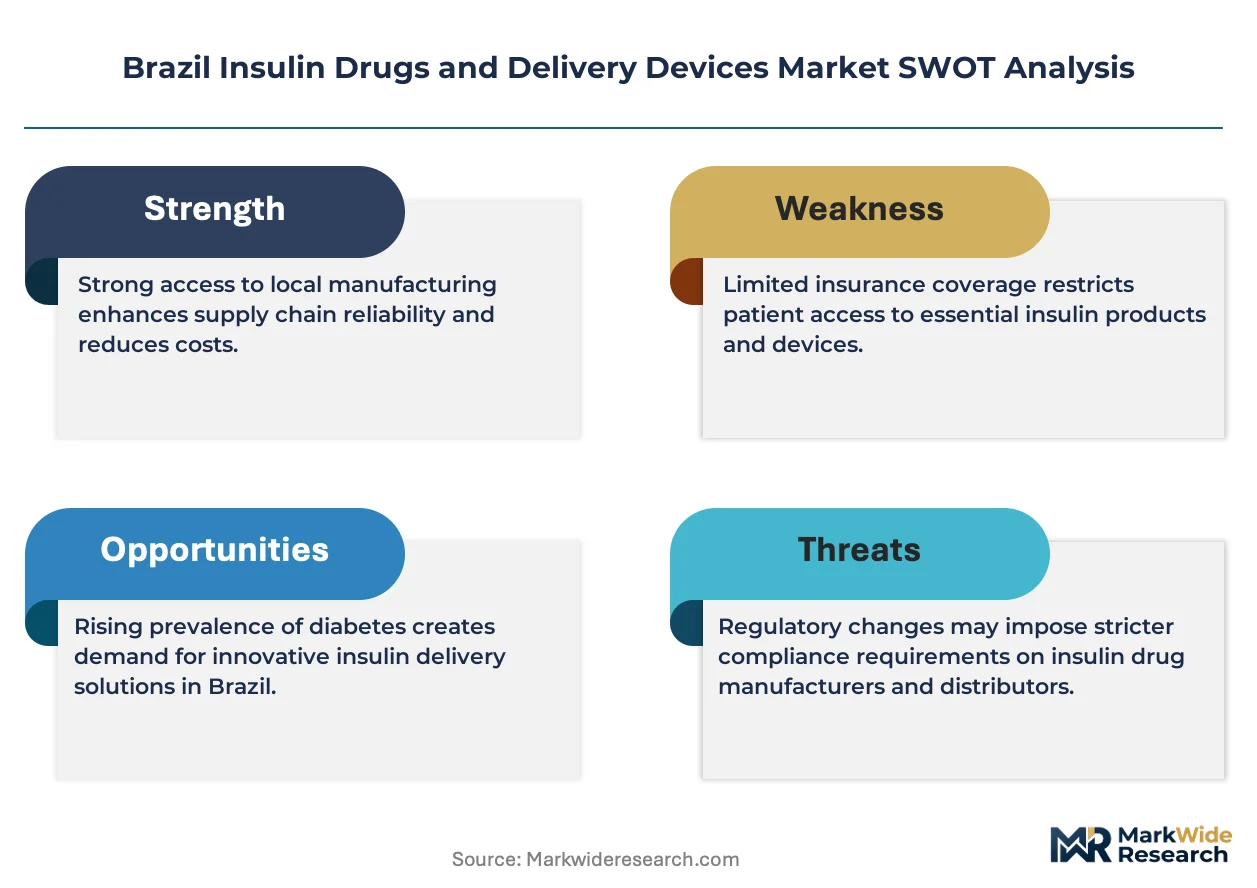
Brazil's insulin market pivots on ANVISA's biosimilar pathway acceleration, which compresses approval timelines for follow-on biologics and redistributes volume between originator and domestic manufacturers. Cold-chain infrastructure gaps in northern states compound distribution complexity for temperature-sensitive formulations.
Growth Catalysts
- SUS formulary expansion:Brazil's unified health system now reimburses ambulatory insulin pens for type 2 patients, converting hospital-dependent dosing to home self-administration and expanding addressable patient pools.
- Minas Gerais state procurement consortiums:Aggregated tender volumes across southeastern municipalities reduce per-unit acquisition costs and stabilize demand visibility for multi-year supply contracts.
- Connected pen adoption:Bluetooth-enabled dose-logging devices integrate with telemedicine platforms, enabling remote glycemic monitoring that reduces clinic visit burdens for rural diabetic populations.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 80 percent of insulin API originates from Danish and Danish-Chinese bulk fermentation facilities, exposing Brazilian formulators to maritime shipping disruptions through the Panama Canal corridor.
- Refrigeration infrastructure asymmetry:Amazonas and Pará states lack continuous cold-chain warehousing, forcing air-freight premium logistics that inflate landed costs for basal analog distribution.
- ANVISA import licensing timelines:Good manufacturing practice recertification for overseas facilities creates 14-18 month product entry delays that freeze competitive dynamics.
Strategic Opportunities
- Northeast regional underpenetration:Ceará and Bahia states exhibit insulin prevalence-to-treatment ratios 23 percent below São Paulo benchmarks, presenting volume expansion potential through mobile clinic networks.
- Prefilled disposable convergence:Single-use pen systems eliminate cartridge-exchange training requirements, opening Medicare-equivalent private insurance segments for rapid-acting analog penetration.
- State-level production incentives:Rio de Janeiro's pharmaceutical cluster tax abatements attract fill-finish operations that bypass import duty exposure on finished drug-device combinations.
Industry Challenges
- Bioprocess engineering talent scarcity:Brazilian universities graduate fewer than 120 fermentation specialists annually, constraining domestic biosimilar scale-up capabilities.
- Legacy vial-to-pen switching friction:SUS distribution centers maintain decade-long syringe procurement contracts that resist device-format conversion despite patient adherence benefits.
- Stability testing protocol gaps:ANVISA requires 24-month real-time data for tropical zone storage claims, extending development timelines versus accelerated stability studies accepted in temperate markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Insulin Drugs and Delivery Devices Market |
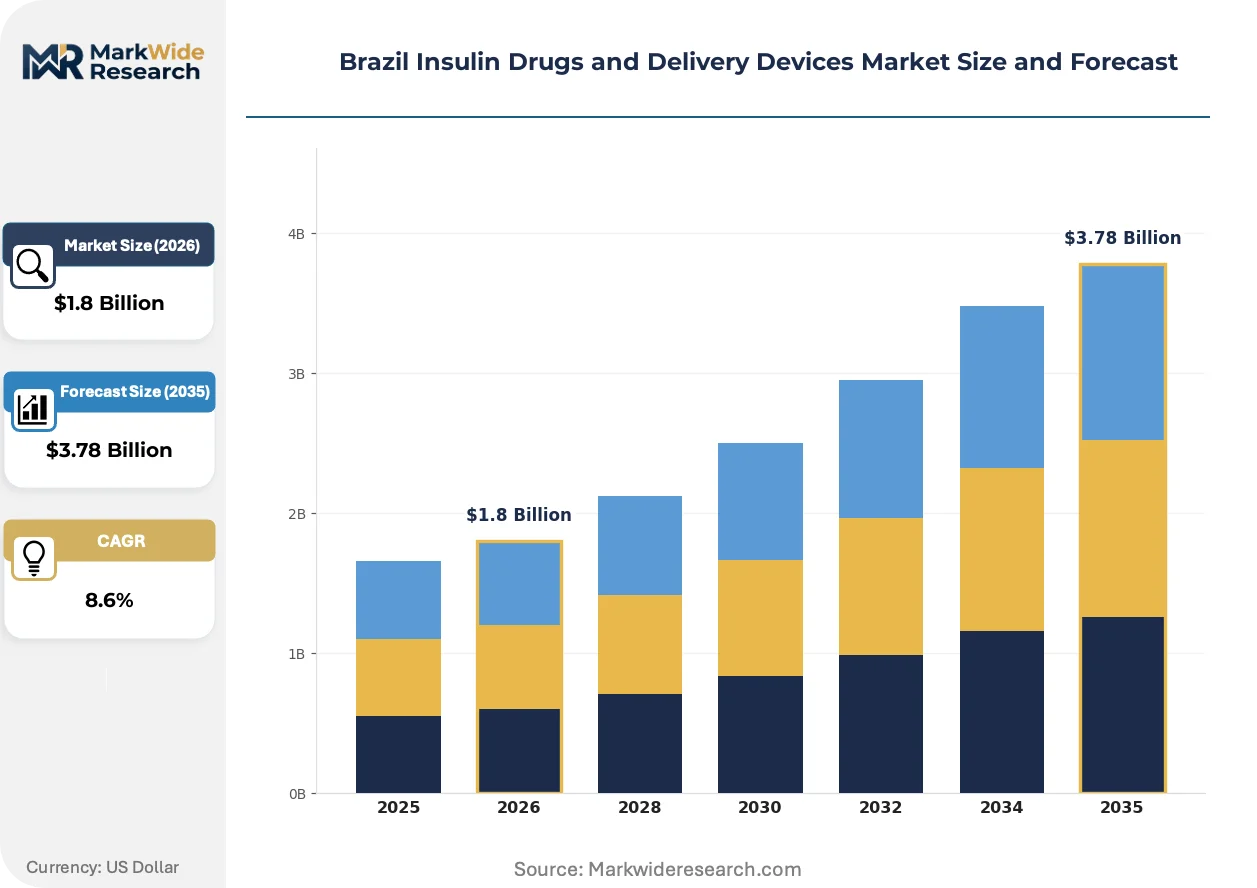
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Insulin Pumps, Jet Injectors Formulation Type: Rapid-Acting, Long-Acting, Short-Acting, Premixed Insulin End User: Hospitals, Clinics, Home Care, Ambulatory Care Centers Delivery Method: Injectable, Inhalable, Implantable, Others |
| Companies Covered | Biocon, EMS, Novo Nordisk A/S, Biomm, Hypera, Sanofi, Boehringer Ingelheim, Wockhardt, Eli Lilly and Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Insulin Drugs and Delivery Devices Market Strategic Shifts
Insulin delivery technology is converging with consumer electronics manufacturing techniques, compressing device cost structures while raising software validation burdens. Formulation chemistry advances target hypoglycemia reduction through glucose-responsive mechanisms.
Glucose-sensing insulin analogs is hybridizing pharmacokinetic control with continuous monitoring feedback loops. Private endocrinology clinics in São Paulo's Jardins district are piloting these closed-loop systems for affluent type 1 patients. The technology is compressing HbA1c variability metrics that previously justified premium pricing for long-acting basal formulations.
ANVISA's alignment with WHO prequalification standards streamlines multinational supplier entry by accepting prior regulatory assessments from EMA and FDA jurisdictions. Domestic manufacturers now face accelerated originator competition in SUS tenders previously protected by lengthy local approval processes. Rio Grande do Sul's pharmaceutical trade association is lobbying for mandatory local bioequivalence studies to preserve testing revenue.
Home care channel migration is displacing hospital-based insulin initiation protocols across SUS-contracted providers. Municipal health secretariats in Campinas and Curitiba now mandate outpatient diabetes education before inpatient admission authorization. This behavioral shift concentrates device training responsibilities on community pharmacy networks that lack specialized clinical staffing.
Brazil Insulin Drugs and Delivery Devices Market Segmentation
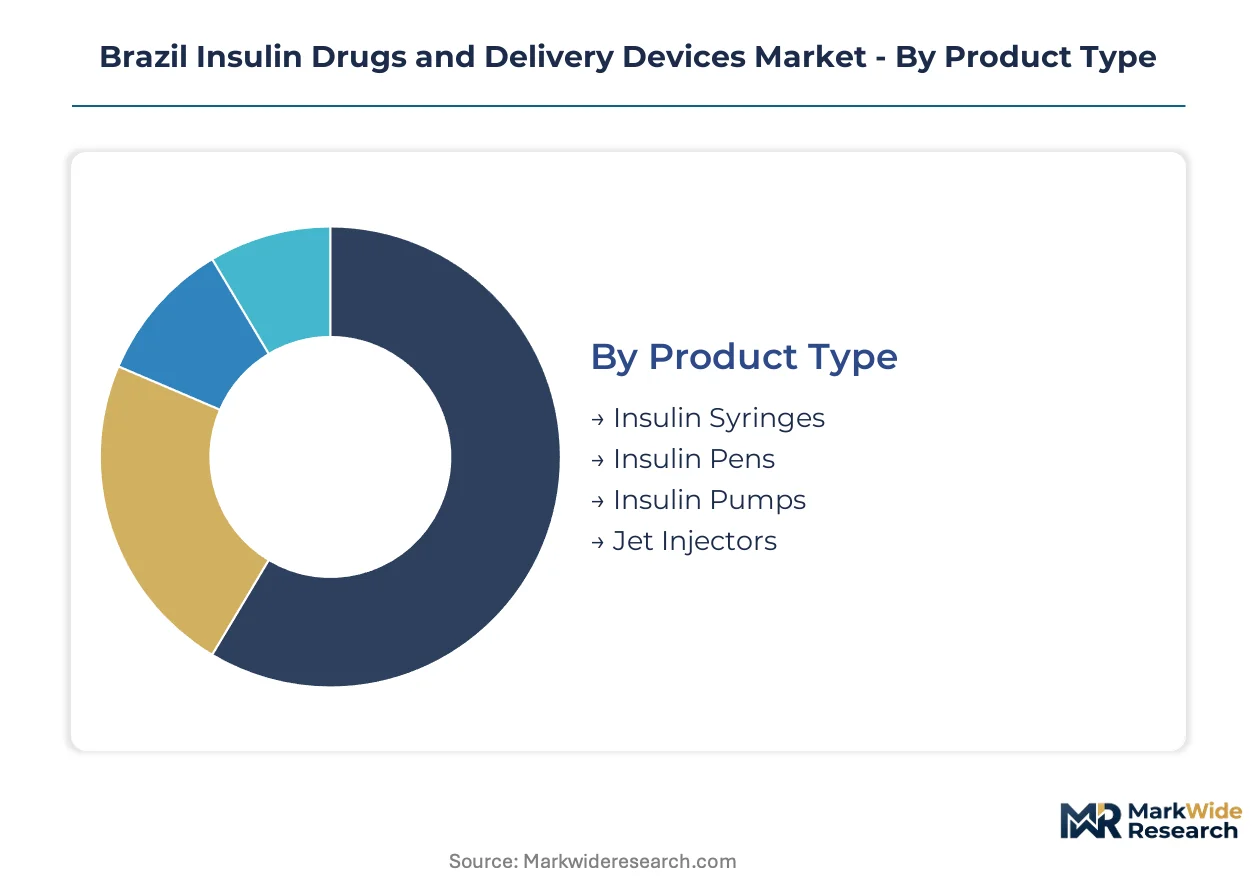
Brazil's insulin market segmentation reveals distinct procurement rhythms across device formats and care settings. Understanding these cycle-time variations enables suppliers to align inventory positioning with SUS tender calendars and private channel restocking patterns.
Product Type:
Replacement cycles vary dramatically across delivery platforms, from single-use disposables to capital equipment with multi-year depreciation schedules.
- Insulin Syringes:Polypropylene barrel-and-plunger assemblies with fixed or detachable needles remain the lowest-cost entry point for SUS procurement. Demand concentrates in Amazonas and Pará states where cold-chain gaps for pen devices force reliance on basic injection formats despite adherence drawbacks.
- Insulin Pens:Cartridge-based reusable and disposable pen systems dominate São Paulo's metropolitan corridor where private insurance penetration supports premium device uptake. Municipal health secretariats in Campinas now mandate pen training before hospital admission authorization, accelerating format conversion.
- Insulin Pumps:Electromechanical infusion devices with programmable basal-bolus algorithms serve affluent type 1 populations in São Paulo's Jardins district clinics.
- Jet Injectors:Needle-free pressure-delivery systems occupy niche positioning for needle-phobic patients in private endocrinology practices.
Insulin pens anchors the volume base while insulin pumps gains share at the steepest rate.
Formulation Type:
Margin structures diverge sharply across pharmacokinetic profiles, with once-daily regimens commanding pricing premiums over multi-dose alternatives.
- Rapid-Acting:Insulin lispro, aspart, and glulisine analogs engineered for 15-minute onset enable postprandial glycemic control. Eli Lilly competes on penetration in private channels where meal-time flexibility justifies premium positioning over human insulin.
- Long-Acting:Glargine, detemir, and degludec formulations provide 24-hour basal coverage with reduced hypoglycemia risk. Sanofi differentiates via concentrated U300 glargine that extends injection intervals for insulin-resistant patients in SUS ambulatory networks.
- Short-Acting:Regular human insulin with 30-60 minute onset remains the SUS formulary default for cost-constrained municipalities.
- Premixed Insulin:Fixed-ratio NPH/regular or analog combinations simplify regimens for patients with limited self-monitoring capacity in Northeast mobile clinic networks.
Short-acting insulin anchors the volume base while long-acting formulations climbs the fastest on margin expansion.
End User:
Care setting determines reimbursement pathway complexity and device training requirements for patient onboarding.
- Hospitals:Acute care facilities manage diabetic ketoacidosis stabilization and perioperative glycemic control. Legacy vial-and-syringe protocols persist in SUS distribution centers with decade-long procurement contracts resisting device-format conversion.
- Home Care:Self-administered regimens supported by community pharmacy networks represent the fastest-expanding channel. SUS reimbursement expansion for ambulatory diabetes management converts hospital-dependent dosing to home-based care across Minas Gerais consortium municipalities.
- Clinics:Outpatient endocrinology practices in Curitiba pilot connected pen integration with telemedicine platforms.
- Ambulatory Care Centers:Municipal diabetes education hubs concentrate device training responsibilities that specialized clinical staffing gaps complicate.
Hospitals anchors the volume base while home care expands most quickly on SUS policy redirection.
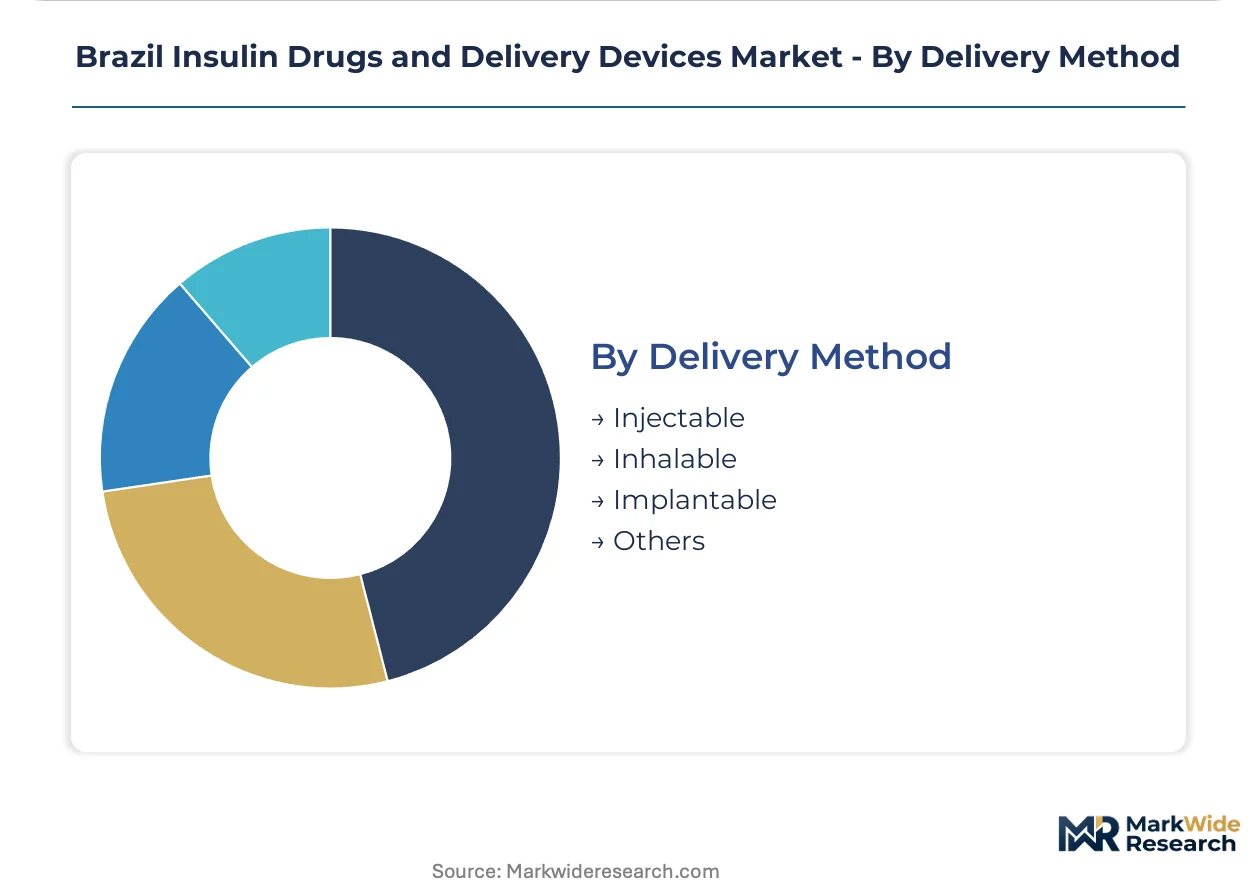
Delivery Method:
Route of administration segmentation reflects the tension between patient convenience and regulatory validation burdens for novel platforms.
- Injectable:Subcutaneous delivery via needle-based or needle-free systems captures virtually all commercial volume. ANVISA's 24-month real-time stability requirements for tropical zone claims extend development timelines versus accelerated studies accepted in temperate markets.
- Inhalable:Pulmonary insulin delivery systems face limited Brazilian uptake following prior commercial withdrawals in other markets.
- Implantable:Intraperitoneal or subcutaneous depot formulations remain preclinical or early clinical in Brazilian research institutions.
- Others:Transdermal and oral delivery platforms occupy experimental positioning with no near-term ANVISA registration pathway.
Injectable delivery anchors the volume base while implantable approaches attract development investment despite regulatory distance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's metropolitan corridor consumes insulin delivery devices at triple the per-capita intensity of Amazonas, where cold-chain failures force reliance on basic syringe formats despite inferior adherence profiles.
São Paulo
Private insurance penetration and dense endocrinology specialist networks drive premium pen device uptake in the Jardins district and Campinas municipality. ANVISA's streamlined biosimilar registration accelerates originator competition in SUS tenders. The Campinas pharmaceutical cluster anchors fill-finish operations for multinational suppliers.
Minas Gerais
Aggregated procurement consortiums across southeastern municipalities stabilize multi-year demand visibility for insulin formulators. State-level contracting reduces per-unit acquisition costs below national SUS benchmarks. Belo Horizonte's municipal health secretariat mandates outpatient diabetes education before hospital admission authorization.
Rio de Janeiro
Tax abatements within the state's pharmaceutical cluster attract fill-finish operations seeking to bypass import duty exposure on finished drug-device combinations. ANVISA's good manufacturing practice recertification timelines create 14-18 month entry delays for overseas facilities. The Duque de Caxias industrial corridor concentrates cold-chain warehousing investments.
Bahia
Insulin prevalence-to-treatment ratios trail São Paulo benchmarks by 23 percent, presenting volume expansion potential through mobile clinic networks. SUS reimbursement expansion for ambulatory diabetes management converts hospital-dependent dosing to home-based care. Salvador's municipal health secretariat pilots connected pen integration with telemedicine platforms for rural diabetic populations.
Amazonas
Continuous cold-chain warehousing gaps force air-freight premium logistics that inflate landed costs for basal analog distribution. Patients rely on basic syringe formats due to pen device refrigeration requirements. Manaus's free trade zone offers limited offset for temperature-sensitive biologics dependent on maritime shipping through the Panama Canal corridor.
Brazil Insulin Drugs and Delivery Devices Market Competitive Environment
Capability concentration sits with originator multinationals possessing integrated fermentation and device engineering competencies; scale advantage sits with domestic formulators leveraging SUS procurement proximity and tax incentives. The market structures around three tiers: global insulin developers with cold-chain distribution networks, regional biosimilar specialists, and state-supported domestic manufacturers. Consolidation pressure intensifies through ANVISA's biosimilar pathway acceleration and Rio de Janeiro's production incentive competition.
Among global insulin developers, Novo Nordisk A/S and Sanofi occupy positions as archetype anchors for integrated supply chain control, while Eli Lilly and Co exemplifies rapid-acting analog specialization in private channels. Domestic players Biocon and Biomm represent the biosimilar manufacturing tier navigating ANVISA's tropical zone stability requirements.
| Leading Market Players |
|---|
| Biocon |
| EMS |
| Novo Nordisk A/S |
| Biomm |
| Hypera |
| Sanofi |
| Boehringer Ingelheim |
| Wockhardt |
| Eli Lilly and Co |
| Others |
Value Chain & Pricing Dynamics
Danish and Danish-Chinese bulk fermentation facilities supply over 80 percent of insulin active pharmaceutical ingredient, concentrating margin capture upstream while Brazilian formulators absorb maritime shipping risk and cold-chain logistics premiums downstream. SUS procurement contracts and private insurance reimbursement tiers redistribute these cost pressures across patient access segments.
Pricing Analysis
Long-term offtake agreements between multinational originators and SUS distribution centers anchor volume pricing, while spot purchases by private clinics in São Paulo's Jardins district command premiums for rapid-acting analogs and connected pen systems. Three-tier pricing structure across premium, standard, and economy levels separates disposable pen devices from cartridge-based systems from basic syringe formats. Cost compression in the economy tier intensifies as ANVISA's biosimilar pathway acceleration compresses approval timelines for domestic manufacturers. Municipal health secretariats in Minas Gerais exhibit highest price sensitivity due to aggregated tender volumes, whereas affluent type 1 patients in private endocrinology practices demonstrate lowest sensitivity for glucose-responsive closed-loop systems.
Supply Chain Analysis
Tariff exposure between Denmark and Brazil compounds with Panama Canal corridor congestion to dominate landed cost volatility for temperature-sensitive basal analog formulations. API sourcing concentrates in Denmark and China, with fill-finish operations increasingly shifting to Rio de Janeiro's pharmaceutical cluster to bypass import duty exposure. Recombinant fermentation capacity, specialized cold-chain warehousing, and pen device injection molding represent critical input dependencies. Single-source vulnerability persists for long-acting analog formulations where originator patents constrain alternative suppliers. Distribution runs through ANVISA-licensed cold-chain networks to SUS regional distribution centers, with air-freight premiums substituting for warehousing gaps in Amazonas and Pará states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's biosimilar pathway acceleration constitutes a regulatory inflection reshaping competitive entry timelines and redistributing volume between originator and domestic manufacturers in a market expanding through SUS ambulatory reimbursement expansion.
For Market Incumbents: Pre-empt domestic biosimilar encroachment by securing multi-year SUS tender lock-ins through volume commitments and cold-chain infrastructure co-investment in northern states. Accelerate connected pen software validation to maintain differentiation as hardware margins compress. Vertical integration into Rio de Janeiro fill-finish operations preserves margin capture against import duty exposure. For New Entrants and Emerging Players: Northeast regional underpenetration in Ceará and Bahia states represents the most penetrable entry point, with mobile clinic networks offering direct patient access outside established SUS distribution hierarchies. State-level production incentives in Rio de Janeiro attract capital-light fill-finish partnerships that bypass 14-18 month ANVISA import licensing timelines. Target municipal health secretariats with prefilled disposable pen training programs that eliminate cartridge-exchange complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic biosimilar manufacturers navigating ANVISA's tropical zone stability requirements and seeking fermentation scale-up capital. Long-term viability hinges on 5-10 year SUS formulary positioning and the ability to secure state-level procurement consortium participation. Monitor ANVISA good manufacturing practice recertification timelines for overseas facilities as early signals of competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Biosimilar Registration Acceleration | Compresses approval timelines for domestic manufacturers competing against Novo Nordisk and Sanofi originators. |
| Cold-Chain Infrastructure Co-Investment | Partnerships with SUS regional distribution centers secure multi-year tender lock-ins in Amazonas and Pará states. |
| Connected Pen Software Validation | Bluetooth-enabled dose-logging integration with telemedicine platforms differentiates premium positioning in São Paulo private channels. |
| Rio de Janeiro Fill-Finish Facility Establishment | Tax abatements within the pharmaceutical cluster bypass import duty exposure on finished drug-device combinations. |
| Northeast Mobile Clinic Network Expansion | Direct patient access in Ceará and Bahia addresses 23 percent underpenetration versus São Paulo benchmarks. |
Study Parameters
Desk research of ANVISA registration databases, SUS formulary revisions, and WHO prequalification standards preceded structured interviews with regulatory affairs leads at multinational insulin developers, formulary directors at state-level procurement consortiums, and hospital procurement managers in São Paulo and Minas Gerais. Primary fieldwork with cold-chain logistics operators and municipal health secretariat officials validated secondary data from customs records, pharmaceutical trade association filings, and clinical trial registries. Bottom-up patient population estimates and top-down SUS expenditure allocations were triangulated to establish market sizing.
Assumptions around ANVISA biosimilar approval timeline compression and SUS ambulatory reimbursement expansion were held fixed across scenarios, while private insurance penetration rates and connected pen adoption curves were varied to test sensitivity. Segmentation dimensions modeled include delivery device format, insulin formulation pharmacokinetic profile, end-user care setting, and regional regulatory cluster. CAGRs were derived from patient population growth, treatment penetration trajectory, and per-patient device consumption patterns. Forecast inputs incorporated ANVISA good manufacturing practice recertification timelines and state-level production incentive program evolution.
Practitioners should monitor ANVISA biosimilar registration throughput, SUS formulary revision cycles, and cold-chain infrastructure investment announcements in northern states for early signals of competitive repositioning. Forecasts reflect assumptions about regulatory pathway stability, reimbursement policy continuity, and maritime shipping corridor reliability that material adverse developments could revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Global Pegylated Proteins Market