
 Progesterone Market | 2026-2036
Progesterone Market Size, Share, and Industry Trends Forecast 2026-2036
Progesterone Market Analysis
Generic formulation revenue is fragmenting across regional manufacturing clusters as price compression intensifies in mature markets. Teva Pharmaceutical Industries Ltd. leverages its vertically integrated API-to-finished-dose capability to sustain margin capture in oral tablet segments. Cipla Inc. anchors its competitive stance through geographic dominance in emerging markets where regulatory pathways remain less congested. Novo Nordisk A/S differentiates via R&D intensity in novel delivery technologies that bypass first-pass metabolism challenges.
Progesterone is a C21 steroid hormone synthesized endogenously in the corpus luteum and placenta, or manufactured semi-synthetically from diosgenin-derived precursors via microbial biotransformation; it functions primarily as a gestational support agent and modulator of endometrial receptivity. Injectable formulations retain the highest clinical efficacy ratings in assisted reproductive technology protocols, while vaginal suppositories capture expanding share in luteal phase support due to superior uterine first-pass uptake. Oral tablets face bioavailability headwinds from hepatic metabolism, yet maintain volume leadership in birth control combinations where cost minimization governs procurement decisions.
FDA bioequivalence standards and EMA's tightened impurity profiling under ICH Q3D guidelines shape product development timelines and API sourcing requirements for manufacturers targeting regulated markets. India's CDSCO enforces progressive local clinical trial mandates that influence market entry sequencing for multinational suppliers. Stakeholders must monitor evolving pharmacovigilance obligations and biosimilar substitution policies as reimbursement authorities recalibrate cost-effectiveness thresholds for hormone therapies.
Market Dynamics
FDA bioequivalence tightening and EMA impurity profiling under ICH Q3D are forcing API-to-finished-dose manufacturers to revalidate entire product lines. Fertility clinic procurement volumes now exceed traditional pharmacy channels in hormone replacement therapy segments.
Growth Catalysts
- Assisted Reproductive Technology Expansion:Fertility clinics in India and the United States are standardizing progesterone luteal support protocols, driving API procurement volumes for injectable formulations.
- REACH and RoHS Alignment:European manufacturers are reformulating excipient matrices to meet tightened chemical safety standards, opening substitution windows for bio-based steroid precursors.
- Microbial Biotransformation:Indian contract manufacturers are deploying engineered yeast strains to convert diosgenin into progesterone with higher stereoselectivity than traditional chemical synthesis routes.
Market Restraints
- Diosgenin Supply Concentration:Wild yam harvesting in Mexico and China faces climate volatility, creating raw material price instability for semi-synthetic production pathways.
- First-Pass Metabolism Limitation:Oral progesterone formulations require 10-fold higher doses than vaginal or injectable routes to achieve therapeutic serum levels, compressing clinical utility in cost-sensitive segments.
- CDSCO Local Trial Mandates:India's progressive clinical trial requirements for imported APIs extend market entry timelines for multinational suppliers by 18-24 months.
Strategic Opportunities
- Subcutaneous Auto-Injector Platforms:Novel delivery technologies bypassing hepatic metabolism are capturing physician preference in luteal phase support protocols.
- Menopausal Hormone Therapy Unbundling:Compounding pharmacies in the United States are creating customized progesterone-progestin combinations outside mass-manufactured dose tiers.
- EMA Biosimilar Substitution Pathways:Emerging reimbursement frameworks in Germany and France are creating volume pull for bioequivalent progesterone formulations in generic substitution programs.
Industry Challenges
- Steroid Synthesis Expertise Scarcity:Microbial biotransformation scale-up requires fermentation specialists with rare combinations of biochemistry and GMP manufacturing experience.
- ICH Q3D Elemental Impurity Validation:Heavy metal testing protocols for palladium catalyst residues are extending analytical development timelines by 6-9 months.
- Legacy ERP Integration:Contract manufacturers upgrading from paper-based batch records to electronic systems face data migration bottlenecks during FDA pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progesterone Market |
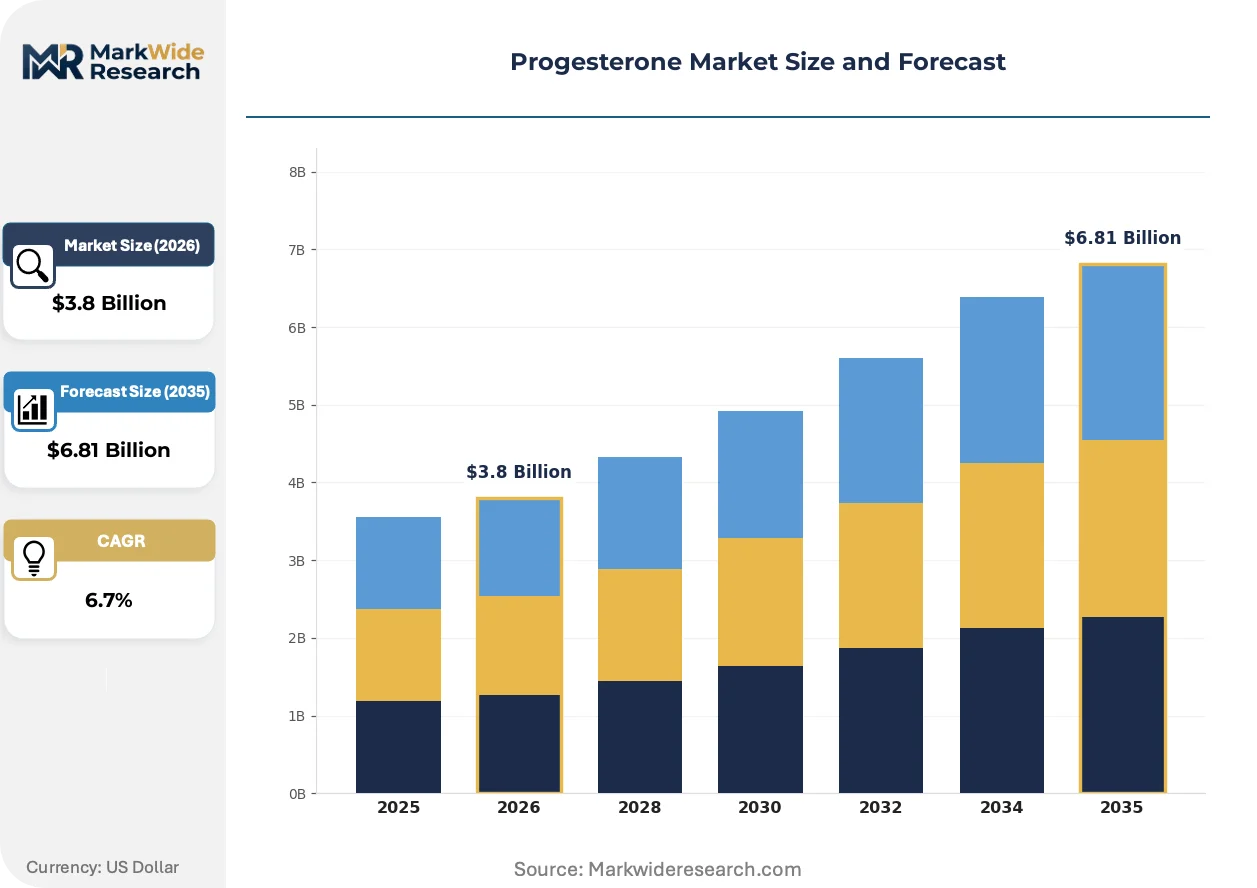
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Tablets, Creams, Vaginal Suppositories End User: Hospitals, Clinics, Homecare, Pharmacies Application: Hormone Replacement Therapy, Birth Control, Fertility Treatment, Menstrual Disorders Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Alkem Laboratories Ltd., Bionpharma Inc., Teva Pharmaceutical Industries Ltd., Estrellas Life Sciences Private Limited, Cipla Inc., Glenmark Pharmaceuticals Ltd., Lupin, Novo Nordisk A/S, Eli Lilly & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progesterone Market Emerging Trajectories
Formulation science and delivery technology are collapsing traditional route-of-administration hierarchies in progesterone therapy. Regulatory chemistry manufacturing and controls expectations are simultaneously tightening, compressing development timelines for new entrants.
Implantable depot formulations are collapsing the distinction between acute luteal support and chronic hormone replacement therapy. Fertility specialists in Spain and Italy are adopting 3-month subcutaneous implants for endometrial preparation in frozen embryo transfer cycles. This convergence is collapsing the market segmentation between short-acting injectables and long-acting contraceptive implants.
EMA's 2023 revision to ICH Q3D guideline implementation deadlines is forcing API manufacturers to requalify entire supplier networks for elemental impurity compliance. European finished dose producers are demanding certificates of analysis with expanded heavy metal panels from Indian and Chinese API sources. Vaginal gel formulations with complex polymer matrices face the most intensive revalidation burdens due to excipient-metal interaction risks.
Hospital procurement consortia in the United Kingdom and Netherlands are consolidating hormone therapy purchasing through centralized tender mechanisms. Traditional wholesale distribution through regional pharmacy networks is losing volume to direct manufacturer-to-hospital contracts with 36-month supply guarantees. This channel compression is most visible in assisted reproductive technology centers where formulary committees now mandate single-source progesterone protocols.
Progesterone Market Segmentation
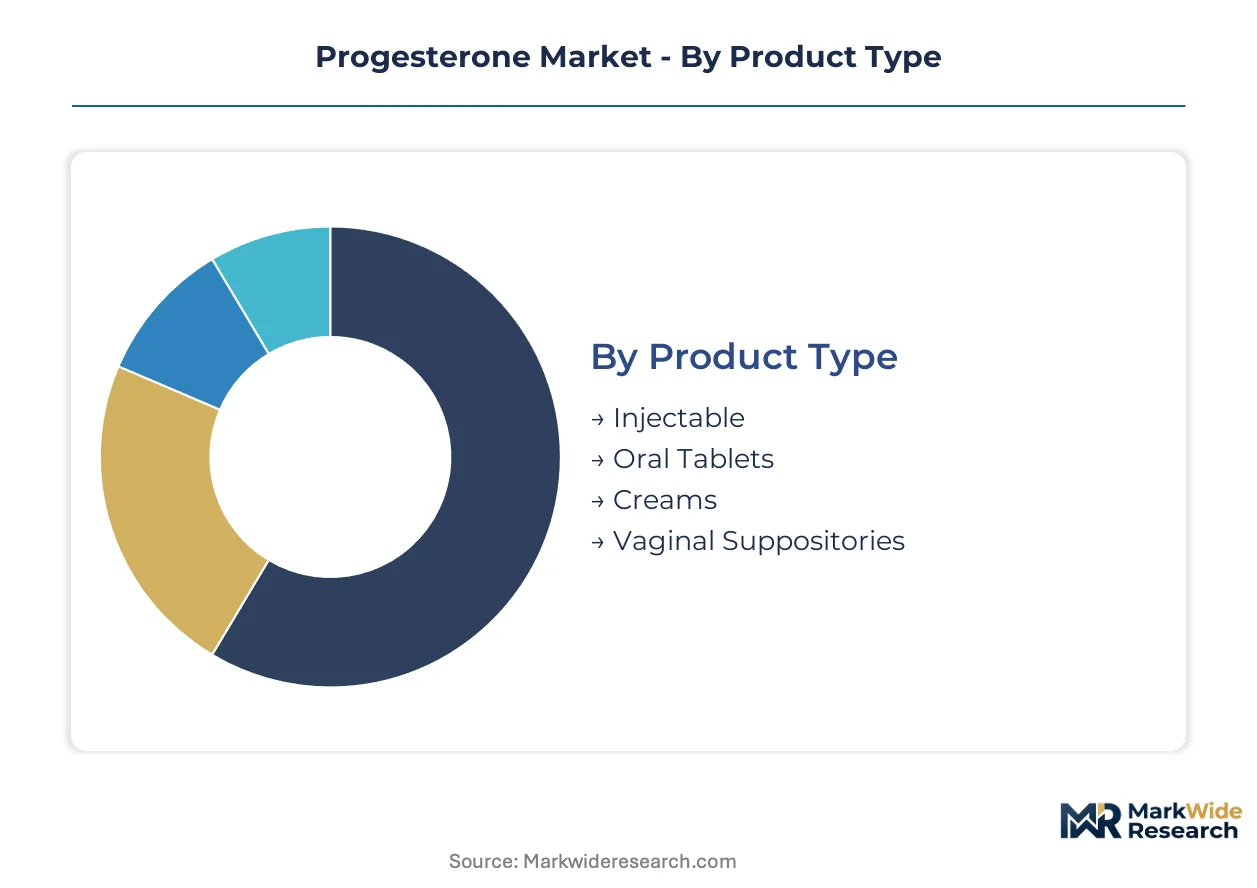
Route-of-administration hierarchies in progesterone therapy are collapsing as formulation science enables novel delivery platforms. Segmentation clarity matters for procurement teams navigating tightening bioequivalence standards and channel consolidation in fertility clinic networks.
Product Type:
After-sales service intensity varies sharply across formulation categories, with injectable and implantable formats demanding specialized training support that oral and topical products rarely require.
- Injectable:Oil-based or aqueous suspensions administered intramuscularly deliver precise serum concentration control for luteal phase support. Fertility clinics in India and the United States are standardizing injectable protocols, driving API procurement volumes as these centers consolidate purchasing through direct manufacturer contracts.
- Oral Tablets:Micronized progesterone formulations face bioavailability constraints from hepatic first-pass metabolism, requiring 10-fold higher doses than parenteral routes. Pharmacy procurement in cost-sensitive emerging markets favors oral tablets for birth control combinations where price minimization governs formulary decisions.
- Creams:Topical progesterone preparations offer patient-administered convenience for menopausal hormone therapy outside clinical settings. Compounding pharmacies in the United States are expanding customized cream formulations as patients seek alternatives to mass-manufactured dose tiers.
- Vaginal Suppositories:Lipophilic bases enable superior uterine first-pass uptake compared to systemic circulation routes. European fertility specialists are adopting vaginal gel formulations with complex polymer matrices despite intensive EMA revalidation burdens under ICH Q3D guidelines.
Injectable formulations hold the largest share; momentum sits with vaginal suppositories as first-pass uptake advantages reshape luteal support protocols.
End User:
Channel economics diverge sharply between institutional procurement and retail pharmacy networks, with volume concentration shifting toward direct manufacturer relationships.
- Hospitals:Centralized tender mechanisms in the United Kingdom and Netherlands are consolidating hormone therapy purchasing through 36-month supply guarantees. Hospital procurement consortia now mandate single-source progesterone protocols that bypass traditional wholesale distribution.
- Clinics:Assisted reproductive technology centers are overtaking traditional pharmacy channels in hormone replacement therapy procurement volumes. Fertility clinics in Spain and Italy are adopting 3-month subcutaneous implants for endometrial preparation in frozen embryo transfer cycles.
- Homecare:Patient-administered formulations reduce clinical visit burden for chronic hormone replacement therapy. Self-injection training programs and telemedicine monitoring are expanding homecare eligibility for subcutaneous auto-injector platforms.
- Pharmacies:Retail networks face volume erosion as institutional procurement concentrates purchasing power. Regional pharmacy distributors are losing share to direct manufacturer-to-hospital contracts with formulary committee gatekeeping.
Hospitals command the largest procurement volumes; clinics are climbing the fastest as fertility treatment standardization accelerates.
Application:
Clinical utility profiles vary across therapeutic indications, with fertility treatment protocols driving the most intensive formulation innovation cycles.
- Hormone Replacement Therapy:Menopausal symptom management combines estrogen with progesterone for endometrial protection. Compounding pharmacies are creating customized progesterone-progestin combinations outside mass-manufactured dose tiers as therapy unbundling progresses.
- Birth Control:Progestin-progesterone combinations in oral contraceptives prioritize cost minimization over bioavailability optimization. Generic substitution programs in Germany and France are creating volume pull for bioequivalent formulations in reimbursement frameworks.
- Fertility Treatment:Luteal phase support demands precise serum concentration maintenance for embryo implantation success. Injectable and vaginal routes dominate assisted reproductive technology protocols due to superior therapeutic efficacy ratings.
- Menstrual Disorders:Dysmenorrhea and irregular cycle management utilize progesterone for endometrial cycle regulation. Oral tablet convenience sustains volume in this segment despite pharmacokinetic limitations.
Fertility treatment captures the steepest expansion trajectory; hormone replacement therapy retains the largest installed base of chronic therapy patients.
Delivery Mode:
Pharmacokinetic optimization is displacing traditional route hierarchies as novel delivery technologies bypass hepatic metabolism constraints.
- Intravenous:Hospital-administered bolus dosing enables rapid serum concentration achievement in acute clinical settings. Critical care applications favor intravenous routes for precise titration control.
- Subcutaneous:Auto-injector platforms are capturing physician preference in luteal phase support protocols. Novel delivery technologies bypassing first-pass metabolism are reshaping competitive positioning in fertility clinic formularies.
- Oral:Hepatic metabolism necessitates high-dose formulations that compress clinical utility in cost-sensitive segments. Patient preference for non-invasive administration sustains oral volume despite pharmacokinetic inefficiency.
- Topical:Transdermal absorption offers patient convenience for menopausal hormone therapy with variable bioavailability. Cream and gel formulations face excipient-metal interaction risks under tightened ICH Q3D impurity profiling.
Oral delivery retains volume leadership; subcutaneous routes are gaining share fastest as auto-injector platforms overcome first-pass limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fertility clinics favor injectable progesterone for luteal support, while Indian and European markets increasingly adopt vaginal formulations for superior uterine uptake. This consumption-mix differential shapes API procurement patterns and finished-dose manufacturing priorities across geographies.
United States
Assisted reproductive technology centers in Massachusetts and California drive concentrated demand for parenteral progesterone formulations. FDA bioequivalence tightening for generic oral tablets is redirecting procurement toward injectable and vaginal alternatives with established efficacy profiles. Fertility clinic networks in the Boston-Cambridge corridor are consolidating purchasing through direct manufacturer contracts that bypass traditional wholesale channels.
India
Domestic API production and contract manufacturing for export markets anchor progesterone supply expansion in Maharashtra and Gujarat. CDSCO progressive local clinical trial mandates for imported APIs extend market entry timelines for multinational suppliers by 18-24 months. Hyderabad-based fermentation facilities are deploying engineered yeast strains for diosgenin-to-progesterone biotransformation with higher stereoselectivity than chemical synthesis routes.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia are consolidating hormone therapy purchasing through centralized tender mechanisms with 36-month supply guarantees. EMA ICH Q3D impurity profiling deadlines are forcing API manufacturers to requalify supplier networks for elemental heavy metal compliance. Frankfurt-Rhine-Main pharmaceutical clusters are reformulating excipient matrices to meet REACH-aligned chemical safety standards.
United Kingdom
National Health Service formulary committees in London and the Midlands now mandate single-source progesterone protocols for assisted reproductive technology centers. MHRA post-Brexit regulatory divergence from EMA guidelines is creating parallel compliance pathways for API registration and finished-dose approval. Cambridge-Oxford biotech corridors are piloting subcutaneous auto-injector platforms that bypass hepatic first-pass metabolism limitations.
Spain
Fertility specialists in Madrid and Barcelona are adopting 3-month subcutaneous progesterone implants for endometrial preparation in frozen embryo transfer cycles. AEMED pharmacovigilance obligations for hormone therapies are intensifying post-market surveillance requirements for both innovator and generic formulations. Catalonia's pharmaceutical manufacturing base is expanding vaginal gel production capacity despite excipient-metal interaction validation burdens under tightened EMA guidelines.
Progesterone Market Vendor Landscape
Capability concentration sits with vertically integrated API-to-finished-dose manufacturers; scale advantage sits with multinational generics houses with broad geographic footprints. The market structure tiers into three strategic archetypes: fermentation-based API specialists with microbial biotransformation expertise, formulation innovators pursuing novel delivery technologies, and volume-driven generics manufacturers competing on cost minimization. Dominant competitive moves include backward integration into diosgenin sourcing and strategic partnerships with fertility clinic networks for direct procurement contracts.
Among Israeli and Danish pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. and Novo Nordisk A/S exemplify contrasting strategic positions—Teva representing the vertically integrated generics archetype with captive API production, Novo Nordisk occupying the innovation-driven tier focused on delivery technology differentiation. Indian multinational Cipla Inc. anchors the emerging-market expansion archetype, leveraging regulatory pathway familiarity across high-volume geographies where price sensitivity governs procurement decisions.
| Leading Market Players |
|---|
| Alkem Laboratories Ltd. |
| Bionpharma Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Estrellas Life Sciences Private Limited |
| Cipla Inc. |
| Glenmark Pharmaceuticals Ltd. |
| Lupin |
| Novo Nordisk A/S |
| Eli Lilly & Company |
| Others |
Supply Flow & Price Mechanics
Mexican and Chinese wild yam harvesting concentration for diosgenin extraction anchors upstream margin capture, while downstream formulation tiers fragment pricing power across API manufacturers, contract manufacturers, and finished-dose marketers competing on bioequivalence certification status.
Pricing Analysis
Long-term offtake contracts dominate API procurement between Indian manufacturers and European finished-dose producers, insulating against diosgenin spot price volatility while compressing margins for non-integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified injectable formulations from EMA-aligned vaginal gels and unbranded oral tablets. Cost compression in oral segments is intensifying because Indian contract manufacturers are expanding microbial biotransformation capacity. Fertility clinics demonstrate lowest price sensitivity due to protocol standardization mandates, while retail pharmacy networks in emerging markets prioritize economy-tier procurement.
Supply Chain Analysis
Tariff exposure between Mexico and India for diosgenin-derived intermediates dominates supply chain risk planning, forcing manufacturers to dual-source steroid precursors across hemispheres. API production concentrates in India, China, and Italy, with fermentation-based biotransformation capacity expanding fastest in Hyderabad and Ahmedabad. Raw material dependencies center on wild yam tubers, palladium catalysts for hydrogenation steps, and pharmaceutical-grade oils for injectable formulations. Single-source vulnerability persists for stereoselective microbial strains engineered at Indian contract research facilities. Distribution runs through direct manufacturer-to-hospital contracts in regulated markets, bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA and EMA bioequivalence standards create switching costs that lock in incumbent API-to-finished-dose relationships across fertility clinic networks.
For Market Incumbents: Pre-empt generic substitution threats by securing captive diosgenin supply through backward integration into Mexican wild yam harvesting cooperatives or engineered yeast strain patent portfolios. Expand microbial biotransformation capacity in Maharashtra to capture cost advantages over chemical synthesis competitors. Lock in 36-month direct procurement contracts with assisted reproductive technology centers before EMA biosimilar substitution pathways mature.
For New Entrants and Emerging Players: Build out subcutaneous auto-injector platform capabilities targeting luteal phase support protocols where first-pass metabolism limitations create white-space opportunities outside oral tablet commoditization. Penetrate United States fertility clinic networks through specialized training partnerships that incumbent generics manufacturers underinvest in. Pursue compounding pharmacy relationships for customized menopausal hormone therapy combinations outside mass-manufactured dose tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated API-to-finished-dose specialists with captive fermentation capacity and established FDA master file portfolios. Long-term viability hinges on regulatory chemistry manufacturing and controls expertise scarcity that limits viable acquisition targets. Monitor CDSCO local clinical trial mandate enforcement as inflection indicator for multinational market entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Biotransformation Scale-Up | Engineered yeast deployment at Hyderabad facilities reduces diosgenin dependency and palladium catalyst exposure. |
| Direct Hospital Procurement Contracts | Bypassing wholesale channels secures 36-month volume commitments from United Kingdom fertility clinic consortia. |
| Subcutaneous Auto-Injector Development | Novel delivery platforms capture physician preference by overcoming hepatic first-pass metabolism limitations. |
| ICH Q3D Compliance Revalidation | Elemental impurity profiling upgrades protect EMA market access against supplier network disqualification. |
| Compounding Pharmacy Partnership | Customized progesterone-progestin combinations access menopausal hormone therapy unbundling demand. |
Methodological Framework
Operator-level perspectives from API manufacturing directors, fertility clinic procurement managers, regulatory affairs leads at multinational generics houses, and compounding pharmacy formulators anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Orange Book filings, EMA EPAR assessments, CDSCO approval databases, and Indian pharmaceutical export statistics. Bottom-up volume modeling across dosage forms, administration routes, and regional regulatory clusters triangulated against top-down market sizing from customs data and industry association reports.
Scenario-bracketing framed analytical approaches across the projection horizon, with base, upside, and downside cases reflecting bioequivalence standard enforcement intensity and fertility clinic protocol standardization pace. Segmentation dimensions modeled include route of administration, end-user channel, therapeutic application, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to observable procurement volume trajectories in India and United States fertility networks. Forecast inputs incorporated ICH Q3D implementation deadline shifts and CDSCO clinical trial mandate progression.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese API specialists or rapid EMA biosimilar substitution policy expansion would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Recombinant Hormone Market