
 Allergic Rhinitis Treatment Market | 2026-2036
Allergic Rhinitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Allergic Rhinitis Treatment Market Intelligence
Project finance for biologics manufacturing facilities is reshaping competitive entry in allergic rhinitis therapeutics, lowering capital barriers for mid-scale producers. Sanofi leverages its European manufacturing network to sustain corticosteroid supply continuity across seasonal demand cycles. GSK plc anchors its position through R&D intensity in nasal spray formulation science. Regeneron Pharmaceuticals Inc. competes via specialized monoclonal antibody development for refractory patient populations.
Allergic rhinitis treatment encompasses pharmacological and immunological interventions targeting IgE-mediated nasal mucosa inflammation, with corticosteroid sprays typically delivering 50-200 micrograms per actuation to suppress local cytokine release and reduce turbinate swelling. The primary purpose spans symptomatic relief through histamine blockade and disease modification via allergen desensitization protocols. Antihistamines and corticosteroids together occupy the mature core of the product landscape, while immunotherapy segments attract disproportionate investment as sublingual tablet approvals extend treatment access beyond injection-dependent protocols. Nasal sprays dominate delivery mode volumes due to direct mucosal targeting, though oral tablets retain pharmacy channel preference for first-line patient self-selection.
FDA bioequivalence standards for generic intranasal corticosteroids and EMA's MDR requirements for combination drug-device products together elevate manufacturing compliance costs while protecting innovator margins. EPA environmental assessments for propellant-based delivery systems additionally constrain formulation choices among US-market suppliers. Stakeholders must monitor evolving pharmacovigilance obligations for biologic rhinitis therapies as regulators tighten post-market surveillance frameworks.
Market Dynamics
Allergen immunotherapy protocols are displacing chronic pharmacotherapy as first-line disease modification, compressing lifetime patient value toward upfront treatment investments while reducing recurring prescription dependencies.
Growth Catalysts
- Sublingual tablet platforms:Oral allergen delivery systems eliminate injection clinic requirements, expanding treatable patient populations beyond urban specialist catchments.
- EMA MDR compliance frameworks:Combination drug-device regulatory harmonization accelerates cross-border product approvals and standardizes quality benchmarks across European markets.
- Pediatric allergy clinic expansion:German university hospitals are scaling desensitization programs, creating dedicated referral pathways that normalize immunotherapy initiation in childhood.
Market Restraints
- Propellant chemistry constraints:EPA environmental assessments restrict hydrofluoroalkane formulations, forcing costly reformulation of established nasal spray products.
- Active pharmaceutical ingredient concentration:Corticosteroid precursor supply depends on concentrated Chinese and Indian manufacturing clusters, exposing formulations to geopolitical trade friction.
- Biologic cold chain requirements:Monoclonal antibody therapies require uninterrupted refrigerated distribution, limiting rural pharmacy participation and inflating logistics costs.
Strategic Opportunities
- Refractory patient biologics:Severe eosinophilic phenotypes inadequately controlled by standard therapy represent addressable populations for targeted monoclonal development.
- EU Green Deal manufacturing incentives:Sustainable process subsidies favor pharmaceutical facilities adopting solvent recovery and renewable energy integration.
- Direct-to-patient subscription models:Sublingual immunotherapy home administration enables recurring revenue structures bypassing traditional pharmacy dispensing.
Industry Challenges
- Specialized immunology workforce scarcity:Allergen extract preparation and dose escalation protocols require trained personnel that academic programs are not producing at replacement rates.
- Multi-year clinical trial timelines:Immunotherapy efficacy endpoints demand extended observation periods, compressing effective patent protection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergic Rhinitis Treatment Market |
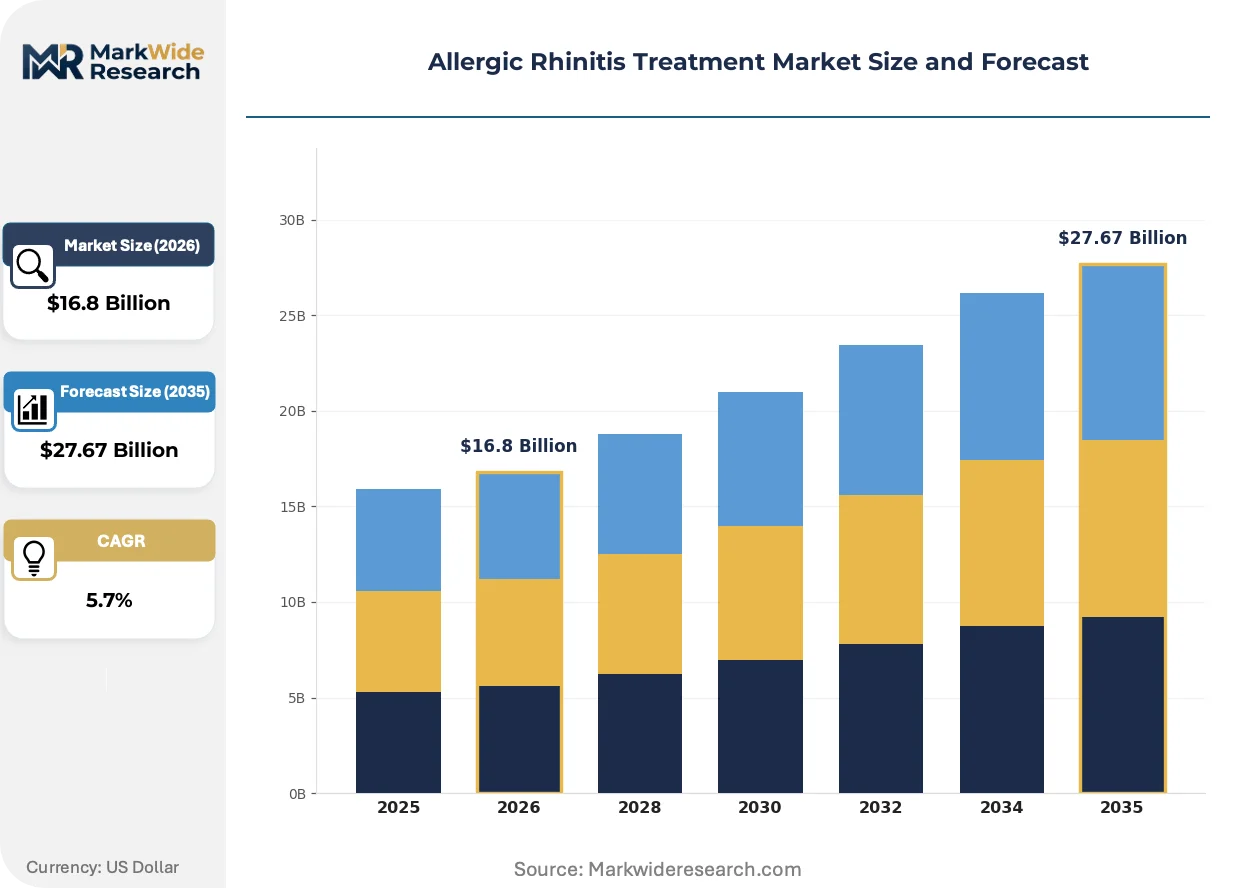
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Decongestants, Leukotriene Receptor Antagonists, Immunotherapy Therapy Area: Seasonal Allergic Rhinitis, Perennial Allergic Rhinitis, Occupational Rhinitis, Vasomotor Rhinitis End User: Otolaryngology Clinics, Allergy Specialists, Primary Care Centers, Pharmacies Delivery Mode: Nasal Sprays, Oral Tablets, Eye Drops, Injections |
| Companies Covered | Boehringer Ingelheim International GmbH, Teva Pharmaceutical Industries Ltd., Sanofi, Bayer AG, Novartis AG, GSK plc, AstraZeneca, Regeneron Pharmaceuticals Inc., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergic Rhinitis Treatment Market Strategic Shifts & Innovations
Formulation science and delivery mechanism engineering are converging to reduce treatment burden while improving mucosal targeting precision. These advances are restructuring competitive advantage around bioavailability optimization rather than molecular novelty alone.
Dry powder nasal delivery systems are rendering obsolete aqueous spray formulations for corticosteroid administration. Otolaryngology practices in France and the Netherlands are adopting breath-actuated devices that deposit active compounds in the anterior nasal cavity with reduced pharyngeal runoff. This technology is rendering obsolete conventional pump mechanisms that relied on patient coordination and generated significant systemic absorption.
FDA bioequivalence standards for generic intranasal corticosteroids have tightened pharmacokinetic comparison requirements, forcing generic sponsors to invest in sophisticated clinical endpoint studies. The agency now demands demonstration of comparable nasal deposition patterns through gamma scintigraphy or equivalent imaging modalities. Innovator manufacturers with established formulation expertise are leveraging these barriers to extend market exclusivity through device-locked combination products.
Self-administered sublingual protocols are displacing supervised injection regimens in working-age adult populations. French occupational health networks have established workplace-based initiation programs that eliminate clinic visit requirements during business hours. This behavioral shift concentrates demand among tablet formulations with established food-independent absorption profiles and 24-hour dosing convenience.
Allergic Rhinitis Treatment Market Segmentation
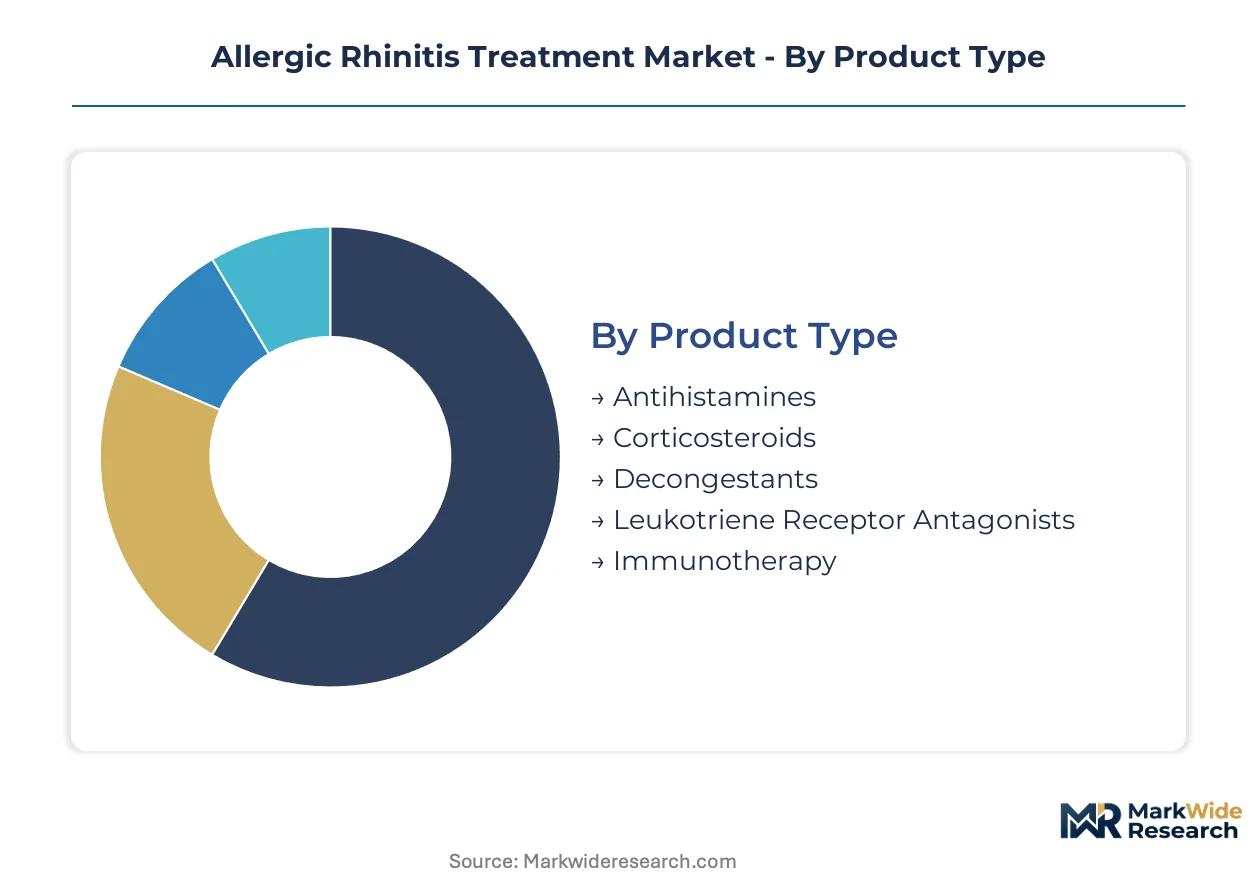
Allergic rhinitis therapeutics fragment across four dimensions that determine prescribing patterns, reimbursement pathways, and competitive positioning. Product type segmentation reveals the tension between symptom suppression and disease modification, while therapy area distinctions govern seasonal inventory planning and patient lifetime value calculations.
Product Type:
Mature pharmacological classes dominate prescription volumes, yet emerging immunological interventions are capturing disproportionate investment flows as disease-modifying protocols displace chronic symptom management.
- Antihistamines:First-generation compounds block H1 receptors peripherally, though sedation limits workplace utility; second-generation formulations such as cetirizine and loratadine concentrate demand among French working-age adults seeking non-impairing relief. The shift toward once-daily oral dosing has compressed pharmacy dispensing margins while expanding self-selection at retail.
- Corticosteroids:Intranasal formulations deliver 50-200 micrograms per actuation directly to nasal mucosa, suppressing local cytokine cascades with minimal systemic absorption. German otolaryngology practices favor fluticasone propionate aqueous sprays for turbinate reduction, though EPA propellant restrictions are forcing aqueous reformulation of older HFA-dependent products.
- Decongestants:Alpha-adrenergic agonists provide rapid nasal patency restoration through vasoconstriction.
- Leukotriene Receptor Antagonists:Montelukast and comparable agents target inflammatory mediators downstream of IgE activation.
- Immunotherapy:Sublingual tablet platforms eliminate injection clinic dependency, with German pediatric allergy programs scaling desensitization protocols that normalize childhood initiation.
Corticosteroids retain volume leadership among prescription-dependent patients; immunotherapy holds the steepest expansion curve as sublingual approvals extend beyond specialist catchments.
Therapy Area:
Cost tier stratification separates acute seasonal intervention from chronic perennial management, with reimbursement intensity scaling to disease duration and occupational impairment severity.
- Seasonal Allergic Rhinitis:Pollen-driven phenotypes concentrate demand in April-July windows across temperate European latitudes, requiring flexible manufacturing capacity and predictive inventory positioning. French occupational health networks have established workplace-based initiation programs that align treatment timing with peak allergen exposure.
- Perennial Allergic Rhinitis:Year-round house dust mite and pet dander sensitivity demands continuous pharmacotherapy or extended immunotherapy protocols, generating higher lifetime patient value but requiring sustained adherence support. German primary care centers manage the majority of these cases through standardized step-care algorithms.
- Occupational Rhinitis:Workplace allergen exposure triggers distinct regulatory reporting obligations and employer liability frameworks.
- Vasomotor Rhinitis:Non-allergic triggers including temperature shifts and irritant exposure respond poorly to antihistamine therapy, limiting addressable market for IgE-targeted interventions.
Seasonal allergic rhinitis commands peak seasonal manufacturing capacity; perennial allergic rhinitis generates the most stable recurring revenue streams.
End User:
Customer type fragmentation reflects referral pathway complexity, with specialist gatekeeping determining access to advanced immunotherapy versus pharmacy-directed self-care.
- Otolaryngology Clinics:Surgical and medical rhinology specialists manage refractory cases with structural complications, prescribing combination intranasal corticosteroid-antihistamine sprays and evaluating turbinate reduction candidacy. Dutch breath-actuated device adoption concentrates in this channel.
- Allergy Specialists:Immunotherapy protocol design and allergen extract preparation require dedicated personnel that academic programs are not producing at replacement rates. German university hospitals are scaling dedicated desensitization programs that normalize childhood initiation.
- Primary Care Centers:First-line prescribing of generic antihistamines and over-the-counter intranasal corticosteroids dominates patient volume.
- Pharmacies:Self-selection of non-sedating antihistamines and saline irrigation products captures mild symptom management.
Allergy specialists control access to highest-value immunotherapy protocols; primary care centers process the greatest prescription volume.
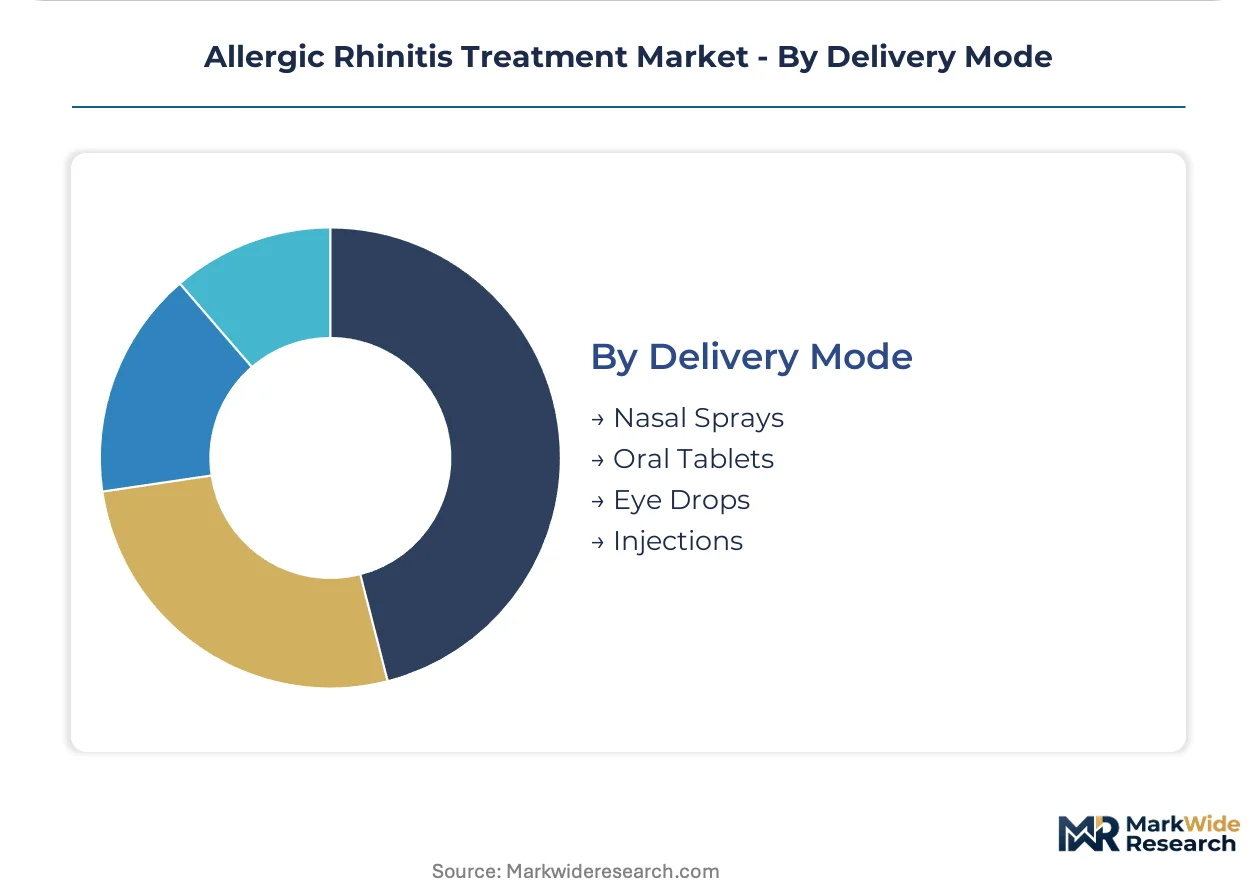
Delivery Mode:
Supply concentration in device manufacturing clusters shapes competitive access, with combination drug-device regulatory harmonization accelerating cross-border approvals.
- Nasal Sprays:Direct mucosal targeting maximizes local bioavailability while minimizing systemic exposure, though patient coordination requirements and pharyngeal runoff limit deposition precision. Breath-actuated devices are displacing conventional pump mechanisms in French and Dutch specialist practices.
- Oral Tablets:Pharmacy channel preference for first-line self-selection concentrates demand in non-sedating antihistamine and sublingual immunotherapy formulations with food-independent absorption.
- Eye Drops:Topical antihistamine and mast cell stabilizer formulations address conjunctival symptoms that frequently accompany nasal pathology.
- Injections:Subcutaneous immunotherapy protocols require supervised administration, constraining patient populations to urban specialist catchments.
Nasal sprays dominate device-dependent prescribing; oral tablets are climbing the fastest as sublingual immunotherapy home administration eliminates clinic visit requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for corticosteroid precursors shapes trade flows, with finished formulation exports from European manufacturing hubs offsetting raw material purchases from Asian chemical clusters. Currency volatility and regulatory divergence create arbitrage opportunities in cross-border pharmaceutical distribution.
Germany
Pediatric allergy clinics at university hospitals in Munich and Heidelberg are expanding sublingual immunotherapy programs for house dust mite desensitization. The EU Green Deal manufacturing incentives are accelerating solvent recovery adoption at pharmaceutical facilities in the Rhine-Main cluster. Bavarian otolaryngology practices are piloting breath-actuated nasal delivery devices that reduce pharyngeal deposition.
France
Occupational health networks in Paris and Lyon have established workplace-based immunotherapy initiation programs that eliminate clinic visit requirements. ANSM pharmacovigilance frameworks are tightening post-market surveillance for biologic rhinitis therapies. The Île-de-France region concentrates demand for non-sedating antihistamines among working-age adults seeking symptom relief without cognitive impairment.
United States
FDA bioequivalence standards for generic intranasal corticosteroids are elevating clinical endpoint study requirements through gamma scintigraphy deposition comparisons. EPA environmental assessments are constraining hydrofluoroalkane propellant formulations in nasal spray products. The Research Triangle Park cluster in North Carolina anchors contract manufacturing for aqueous corticosteroid reformulations.
United Kingdom
NICE cost-effectiveness thresholds are prioritizing sublingual immunotherapy tablets over injection protocols in seasonal allergic rhinitis guidelines. MHRA post-Brexit regulatory autonomy is diverging from EMA MDR harmonization timelines for combination drug-device approvals. London-based allergy specialists are consolidating referral pathways for refractory eosinophilic phenotypes requiring monoclonal antibody evaluation.
Japan
PMDA seasonal approval windows for pollen-driven therapeutics concentrate manufacturing campaigns in Osaka and Tokyo pharmaceutical corridors. METI pharmaceutical competitiveness subsidies are supporting dry powder nasal delivery technology development. Kansai region primary care networks are standardizing step-care algorithms that escalate from antihistamines to intranasal corticosteroids before immunotherapy referral.
Allergic Rhinitis Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in active pharmaceutical ingredient and device manufacturing. Market structure consolidates around multinational pharmaceutical conglomerates with established European manufacturing networks, while mid-scale producers exploit project finance structures to enter biologics manufacturing. Three archetypes dominate: corticosteroid formulation incumbents with device-locked combination products, sublingual immunotherapy specialists expanding beyond injection-dependent protocols, and monoclonal antibody developers targeting refractory patient populations. Competitive moves center on sustainable process certification for EU Green Deal compliance and direct-to-patient subscription models that bypass traditional pharmacy channels.
Among European-based pharmaceutical conglomerates, Sanofi, GSK plc, and Boehringer Ingelheim International GmbH occupy positions that exemplify distinct competitive vectors. Sanofi represents the corticosteroid incumbent archetype with manufacturing network continuity across seasonal demand cycles. GSK plc sits within the formulation science intensifier tier, anchoring R&D investment in nasal spray delivery optimization. Boehringer Ingelheim International GmbH exemplifies the diversified respiratory portfolio structure that spans allergic rhinitis into adjacent obstructive airway indications.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Bayer AG |
| Novartis AG |
| GSK plc |
| AstraZeneca |
| Regeneron Pharmaceuticals Inc. |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
The Rhine-Main pharmaceutical corridor's freight cost dynamics link concentrated corticosteroid precursor supply to downstream price differentiation between aqueous spray reformulations and legacy propellant-dependent products. API concentration in Indian and Chinese manufacturing clusters amplifies logistics cost sensitivity, while EPA environmental assessments force costly formulation shifts that concentrate pricing power among established European manufacturers with solvent recovery capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in allergic rhinitis therapeutics. Certification grade under FDA bioequivalence standards and EMA MDR compliance tiers separate innovator device-locked combinations from generic aqueous sprays. Pricing pressure stems from propellant chemistry constraints forcing HFA-to-aqueous reformulation investments. Primary care centers exhibit highest price sensitivity due to step-care algorithm standardization, while allergy specialists demonstrate lowest sensitivity given immunotherapy protocol lock-in.
Supply Chain Analysis
Contract manufacturing concentration at Boehringer Ingelheim's Ingelheim site and GSK plc's Ware and Montrose facilities anchors European finished formulation capacity. Active pharmaceutical ingredient supply draws from concentrated manufacturing clusters in India and China for corticosteroid precursors, with German and Swiss facilities handling final combination processing. Single-source vulnerability in Chinese API precursors for fluticasone propionate creates structural exposure. Distribution runs through specialist clinic networks for immunotherapy protocols and pharmacy channels for self-selected antihistamine products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Allergic rhinitis therapeutics present a fragmentation opportunity as sublingual tablet platforms displace injection-dependent protocols, creating specialized niches for home-administration formulations and workplace-based initiation programs.
For Market Incumbents: Entrench position through backward integration into API precursor supply and captive device manufacturing for breath-actuated delivery systems. Sanofi's European manufacturing network continuity offers a template for seasonal demand cycle management. Prioritize EMA MDR certification investment to extend combination product exclusivity against generic gamma scintigraphy barriers.
For New Entrants and Emerging Players: Build out direct-to-patient subscription infrastructure targeting French occupational health networks and German pediatric allergy clinic referral pathways. The most penetrable segment lies in sublingual immunotherapy home administration for working-age adults seeking clinic-visit elimination. Pursue EU Green Deal sustainable process certification as a differentiated go-to-market credential.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking respiratory portfolio rationalization, particularly sublingual tablet platforms with established food-independent absorption profiles. Long-term viability centers on disease-modifying protocol displacement of chronic pharmacotherapy. Monitor EMA MDR harmonization timelines and FDA bioequivalence standard tightening as inflection indicators for generic competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA MDR compliance for combination drug-device products accelerates cross-border European market access. |
| Manufacturing Scale-Up | Solvent recovery adoption at Rhine-Main facilities aligns with EU Green Deal subsidy eligibility requirements. |
| Pipeline Diversification | Monoclonal antibody development for refractory eosinophilic phenotypes addresses underserved severe patient populations. |
| Distribution Channel Expansion | Workplace-based immunotherapy initiation programs in Paris and Lyon bypass traditional pharmacy dispensing. |
| Sustainability Repositioning | Dry powder nasal delivery technology eliminates aqueous spray propellant chemistry constraints under EPA assessments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation anchored volume and value estimates.
Forecast inputs across the projection horizon incorporated treatment line stratification, dosage form segmentation, administration route differentiation, and regional regulatory cluster dynamics. CAGRs derived from patient cohort growth, protocol substitution rates, and pricing trajectory modeling. Specific inputs included immunotherapy penetration curves in German pediatric settings and sublingual tablet uptake in French occupational health networks.
Practitioners should monitor EMA MDR implementation timelines, FDA bioequivalence standard evolution, and API precursor trade flow disruptions for early signals of forecast revision. Quarterly review of regulatory submission cadences and pediatric allergy clinic expansion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market