
 US Frozen Cocktail Popsicles Market | 2026-2036
US Frozen Cocktail Popsicles Market Size, Share, and Industry Trends Forecast 2026-2036
US Frozen Cocktail Popsicles Market Insights
The US Frozen Cocktail Popsicles Market is rebalancing between premium craft formulations and mass-market commodity offerings, with alcohol content clarity and ingredient sourcing becoming the fault lines. Cutwater Spirits leverages its spirits heritage to anchor premium positioning through proprietary base formulations. Slim Chillers competes on portion-controlled formats that sustain repeat purchase frequency in club retail channels.
Frozen cocktail popsicles are alcohol-infused frozen confections manufactured through controlled freezing of distilled spirits, wine, or malt bases combined with flavoring agents and stabilizers, typically containing 5-15% ABV and engineered for single-serve consumption occasions. The alcoholic segment dominates current revenue pools while organic formulations capture the fastest-growing margin tier as clean-label expectations migrate from food to beverage alcohol. Distribution through food service channels concentrates volume, though online direct-to-consumer pathways expand fastest as state-level shipping regulations loosen.
FDA labeling mandates for alcohol content and TTB formula approval requirements shape product development timelines and interstate market access for manufacturers. State-level ABC boards impose additional tier restrictions that fragment go-to-market strategies across jurisdictions. Stakeholders must monitor evolving direct-shipping legislation and TTB guidance on frozen alcohol product classification to anticipate channel expansion feasibility.
Market Dynamics
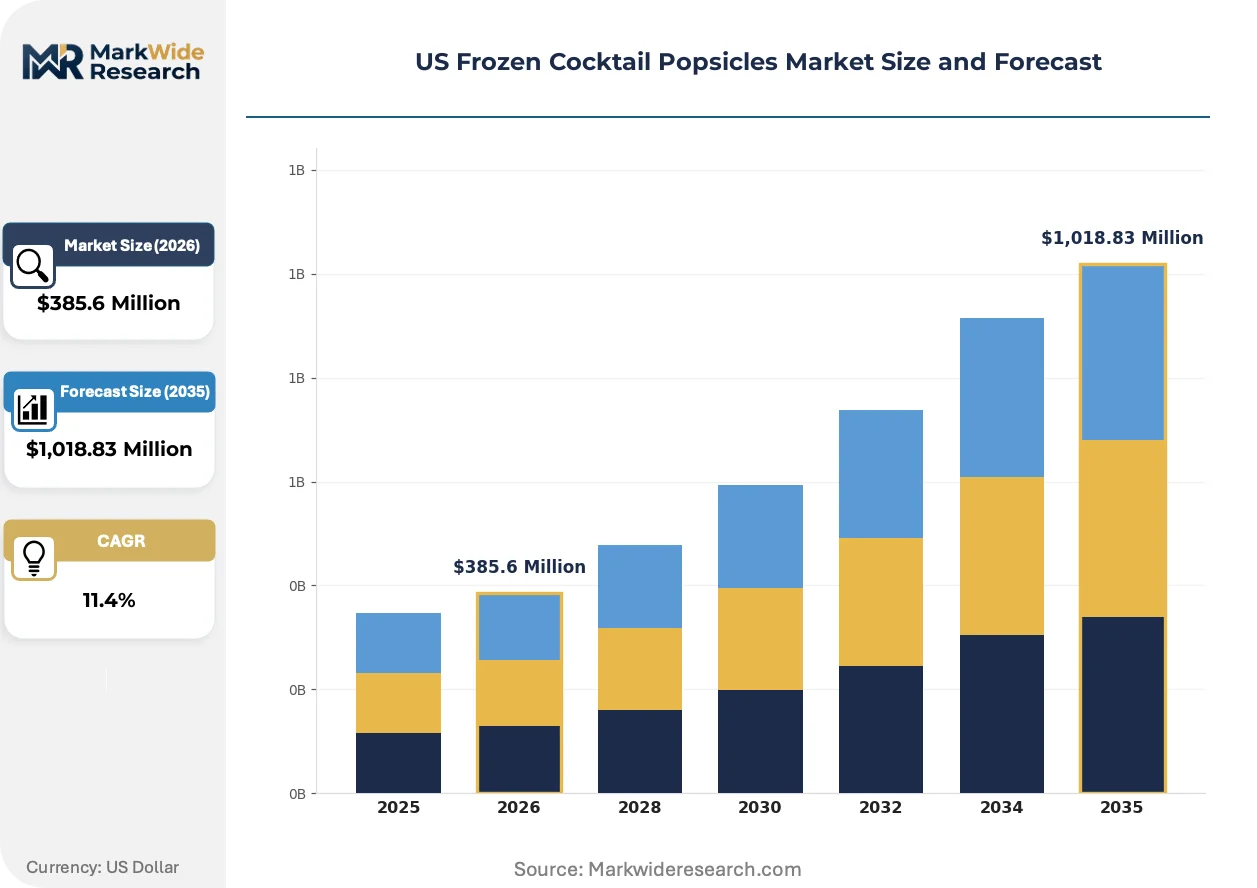
TTB formula approval requirements and state-level ABC board tier restrictions are fragmenting go-to-market strategies, forcing manufacturers to build jurisdiction-specific distribution networks rather than national rollouts.
Growth Catalysts
- Direct-to-Consumer Channel Liberalization:Loosening state-level shipping regulations for alcohol-infused products enables manufacturers to bypass traditional three-tier distribution. California, Florida, and New York lead this regulatory evolution.
- FDA Labeling Clarity Mandates:Standardized alcohol content disclosure requirements reduce consumer confusion and accelerate retail shelf placement velocity. This regulatory framework builds retailer confidence in frozen alcohol categories.
- Premium Frozen Beverage Culture:Coastal metropolitan clusters demonstrate sustained consumption of craft cocktail formats. Adult social gatherings in these geographies normalize single-serve frozen alcohol as occasion-appropriate.
Market Restraints
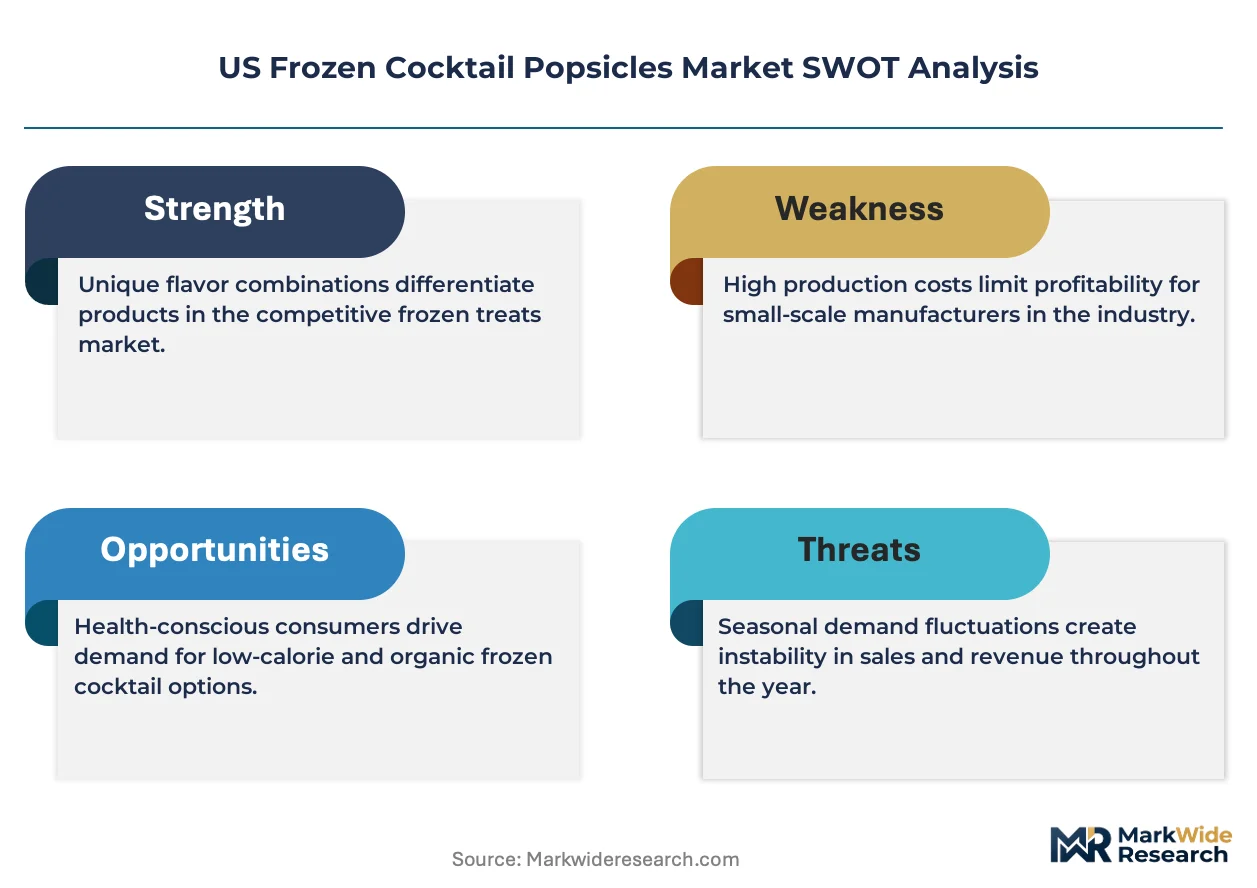
- Ethanol Supply Concentration:Distilled spirits base procurement depends on concentrated Midwest grain ethanol production. Weather volatility and biofuel policy shifts transmit directly to input cost instability.
- Interstate Distribution Friction:State ABC board tier restrictions prevent uniform national distribution. Each jurisdiction requires separate wholesaler relationships and compliance documentation.
- TTB Approval Timeline Compression:Formula approval processes extend product development cycles by 4-8 months. This regulatory lag delays market entry for seasonal flavor innovations.
Strategic Opportunities
- Organic Formulation Tier:Clean-label ingredient sourcing captures margin expansion as consumer expectations migrate from food to beverage alcohol. USDA organic certification enables premium positioning.
- Food Service Channel Deepening:On-premise venues in Florida and California demonstrate underpenetrated potential for frozen cocktail popsicle programs. Poolside and beachfront hospitality formats represent white space.
- Controlled-Atmosphere Freezing Technology:Precision temperature management systems reduce ice crystal formation and improve mouthfeel. This equipment convergence enables ABV elevation without texture degradation.
Industry Challenges
- TTB Classification Ambiguity:Frozen alcohol product categorization remains unresolved in federal guidance. Manufacturers face compliance uncertainty regarding excise tax treatment and labeling jurisdiction.
- Cold Chain Integrity Requirements:Maintaining -18°C through last-mile delivery demands specialized logistics infrastructure. Capital deployment for refrigerated transportation networks strains emerging brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Frozen Cocktail Popsicles Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcoholic, Non-Alcoholic, Organic, Gluten-Free Flavor Profile: Citrus, Berry, Tropical, Creamy Packaging Type: Pouches, Cups, Boxes, Bulk Packaging Distribution Channel: Retail Stores, Online, Food Service, Events |
| Companies Covered | Shooter Pops, LLC - Claffey’s Cocktails, Cooloo, American Beverage Corporation - Daily’s Cocktails, Cutwater Spirits, Slim Chillers, FrutaPop, LIC Frozen Cocktails, SnöBar, Fishers Island Lemonade, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Frozen Cocktail Popsicles Market Trends and Innovations
Formulation science and distribution technology are converging to reshape how alcohol-infused frozen products reach consumers, with regulatory clarity and sensory engineering driving competitive differentiation.
Controlled-atmosphere freezing equipment is expanding into production facilities serving the premium tier. This technology manipulates nucleation rates to achieve smaller ice crystal structures than conventional blast freezing. Craft manufacturers in California and New York adopt these systems to support 10-15% ABV formulations without sacrificing texture integrity. The equipment investment is expanding into mid-tier producers as lease financing models reduce capital barriers.
TTB guidance development on frozen alcohol classification is reshaping interstate commerce feasibility. Pending federal determinations will clarify whether these products fall under wine, distilled spirits, or malt beverage tax treatment. This regulatory uncertainty most acutely affects direct-to-consumer shippers building multi-state fulfillment networks. Manufacturers are responding by diversifying state-level legal counsel and delaying national marketing campaigns until classification resolves.
Club retail procurement patterns are compressing supplier qualification cycles. Buyers at Costco and Sam's Club now demand 90-day sell-through guarantees rather than annual volume commitments. This shift forces manufacturers to abandon seasonal SKU proliferation in favor of core flavor permanence. The pattern is most visible in Florida, where warehouse club volume concentrates and repeat purchase frequency determines shelf survival.
US Frozen Cocktail Popsicles Market Segmentation
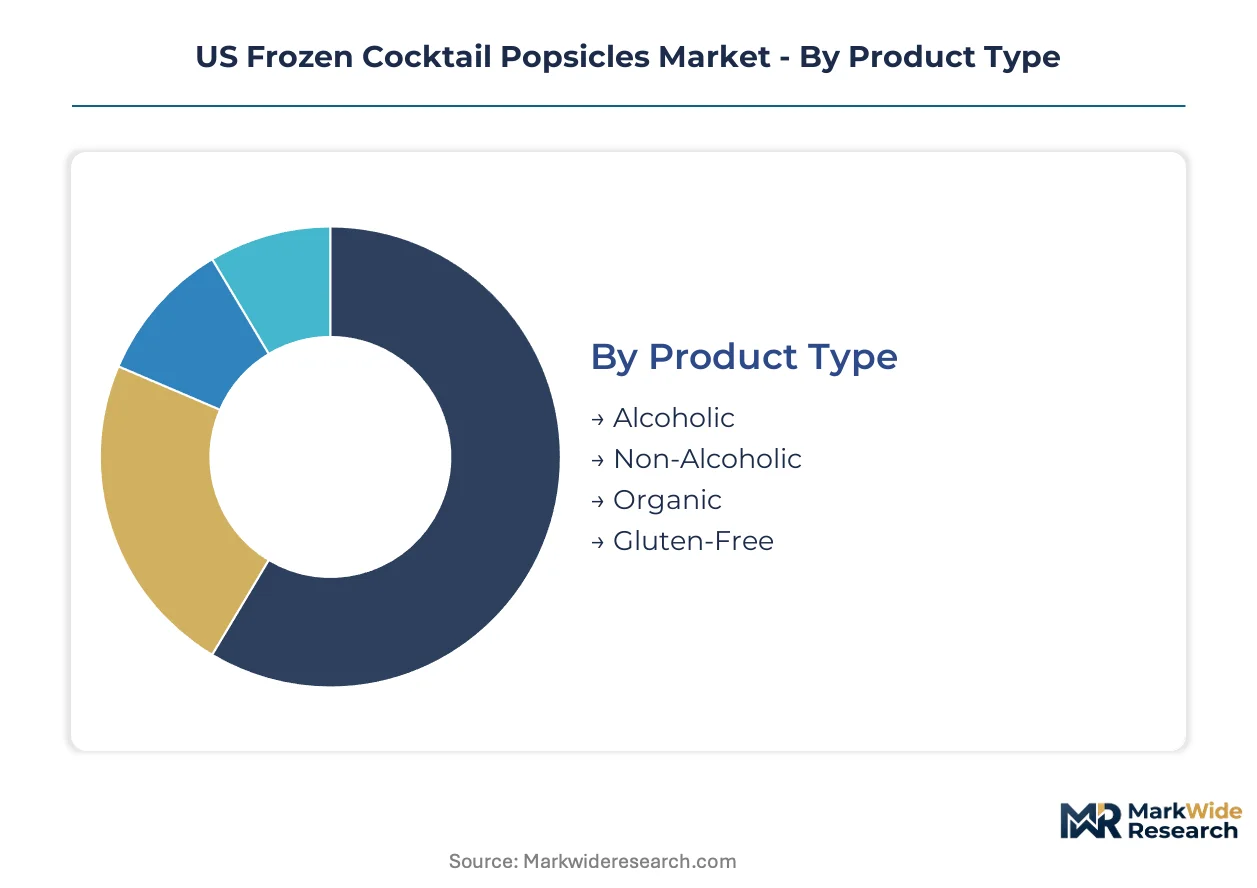
Segmentation in the US Frozen Cocktail Popsicles Market exposes how formulation chemistry, packaging engineering, and channel access create distinct competitive arenas. Each dimension carries unique regulatory burdens and margin structures that reshape manufacturer priorities.
Product Type:
Supply concentration in ethanol sourcing and organic certification capacity is fragmenting competitive positioning across formulation tiers.
- Alcoholic:Distilled spirits, wine, or malt bases frozen with stabilizers at 5-15% ABV. Demand clusters in California, Florida, and New York poolside venues where adult social gatherings normalize single-serve frozen consumption. TTB formula approval timelines and state ABC tier restrictions constrain interstate rollout velocity.
- Organic:USDA-certified formulations using clean-label ingredient sourcing. Margin expansion is steepest here as consumer expectations migrate from food to beverage alcohol. Certification bottlenecks and ingredient procurement costs limit supplier proliferation.
- Non-Alcoholic:Spirit-flavored frozen confections without ethanol content, targeting designated drivers and family-inclusive occasions.
- Gluten-Free:Malt-free formulations using alternative grain bases, capturing celiac-sensitive and wellness-positioned consumers.
Today's leader: Alcoholic. Tomorrow's challenger: Organic.
Flavor Profile:
Application-driven demand concentration in coastal hospitality venues is elevating certain taste architectures above commodity alternatives.
- Citrus:Lemon, lime, and grapefruit-forward formulations leveraging natural acidity for shelf stability and palate refreshment. Florida beachfront resorts and California rooftop bars concentrate procurement volume for this profile.
- Tropical:Coconut, pineapple, and passion fruit bases. Demand concentrates in Florida poolside hospitality where vacation-consumption psychology supports premium pricing.
- Berry:Strawberry, raspberry, and blueberry infusions targeting health-positioned consumption occasions.
- Creamy:Dairy or coconut cream-based frozen desserts with dessert-cocktail hybrid positioning.
Volume currently favors Citrus. Expansion is climbing fastest in Tropical.
Packaging Type:
Cost tier differentiation between single-serve convenience and food service operational efficiency is reshaping procurement specifications.
- Pouches:Flexible film single-serve formats optimizing freezer space and direct consumption. Club retail channels in Florida demand 90-day sell-through guarantees for these SKUs.
- Cups:Rigid portion-controlled containers supporting on-premise service in hospitality venues. California craft manufacturers favor this format for premium positioning.
- Boxes:Multi-count retail packaging for home freezer stockpiling and gift occasions.
- Bulk Packaging:Food service totes for high-volume hospitality accounts with dedicated freezer infrastructure.
Margin protection centers on Cups. Volume scaling depends on Pouches.
Distribution Channel:
Geographic concentration in direct-to-consumer regulatory liberalization is accelerating channel migration away from traditional three-tier systems.
- Online:Direct-to-consumer shipping enabled by loosening state-level alcohol delivery regulations. California, Florida, and New York lead this regulatory evolution, though TTB classification ambiguity complicates multi-state fulfillment.
- Food Service:On-premise venues including poolside hospitality and beachfront bars. Underpenetrated potential exists in Florida and California resort formats.
- Retail Stores:Grocery and liquor store frozen sections requiring cold chain integrity through last-mile delivery.
- Events:Festival and private party catering with temporary permitting requirements.
Speed of access favors Online. Stability of demand anchors in Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage formulation talent clusters along coastal metropolitan corridors where frozen cocktail culture has achieved mainstream normalization. TTB field offices and state ABC administrative capacity concentrate in these same jurisdictions, creating regulatory expertise pools that accelerate product approval velocity.
California
Los Angeles and San Diego hospitality workforces sustain the nation's densest concentration of frozen beverage program specialists. California ABC direct-shipping permits for alcohol-infused products outpace national issuance rates, enabling manufacturer-to-consumer channel experimentation. San Diego craft distilleries anchor controlled-atmosphere freezing technology adoption for premium ABV formulations.
Florida
Miami-Dade and Orange County tourism employment drives poolside consumption occasion expertise unmatched domestically. Florida's division of alcoholic beverages and tobacco maintains streamlined seasonal permitting for resort hospitality formats. Tampa Bay warehouse club procurement volume determines national pouch-format sell-through benchmarks.
New York
New York City metropolitan bartending talent supplies cocktail-forward formulation R&D capabilities. State Liquor Authority direct-shipping liberalization for frozen alcohol products enables DTC channel pilot programs. Long Island frozen confection manufacturing infrastructure supports co-packing relationships for emerging brands.
Texas
Dallas-Fort Worth and Austin mixology programs generate flavor profile innovation pipelines for mass-market adaptation. Texas Alcoholic Beverage Commission three-tier enforcement creates distribution network complexity that favors established wholesaler relationships. Hill Country distillery tourism circuits incubate consumer education for premium frozen formats.
Illinois
Chicago hospitality management talent supplies national account coordination for food service channel expansion. Illinois Liquor Control Commission formula label approval processing times lag coastal jurisdictions, delaying market entry for seasonal innovations. Great Lakes distribution hub infrastructure enables Midwest cold chain logistics optimization.
US Frozen Cocktail Popsicles Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation, packaging, and channel access dimensions. The vendor base separates between spirits-heritage manufacturers with captive ethanol supply and contract-reliant brands dependent on third-party base procurement. Three archetypes dominate: distilled spirits legacy players leveraging proprietary base formulations, portion-control specialists optimizing club retail velocity, and organic-certified entrants capturing clean-label margin tiers. Capacity expansion through controlled-atmosphere freezing equipment leasing and strategic partnerships with regional cold chain logistics providers constitute the primary competitive moves.
Within the spirits-heritage archetype, Cutwater Spirits anchors premium positioning through proprietary base formulation control. Slim Chillers exemplifies portion-controlled format optimization for repeat purchase frequency in club retail channels. Among contract-manufacturing reliant entrants, FrutaPop and LIC Frozen Cocktails occupy positions dependent on third-party ethanol sourcing and co-packing relationships.
| Leading Market Players |
|---|
| Shooter Pops, LLC - Claffey's Cocktails |
| Cooloo |
| American Beverage Corporation - Daily's Cocktails |
| Cutwater Spirits |
| Slim Chillers |
| FrutaPop |
| LIC Frozen Cocktails |
| SnöBar |
| Fishers Island Lemonade |
| Others |
Pricing and Supply Chain Analysis
Controlled-atmosphere freezing technology adoption is compressing production cost curves for premium ABV formulations while simultaneously concentrating equipment supply among California and New York facility operators. This capital-intensity shift is reshaping margin structures across organic and conventional tiers as manufacturers face divergent paths for cost recovery.
Pricing Analysis
Unbundled equipment leasing separates from bundled formulation-plus-freezing service contracts as the dominant pricing split. Three-tier pricing structure across premium craft, mid-tier club retail, and economy private-label levels stratifies by ABV certification and organic USDA status. Pricing pressure stems from club retail buyers demanding 90-day sell-through guarantees that compress supplier margins. Food service buyers show lowest price sensitivity due to occasion-based premium positioning, while mass-market pouch formats face highest consumer price elasticity.
Supply Chain Analysis
USDA organic certification and TTB formula approval gates fragment supplier qualification timelines, extending procurement cycles for emerging brands. Ethanol sourcing draws from Midwest grain production, with stabilizer and flavoring agent imports resting on China and India chemical manufacturing. Single-source vulnerability concentrates in controlled-atmosphere freezing equipment where European and Japanese suppliers dominate. Distribution runs through refrigerated third-party logistics networks anchored in Florida, California, and Texas cold chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where consumer willingness-to-pay is migrating toward certified-organic and higher-ABV premium specifications rather than commodity convenience formats.
For Market Incumbents: Extend proprietary base formulation control into organic certification tiers to capture margin expansion from clean-label demand migration. Acquire controlled-atmosphere freezing capacity in California or Florida to reduce equipment lease dependency and defend against contract-manufacturing entrants. TTB classification ambiguity poses regulatory threat requiring diversified state-level legal counsel investment. For New Entrants and Emerging Players: Poolside hospitality buyers in Florida and California represent the most penetrable white-space target, with underdeveloped frozen cocktail popsicle programs at beachfront resorts and rooftop venues. Food service channel entry through seasonal permitting relationships offers lower regulatory friction than national retail distribution. Direct-to-consumer shipping pilot programs in New York provide go-to-market angle with fastest feedback loops for flavor optimization. For Investors and Strategic Acquirers: Valuations sit cheapest among contract-manufacturing reliant brands lacking captive ethanol supply or controlled-atmosphere freezing infrastructure. Long-term viability favors spirits-heritage players with backward integration into base formulation and multi-state ABC board relationship networks. Watch TTB federal classification resolution as inflection signal for direct-to-consumer channel expansion feasibility and interstate commerce normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA organic status captures fastest-growing margin tier as clean-label expectations migrate from food to beverage alcohol. |
| Controlled-Atmosphere Freezing Capacity Addition | Precision temperature management enables 10-15% ABV formulations without texture degradation for premium positioning. |
| Direct-to-Consumer Channel Launch | California, Florida, and New York direct-shipping liberalization enables manufacturer bypass of traditional three-tier distribution. |
| Food Service Partnership Development | Poolside and beachfront hospitality formats in Florida demonstrate underpenetrated volume potential for frozen cocktail programs. |
| State-Level Regulatory Diversification | Multi-jurisdiction ABC board relationships reduce TTB classification ambiguity risk and accelerate seasonal flavor approval timelines. |
Research Methodology
Bottom-up hospitality venue and retail channel modeling reconciled against top-down ethanol supply and freezing equipment production tracking forms the analytical core. Primary interviews with frozen beverage program directors, club retail category buyers, craft distillery operations managers, and cold chain logistics providers combined with secondary validation from FDA labeling guidance documents, TTB formula approval databases, state ABC board regulatory filings, and customs records for stabilizer and flavoring agent imports.
Historical trendline analysis of ABV formulation adoption rates and organic certification penetration established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type tier, flavor profile category, packaging format, and distribution channel, with regional regulatory cluster as industry-specific overlay. CAGRs were derived from regression analysis against adult social gathering occasion frequency and direct-to-consumer shipping regulatory liberalization indices.
Underlying measurement precision varies by segment; alcoholic and organic tiers carry tighter precision than non-alcoholic and gluten-free categories due to more established reporting infrastructure. Forecasts reflect assumptions regarding TTB classification resolution timing and state-level shipping regulation trajectories. A model refresh is warranted upon material change in federal frozen alcohol product tax treatment determination.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Wine Glass Market