
 Wine Glass Market | 2026-2036
Wine Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Glass Market Insights
Specialty retail and direct-to-consumer channels is narrowing as e-commerce platforms capture growing share of premium wine glass transactions. Riedel leverages its generational design heritage to command pricing power in sommelier-driven segments. Zwiesel Glas competes through patented Tritan crystal technology that resists chipping in commercial dishwashers. Anhui Deli Daily Glass anchors volume production for private-label and mass-market distribution across Asia.
A wine glass is a stemmed or stemless drinking vessel engineered with specific bowl curvature, rim diameter, and wall thickness to direct wine toward targeted palate zones and concentrate aromatic compounds. Lead-free crystal variants achieve refractive clarity through zinc oxide or barium oxide substitution while maintaining thin-walled drawability for mouthfeel optimization. Red wine glass configurations dominate value pools due to oversized bowl engineering for aeration, though champagne flute demand is accelerating in event-catering procurement. Crystal material commands margin concentration despite higher breakage rates, while silicone segments occupy niche outdoor and travel applications.
REACH compliance in Europe mandates substitution of lead and cadmium in crystal formulations, redirecting R&D spend toward barium-based alternatives. FDA food-contact regulations in the United States govern leachate testing for decorative surface coatings on imported glassware. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that could impose end-of-life recovery obligations on packaging-adjacent tableware categories.
Market Dynamics
The Wine Glass Market is experiencing structural pressure from REACH-mandated lead elimination, which is forcing crystal manufacturers to reformulate around barium oxide and zinc oxide substitutes while maintaining thin-wall drawability for sommelier-grade stemware.
Growth Catalysts
- EU REACH chemical substitution mandates:Regulatory pressure on lead and cadmium in crystal formulations is accelerating R&D investment into refractive alternatives, creating first-mover advantage for compliant producers.
- Premium hospitality procurement expansion:North American and European fine-dining venues are expanding stemware budgets to differentiate guest experiences through tactile and aromatic optimization.
- Event-catering flute acceleration:Champagne flute demand is concentrating in commercial procurement channels for weddings and corporate hospitality, outpacing traditional red wine bowl growth in volume terms.
Market Restraints
- Barium oxide supply concentration:Alternative crystal formulations depend on concentrated mining geographies for barium and zinc inputs, exposing producers to raw material volatility.
- Extended producer responsibility frameworks:California and New York are advancing end-of-life recovery obligations on tableware adjacent to packaging categories, creating compliance cost uncertainty.
- Silicone substitution in outdoor applications:Unbreakable silicone vessels are capturing camping and travel use cases where breakage risk outweighs sensory performance.
Strategic Opportunities
- German precision glassmaking cluster leverage:Riedel and Zwiesel Glas anchor expertise concentration that can be licensed or partnered for technology transfer to emerging production bases.
- Direct-to-consumer channel capture:E-commerce platforms are narrowing specialty retail share, creating white space for brand-controlled subscription and customization models.
- PLI scheme alignment in India:India's production-linked incentive framework for manufacturing offers tariff and tax advantages for glassware capacity localization serving Asian hospitality growth.
Industry Challenges
- Generational craft skill attrition:Mouth-blown crystal production depends on specialized artisan labor pools in Bavaria and Bohemia that are shrinking without structured apprenticeship pipelines.
- Multi-jurisdiction certification timelines:FDA food-contact leachate testing for decorative coatings operates on incompatible protocols with EU EFSA evaluations, delaying product launches.
- Commercial dishwasher compatibility engineering:Tritan and similar chip-resistant formulations require capital-intensive furnace modifications that strain mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Glass Market |
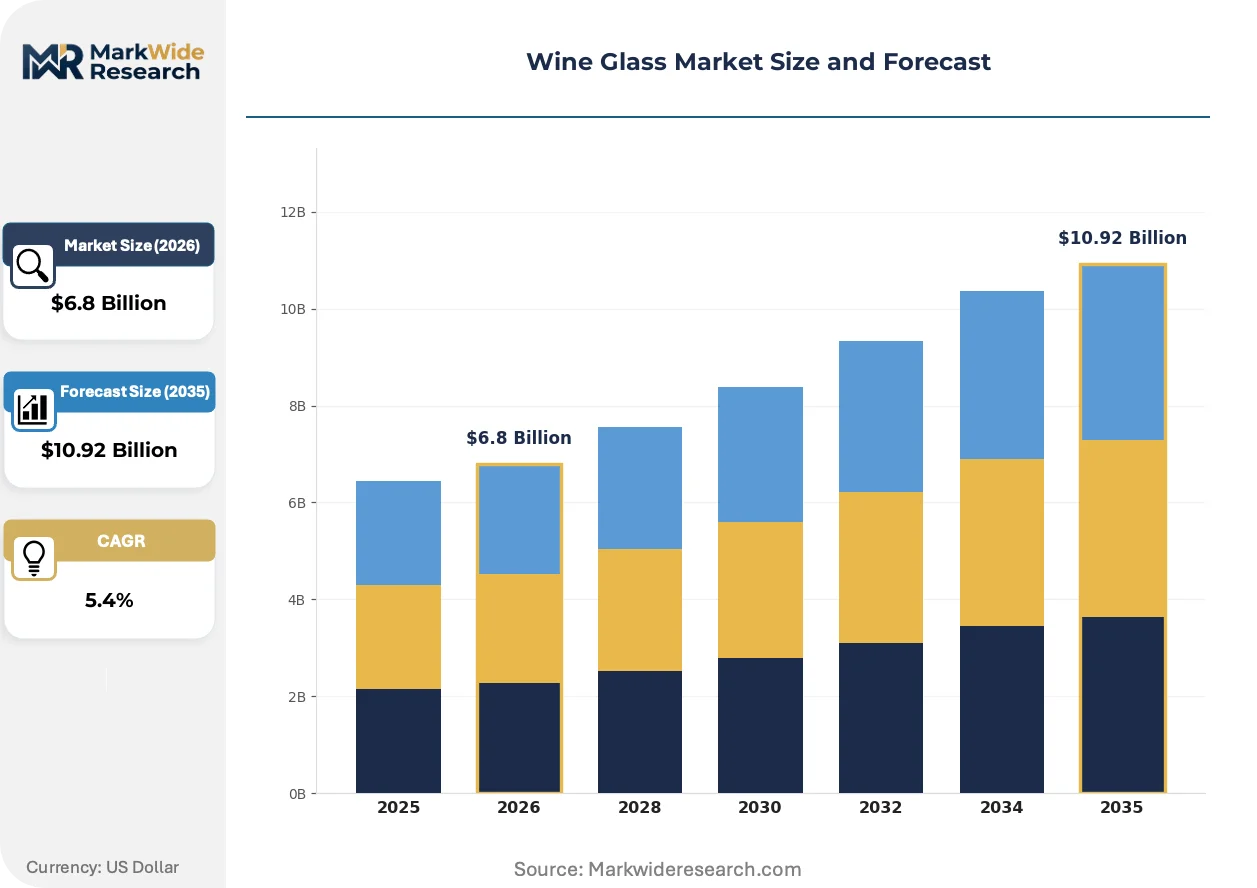
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Red Wine Glass, White Wine Glass, Champagne Flute, Dessert Wine Glass Material: Crystal, Glass, Plastic, Silicone Design: Classic, Modern, Vintage, Custom Size: Small, Medium, Large, Extra Large |
| Companies Covered | Zalto, Bormioli Rocco, Libbey, Anhui Deli Daily Glass, Arc Holdings, Riedel, Gabriel-Glas, Steelite International, Zwiesel Glas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Glass Market Trends and Innovations
Material science advances and regulatory chemistry mandates are compressing traditional manufacturing methods while digital channels rewrite how stemware reaches end buyers.
Lead-free crystal technology is collapsing the performance gap between traditional leaded formulations and refractive alternatives. Barium oxide and zinc oxide substitution achieves comparable clarity and thin-wall drawability for sommelier-driven segments. Premium hospitality buyers in Germany and Austria are adopting these variants at accelerated pace as REACH compliance deadlines approach.
REACH chemical safety enforcement is eliminating lead and cadmium from EU-manufactured crystal entirely. ECHA monitoring of imported glassware is tightening border controls on non-compliant Asian production. Decorative coating suppliers are redirecting R&D spend toward titanium dioxide and rare earth alternatives that satisfy both EU and FDA migration limits.
Specialty retail intermediation is eroding as brand-direct e-commerce captures educated consumer segments. Riedel's generational design authority translates effectively to digital storytelling, displacing sommelier-dependent wholesale channels. This channel compression is most visible in North American urban markets where subscription-based stemware curation is replacing registry-driven department store purchasing.
Wine Glass Market Segmentation
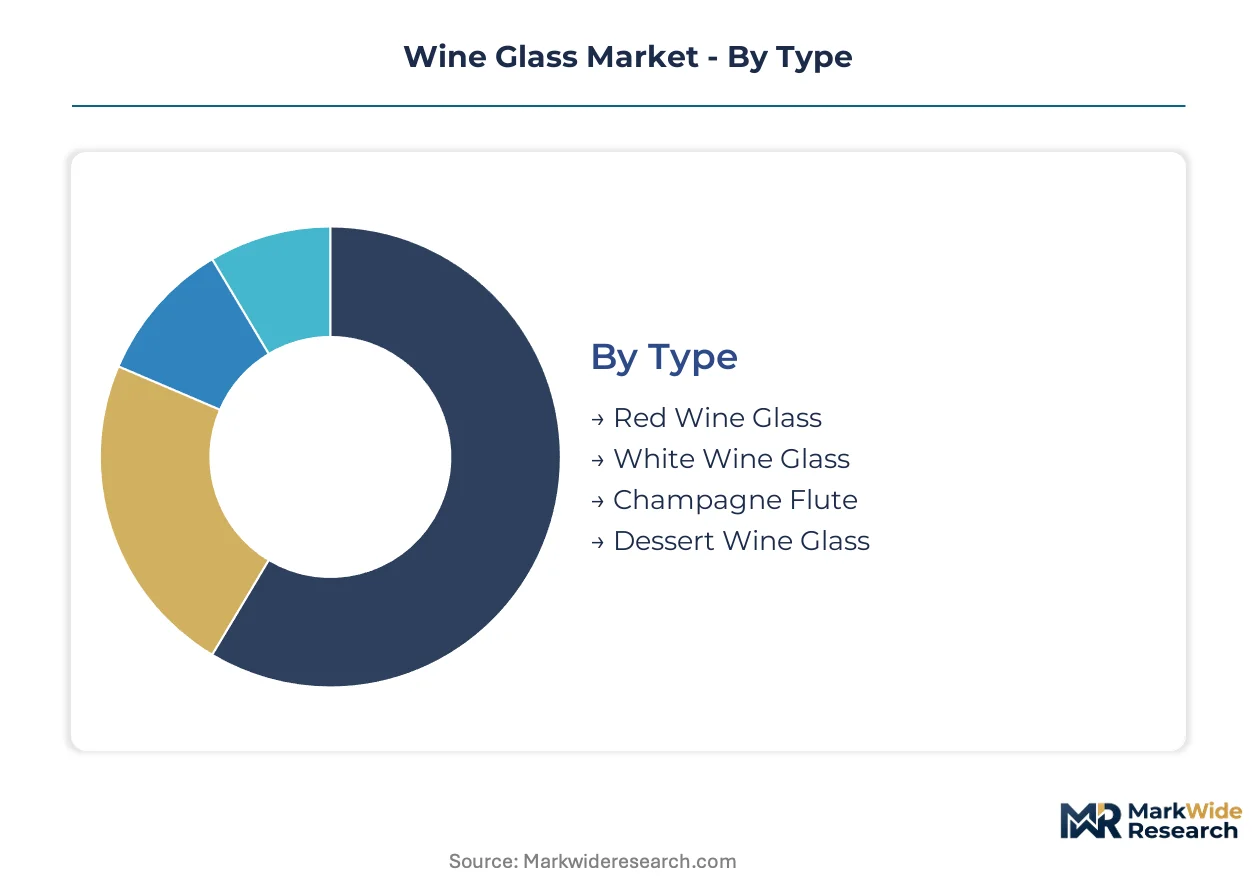
Wine glass segmentation reflects divergent technical requirements across hospitality procurement and consumer channels. Bowl geometry, material refractive index, and dimensional specifications determine price realization and replacement frequency in distinct use environments.
Type:
Application context drives bowl engineering priorities and procurement volume concentration.
- Red Wine Glass:Oversized bowl configurations with 600-900ml capacity maximize aeration surface area for tannin softening. Fine-dining venues in Germany and Austria prioritize thin-walled lead-free crystal variants for tactile differentiation.
- Champagne Flute:Narrow cylindrical geometry preserves effervescence through reduced surface-area-to-volume ratios. Event-catering procurement in France and Italy is expanding flute inventories for wedding and corporate hospitality contracts.
- White Wine Glass:Smaller bowl volumes maintain cooler serving temperatures through reduced thermal mass. Riedel's varietal-specific designs dominate sommelier-driven segments.
- Dessert Wine Glass:Compact 200-300ml capacity concentrates aromatic intensity for fortified wines. Zwiesel Glas produces dishwasher-safe Tritan variants for commercial dessert service.
Red Wine Glass holds installed capacity. Champagne Flute is rotating up the share rankings.
Material:
Cost tier and performance specifications stratify manufacturing inputs and margin structures.
- Crystal:Barium oxide and zinc oxide substitution achieves lead-free refractive clarity while maintaining thin-wall drawability. REACH compliance mandates in Europe are accelerating adoption of compliant formulations across premium hospitality procurement.
- Glass:Soda-lime composition dominates volume production for private-label retail and casual dining segments. Anhui Deli Daily Glass anchors mass-market supply across Asian distribution channels.
- Silicone:Unbreakable elastomer construction captures outdoor and travel applications where breakage risk outweighs sensory performance. Camping and poolside venues in Australia favor collapsible variants.
- Plastic:Polycarbonate and Tritan copolyester serve disposable and high-frequency replacement environments. Music festivals and stadium concessions in the United States specify single-use alternatives.
Crystal commands margin concentration. Silicone is climbing the fastest in niche outdoor procurement.
Design:
Customer type and channel positioning determine aesthetic differentiation strategies.
- Classic:Stemmed profiles with rounded bowls reference 18th-century Venetian and Bohemian traditions. Heritage hospitality venues in Vienna and Prague specify mouth-blown variants.
- Modern:Angular geometries and stemless configurations target urban residential markets. Direct-to-consumer e-commerce channels in the United States favor minimalist Scandinavian-influenced lines.
- Vintage:Reproduction patterns and colored stems serve registry-driven gifting occasions. Estate sale and auction sourcing in the United Kingdom supports secondary market valuation.
- Custom:Etched monograms and corporate logos anchor event-catering and hospitality branding. Wedding planners in California commission personalized flute sets for table settings.
Classic maintains production heritage concentration. Modern is gaining share fastest through digital channel capture.
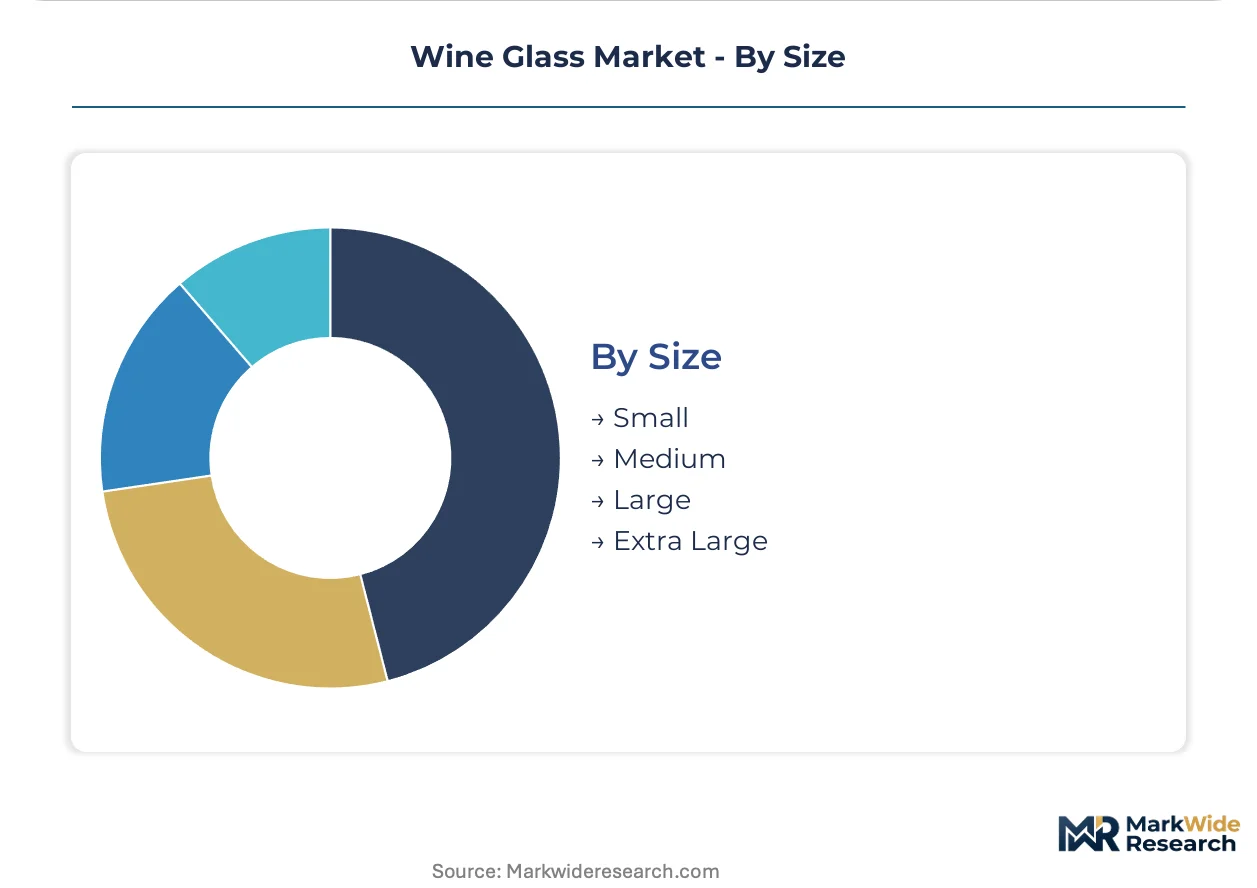
Size:
Volume specifications correlate with serving protocols and replacement economics across end-use segments.
- Large:700ml+ capacity supports full-bottle service formats in steakhouse and wine bar concepts. Texas and California hospitality operators specify oversized bowls for red wine presentations.
- Medium:400-600ml range balances aeration performance with storage efficiency. Standard inventory for multi-concept restaurant groups in Illinois and Florida.
- Small:200-400ml formats suit tasting flights and portion-controlled service. Wine education programs in New York and Napa Valley specify smaller volumes for comparative evaluation.
- Extra Large:1000ml+ novelty formats serve ceremonial and display functions. Limited production in Bavaria for export to Middle Eastern hospitality developments.
Medium holds baseline procurement volume. Large is expanding most quickly in premium casual dining formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for manufacturing is attracting glassware capacity localization to serve Asian hospitality expansion. Procurement patterns concentrate in Germany, the United States, and China where premium dining and event-catering channels drive differentiated demand.
Germany
Fine-dining venues in Bavaria and Baden-Württemberg prioritize thin-walled lead-free crystal for tactile differentiation. ECHA enforces REACH compliance deadlines that eliminate lead and cadmium from crystal formulations entirely. The Zwiesel and Riedel production clusters in Bavaria anchor precision glassmaking expertise that supplies sommelier-grade stemware globally.
United States
Texas and California hospitality operators specify oversized red wine bowls for premium casual dining presentations. FDA food-contact regulations govern leachate testing for decorative surface coatings on imported glassware. New York and Napa Valley wine education programs drive procurement of smaller-format tasting glasses for comparative evaluation.
China
Private-label retail and mass-market distribution channels concentrate volume demand for soda-lime glass production. GB standards and MIIT oversight shape domestic manufacturing compliance for food-contact materials. Anhui province anchors high-volume fabrication capacity serving Asian distribution networks and export markets.
France
Event-catering procurement in Île-de-France and Provence-Alpes-Côte d'Azur accelerates champagne flute inventories for wedding and corporate contracts. ANSM monitors chemical migration limits for decorative coatings under EU framework alignment. Paris-based hospitality groups influence stemware design trends across European fine-dining channels.
India
Maharashtra and Karnataka hospitality developments are expanding stemware procurement as premium dining formats proliferate in Mumbai and Bangalore. The PLI scheme offers tariff and tax advantages for glassware capacity localization serving domestic and export demand. Tamil Nadu fabrication clusters are positioning for technology transfer partnerships with European precision glassmakers.
Wine Glass Market Competitive Landscape
On the supply side, the industry is bifurcated between precision crystal specialists and high-volume soda-lime fabricators. Tiered competitive positioning separates generational design houses from private-label contract manufacturers. Three archetypes dominate: heritage mouth-blown crystal ateliers, patented technology licensors, and scale-driven mass-market suppliers. Strategic moves concentrate on technology licensing agreements and direct-to-consumer channel capture.
Within the heritage crystal tier, Riedel and Zwiesel Glas exemplify generational design authority and patented refractive technology respectively. Anhui Deli Daily Glass occupies the scale-driven position serving private-label and mass-market channels across Asia. These three anchors illustrate the competitive spectrum from sommelier-grade precision to volume fabrication efficiency.
| Leading Market Players |
|---|
| Zalto |
| Bormioli Rocco |
| Libbey |
| Anhui Deli Daily Glass |
| Arc Holdings |
| Riedel |
| Gabriel-Glas |
| Steeelite International |
| Zwiesel Glas |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Bavarian mouth-blown crystal ateliers is compressing lead times for sommelier-grade stemware while elevating pricing power for heritage producers serving fine-dining procurement channels. This utilization squeeze propagates through contract structures, forcing hospitality buyers toward longer-term commitments or alternative formulations.
Pricing Analysis
Volume-discount tiering separates heritage mouth-blown ateliers from machine-drawn precision manufacturers from mass-market soda-lime fabricators. Price differentiation rests on certification grade—REACH-compliant barium crystal commands premium positioning against legacy lead formulations—and brand heritage anchored in generational design authority. Cost compression in machine-drawn tiers intensifies as Anhui Deli Daily Glass scales furnace throughput for private-label retail. Event-catering procurement exhibits highest price sensitivity due to replacement frequency, while trophy hospitality venues in Vienna and Paris show lowest sensitivity to per-unit cost.
Supply Chain Analysis
Extended payment terms from European hospitality groups are straining mid-cap furnace operators who lack supply-chain finance facilities. Manufacturing concentrates in Germany, China, and the Czech Republic, with raw material sourcing drawing from concentrated barium mining geographies in Kazakhstan and China plus zinc oxide from Peru and Australia. Single-source vulnerability in barium oxide supply exposes reformulating crystal producers to input volatility. Distribution runs through direct-to-consumer e-commerce platforms that displace wholesale intermediation in North American urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine glass market functions as a defensive-moat story where regulatory entrenchment in REACH compliance creates asymmetric barriers—first-mover certification investment locks out late entrants from premium hospitality procurement.
For Market Incumbents: Pre-empt silicone substitution in outdoor applications by acquiring collapsible elastomer technology or licensing unbreakable formulations from materials specialists. Vertical integration into barium oxide sourcing hedges raw material volatility threatening margin stability in lead-free crystal tiers. Channel control through subscription-based stemware curation displaces registry-driven department store purchasing before emerging DTC brands capture urban residential segments.
For New Entrants and Emerging Players: Maharashtra and Karnataka hospitality developments in India represent the most penetrable geography, where premium dining format proliferation outpaces localized precision glassmaking capacity. Target technology transfer partnerships with Bavarian ateliers to leapfrog furnace engineering barriers. A go-to-market angle anchored in PLI scheme alignment offers tariff advantages against imported European stemware serving domestic Indian hospitality procurement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Tritan crystal furnace modifications required for commercial dishwasher compatibility. Long-term viability favors patented technology licensors with defensible formulation IP over volume fabricators exposed to soda-lime commodity pricing. The acquisition target archetype is mid-cap precision manufacturers with REACH-compliant barium oxide expertise and dormant capacity for hospitality channel expansion. The signal to watch is ECHA enforcement intensity on imported Asian crystal border controls.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Crystal Formulation Patent Licensing | REACH compliance deadlines in Germany accelerate royalty streams from barium oxide substitution technology. |
| Direct-to-Consumer Channel Buildout | Riedel's generational design authority translates to digital subscription models displacing wholesale intermediation. |
| PLI Scheme Manufacturing Localization | Tamil Nadu fabrication clusters capture tariff advantages serving Asian hospitality expansion from Mumbai and Bangalore. |
| Tritan Furnace Technology Upgrade | Zwiesel Glas patents chip-resistant formulations that reduce replacement frequency in commercial dishwasher environments. |
| Raw Material Backward Integration | Barium oxide supply concentration in Kazakhstan exposes producers to volatility absent captive mining or long-term offtake. |
Research Methodology
Initial hypotheses were tested against primary input from sommelier procurement directors, furnace operations managers at precision glassworks, hospitality supply chain executives, and regulatory compliance officers at crystal manufacturers, then refined through secondary validation. Sources included ECHA REACH enforcement bulletins, FDA food-contact leachate testing protocols, German glassmaking association technical standards, and customs trade data on barium oxide import flows. Bottom-up triangulation across individual SKU pricing in hospitality procurement databases converged with top-down market sizing from furnace capacity utilization reports.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions spanning bowl geometry type, material refractive index tier, design archetype, and regional hospitality development intensity. CAGRs derived from historical replacement frequency patterns in commercial foodservice channels, adjusted for regulatory phase-out timelines on leaded crystal formulations. Industry-specific forecast inputs incorporated PLI scheme uptake rates in Indian manufacturing zones and REACH compliance adoption curves across European production bases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed consolidation plays or state-subsidized Chinese capacity expansions would shift outcomes. Macroeconomic deviation in hospitality capital expenditure cycles, regulatory acceleration in extended producer responsibility frameworks, or breakthrough advances in unbreakable silicone clarity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Global Distillation System Market