
 Cocktail Market | 2026-2036
Cocktail Market Size, Share, and Industry Trends Forecast 2026-2036
Cocktail Market Analysis
Hotel and resort beverage programs is realigning cocktail procurement toward premium pre-mixed and craft formats that reduce labor cost while elevating perceived quality. Diageo plc leverages its extensive spirits portfolio to dominate hotel minibar and banquet channel supply. Bacardi Limited anchors Caribbean and Latin American resort markets through rum-based cocktail specialization. Beam Suntory competes in the Japanese whisky highball segment, a category that has expanded into international hospitality settings.
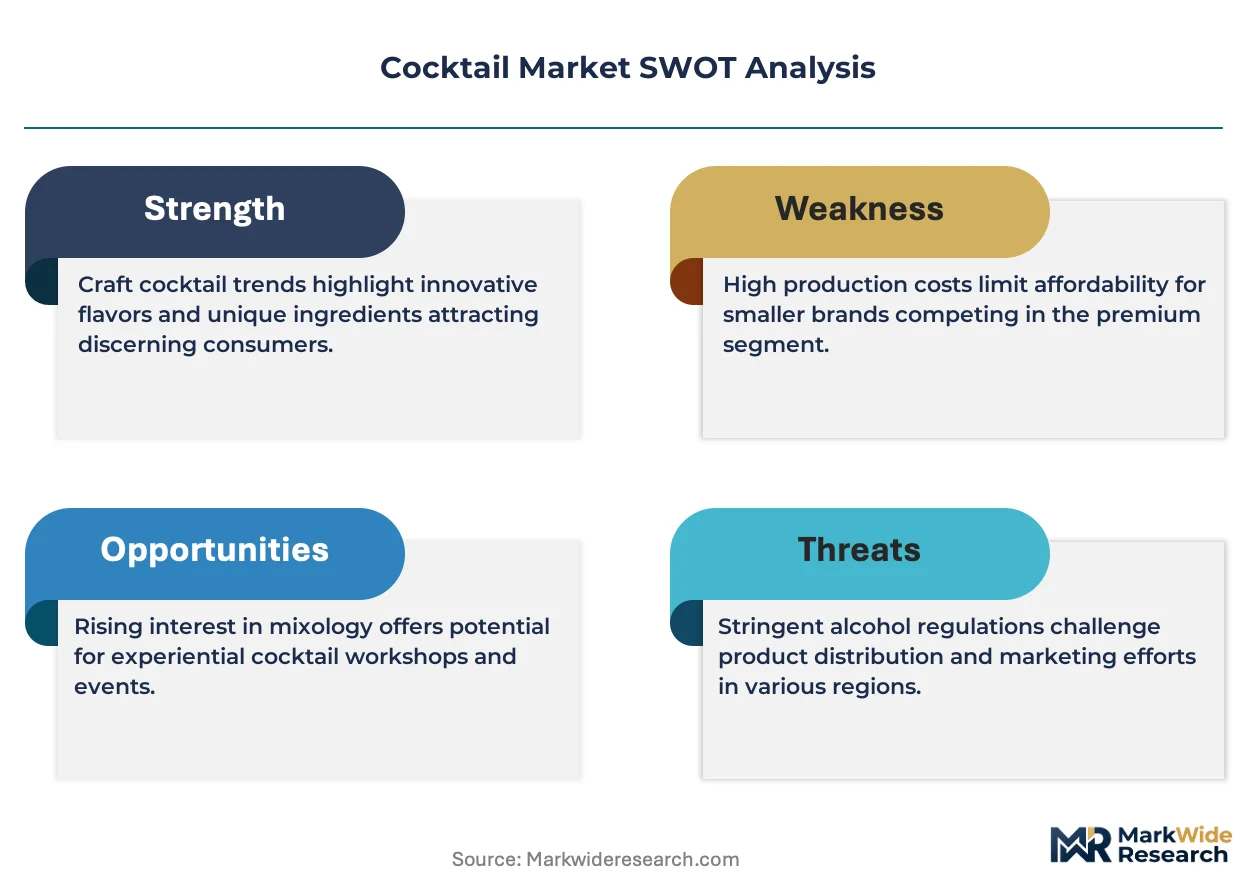
A cocktail comprises a mixed alcoholic beverage prepared by combining spirits with liqueurs, bitters, fruit purees, or other modifiers, typically served chilled and diluted through shaking or stirring to achieve balanced flavor and specified alcohol-by-volume parameters. Its primary commercial purpose centers on delivering consistent, scalable beverage experiences across on-premise hospitality and off-premise retail environments. RTD and pre-mixed formats now capture the fastest expansion as packaging innovation in cans and slim bottles enables portability and single-serve precision. Craft cocktails command premium margin pools in bars and events channels, while mixers and fruit purees sustain volume foundations through retail and online distribution.
FDA oversight of food additive safety and TTB labeling standards govern ingredient disclosure and alcohol content claims for cocktails sold in the United States, directly shaping product formulation and market access requirements. EMA and national regulators across Europe enforce varying thresholds for bitters and botanical additives, creating fragmented compliance obligations for cross-border RTD launches. Stakeholders must monitor evolving packaging sustainability mandates and alcohol taxation proposals that threaten to restructure cost competitiveness across distribution channels.
Market Dynamics
Post-pandemic experiential spending recovery is forcing hospitality venues to deepen cocktail menu complexity while compressing labor costs, creating structural tension between craft authenticity and operational scalability that RTD formats now resolve.
Growth Catalysts
- FDA and TTB Labeling Frameworks:Stringent ingredient disclosure mandates in the United States are accelerating premium RTD adoption as brands compete on transparency credentials. Compliance investments now function as competitive differentiation.
- Craft Cocktail Culture:American consumers demonstrate sustained willingness to pay premium prices for complex flavor profiles, pulling capital into specialized bitters and small-batch modifier production.
- Canning Technology:Advanced nitrogen-dosing and liner innovations are extending shelf stability for pre-mixed cocktails without artificial preservatives, unlocking retail distribution scale previously reserved for beer.
Market Restraints
- Glass and Aluminum Input Volatility:Packaging material cost swings compress margin predictability for RTD producers operating on fixed-price retail contracts.
- Spirits Supply Concentration:Premium whiskey and aged rum availability concentrates among established distillers in Scotland and Caribbean basin, constraining independent craft cocktail brand expansion.
- Substitution from Non-Alcoholic Alternatives:Sophisticated zero-proof spirits and functional beverages capture occasion-share from traditional cocktail consumption, particularly among health-conscious demographics.
Strategic Opportunities
- Indian Urban Markets:Rising disposable income in Mumbai and Bangalore creates underpenetrated demand for premium imported spirits and mixology education.
- Hotel Minibar Channel:Single-serve premium formats replace legacy miniature bottles, capturing higher per-unit economics through perceived quality elevation.
- EU Packaging Sustainability Mandates:CSRD-aligned circular packaging requirements favor early movers with aluminum-to-aluminum closed-loop systems and carbon-labeled supply chains.
Industry Challenges
- Certified Mixologist Talent Scarcity:Hospitality venues struggle to staff programs requiring advanced technique proficiency, forcing reliance on pre-mixed solutions that dilute brand differentiation.
- Multi-Jurisdiction Compliance Burden:EMA botanical thresholds, FDA additive approvals, and national alcohol taxation regimes create fragmented product registration timelines that delay cross-border launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocktail Market |
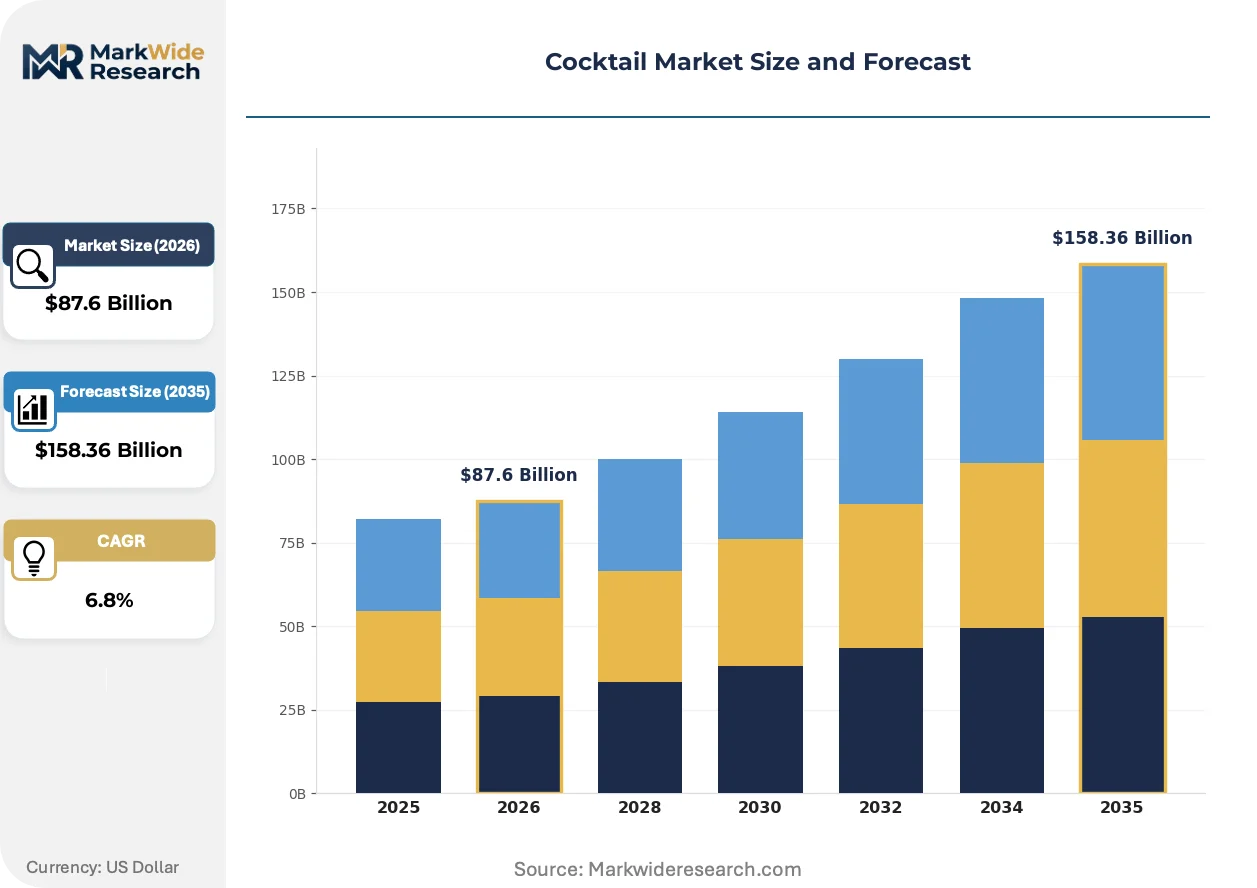
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Mixed, Craft, RTD, Mixers Ingredient Type: Spirits, Liqueurs, Bitters, Fruit Purees Packaging Type: Bottles, Cans, Tetra Paks, Kegs Distribution Channel: Retail, Bars, Online, Events |
| Companies Covered | Diageo plc, Bacardi Limited, Beam Suntory, Brown-Forman Corporation, Pernod Ricard, Campari Group, Constellation Brands, Anheuser-Busch InBev, Asahi Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocktail Market Emerging Trajectories
Three interconnected shifts are restructuring how cocktail value is created and captured: packaging technology enabling new distribution economics, regulatory transparency demands reshaping formulation priorities, and procurement behavior favoring consolidated supplier relationships over fragmented sourcing.
Nitrogen-charged canning systems are overtaking traditional bottling for premium RTD cocktails. The technology preserves volatile aromatic compounds through oxygen exclusion, extending shelf life without chemical stabilizers. Hotel chains and airline catering divisions are adopting these formats at accelerating pace, collapsing the historical quality gap between on-premise craft execution and pre-mixed convenience.
REACH chemical registration requirements in Europe are forcing reformulation of bitters and botanical modifiers containing legacy compounds. Producers must substitute approved alternatives or withdraw SKUs from EU distribution. American RTD brands exporting to Germany and France are establishing dedicated compliance teams, treating European regulatory alignment as a product development gate rather than post-formulation documentation.
Consolidated beverage procurement contracts are displacing fragmented supplier relationships in resort and casino operations. Procurement directors now favor single-source agreements covering spirits, mixers, and pre-mixed formats to simplify inventory management and volume rebate optimization. This concentration is most visible in Las Vegas and Macau integrated resort properties, where procurement centralization has reduced active vendor counts by half within three years.
Cocktail Market Segmentation
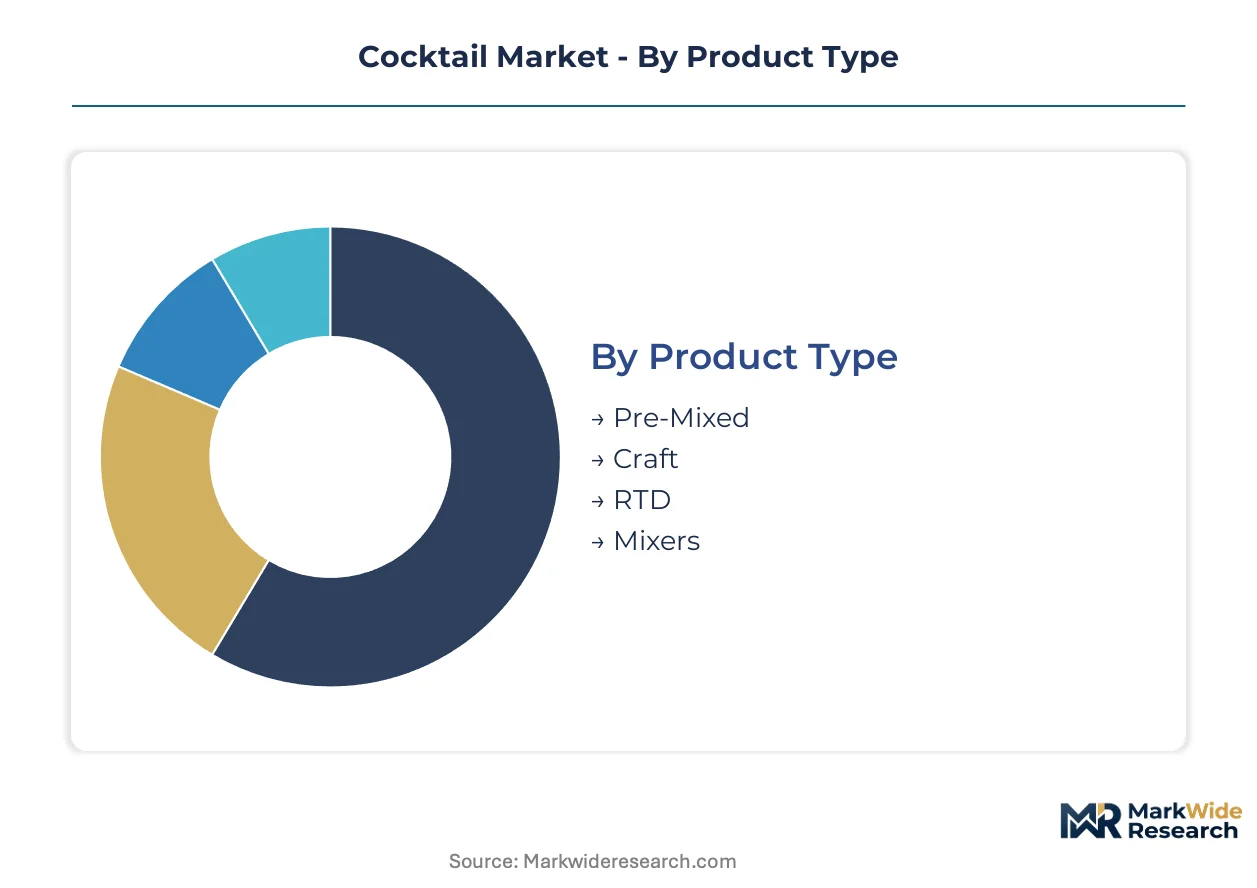
Cocktail market segmentation reveals how procurement priorities diverge across hospitality and retail channels. Understanding these fault lines exposes where margin pools concentrate and which formats command pricing power.
Product Type:
Premium hospitality buyers prioritize labor efficiency and consistency; retail consumers favor portability and occasion-appropriate formats.
- Pre-Mixed:Batch-prepared cocktails stabilized through pasteurization or nitrogen flushing, typically bottled in multi-serve formats for hotel banquet and airline catering operations. Demand concentrates in Las Vegas integrated resorts and Dubai luxury hotels where labor cost compression overrides craft authenticity concerns.
- RTD:Single-serve canned or bottled cocktails with precisely calibrated alcohol-by-volume, enabled by advanced liner technologies that prevent flavor degradation. American convenience retail and Japanese kombini chains are pulling volume as on-the-go consumption occasions expand.
- Craft:Hand-finished cocktails prepared to order in premium bars and restaurants, commanding price premiums through technique demonstration and ingredient provenance storytelling.
- Mixers:Non-alcoholic modifiers including tonics, sodas, and syrups that enable consumer customization in home bartending occasions.
Pre-Mixed leads volumes today; RTD is gaining share fastest.
Ingredient Type:
Formulation choices determine regulatory pathway complexity and supply security exposure across jurisdictions.
- Spirits:Whiskey, vodka, gin, and rum bases that define alcohol content and taxation classification. Scotch whisky and aged Caribbean rum availability concentrates among established distillers, constraining independent brand expansion.
- Liqueurs:Sweetened spirit infusions that add viscosity and flavor depth, requiring careful balance to avoid cloying profiles in finished cocktails.
- Bitters:Concentrated botanical extracts dosed in drops or dashes; EMA and FDA registration requirements are forcing reformulation of legacy compounds containing unapproved additives.
- Fruit Purees:Shelf-stable or fresh citrus and tropical fruit preparations that deliver acidity and aromatic complexity; cold-pressed and HPP-treated variants command premium positioning in craft programs.
Spirits anchor revenue concentration; fruit purees show steepest expansion trajectory in premium applications.
Packaging Type:
Material selection trades sustainability credentials against shelf stability requirements and channel-specific handling constraints.
- Cans:Aluminum containers with nitrogen-dosing systems that exclude oxygen and preserve volatile aromatics without chemical preservatives. Hotel chains and airline caterers are adopting at accelerating pace.
- Bottles:Glass or PET formats that communicate premium positioning through weight and transparency; higher shipping costs limit distribution radius for craft producers.
- Tetra Paks:Aseptic cartons offering lightweight shipping economics and extended ambient shelf life, penetrating institutional foodservice and travel retail channels.
- Kegs:Stainless steel returnable vessels for high-volume on-premise dispensing, minimizing packaging waste but requiring dedicated tap infrastructure and cleaning protocols.
Cans dominate new product launches; bottles retain margin leadership in gift and luxury channels.
Distribution Channel:
Channel selection determines margin structure, brand control, and consumer data access for cocktail producers.
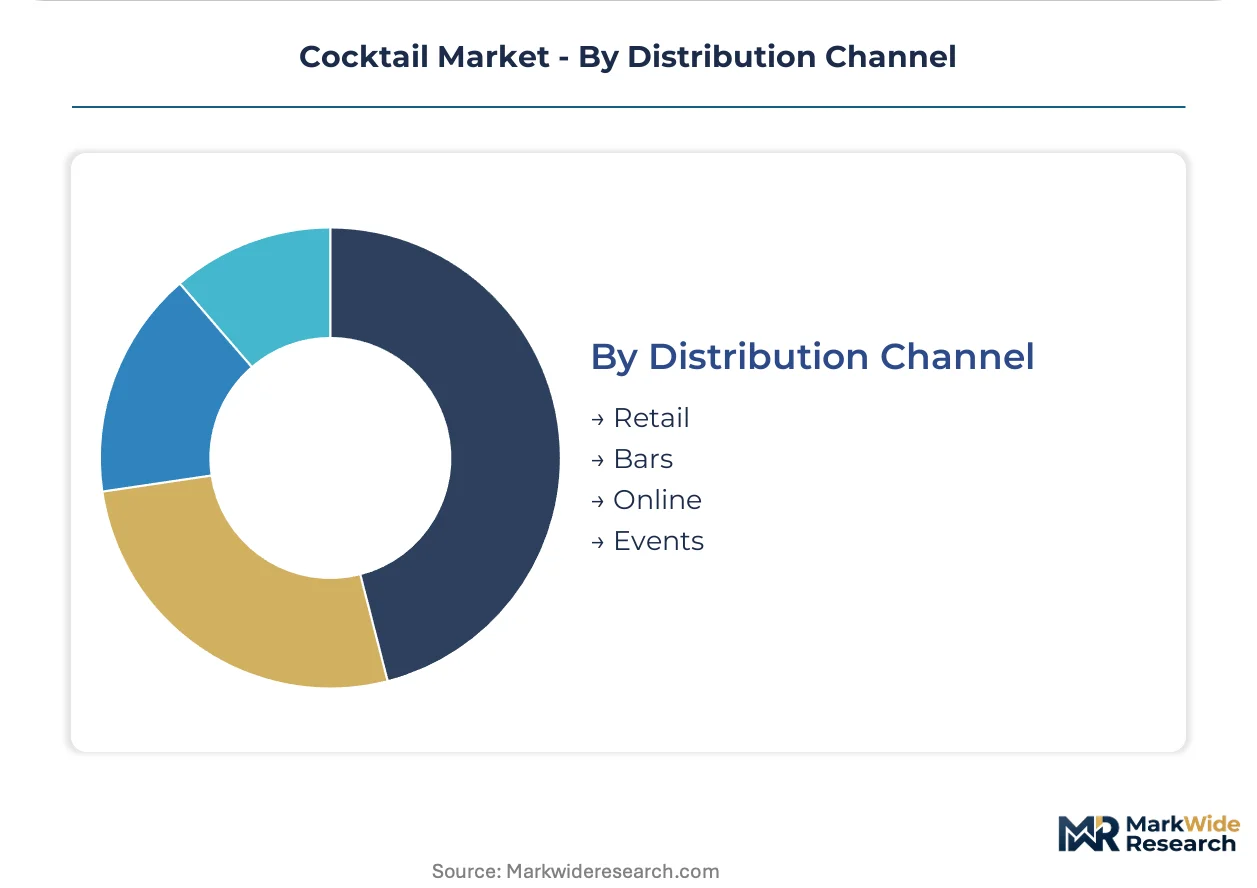
- Bars:On-premise venues where technique execution and atmosphere create experiential value; certified mixologist scarcity is forcing reliance on simplified programs or pre-mixed solutions.
- Retail:Supermarkets, liquor stores, and convenience outlets where packaging innovation and shelf placement drive discovery; TTB and state-level labeling compliance creates fragmented market access.
- Online:Direct-to-consumer and marketplace platforms that enable subscription models and limited releases; shipping restrictions on alcohol vary by state and country, complicating fulfillment.
- Events:Festivals, weddings, and corporate gatherings where batch efficiency and speed of service outweigh customization; consolidated procurement contracts are displacing fragmented supplier relationships.
Bars capture highest per-unit economics; online is expanding most quickly as logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cocktail production toward jurisdictions with streamlined compliance pathways. TTB labeling requirements in the United States impose steeper formulation costs than European frameworks, prompting some RTD brands to prioritize EU-first launches. Emerging markets with evolving alcohol taxation regimes are attracting contract manufacturing investment.
United States
Post-pandemic experiential spending recovery is deepening cocktail menu complexity at premium hospitality venues. FDA and TTB frameworks mandate stringent ingredient disclosure and alcohol content labeling, accelerating premium RTD adoption as brands compete on transparency credentials. Las Vegas integrated resorts are consolidating procurement contracts, reducing active vendor counts by half within three years.
Germany
REACH chemical registration requirements are forcing reformulation of bitters and botanical modifiers containing legacy compounds. EMA botanical thresholds create fragmented compliance obligations for cross-border RTD launches. Berlin and Munich hospitality clusters are adopting nitrogen-charged canning systems for hotel minibar and airline catering channels.
Japan
Whisky highball culture has expanded into international hospitality settings, pulling demand for precision-calibrated RTD formats. METI standards govern packaging sustainability and alcohol taxation structures. Tokyo and Osaka kombini chains are driving volume growth in single-serve canned cocktails with precisely calibrated alcohol-by-volume.
India
Rising disposable income in Mumbai and Bangalore is creating underpenetrated demand for premium imported spirits and mixology education. FSSAI regulations govern food additive safety and labeling standards for alcoholic beverages. Maharashtra and Karnataka urban clusters are attracting investment in specialized bitters and small-batch modifier production.
Brazil
Rum-based cocktail specialization anchors Caribbean and Latin American resort market supply relationships. ANVISA oversees pharmaceutical-grade botanical additive approvals for bitters and modifiers. São Paulo and Rio de Janeiro hospitality venues are compressing labor costs through pre-mixed format adoption while elevating perceived quality.
Cocktail Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with spirits conglomerates dominating hotel minibar and banquet channels while independent craft producers capture premium bar margins. The vendor base concentrates among established distillers with captive aged stock reserves. Three archetypes define competitive positioning: integrated spirits conglomerates with portfolio breadth, regional specialists with single-category depth, and contract manufacturers serving private-label retail programs. M&A activity targets bitters and modifier brands with established distribution, while capacity expansion focuses on nitrogen-dosing canning lines.
Within the integrated conglomerate tier, Diageo plc and Bacardi Limited exemplify scale-driven positioning across hospitality procurement channels. Beam Suntory occupies a specialist position in Japanese whisky highball segmentation that has expanded internationally. These three entities represent divergent geographic anchoring strategies: London-based portfolio breadth, Bermuda-rooted rum specialization, and Osaka-Tokyo whisky precision.
| Leading Market Players |
|---|
| Diageo plc |
| Bacardi Limited |
| Beam Suntory |
| Brown-Forman Corporation |
| Pernod Ricard |
| Campari Group |
| Constellation Brands |
| Anheuser-Busch InBev |
| Asahi Group Holdings |
| Others |
Supply Flow & Price Mechanics
Nitrogen-dosing canning technology is collapsing the historical cost gap between premium craft execution and mass-produced RTD formats, simultaneously redistributing margin pools toward producers with captive aluminum supply agreements and certified liner manufacturing partnerships.
Pricing Analysis
Distributor margin compression in the United States runs through fixed-price retail contracts that expose RTD producers to aluminum and glass input volatility. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-flushed craft cans from conventional bottled formats and value-oriented tetra-pak institutional offerings. Cost compression in the premium tier is intensifying because spirits supply concentration among Scottish and Caribbean distillers constrains independent brand expansion. Hotel and casino procurement directors demonstrate lowest price sensitivity through consolidated single-source agreements, while convenience retail channels exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Direct-to-hospitality channels handle integrated resort and airline catering demand through consolidated procurement contracts that halved active vendor counts in Las Vegas within three years. Geographic supply concentration centers on Scotland for aged whisky, the Caribbean basin for premium rum, and Japan for precision-distilled spirits used in highball formats. Raw material dependencies include aluminum sheet for canning, nitrogen gas for inerting systems, and cold-pressed fruit purees for modifier production. Single-source vulnerability in Caribbean rum aging stock creates supply chain risk for brands without captive distillery relationships. Distribution runs through three-tier alcohol regulation in the United States and direct-import arrangements in Dubai and Macau.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between TTB-intensive United States formulation requirements and streamlined EU compliance pathways positions contract manufacturing in Germany and the Netherlands as a cost-optimized production base for brands seeking dual-market access.
For Market Incumbents: Deepen captive supply relationships with Caribbean rum distillers and Scottish whisky houses to defend against spirits availability constraints threatening RTD portfolio expansion. Prioritize backward integration into nitrogen-dosing canning capacity to capture margin compression from aluminum input volatility. Channel control through exclusive hotel minibar partnerships represents the priority defensive lever against consolidated procurement centralization. For New Entrants and Emerging Players: Launch via direct-to-consumer online platforms with subscription-based mixology education bundles to bypass fragmented three-tier distribution barriers in the United States. White-space targets include Indian urban markets in Mumbai and Bangalore where premium imported spirits demand outpaces supply infrastructure. The most penetrable segment comprises specialized bitters and botanical modifiers facing EMA-forced reformulation of legacy compounds. For Investors and Strategic Acquirers: Valuations sit cheapest among independent craft cocktail brands with established distribution but limited aged spirits inventory. Long-term viability across the projection horizon hinges on regulatory compliance capabilities as REACH and TTB frameworks tighten additive approval pathways. Acquisition target archetype: regional bitters producers with EMA-aligned formulation portfolios and existing hotel channel relationships. The signal to watch is aluminum-to-aluminum closed-loop packaging certification as EU CSRD mandates reshape cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Canning Capacity | Captures margin from nitrogen-dosing technology adoption in hotel and airline channels. |
| EMA-Aligned Bitters Reformulation | Preserves EU market access as REACH chemical registration requirements tighten botanical additive approvals. |
| Hotel Minibar Channel Consolidation | Replaces legacy miniature bottles with single-serve premium formats in Las Vegas and Dubai properties. |
| Indian Urban Market Entry | Addresses underpenetrated demand for mixology education and premium imported spirits in Mumbai and Bangalore. |
| Aluminum Closed-Loop Certification | Aligns with EU CSRD packaging sustainability mandates favoring carbon-labeled supply chains. |
Methodological Framework
Multiple input streams — structured interviews with beverage program directors at integrated resorts, procurement leads at airline catering divisions, regulatory affairs specialists at RTD manufacturers, and distribution channel partners — were reconciled against secondary validation from TTB label approval databases, FDA food additive petitions, EMA botanical registration filings, and customs trade records. Bottom-up volume estimates from individual product registrations and top-down market sizing from spirits industry association data were triangulated to produce convergent estimates.
Data-stream reconciliation across the projection horizon employed segmentation modeling by product format, packaging material, distribution channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of nitrogen-dosing adoption rates, aluminum pricing cycles, and hospitality procurement consolidation patterns. Industry-specific forecast inputs included hotel minibar format conversion timelines and kombini chain expansion trajectories in Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alcohol taxation regime shifts or sustained aluminum price spikes. Periodic stress-testing of base assumptions is recommended given substitution risk from zero-proof spirits and evolving FDA additive approval pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
France Tequila Market