
 Chocolate Beer Market | 2026-2036
Chocolate Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Beer Market Intelligence
The replacement of artificial chocolate flavorings with artisanal cacao nibs and single-origin cocoa is restructuring product economics for premium chocolate beers. Anheuser-Busch InBev leverages its vast distribution channels to push its chocolate-flavored offerings into mainstream retail. In contrast, Dogfish Head Craft Brewery differentiates through its focus on unique, often high-gravity, experimental brews. New Belgium Brewing Company sustains a strong presence in the craft segment with its well-established seasonal releases.
Chocolate beer is a category of beer characterized by prominent chocolate or cocoa flavors, achieved either through specific dark roasted malts or the direct addition of cacao products. The process often involves infusing cacao nibs or powder during the fermentation or conditioning phase to impart authentic flavor. Stout and Porter product types form the backbone of the market, as their roasted malt base naturally complements chocolate notes. Offerings emphasizing Dark Chocolate and Cocoa Nib flavor profiles command higher price points compared to sweeter milk chocolate-infused alternatives.
Brewers must navigate a complex web of food and beverage regulations, including the FDA's allergen labeling requirements in the United States and the EU's food additive rules overseen by EFSA. These standards dictate permissible ingredients and marketing claims, directly impacting formulation and cross-border trade. The central challenge for brewers will be to balance the use of premium, ethically sourced cocoa with the need for scalable production and accessible consumer pricing.
Market Dynamics
The central dynamic shaping the chocolate beer market is the bifurcation between mass-market scale and artisanal authenticity. Large brewers leverage distribution to push accessible, flavored beers, while craft producers build value through premium, single-origin cacao and complex brewing techniques.
Growth Catalysts
- Artisanal Brewing Techniques:Innovations in cold-brewing and extended aging with cacao nibs are creating more complex and stable flavor profiles, attracting craft beer connoisseurs seeking novel sensory experiences.
- Specialty Retail Channel Expansion:The growth of dedicated craft beer stores and taprooms provides a crucial sales channel for premium and experimental chocolate beers, bypassing the competitive shelf space of large grocery chains.
- United States Craft Beer Ecosystem:A mature craft brewing culture and an adventurous consumer base in the United States create a highly receptive environment for niche products like high-gravity or barrel-aged chocolate stouts.
Market Restraints
- Input Cost Volatility:Dependence on artisanal cacao and single-origin cocoa, which are subject to climate-related supply shocks and price fluctuations, creates significant cost pressure for brewers focused on premium offerings.
- Complex Regulatory Compliance:Brewers must adhere to stringent food additive rules, such as those governed by the EFSA in Europe, and allergen labeling requirements from the FDA, which adds complexity and cost to production.
- Flavor Profile Competition:Chocolate beers compete for consumer attention not only with traditional stouts and porters but also with a growing array of other flavored craft beers, including coffee, fruit, and spice-infused varieties.
Strategic Opportunities
- Non-Alcoholic and Low-Alcohol Variants:Developing sophisticated non-alcoholic chocolate beers presents a significant opportunity to capture demand from health-conscious consumers and expand into new consumption occasions.
- Geographic Expansion into Europe:Targeting markets with established beer traditions but nascent craft chocolate beer scenes, such as the United Kingdom and Germany, offers substantial growth potential.
- Direct-to-Consumer (DTC) Models:Leveraging e-commerce platforms and subscription box services allows niche brewers to build direct relationships with consumers and bypass traditional three-tier distribution hurdles.
Industry Challenges
- Supply Chain Consistency:Securing a consistent, scalable supply of high-quality, ethically sourced single-origin cacao nibs poses a significant logistical challenge for brewers aiming to grow production without compromising on quality.
- Flavor Stability and Shelf Life:Maintaining the integrity of authentic chocolate flavors over time, especially in non-pasteurized craft beers, is a technical hurdle that requires specialized brewing expertise and quality control.
- Consumer Education on Authenticity:Differentiating products made with real cacao from those using artificial flavorings requires significant marketing investment to educate consumers on ingredient quality and justify premium price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Beer Market |
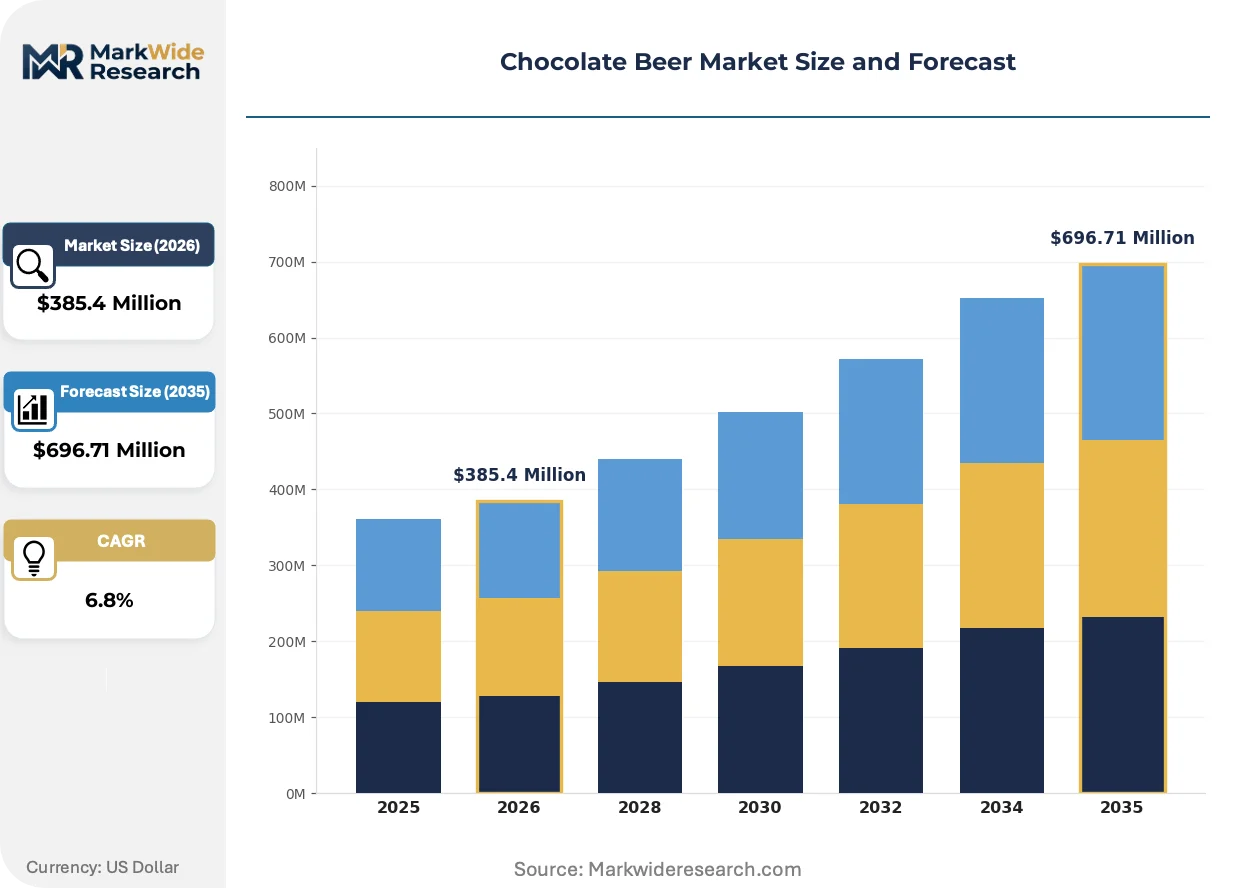
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stout, Porter, Ale, Lager, Wheat Beer, Pilsner Flavor Profile: Dark Chocolate, Milk Chocolate, Cocoa Nibs, Caramel, Coffee, Hazelnut Application: Bars & Pubs, Breweries, Restaurants, Private Events, Home Brewing, Specialty Stores Packaging Type: Bottle, Can, Keg, Growler, Multipack, Gift Box |
| Companies Covered | Sierra Nevada Brewing, Bell’s Brewery, Anheuser-Busch InBev, Omer Vander Ghinste, Deschutes Brewery, D.G. Yuengling & Sons, Stone Brewing, Dogfish Head Craft Brewery, New Belgium Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Beer Market Strategic Shifts & Innovations
Authenticity in ingredient sourcing and brewing methods is the primary theme driving innovation. Brewers are moving away from simplistic sweetness, instead focusing on expressing the nuanced terroir of specific cacao varieties through advanced fermentation and conditioning processes.
Cold-Brew Infusion Cold-brewing techniques, adapted from the coffee industry, allow for the gentle extraction of rich cocoa flavors without the harsh bitterness that can come from hot-side additions. Craft brewers are the primary adopters, using this method for their premium and limited-edition releases. This focus on nuanced flavor extraction is overtaking the previous reliance on adding processed chocolate syrups or artificial flavorings post-fermentation.
Heightened Allergen Scrutiny Regulatory frameworks like the FDA's allergen labeling rules are forcing greater discipline in production. These regulations require clear identification of ingredients derived from major allergens, which can include tree nuts if cacao is processed in shared facilities. Small and mid-sized craft breweries are most impacted, needing to invest in supply chain verification and potentially dedicated equipment to prevent cross-contamination.
A Shift Toward Provenance A consumer preference for ingredient transparency is reshaping purchasing behavior, particularly within specialty retail channels. This trend disrupts the use of generic cocoa powder, creating demand for beers that prominently feature the origin of their cacao, such as single-origin beans from Ecuador or Ghana. This focus on provenance is most visible in the taprooms and independent bottle shops of the United States and Western Europe.
Chocolate Beer Market Segmentation
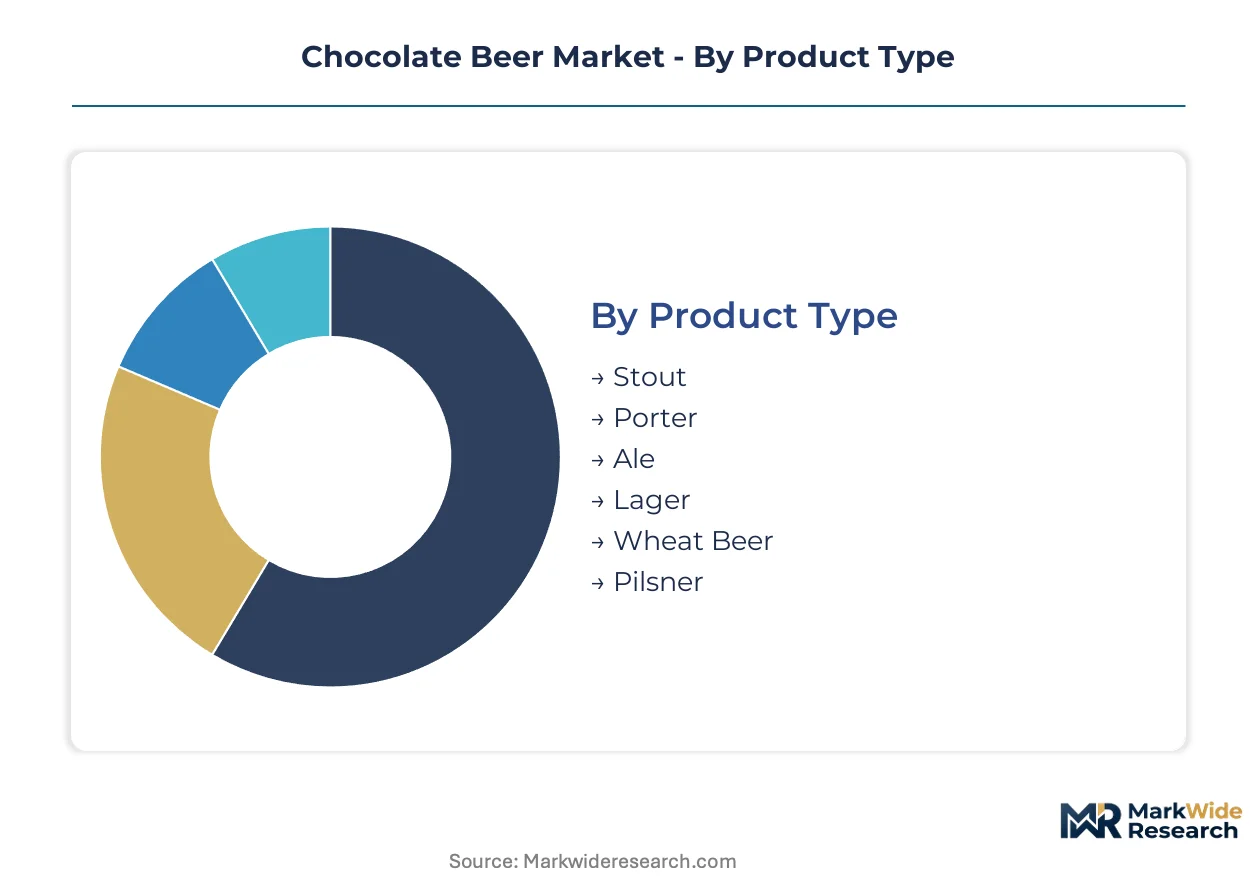
The chocolate beer market segments define distinct pathways for product development and consumer engagement. Understanding these divisions allows brewers to tailor offerings, optimize distribution, and target specific consumer preferences within this evolving beverage category. Each segment reflects unique production methods, flavor profiles, or consumption patterns.
Product Type:
Supply concentration for chocolate beer heavily favors traditional dark beer styles which naturally complement cocoa notes.
- Stout:This product type, characterized by its dark, roasted malt profile, provides a robust foundation for chocolate flavors, often featuring notes of coffee and dark chocolate. Demand concentrates in the United States, where craft brewers frequently release barrel-aged or high-gravity chocolate stouts.
- Porter:Porters offer a slightly lighter body than stouts but retain significant roasted malt character, making them excellent vehicles for cocoa infusion. This style appeals to consumers seeking a balance between richness and drinkability, particularly in established craft beer markets like the United Kingdom.
- Ale:Ales encompass a broad range of top-fermented beers, allowing for diverse chocolate beer interpretations from brown ales to stronger imperial ales.
- Lager:While less common, some brewers experiment with darker lagers to create crisp, chocolate-infused variants, appealing to a broader consumer base.
- Wheat Beer:Wheat beers, known for their fruity and spicy notes, can be blended with chocolate to create unique, often lighter-bodied, dessert-like offerings.
- Pilsner:Chocolate pilsners represent a niche segment, often featuring subtle cocoa additions to a light, refreshing base.
Today's leader: Stout. Tomorrow's challenger: Ale.
Flavor Profile:
Application of specific cacao products and flavor adjuncts drives differentiation within chocolate beer offerings.
- Dark Chocolate:This profile emphasizes bitterness and roasted notes from high-quality cacao, appealing to connoisseurs seeking sophisticated, less sweet experiences. Consumers in Western Europe frequently seek these complex, authentic chocolate expressions.
- Cocoa Nibs:Direct infusion of cocoa nibs provides authentic, nuanced chocolate flavors with earthy and fruity undertones, often without excessive sweetness. This method is gaining popularity among craft brewers for its ability to convey provenance.
- Milk Chocolate:Sweeter and creamier, milk chocolate profiles are achieved through lactose additions or specific chocolate types, targeting consumers who prefer a more indulgent and accessible taste.
- Caramel:Caramel notes, often derived from specialty malts or added flavorings, complement chocolate beers by adding sweetness and complexity.
- Coffee:The combination of coffee and chocolate flavors creates a popular synergy, often found in stouts and porters, appealing to drinkers of both beverages.
- Hazelnut:Hazelnut additions provide a nutty, rich dimension to chocolate beers, reminiscent of popular confectionery items.
Dark Chocolate represents the fastest-growing trajectory, driven by consumer demand for premium ingredients. Milk Chocolate maintains a strong presence due to its broad appeal.
Application:
Customer type dictates the distribution channels and presentation of chocolate beer products.
- Specialty Stores:These retail outlets cater to craft beer enthusiasts seeking unique, limited-edition, and premium chocolate beers, often with higher price points. The United States market shows significant concentration in this channel.
- Bars & Pubs:Traditional on-premise venues offer chocolate beers on tap or in bottles, providing a social consumption experience and driving trial for new products. Urban centers across Europe are key for this application.
- Breweries:Direct sales from brewery taprooms and retail spaces allow producers to showcase their full range of chocolate beer innovations and engage directly with consumers.
- Restaurants:Upscale restaurants integrate chocolate beers into their beverage programs, often pairing them with desserts or rich main courses.
- Private Events:Chocolate beers are increasingly featured at weddings, corporate gatherings, and other private events, offering a unique beverage option.
- Home Brewing:The home brewing community actively experiments with chocolate beer recipes, contributing to ingredient demand and flavor innovation.
Specialty Stores are expanding most quickly, while Bars & Pubs maintain consistent demand.
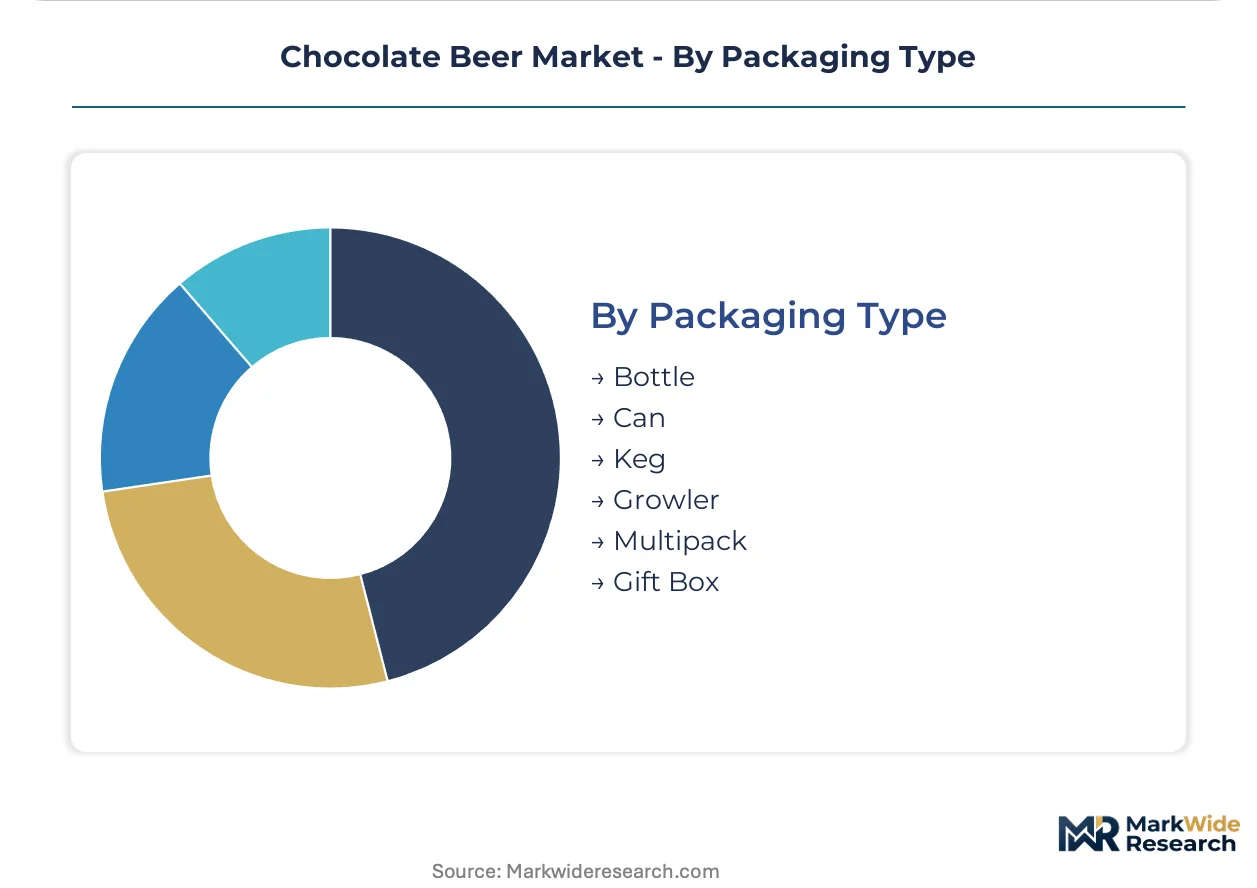
Packaging Type:
Volume considerations and consumer convenience shape the preferred packaging formats for chocolate beer.
- Bottle:Bottles remain a premium packaging choice for chocolate beers, particularly for barrel-aged or high-ABV variants, often signaling quality and collectibility. The European market frequently utilizes bottles for craft offerings.
- Can:Cans offer superior light and oxygen protection, preserving flavor integrity and providing portability, making them popular for everyday consumption and outdoor activities. Demand for canned craft beer is rising in North America.
- Keg:Kegs are essential for on-premise consumption in bars and restaurants, allowing for draft service and larger volume sales.
- Growler:Reusable growlers allow consumers to purchase fresh draft beer directly from breweries, supporting local businesses and reducing waste.
- Multipack:Multipacks offer convenience and value for consumers, encouraging larger purchases of popular chocolate beer varieties.
- Gift Box:Curated gift boxes featuring various chocolate beers target the gifting market, often containing limited-edition or specialty brews.
Bottle packaging holds the largest share, with Can packaging gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States craft brewing sector drives significant innovation in chocolate beer, with its mature ecosystem fostering diverse product development. This market expansion extends across key global regions, each contributing unique consumer preferences and regulatory landscapes. Brewers navigate varied compliance requirements and distribution channels to meet local demand.
United States
Consumer demand for high-gravity and barrel-aged chocolate stouts fuels product development across the United States. The FDA's stringent allergen labeling requirements necessitate meticulous ingredient sourcing and production protocols for brewers. Breweries in the Pacific Northwest actively pioneer experimental chocolate beer releases, attracting discerning craft enthusiasts.
United Kingdom
Established craft beer markets in the United Kingdom show growing interest in chocolate-infused porters and stouts. The Food Standards Agency provides guidance on food additive usage, influencing ingredient choices for specialty brewers. Urban taprooms in London and independent bottle shops across England serve as vital channels for new chocolate beer introductions.
Germany
Germany's deep-rooted beer traditions are gradually embracing craft chocolate beer, appealing to quality-conscious consumers. The Lebensmittel-, Bedarfsgegenstände- und Futtermittelgesetzbuch (LFGB) governs food additives, impacting formulation for specialty brews. Breweries in Bavaria, known for their traditional styles, increasingly experiment with chocolate beer variants for local markets.
Australia
Australia's adventurous consumer base drives demand for unique chocolate beer flavor profiles within its expanding craft scene. Food Standards Australia New Zealand (FSANZ) mandates clear ingredient labeling and regulates food additives for brewers. Craft breweries in Melbourne actively innovate with diverse chocolate beer styles, drawing significant interest from local enthusiasts.
Chocolate Beer Market Key Industry Players
Global majors compete with regional champions across distribution reach and product innovation within the chocolate beer market. This market exhibits a tiered structure, with large-scale producers focusing on accessible, flavored offerings and craft brewers emphasizing premiumization through unique ingredients. Strategic archetypes include mass-market producers leveraging vast networks, specialty craft innovators pushing experimental boundaries, and regional heritage breweries maintaining traditional appeal. Competitive moves involve aggressive geographic expansion and portfolio diversification to capture varied consumer preferences across segments.
At the scale-driven end, Anheuser-Busch InBev exemplifies a global brewing conglomerate leveraging extensive distribution channels for its flavored beer offerings. Craft innovators like Dogfish Head Craft Brewery occupy a distinct position, focusing on unique, often high-gravity, experimental brews that attract connoisseurs. New Belgium Brewing Company represents an established craft brewery, sustaining a strong presence in the segment with its well-known seasonal releases. These companies, alongside others such as Sierra Nevada Brewing and Bell’s Brewery, anchor different market segments, from widespread commercial availability to niche artisanal appeal. Their strategies collectively shape the market's trajectory.
| Leading Market Players |
|---|
| Sierra Nevada Brewing |
| Bell’s Brewery |
| Anheuser-Busch InBev |
| Omer Vander Ghinste |
| Deschutes Brewery |
| D.G. Yuengling & Sons |
| Stone Brewing |
| Dogfish Head Craft Brewery |
| New Belgium Brewing Company |
Cost & Logistics Intelligence
Family-owned craft breweries often drive supply behavior for premium cacao, influencing pricing discipline for specialty chocolate beers. Their focus on artisanal ingredients supports higher price points for unique flavor profiles.
Pricing Analysis
Input cost pass-through from ethically sourced cacao significantly influences chocolate beer pricing. Premium-mid-economy pricing differentiation prevails, driven by the quality grade of cacao and established craft brand premiums. Pricing softness reflects competition from other flavored beer categories in mainstream retail. Mass-market consumers exhibit higher price sensitivity, while craft connoisseurs readily pay for unique, authentic chocolate expressions.
Supply Chain Analysis
Workforce availability in cacao-producing regions like Ecuador and Ghana directly impacts the supply consistency of key raw materials. The chocolate beer supply chain draws from these regions for high-quality cacao nibs and specialty malts. Commodity price volatility for cacao presents a significant structural risk for brewers. Distribution runs through a hybrid model, combining large-scale retail for mainstream offerings with direct-to-consumer and specialty retail for craft products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chocolate beer market operates as a stable compounder, with consumer demand for authentic flavor experiences driving consistent growth. Innovation in cold-brewing techniques further supports this steady expansion.
For Market Incumbents: Extend existing distribution networks into nascent European craft beer markets to counter flavor profile competition. Deepen vertical integration into ethically sourced cacao production to secure consistent input quality. Invest in certifications for sustainable cocoa to reinforce brand trust and premium positioning. This strategy mitigates supply chain risks while expanding market penetration.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable route for market entry by bypassing traditional distribution hurdles. Target the underpenetrated non-alcoholic chocolate beer segment, appealing to health-conscious consumers. Focus on unique, experimental flavor combinations using single-origin cacao to differentiate offerings. A strong online presence and subscription models can build a loyal customer base.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized craft breweries with strong regional brand equity and proven cacao sourcing relationships. The market demonstrates long-term viability over a 5-10 year window, driven by sustained consumer demand for artisanal products. Target companies specializing in unique, ethically sourced chocolate beer variants. Growth in specialty retail channel expansion serves as a key signal for robust market penetration and future returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Cacao Sourcing Partnership | Secures consistent supply of premium, ethically sourced cacao for specialized brews. |
| Non-Alcoholic Variant Development | Captures demand from health-conscious consumers and expands consumption occasions for chocolate beer. |
| European Market Entry | Leverages established beer traditions and nascent craft chocolate beer scenes for growth. |
| Cold-Brew Infusion Technology | Enhances flavor stability and extracts nuanced cocoa notes without harsh bitterness. |
| Direct-to-Consumer Channel Expansion | Builds direct customer relationships and bypasses traditional distribution challenges for niche offerings. |
Research Approach
Direct dialogue with brewmasters, craft brewery owners, specialty retail buyers, and cacao suppliers provided primary qualitative insights. This primary research was validated through extensive secondary data analysis, including industry association reports, company annual reports, food and beverage regulatory filings, and trade publications. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Volume and value projections emerged from a robust analytical framework applied across the modeling period. The framework modeled segmentation dimensions including product type, flavor profile, application, packaging type, and regional consumption patterns. Compound Annual Growth Rates were derived from historical trend analysis and projected market dynamics. Cacao commodity prices and craft beer consumption rates served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cold-brewing infusion techniques would alter the outlook. Forecasts reflect assumptions regarding regulatory stability in food additives and consistent cacao supply. Material deviation in climate-related cacao supply shocks or significant regulatory changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
North America Alcoholic Beverages Market