
 Isoamyl Alcohol Market | 2026-2036
Isoamyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Isoamyl Alcohol Market Outlook
EU REACH chemical registration requirements is pivoting formulators toward verified supply chains for fragrance and flavor inputs. BASF leverages its integrated C4-chemistry platform to sustain cost-competitive synthetic isoamyl alcohol output across European manufacturing sites. Oxea-Chemicals anchors its position through specialized high-purity grades serving pharmaceutical solvent applications. Alfrebro differentiates via natural extraction expertise tied to fermentation-based supply streams.
Isoamyl alcohol, a branched-chain pentyl alcohol with the formula C₅H₁₂O, occurs naturally in fusel oils from alcoholic fermentation and is produced industrially through chlorination of isopentane or catalytic hydrogenation of isoamylene; it functions primarily as a solvent, flavor carrier, and chemical building block across fragrance, pharmaceutical, and industrial formulations. Synthetic isoamyl alcohol dominates volume production due to lower unit costs and consistent specification, while natural grades command premium positioning in clean-label flavoring agent applications where EU EFSA and FDA GRAS designations govern market access. The solvent application segment leads industrial offtake, though flavoring agent demand in Food & Beverage end-use channels shows the strongest structural momentum as formulators replace synthetic alternatives.
REACH registration obligations in Europe, FDA GRAS self-affirmation pathways in the United States, and China's GB food additive standards collectively shape product purity thresholds, documentation burdens, and cross-border market eligibility for isoamyl alcohol suppliers. EMA pharmaceutical excipient guidelines and ICH Q3C residual solvent specifications further constrain acceptable impurity profiles for drug-grade material, compressing the qualified supplier base. Stakeholders must monitor evolving biobased certification schemes and regional carbon accounting rules to secure position in premium natural-grade segments.
Market Dynamics
Fermentation-derived supply chains are displacing synthetic production routes as clean-label mandates from EU EFSA and FDA GRAS tighten purity documentation requirements across flavor and fragrance procurement.
Growth Catalysts
- EU REACH registration:Chemical formulators pivot toward verified supply chains, expanding demand for documented isoamyl alcohol grades in pharmaceutical solvent and fragrance applications.
- Food & Beverage clean-label pivot:Natural flavoring procurement accelerates as Asia-Pacific manufacturers reformulate to meet tightening SAMR and FSSAI additive standards.
- Jiangsu and Shandong clusters:China's fermentation infrastructure expansion serves domestic flavor houses and export markets with biobased isoamyl alcohol output.
Market Restraints
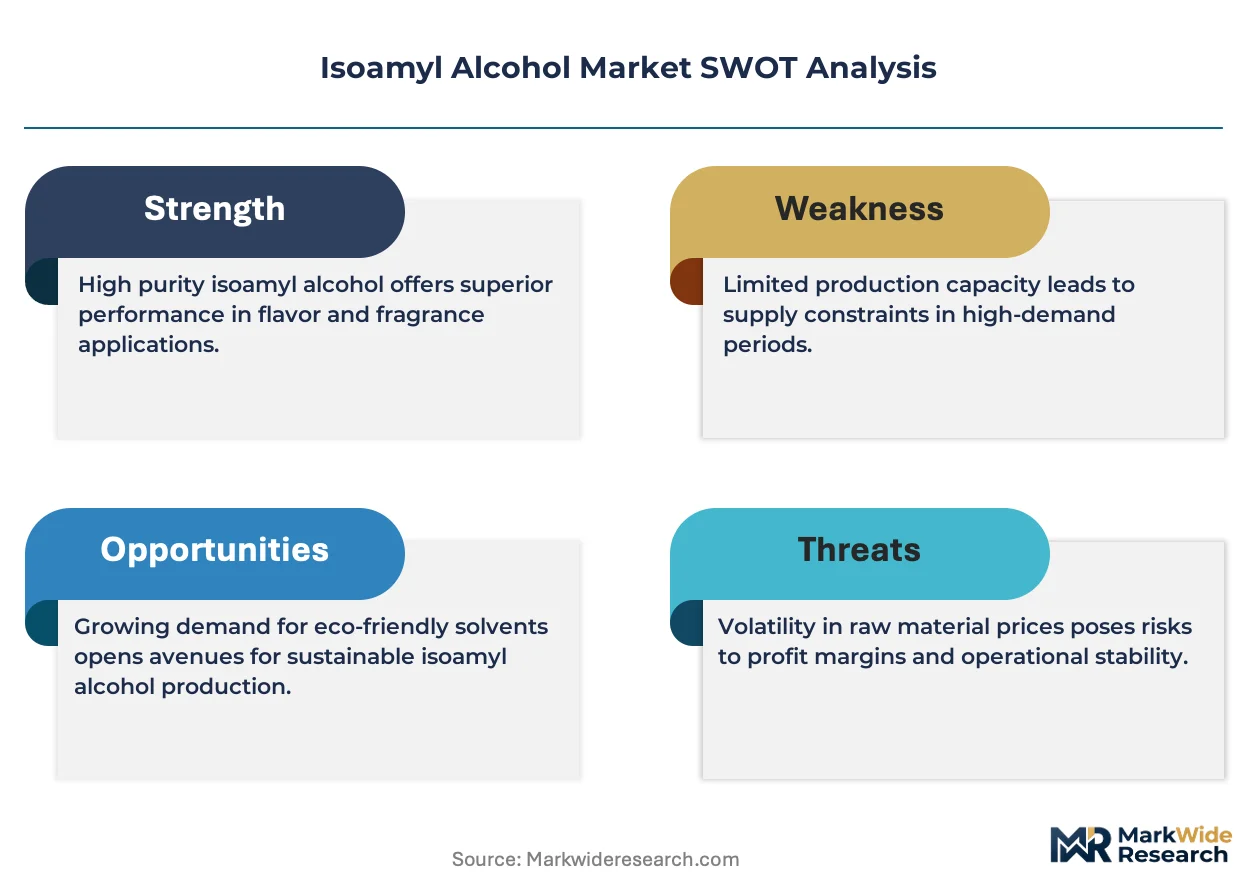
- Petrochemical feedstock volatility:Synthetic isoamyl alcohol production exposed to isopentane and isoamylene price swings, compressing margin stability for non-integrated producers.
- Supplier concentration:BASF's integrated C4-chemistry platform dominates European synthetic output, creating dependency risk for non-captive buyers.
- Natural grade yield limitations:Fermentation-based extraction from fusel oils faces batch-to-batch variability, constraining scale-up for premium clean-label segments.
Strategic Opportunities
- India FSSAI enforcement gap:Domestic natural-grade production capacity remains underdeveloped relative to labeling mandate rollout, opening local supply chain investment windows.
- Pharmaceutical excipient upgrade:EMA and ICH Q3C residual solvent specifications create demand for drug-grade high-purity material with compressed impurity profiles.
- Biobased certification convergence:EU Green Deal carbon accounting rules and emerging sustainability schemes enable premium pricing for verified fermentation-derived supply streams.
Industry Challenges
- Analytical chemistry talent scarcity:Documentation for REACH, FDA GRAS, and GB standards requires specialized regulatory affairs capacity that mid-tier suppliers struggle to staff.
- Multi-jurisdiction certification timelines:Parallel EMA excipient qualification and EFSA food additive reviews extend market entry cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoamyl Alcohol Market |
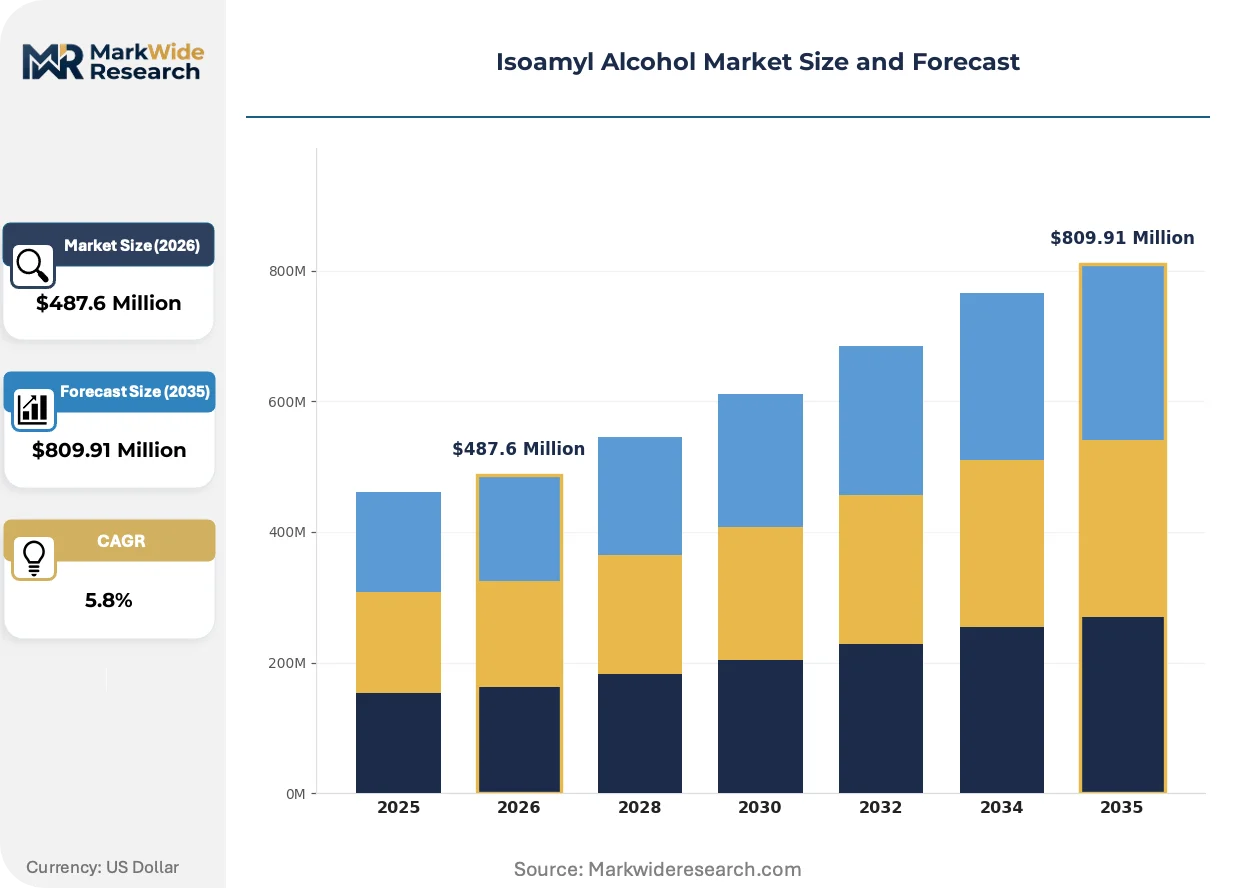
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Isoamyl Alcohol, Synthetic Isoamyl Alcohol, Blended Isoamyl Alcohol, Industrial Grade Isoamyl Alcohol End User: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals Application: Solvent, Flavoring Agent, Chemical Intermediate, Extracting Agent Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Chemoxy, Oxea-Chemicals, BASF, Kaili Chemical, Nimble Technologies, Petrom, Alfrebro, Yancheng Hongtai Bioengineering, Oxiteno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoamyl Alcohol Market Strategic Shifts
Bioprocess engineering advances are collapsing the cost gap between synthetic and fermentation-derived isoamyl alcohol, while regulatory documentation requirements reshape competitive positioning around supply chain transparency rather than unit economics alone.
Continuous fermentation technology is converging with membrane separation systems to boost natural-grade isoamyl alcohol yields from fusel oil streams. European fragrance houses and pharmaceutical formulators adopt these integrated bioprocess platforms to secure EMA-compliant supply chains. The technology is converging with carbon accounting frameworks to create defensible premium positioning against petrochemical alternatives.
China's SAMR issued revised GB standards for food additive purity in 2023, tightening heavy metal and residual solvent limits for imported and domestic isoamyl alcohol alike. Flavor houses serving the Chinese market now require third-party analytical certificates beyond traditional COA documentation. Domestic Jiangsu and Shandong producers invest in in-house GC-MS and ICP-MS capacity to preempt compliance friction.
Buyer concentration among multinational flavor and fragrance houses has compressed supplier qualification cycles from multi-year engagements to 12-18 month windows. Tier-one procurement teams now mandate blockchain-traceable supply chain documentation alongside traditional purity specifications. This pattern is most pronounced in EU and North American markets where EFSA and FDA enforcement creates liability exposure for undocumented inputs.
Isoamyl Alcohol Market Segmentation
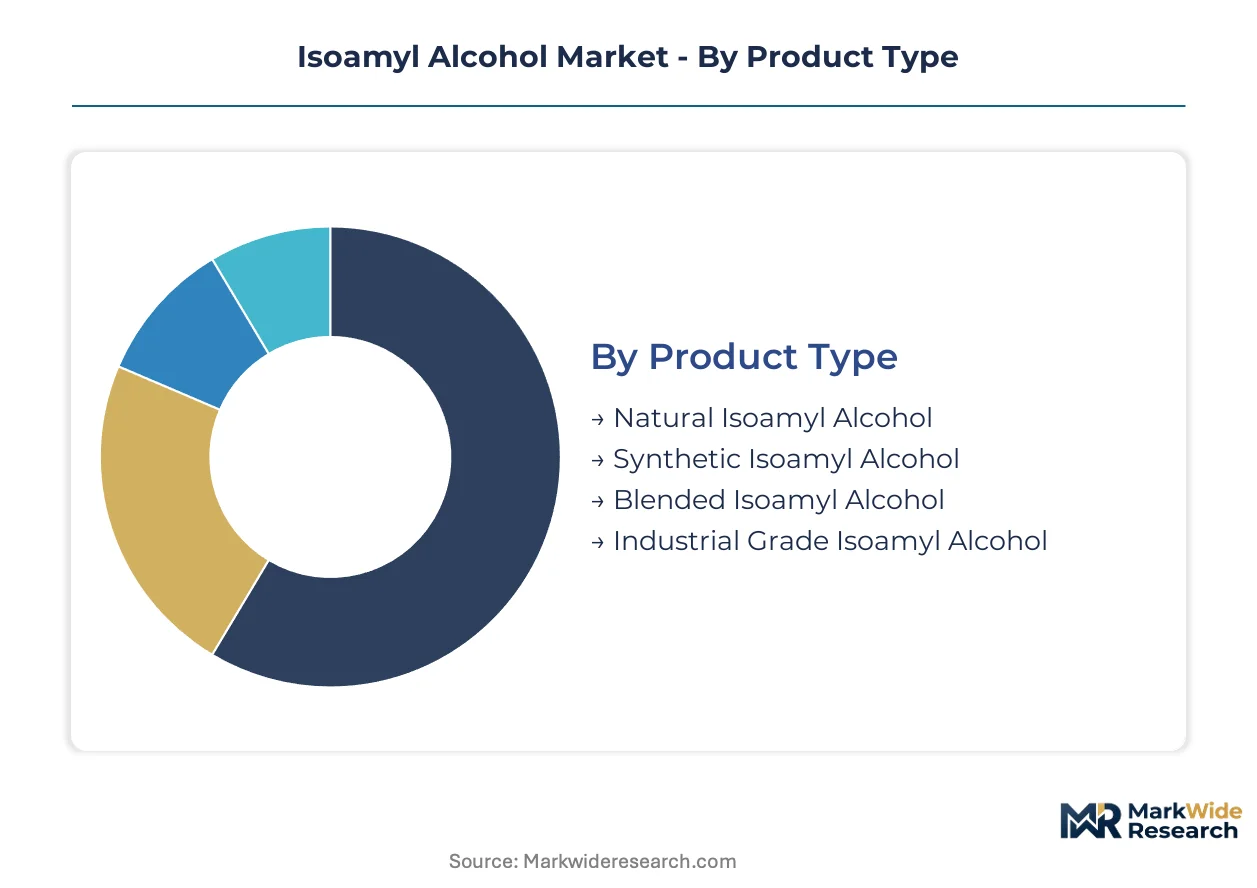
Segmentation in isoamyl alcohol markets reveals divergent margin structures between commodity synthetic grades and premium natural variants. Procurement teams across flavor houses and pharmaceutical formulators prioritize specification-grade alignment over volume pricing, fragmenting supplier qualification pathways.
Product Type:
Standardization dominates synthetic grades while natural variants require batch-specific certification documentation.
- Natural Isoamyl Alcohol:Extracted from fusel oils via fractional distillation with fermentation batch traceability required for EFSA and FDA GRAS compliance. European fragrance houses and Asia-Pacific clean-label formulators drive procurement, constrained by fusel oil feedstock availability and yield variability per fermentation run.
- Synthetic Isoamyl Alcohol:Manufactured through isopentane chlorination or isoamylene hydrogenation with consistent C₅H₁₂O purity above 99%. BASF's Ludwigshafen and Oxea's Oberhausen sites anchor European supply, serving industrial solvent and pharmaceutical excipient markets where specification uniformity outweighs biobased claims.
- Blended Isoamyl Alcohol:Combines synthetic base stocks with natural fractions to balance cost and label positioning.
- Industrial Grade Isoamyl Alcohol:Lower purity material for coatings and cleaning formulations without food-contact certification.
Leading the category by volume: Synthetic Isoamyl Alcohol. Expanding most quickly: Natural Isoamyl Alcohol.
End User:
Margin compression in industrial chemicals contrasts with premium retention in regulated pharmaceutical and food-contact applications.
- Pharmaceuticals:Drug-grade solvent demand follows EMA excipient guidelines and ICH Q3C residual solvent specifications, requiring sub-ppm impurity thresholds. Oxea-Chemicals and specialized high-purity refiners capture value through documented compliance packages that extend qualification cycles but lock in multi-year supply agreements.
- Food & Beverage:Natural flavoring procurement concentrates in Asia-Pacific as China's SAMR and India's FSSAI tighten additive purity mandates. Jiangsu and Shandong fermentation clusters supply domestic flavor houses with GB-standard documentation for banana and pear flavor formulations.
- Cosmetics:Fragrance compounders source both natural and synthetic grades depending on EU REACH registration status and end-market positioning.
- Chemicals:Industrial solvent offtake serves coatings, adhesives, and extraction processes with price-sensitive procurement.
Highest margin capture: Pharmaceuticals. Steepest volume expansion: Food & Beverage.
Application:
Functional differentiation separates commodity solvent markets from value-retained flavor and pharmaceutical intermediates.
- Solvent:Industrial dissolution and extraction processes consume volume production, particularly in coatings and specialty chemical manufacturing where petrochemical-derived synthetic grades dominate unit economics.
- Flavoring Agent:Clean-label banana, pear, and whiskey flavor formulations require natural-grade material with full fermentation traceability. EU EFSA and FDA GRAS documentation burdens favor suppliers with integrated analytical chemistry capabilities.
- Chemical Intermediate:Building block for esterification reactions producing isoamyl acetate and other fragrance compounds.
- Extracting Agent:Selective solvent for pharmaceutical and natural product isolation processes.
Dominant by tonnage: Solvent. Gaining share fastest: Flavoring Agent.
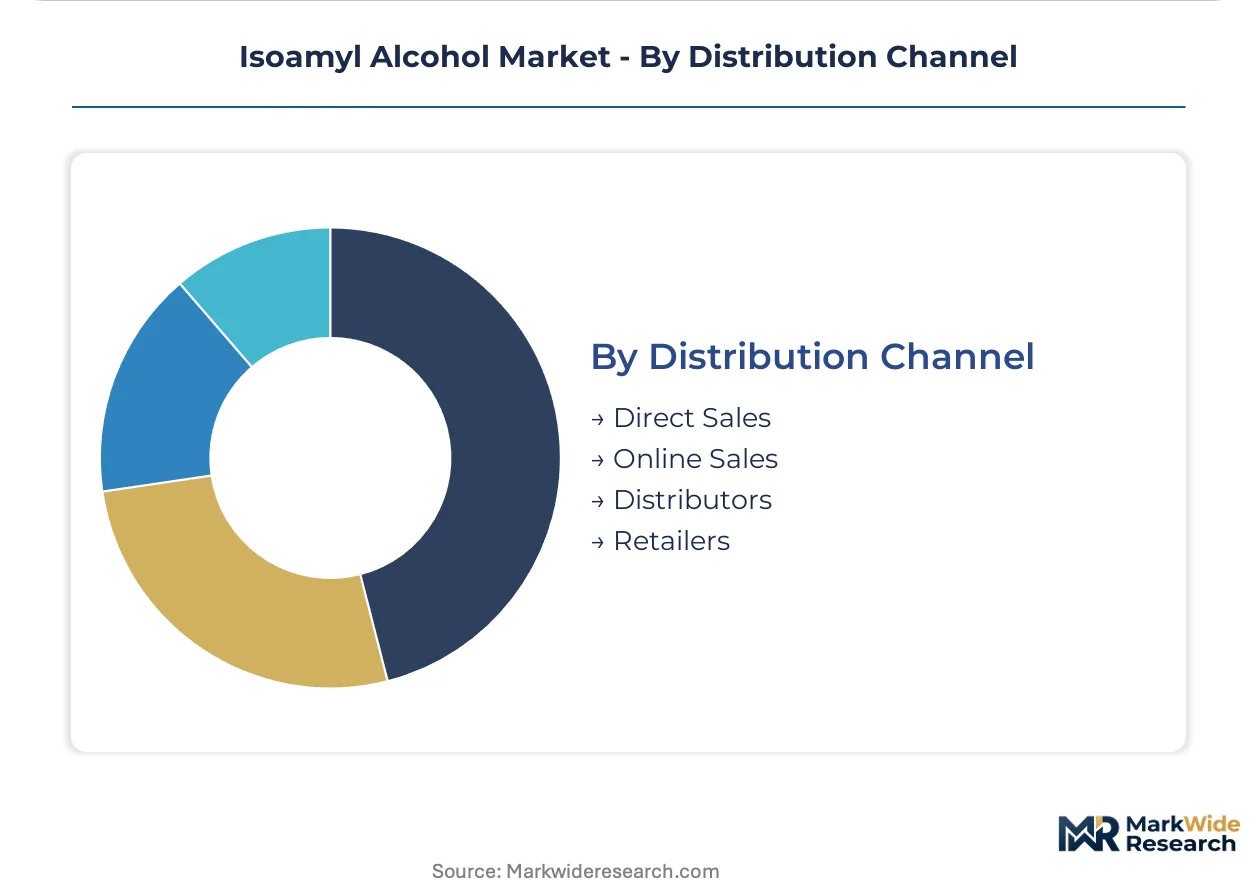
Distribution Channel:
Relationship depth varies from transactional spot purchasing to qualified supplier integration with blockchain documentation.
- Direct Sales:Multinational flavor and fragrance houses mandate direct supplier relationships with 12-18 month qualification cycles, in-house GC-MS verification, and chain-of-custody documentation.
- Distributors:Regional chemical distributors serve mid-tier pharmaceutical and industrial accounts with stocked inventory and technical support.
- Online Sales:E-procurement platforms gain traction for standardized industrial grades with published specifications.
- Retailers:Limited to small-volume laboratory and specialty chemical outlets.
Controlling volume flow: Direct Sales. Expanding access: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces anchor fermentation-derived isoamyl alcohol production, serving domestic flavor houses and export markets with biobased supply chains.
China
Flavor houses in Shanghai and Guangzhou drive procurement of natural-grade material for banana and pear formulations. SAMR's 2023 GB standards revision tightened heavy metal limits, forcing third-party analytical documentation. Jiangsu and Shandong chemical clusters expand in-house GC-MS and ICP-MS capacity to preempt compliance friction.
Germany
Fragrance compounders in Ludwigshafen and Leverkusen source REACH-registered grades for EU cosmetic and pharmaceutical applications. ECHA enforcement on chemical registration documentation compresses qualified supplier lists. Oberhausen and Marl industrial sites sustain synthetic output through integrated C4-chemistry platforms.
United States
Pharmaceutical formulators in New Jersey and North Carolina demand drug-grade solvents meeting ICH Q3C residual solvent specifications. FDA GRAS self-affirmation pathways govern natural-grade market access for flavor applications. Houston and Baton Rouge petrochemical corridors supply synthetic feedstocks for industrial solvent markets.
India
Food manufacturers in Mumbai and Delhi-NCR accelerate natural flavoring procurement ahead of FSSAI labeling mandate enforcement. Domestic natural-grade production capacity remains underdeveloped relative to regulatory rollout timelines. Gujarat and Maharashtra chemical zones attract investment for fermentation infrastructure expansion.
Brazil
São Paulo-based flavor houses pivot toward clean-label formulations as ANVISA tightens food additive purity requirements. Sugar-cane ethanol fermentation infrastructure offers feedstock proximity for biobased isoamyl alcohol development. Campinas and Paulínia industrial parks host emerging specialty chemical production clusters.
Isoamyl Alcohol Market Competitive Environment
Premium-margin players sit above commodity-margin players across documentation capability and regulatory qualification depth. The vendor base stratifies into three tiers: integrated petrochemical majors with captive feedstock control, fermentation specialists with natural-grade extraction expertise, and regional distributors serving price-sensitive industrial accounts. Strategic moves concentrate on backward integration into fermentation feedstocks and geographic expansion into underpenetrated Asia-Pacific markets.
Within the integrated petrochemical tier, BASF and Oxea-Chemicals exemplify scale-driven positioning through Ludwigshafen and Oberhausen manufacturing footprints. Alfrebro occupies a position among natural extraction specialists leveraging fermentation-based supply streams for premium fragrance and flavor applications. Kaili Chemical and Yancheng Hongtai Bioengineering represent Chinese fermentation-focused producers serving domestic GB-standard markets and export channels.
| Leading Market Players |
|---|
| Chemoxy |
| Oxea-Chemicals |
| BASF |
| Kaili Chemical |
| Nimble Technologies |
| Petrom |
| Alfrebro |
| Yancheng Hongtai Bioengineering |
| Oxiteno |
| Others |
Value Chain & Pricing Dynamics
Isopentane spot pricing and isoamylene contract benchmarks cascade through synthetic isoamyl alcohol production into three distinct procurement tiers. Natural-grade fermentation output commands EFSA-documented premiums above commodity synthetic material, while industrial-grade solvent supply tracks feedstock volatility with minimal markup.
Pricing Analysis
Yield-linked pricing anchors pharmaceutical-grade contracts, where EMA excipient qualification costs amortize across multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered natural grades from synthetic industrial material and uncontracted spot purchases. Cost compression in synthetic grades is intensifying because BASF's integrated C4-chemistry platform captures feedstock margin that non-integrated producers forfeit. Industrial solvent buyers exhibit highest price sensitivity; pharmaceutical formulators accept premium positioning for documented impurity profiles.
Supply Chain Analysis
Direct-to-flavor-house channels handle multinational procurement with 12-18 month qualification cycles and blockchain documentation mandates. Manufacturing gravity centers on Germany, China, and India, with Ludwigshafen and Oberhausen anchoring European synthetic output while Jiangsu and Shandong fermentation clusters serve Asia-Pacific demand. Raw material flows draw from petrochemical isopentane streams, bioethanol fusel oil byproducts, and catalytic isoamylene hydrogenation feeds. Single-source vulnerability concentrates in BASF's European synthetic dominance, where non-captive buyers lack alternative qualified suppliers. Distribution runs through qualified direct relationships for regulated grades and regional chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around documentation-capable suppliers as multi-jurisdiction certification timelines force mid-tier players into exit or acquisition. Regulatory compliance burdens are accelerating supplier base compression.
For Market Incumbents: Hedge against fermentation yield variability by securing captive fusel oil supply agreements with Chinese bioethanol producers. Expand in-house GC-MS and ICP-MS analytical capacity to preempt EFSA and FDA GRAS documentation friction. BASF's integrated C4-chemistry platform demonstrates how feedstock control defends margin position against petrochemical price swings.
For New Entrants and Emerging Players: Capture India's underdeveloped natural-grade production capacity ahead of FSSAI labeling mandate enforcement. Gujarat and Maharashtra chemical zones offer fermentation infrastructure investment windows with proximity to Mumbai and Delhi-NCR flavor house demand. Lead with third-party analytical certification capabilities to compress buyer qualification cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European synthetic producers with REACH registration assets but stretched working capital from feedstock volatility. Long-term viability hinges on backward integration into fermentation feedstocks or pharmaceutical-grade purification capabilities. Watch for EMA excipient guideline revisions as inflection indicators for high-purity grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captures fusel oil supply security for EFSA-compliant natural-grade output. |
| In-House Analytical Chemistry Capacity Buildout | Compresses SAMR and FDA GRAS documentation cycles for flavor house buyers. |
| Pharmaceutical Excipient Qualification Investment | Locks multi-year supply agreements with EMA-guided drug formulators. |
| Geographic Expansion into Indian Production | Preempts FSSAI enforcement gaps with domestic natural-grade capacity. |
| Blockchain Supply Chain Documentation | Satisfies multinational flavor house procurement mandates for traceability. |
Study Parameters
Trade databases, ECHA registration filings, and SAMR GB standard publications formed the secondary backbone for supply-side calibration. Primary interviews with flavor house procurement directors, pharmaceutical excipient qualification managers, fermentation plant engineers, and chemical distribution channel heads validated demand-side assumptions. Bottom-up volume builds across grade tiers, end-use segments, and regional production clusters were cross-checked against top-down chemical industry consumption benchmarks.
Bottom-up modeling segmented the market by product type, application function, end-user industry, and distribution channel across the analysis window. CAGRs were derived from regression-adjusted production capacity trajectories and buyer procurement survey data. Forecast inputs incorporated EMA guideline revision timelines, FSSAI enforcement rollout patterns, and bioethanol fermentation yield improvement curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon accounting rule changes and biobased certification scheme convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Port Wine Market