
 Fortified Wine Market | 2026-2036
Fortified Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Wine Market Intelligence
Advanced temperature and yeast-strain monitoring systems for fermentation control is reconfiguring consistency in large-scale fortified wine production. E. & J. Gallo Winery leverages its extensive distribution network to reach diverse price points. Symington Family Estates Vinhos S.A. specializes in the production of premium Port wines, anchoring its brand in heritage. Pernod Ricard competes across multiple beverage categories, integrating fortified wines into its broader portfolio.
Fortified wine is a wine to which a distilled spirit, usually grape brandy, has been added. This process increases the alcohol content, typically to a range of 15% to 22% ABV, and enhances shelf stability. While Port and Sherry command significant value due to their historical and geographical indications, Marsala finds extensive use in culinary applications. The Retail channel remains dominant, but the Online channel represents the fastest-growing path to market, especially for Premium and Luxury tiers.
The European Union’s Protected Designation of Origin (PDO) rules for products like Port and Sherry set stringent production and labeling standards. In the United States, the Alcohol and Tobacco Tax and Trade Bureau (TTB) governs labeling and advertising to ensure consumer transparency. Producers must continually balance adherence to traditional production methods with evolving consumer preferences for lower-sugar and cocktail-friendly profiles.
Market Dynamics
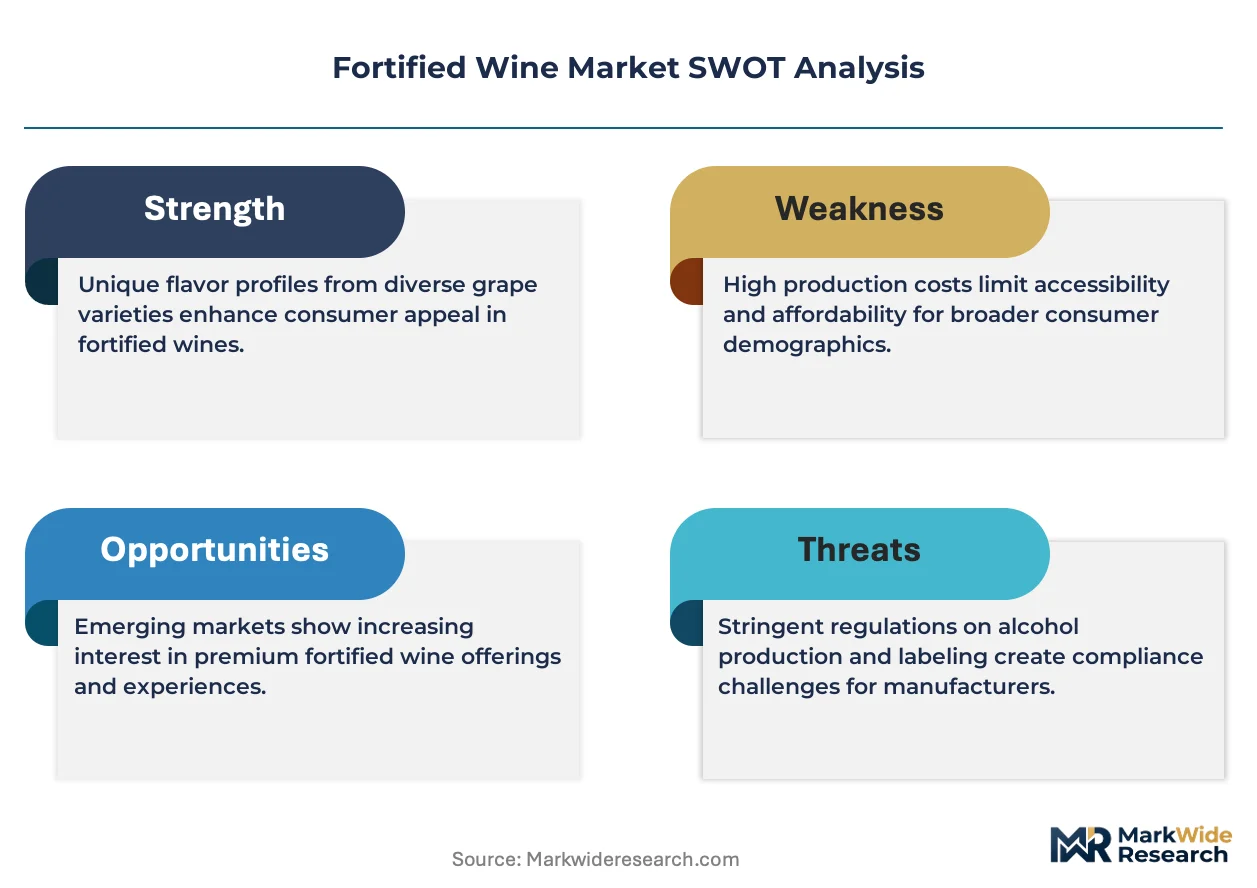
The central tension shaping the fortified wine market is the conflict between adherence to geographically protected, traditional production methods and the pull of modern consumer demand for cocktail-friendly, lower-sugar, and novel flavor profiles.
Growth Catalysts
- Protected Designation of Origin:The European Union's PDO framework for products like Port and Sherry establishes a legal guarantee of authenticity and quality, supporting premium price positioning and protecting heritage brands from imitation.
- On-Trade Channel Expansion:A resurgence in classic and craft cocktail culture, particularly within metropolitan hubs in the United States and United Kingdom, creates new applications and introduces fortified wines to a younger consumer demographic.
- Premiumization in Mature Markets:Consumers in established markets are increasingly trading up from standard to premium and super-premium fortified wines, seeking complex flavor profiles and products with verifiable provenance and age statements.
Market Restraints
- Competition from Substitutes:Fortified wines compete for share-of-occasion with a wide array of other aperitifs and digestifs, including artisanal vermouths, amari, and other botanical spirits, which often have more modern brand imaging.
- High Taxation Levels:In many key consumption markets, including the United Kingdom and Scandinavian countries, high excise duties based on alcohol content place fortified wines at a price disadvantage relative to standard table wines.
- Input Cost Pressures:The cost and availability of high-quality grape spirits for fortification are a significant restraint, as brandy production itself competes for grape supply and is subject to separate market volatilities.
Strategic Opportunities
- New Market Development:Untapped demand exists in affluent Asian markets like Japan and South Korea, where consumer interest in heritage, craftsmanship, and complex flavor profiles aligns with premium Port and Sherry offerings.
- Channel Innovation:Direct-to-consumer (DTC) sales platforms and curated subscription services offer a path to bypass crowded retail shelves, allowing producers to control branding and capture higher margins, especially for niche products.
- Low-Sugar Formulations:Developing and marketing lower-sugar or drier styles of traditional fortified wines, such as dry white Port or Fino Sherry, can attract health-conscious consumers and expand usage occasions.
Industry Challenges
- Specialized Talent Scarcity:The industry faces a shortage of oenologists and cellar masters with the specific, long-term experience required to manage complex aging systems like the solera method for Sherry or the blending of vintage Ports.
- Long Aging and Inventory Cycles:The production of premium aged fortified wines requires significant capital to be tied up in inventory for years or even decades, creating financial pressure and limiting production flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Wine Market |
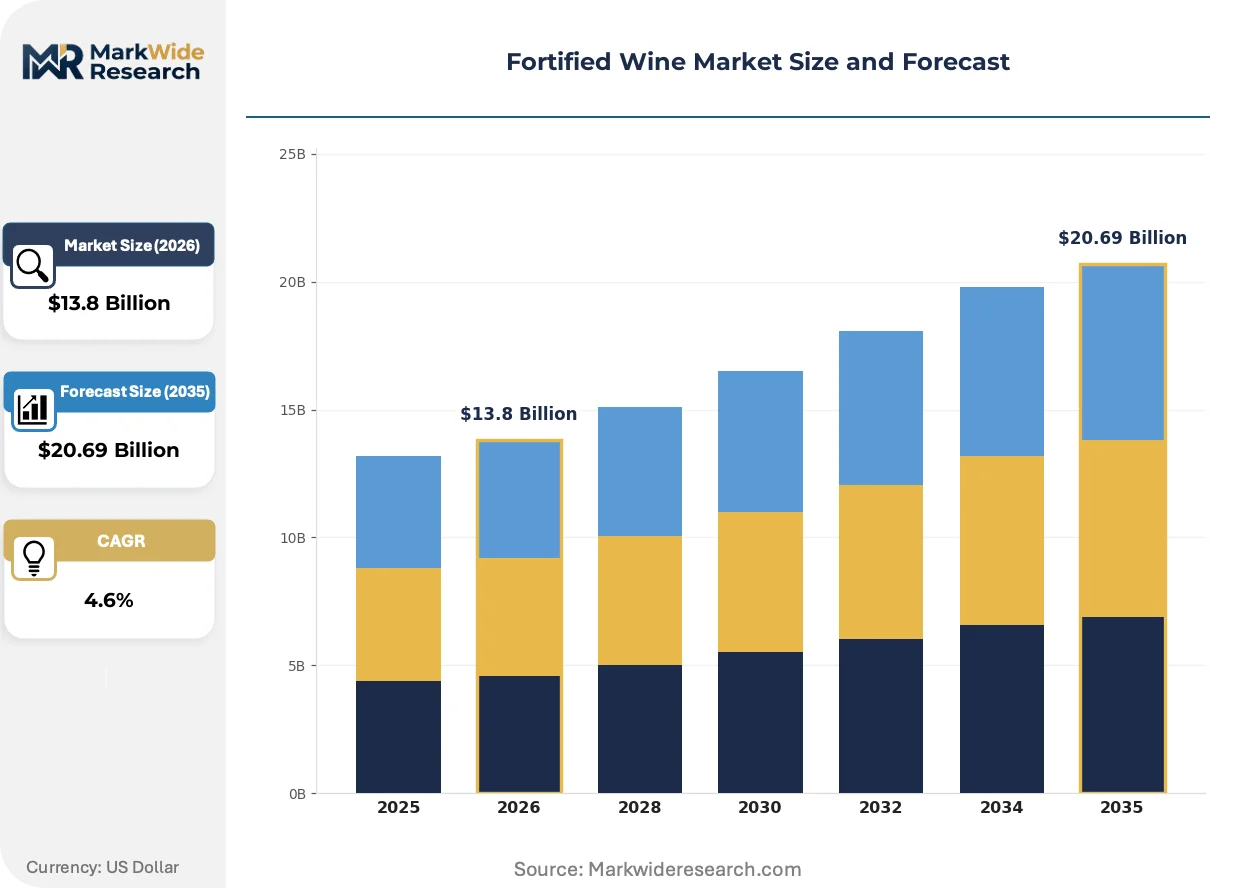
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Port, Sherry, Madeira, Marsala Production Method: Traditional, Modern, Organic, Aging Distribution Channel: Retail, Online, Wholesalers, Direct Sales Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | E. & J. Gallo Winery, Pernod Ricard, Symington Family Estates Vinhos S.A., Sogrape SGPS, S.A., Constellation Brands Inc., Caffo Group, Bacardi Limited, Emilio Lustau S.A., Kopke Group Fine Wines, SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Wine Market Strategic Shifts & Innovations
The market is defined by an intersection of technology and tradition, where data-driven production techniques are being integrated into centuries-old winemaking processes. This integration seeks to enhance consistency and appeal to modern palates without sacrificing the core identity of heritage products.
Advanced fermentation monitoring systems, incorporating real-time temperature sensors and yeast-strain analysis, provide precise control over the winemaking process. Large-scale producers are the primary adopters, seeking to replicate premium quality consistently across large batches. This technology is collapsing the perceived gap between small-batch artisanal quality and high-volume industrial output, enabling the consistent delivery of complex flavor profiles at scale.
In the United States, the Alcohol and Tobacco Tax and Trade Bureau (TTB) mandates stringent labeling rules that govern the information presented to consumers. This regulation forces all producers, both domestic and foreign, to provide clear details on origin, alcohol percentage, and class type. Importers of European products like Madeira or Marsala are most affected, as they must ensure their packaging complies with TTB standards, which can differ from EU PDO requirements.
A distinct shift in purchasing behavior shows consumers moving towards curated digital channels for discovery and acquisition. This trend disrupts the conventional multi-tier distribution model, particularly for premium and niche fortified wine segments. The movement is most visible in the United States and the United Kingdom, where online retailers and direct-to-consumer club shipments represent the fastest-growing path to market for high-value vintage and rare bottlings.
Fortified Wine Market Segmentation
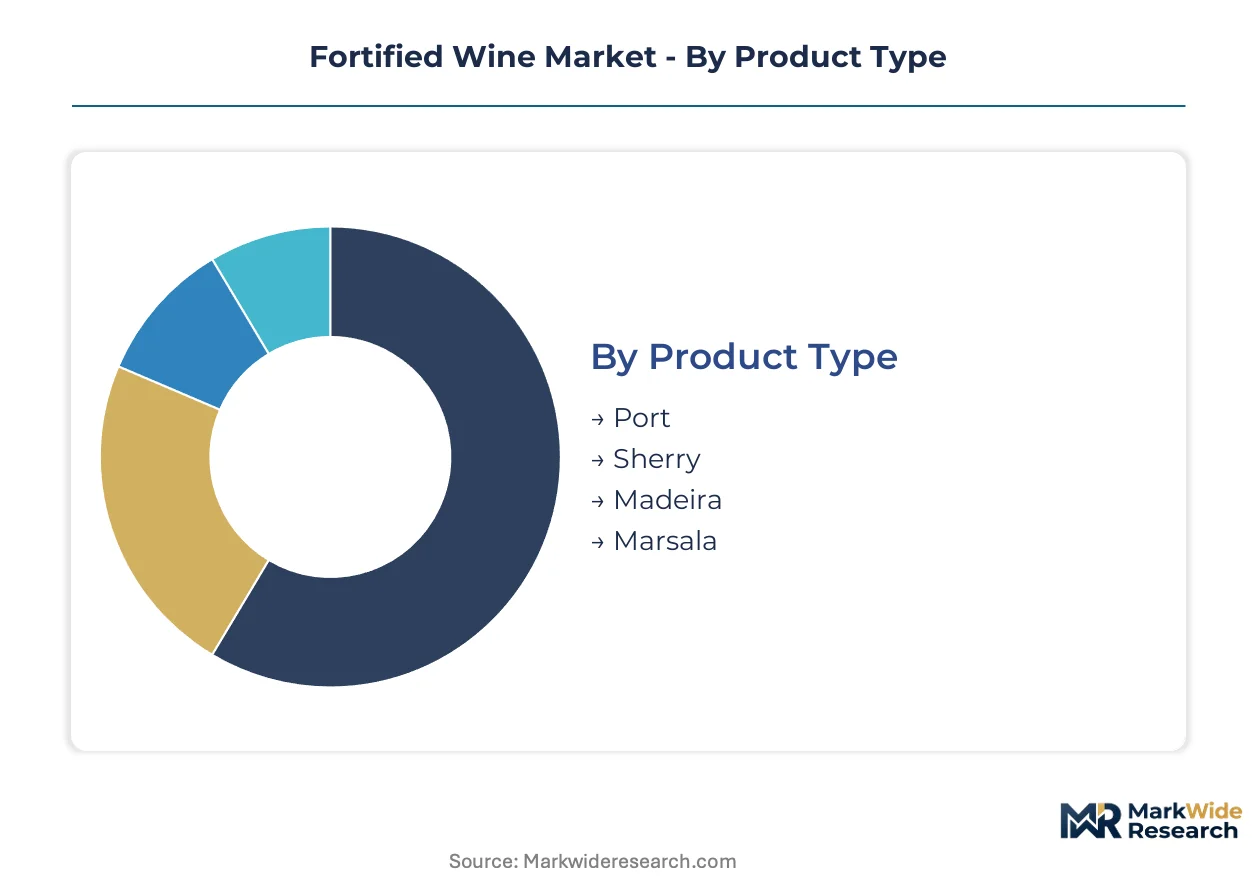
Understanding the fortified wine market's structure requires detailed segmentation across product types, production methods, distribution channels, and price tiers. This granular analysis reveals varied consumer preferences and distinct market dynamics shaping demand. Each segment presents unique opportunities and challenges for producers and distributors navigating this evolving landscape.
Product Type:
The diversity of fortified wine product types defines distinct consumption occasions and flavor profiles across global markets.
- Port:A sweet, red fortified wine primarily from the Douro Valley in Portugal, typically consumed as a dessert wine or digestif. Demand concentrates in the United Kingdom, driven by established cultural traditions and premiumization trends for aged expressions.
- Sherry:A diverse fortified wine range from Andalusia, Spain, encompassing dry (Fino, Manzanilla) to sweet (Pedro Ximénez) styles, often aged through a solera system. Its versatility in culinary applications and cocktail culture drives demand in the United States.
- Madeira:A long-lived fortified wine from the Portuguese Madeira Islands, known for its unique cooking process and high acidity, appealing to connoisseurs globally.
- Marsala:An Italian fortified wine from Sicily, widely utilized in cooking and dessert preparation, finding consistent demand in European kitchens.
Port commands the established base. The steepest expansion runs through Sherry.
Production Method:
Innovation and adherence to historical practices shape the production methods employed in fortified wine, influencing both quality and market positioning.
- Traditional:Methods adhering to centuries-old practices, often involving specific grape varietals, regional aging systems like solera, and minimal technological intervention. This approach underpins premiumization in European markets for products with Protected Designation of Origin.
- Organic:Winemaking practices that avoid synthetic pesticides, herbicides, and fertilizers, focusing on sustainable vineyard management and natural fermentation processes. Consumer demand for healthier, environmentally conscious products drives growth in Western Europe and North America.
- Modern:Incorporates advanced fermentation monitoring and temperature control systems to ensure consistency and efficiency in large-scale production, particularly for mid-range products.
- Aging:Refers to the extended maturation of fortified wines in barrels or bottles, developing complex flavors and aromas, crucial for luxury segments like Vintage Port.
The market continues to value Traditional production, while Organic methods are gaining share fastest among new consumers.
Distribution Channel:
Market access and consumer purchasing habits dictate the effectiveness of various distribution channels for fortified wines.
- Online:Digital platforms and e-commerce websites facilitate direct consumer purchases, offering wider selection and convenience, especially for premium and luxury tiers. This channel represents the fastest-growing path to market in the United States and the United Kingdom.
- Retail:Supermarkets, liquor stores, and specialist wine shops provide broad accessibility for consumers, dominating sales volume for standard and mid-range fortified wines. European markets, particularly France and Germany, show strong retail channel performance.
- Wholesalers:Intermediaries connecting producers to retail and on-trade establishments, crucial for logistics and market penetration across diverse geographies.
- Direct Sales:Producers sell directly to consumers via cellar doors, winery websites, or subscription clubs, fostering brand loyalty and higher margins for niche products.
Retail remains the dominant channel for fortified wine sales, but the Online segment exhibits robust expansion.
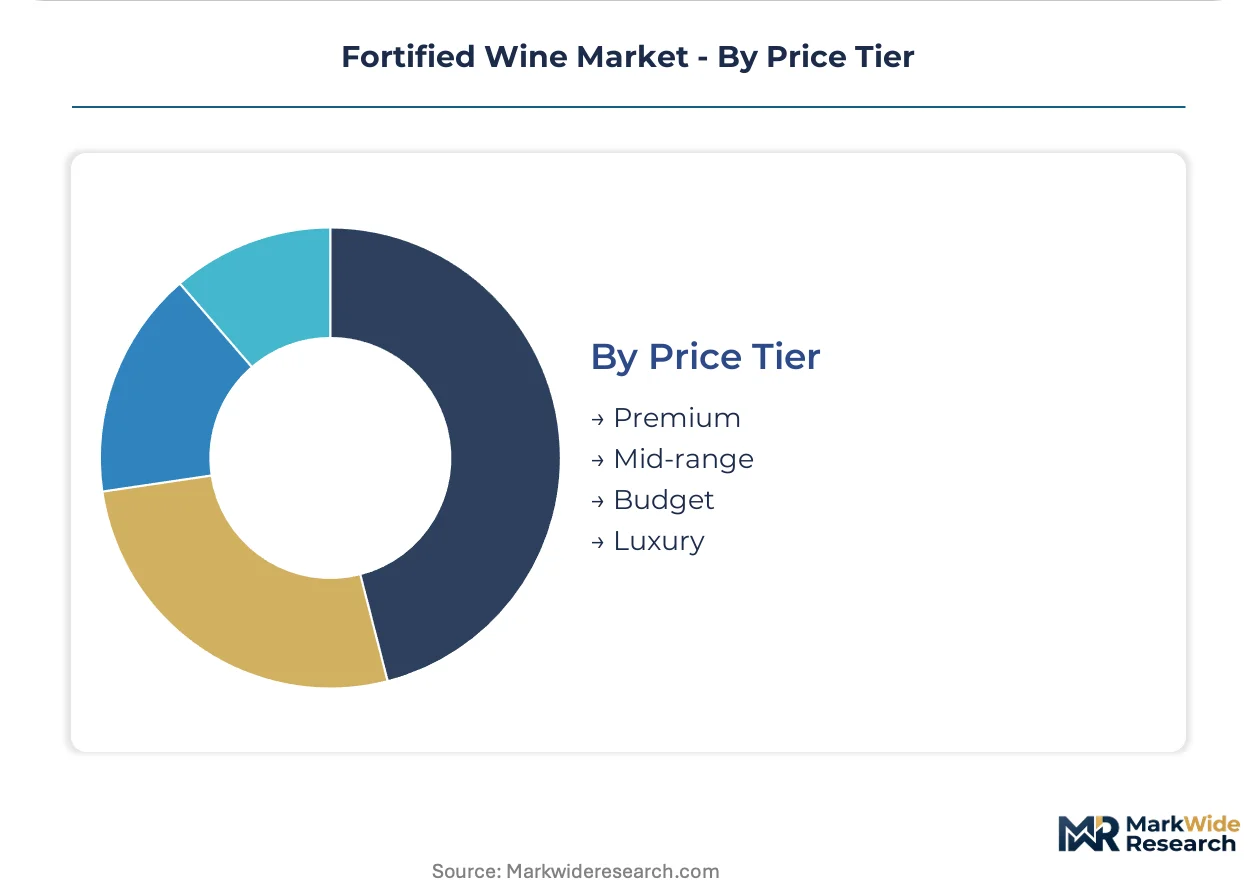
Price Tier:
Consumer expenditure patterns and perceived product value differentiate the various price tiers within the fortified wine market.
- Luxury:Fortified wines characterized by exceptional quality, rarity, extensive aging, and high price points, often linked to limited editions or specific vintages. Demand for luxury products is expanding in affluent Asian markets like Japan and South Korea.
- Premium:Products offering superior quality and distinct characteristics, often with verifiable provenance and age statements, appealing to discerning consumers willing to trade up. This tier shows significant growth in mature markets like the United Kingdom.
- Mid-range:Wines providing good quality and value, accessible to a broader consumer base for everyday consumption or gifting occasions.
- Budget:Entry-level fortified wines focused on affordability and broad availability, often used for cooking or as accessible aperitifs.
Mid-range products form the volume backbone, while Luxury offerings are experiencing the most rapid ascent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portuguese Port and Spanish Sherry exports significantly influence fortified wine consumption patterns across key global markets. This trade flow underpins demand in established European territories and emerging Asian economies. Producers navigate diverse regulatory landscapes and evolving consumer preferences.
United Kingdom
A mature consumer base and traditional consumption drive demand for fortified wines in the United Kingdom. High excise duties based on alcohol content impact pricing and competitive positioning. London's metropolitan hubs particularly contribute to cocktail culture and on-trade channel expansion.
United States
The growing cocktail culture and the versatility of Sherry in culinary applications fuel demand across the United States. The Alcohol and Tobacco Tax and Trade Bureau (TTB) mandates stringent labeling rules for all alcoholic beverages. New York and California metropolitan areas exhibit strong online channel growth for premium fortified wine offerings.
Japan
Consumer interest in heritage products, craftsmanship, and complex flavor profiles drives demand for premium fortified wines in Japan. The Ministry of Economy, Trade and Industry (METI) oversees import regulations for alcoholic beverages. Tokyo's affluent consumers show rising demand for luxury Port and Sherry selections.
Germany
Consistent retail channel performance for mid-range fortified wines and growing interest in organic production methods characterize the German market. Germany adheres to European Union (EU) food and beverage standards, including PDO rules for imported products. Major cities like Berlin and Munich contribute to stable consumption patterns and supermarket sales.
Spain
Strong domestic consumption of Sherry and growing export markets for traditional styles define the Spanish fortified wine sector. The EU's Protected Designation of Origin (PDO) framework strictly governs Sherry production and labeling within the region. Andalusia remains the core production region, maintaining traditional solera aging systems.
Fortified Wine Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing heritage brands, large-scale beverage conglomerates, and specialized artisanal producers. Large multinational players often leverage extensive distribution networks to reach diverse price points. Conversely, smaller, family-owned estates anchor their brands in heritage and premium positioning. Dominant competitive moves include strategic partnerships for market access and portfolio diversification across beverage categories.
At the scale-driven end, E. & J. Gallo Winery leverages its extensive distribution network for broad market penetration, targeting diverse price points. Multinational beverage giants, such as Pernod Ricard, integrate fortified wines into their broader portfolios, competing across multiple categories and consumer occasions. Symington Family Estates Vinhos S.A. exemplifies the heritage-focused archetype, specializing in premium Port wines and anchoring its brand in long-standing tradition and quality. These distinct operational models and market approaches collectively shape the industry's competitive dynamics.
| Leading Market Players |
|---|
| E. & J. Gallo Winery |
| Pernod Ricard |
| Symington Family Estates Vinhos S.A. |
| Sogrape SGPS, S.A. |
| Constellation Brands Inc. |
| Caffo Group |
| Bacardi Limited |
| Emilio Lustau S.A. |
| Kopke Group Fine Wines, SA |
| Others |
Cost & Logistics Intelligence
Input cost volatility for grape spirits significantly determines pricing tier spreads and shapes the fortified wine supply chain. This raw material's market fluctuations directly impact producer margins and sourcing strategies across all segments.
Pricing Analysis
Traditional production methods versus modern consistency-driven techniques create distinct pricing tiers in the fortified wine market. Value-based pricing, with significant brand premium for heritage products, dominates the market structure. Price differentiation stems from quality grade, verifiable provenance, and brand reputation. High taxation levels in key consumption markets exert pricing pressure on mid-range and budget offerings, while luxury segment consumers exhibit the least price sensitivity.
Supply Chain Analysis
Single-source vulnerability due to Protected Designation of Origin regulations dominates the fortified wine supply chain. Production concentrates heavily in Portugal for Port and Spain for Sherry, relying on high-quality grape spirits and specific regional grape varietals. This creates a reliance on a few key regions and inputs. A multi-tier distribution model, involving wholesalers and retailers, handles the majority of volume, while direct-to-consumer online channels serve premium niche products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fortified wine market is experiencing an early-cycle expansion story, driven by renewed consumer interest in cocktail culture. This tailwind creates opportunities for product innovation and market penetration in new demographics.
For Market Incumbents:Entrench existing market leadership by reinforcing Protected Designation of Origin status for heritage brands. Diversify product portfolios to include lower-sugar and cocktail-friendly profiles, addressing the threat from artisanal vermouths and modern aperitifs. Strengthen on-trade channel control, particularly in metropolitan hubs, to maintain visibility and consumer engagement. Strategic R&D into innovative flavor combinations can broaden appeal without sacrificing traditional identity.
For New Entrants and Emerging Players:Untapped demand in affluent Asian markets like Japan and South Korea offers a significant entry point for new fortified wine brands. Target younger consumers through cocktail-friendly formulations and innovative branding, especially in urban centers. Curated subscription services and direct-to-consumer platforms provide a path to market for unique small-batch or organic offerings. Focus on digital engagement to build brand awareness and bypass traditional retail gatekeepers.
For Investors and Strategic Acquirers:Updates to the European Union’s PDO framework reshapes the acquisition landscape for fortified wine producers. The market demonstrates long-term viability, driven by premiumization trends and heritage appeal over the next 5-10 years. Target heritage brands with strong Protected Designation of Origin status or tech-enabled direct-to-consumer platforms. Watch for further expansion of TTB's labeling requirements in the United States as a signal of regulatory shifts impacting market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification | Attracts health-conscious consumers and expands usage occasions beyond traditional digestifs. |
| Digital Channel Investment | Captures higher margins and reaches premium consumers in fast-growing online segments. |
| PDO Reinforcement | Safeguards authenticity, commands premium pricing, and defends against imitation products. |
| Emerging Market Entry | Taps into new consumer bases with high purchasing power and interest in luxury goods. |
| Production Technology Upgrade | Ensures consistent quality across large batches and optimizes resource utilization for efficiency. |
Research Approach
Desk research of regulatory filings, trade association reports, and company financial statements preceded structured interviews with oenologists, cellar masters, brand managers, and retail buyers. This approach combined primary insights with secondary validation, ensuring comprehensive data collection. Bottom-up data aggregation from granular segments was triangulated with top-down market sizing estimates.
Assumptions regarding stable regulatory environments and consistent raw material availability were held fixed, while consumer preference shifts and channel evolution were varied. The analytical framework projected market growth across the analysis window, segmenting by product type, production method, distribution channel, and price tier. Compound Annual Growth Rates were derived from regression analysis and expert consensus. Grape harvest yields and consumer cocktail consumption trends served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large beverage conglomerates or new artisanal producers would shift outcomes. Forecasts reflect assumptions regarding economic stability and current trade policies, though unforeseen changes in excise duties or severe climate events impacting grape supply could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Brewers Spent Grain Market