
 Commercial Wine Dispenser Market | 2026-2036
Commercial Wine Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Wine Dispenser Market Outlook
Multi-source component procurement is expanding across the commercial wine dispenser supply chain as manufacturers diversify beyond single-region electronics and compressor sourcing. Napa Technology leverages in-house thermal engineering to sustain premium positioning in temperature-controlled units. Enomatic competes through proprietary argon-preservation technology that extends open-bottle shelf life. Berg Company anchors its North American footprint with region-specific service networks for countertop and floor-standing installations.
A commercial wine dispenser is a refrigerated, pressurized serving system that maintains wine at precise temperatures while preventing oxidation through inert gas displacement, typically using nitrogen or argon injection at 3-5 psi. These systems serve the hospitality industry's need to serve wine by-the-glass without spoilage, reducing waste from opened bottles. Wall-mounted units dominate space-constrained urban wine bars where floor space commands premium lease rates, while automated pouring technology captures the fastest expansion as labor costs reshape front-of-house staffing models. Tabletop systems occupy a mature niche in hotel minibars and private dining rooms where discrete service outweighs throughput requirements.
The U.S. Food and Drug Administration governs food-contact materials in dispenser tubing and seals, while the EPA's SNAP program regulates refrigerant selections that constrain compressor technology choices. The EU F-Gas Regulation phases down hydrofluorocarbon use, forcing European-market redesigns toward natural refrigerant architectures. California's Title 24 building efficiency standards add state-level energy consumption thresholds that filter equipment eligibility for commercial rebates. Stakeholders must monitor evolving refrigerant compliance timelines and energy-labeling harmonization between North American and European certification frameworks to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
The commercial wine dispenser market is restructuring around refrigerant compliance timelines that compress product development cycles while simultaneously fragmenting supplier bases across three continents.
Growth Catalysts
- California Title 24 rebates:Energy efficiency thresholds for commercial kitchen equipment accelerate replacement cycles in Napa Valley tasting rooms and urban wine bars.
- Argon preservation systems:Inert gas injection technology at 3-5 psi extends open-bottle shelf life, reducing per-glass waste costs for fine-dining operators.
- Labor cost pressures:Front-of-house staffing model changes in North American hospitality drive automated pouring adoption for consistent portion control.
Market Restraints
- Copper and aluminum price volatility:Compressor coil and heat exchanger materials expose manufacturers to commodity swings that compress margin buffers.
- Single-source electronics concentration:Control board and sensor procurement from concentrated Asian supply nodes creates disruption vulnerability.
- EU F-Gas phase-down:Hydrofluorocarbon refrigerant restrictions force European-market redesigns toward natural refrigerant architectures with unproven field reliability.
Strategic Opportunities
- Hotel minibar retrofit:Discrete tabletop systems penetrate luxury hospitality segments where space constraints and silent operation outweigh throughput requirements.
- US Inflation Reduction Act commercial rebates:Energy-efficient equipment tax incentives lower effective acquisition costs for independent restaurant operators.
- IoT-enabled remote diagnostics:Predictive maintenance convergence with cloud analytics creates recurring revenue streams for service-contract bundling.
Industry Challenges
- Cross-border refrigerant certification timelines:Divergent EPA SNAP and EU F-Gas compliance windows strand inventory in distribution channels.
- Thermal engineering talent scarcity:Specialized refrigeration system design expertise concentrates with legacy manufacturers, constraining new entrant scale-up.
- Legacy POS integration friction:Automated pouring systems require API development for property-management and point-of-sale compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Wine Dispenser Market |
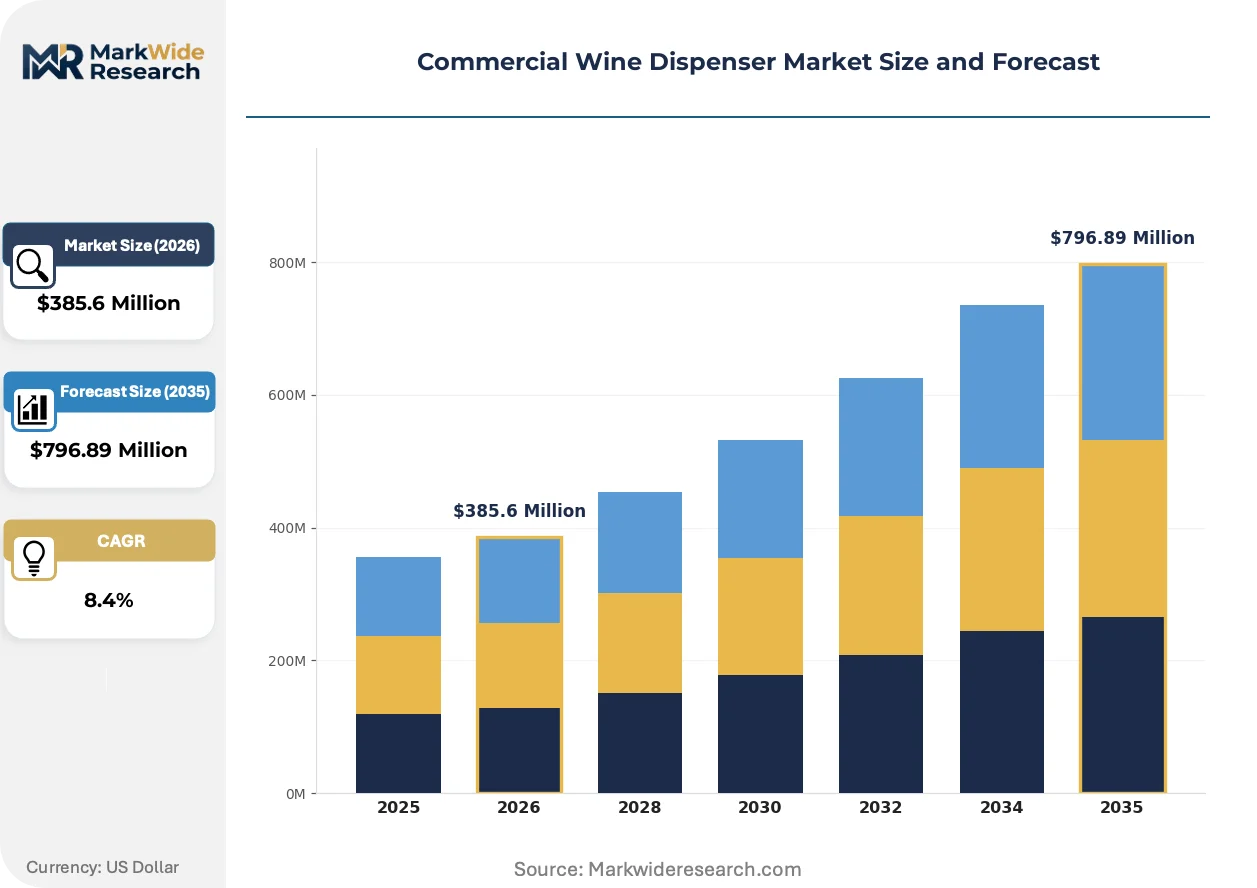
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Units, Countertop Dispensers, Tabletop Systems, Floor-Standing Machines End User: Restaurants, Wine Bars, Hotels, Event Venues Technology: Weighted Dispensers, Flow Control Systems, Automated Pouring, Manual Dispensing Distribution Channel: Online Retailers, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Napa Technology, Enomatic, Rosseto Serving Solutions, Berg Company, The Godrej Group, Lancer Beer Systems, WineEmotion, Vinotemp, Cornelius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Wine Dispenser Market Strategic Shifts
Dispenser architecture is fragmenting into configurable subsystems that decouple thermal management from dispensing mechanics, enabling faster customization for venue-specific footprints.
Modular compressor and cooling loop assemblies are modularizing the traditional monolithic dispenser design. Boutique hotel operators and small-format wine bars adopt these plug-and-play thermal units for rapid deployment without specialized installation crews. This architecture is modularizing the supply chain, allowing regional assemblers to compete without captive manufacturing of precision refrigeration components.
The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs that eliminate common refrigerants from new equipment. European manufacturers accelerate propane and carbon dioxide system development while navigating safety certification complexity. Wall-mounted urban installations face the tightest space constraints for natural refrigerant heat exchangers, driving compact coil innovation.
Leasing and subscription service contracts displace capital purchase models for mid-tier restaurant operators. Third-party service providers bundle equipment, maintenance, and gas supply into per-glass pricing that transfers oxidation risk away from venue owners. This shift concentrates most visibly in California's vineyard-tourism corridor where seasonal demand volatility favors operational expense treatment.
Commercial Wine Dispenser Market Segmentation
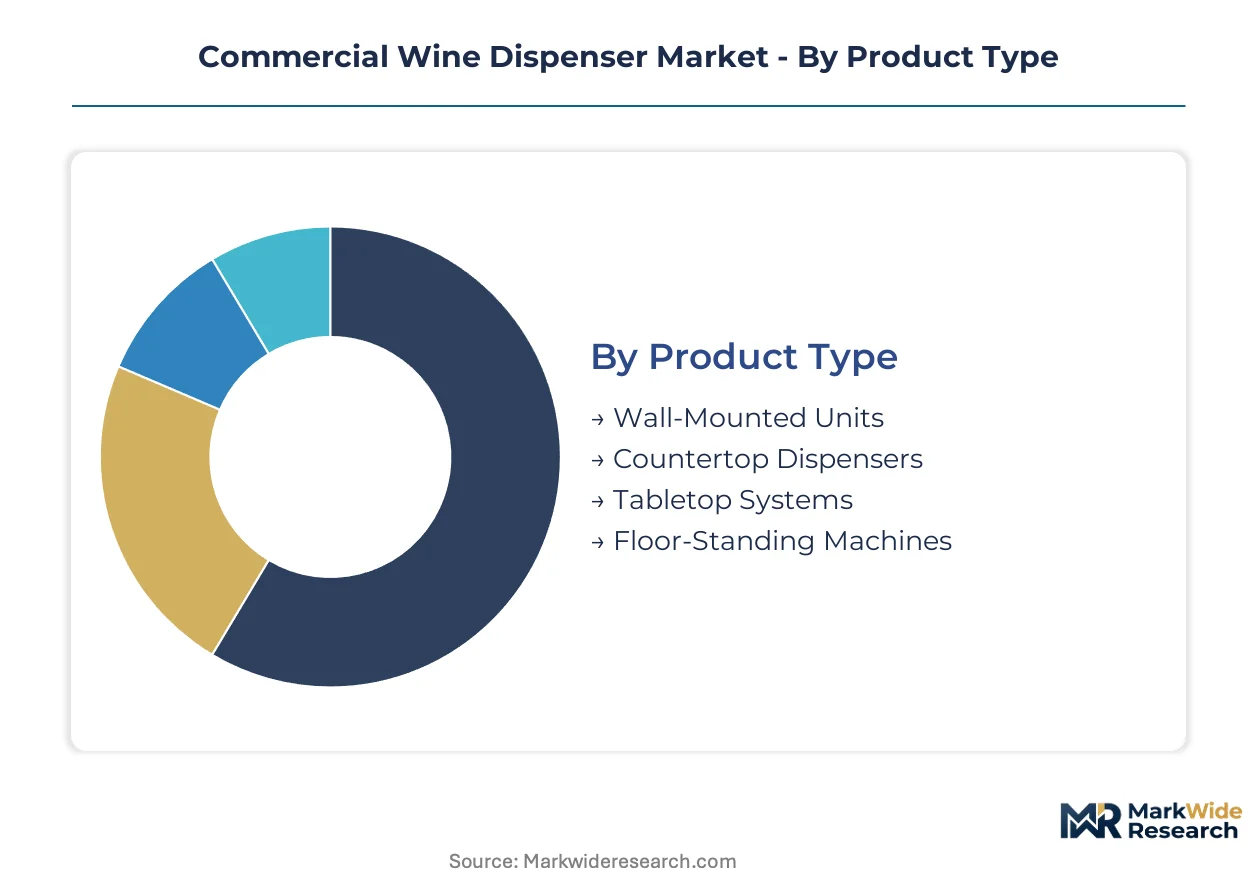
Dispenser architecture fragments across four distinct dimensions. Each category carries unique capital requirements, installation complexity, and service lifecycle economics that reshape procurement patterns for hospitality operators.
Product Type:
Capital intensity peaks with floor-standing machines requiring dedicated refrigeration infrastructure and specialized installation crews, while wall-mounted variants minimize upfront outlays.
- Wall-Mounted Units:Compact refrigeration systems with external compressor housing designed for vertical installation against bar backsplashes. Demand concentrates in Manhattan and San Francisco wine bars where lease rates exceed $85 per square foot and floor space carries premium valuations.
- Countertop Dispensers:Self-contained thermal units with integrated cooling loops and single-bottle capacity. Napa Valley tasting rooms deploy these for flexible tasting-flight configurations during peak harvest-season visitation.
- Tabletop Systems:Silent-operation units with argon canister integration for discrete hotel minibar service.
- Floor-Standing Machines:High-throughput systems with multi-bottle capacity and independent climate zones for red and white service.
Most installed capacity flows through countertop dispensers. Expansion is steepest in wall-mounted units.
End User:
Volume concentration varies sharply by service model, with fine-dining restaurants prioritizing portion precision while event venues demand rapid throughput for transient crowds.
- Restaurants:Full-service establishments requiring automated pouring integration with POS systems for inventory tracking. Michelin-starred venues in California and New York drive specification for argon-preservation systems that justify premium by-the-glass pricing.
- Wine Bars:Specialized operators with high bottle-turnover economics and staff-trained sommelier service models.
- Hotels:Luxury hospitality properties with minibar retrofit programs and private dining room installations.
- Event Venues:Conference centers and wedding facilities with seasonal demand spikes and rental-oriented procurement.
Restaurants hold the dominant installed base. Wine bars are gaining share fastest through automated pouring adoption.
Technology:
Automation intensity separates capital-light manual systems from sensor-equipped platforms requiring control board integration and software maintenance contracts.
- Automated Pouring:Solenoid valve systems with volumetric sensors and cloud-connected diagnostics enabling remote calibration. Labor cost pressures in Chicago and Boston hospitality markets accelerate deployment for consistent portion control.
- Flow Control Systems:Mechanical regulators with pressure-sensitive dispensing triggers for mid-tier operator budgets.
- Weighted Dispensers:Gravity-fed systems with bottle cradle scales for basic inventory tracking.
- Manual Dispensing:Traditional spigot and tap configurations with minimal electronics exposure.
Manual dispensing retains the largest legacy footprint. Automated pouring shows the steepest expansion trajectory.
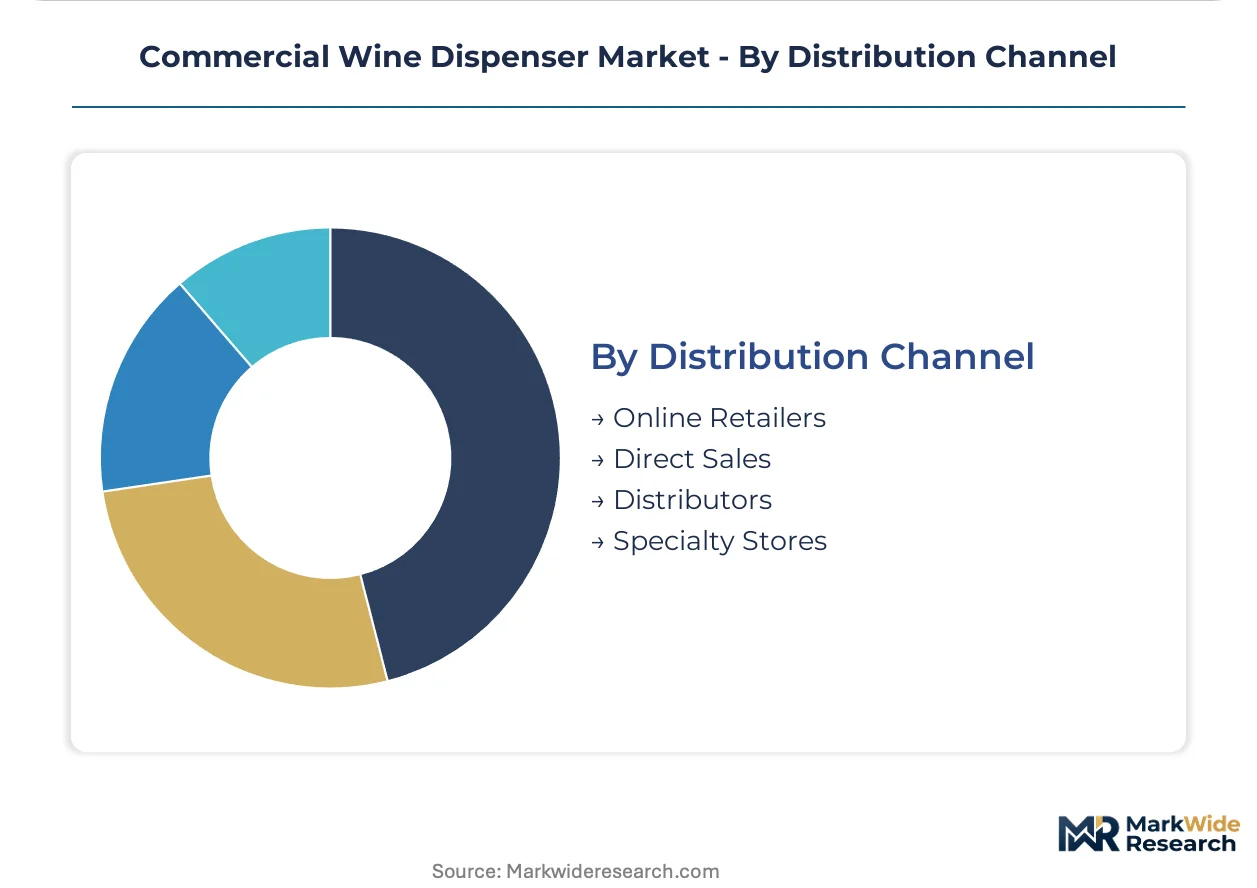
Distribution Channel:
Channel selection determines service bundling depth, with direct sales capturing complex installations while online retail serves replacement and upgrade cycles.
- Direct Sales:Manufacturer-led specification for custom installations with thermal engineering consultation and service contract integration. Berg Company and Napa Technology deploy field teams for California and New York metro deployments.
- Distributors:Regional foodservice equipment networks with local inventory and installation capability.
- Online Retailers:E-commerce platforms with standardized SKUs for countertop and tabletop replacement purchases.
- Specialty Stores:Wine industry supply boutiques with hands-on demonstration and sommelier-trained sales staff.
Distributors channel the majority of current volume. Direct sales are climbing fastest as automation complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Napa Valley's vineyard-tourism corridor generates concentrated procurement pull for high-throughput tasting-room dispensers. California's Title 24 rebates accelerate replacement cycles in urban wine bars and hospitality venues. Regulatory divergence between EPA SNAP and EU F-Gas timelines fragments cross-border inventory management.
United States
Fine-dining establishments in Manhattan and Chicago drive automated pouring adoption as labor costs reshape front-of-house staffing. The FDA governs food-contact materials in dispenser tubing while the EPA's SNAP program constrains refrigerant selections for compressor technology. Napa Valley tasting rooms deploy countertop systems for flexible harvest-season configurations.
Germany
Precision-engineered thermal systems serve Michelin-starred venues demanding consistent portion control and extended shelf-life preservation. The EU F-Gas Regulation phases down hydrofluorocarbon use, forcing redesigns toward natural refrigerant architectures. Bavarian hospitality clusters around Munich anchor demand for compact wall-mounted units in space-constrained urban wine bars.
France
Champagne houses and Bordeaux château tasting rooms prioritize argon-preservation technology for premium by-the-glass service. REACH compliance governs chemical safety in seals and tubing materials. The Île-de-France region concentrates specification activity for luxury hotel minibar retrofit programs.
Italy
Tuscan vineyard tourism and Milanese hospitality drive demand for multi-bottle floor-standing systems with independent climate zones. CE marking requirements filter equipment eligibility for commercial distribution. Piedmont's Barolo-producing estates adopt automated pouring for consistent tasting-flight execution during peak visitation periods.
United Kingdom
London's high-lease-rate wine bars favor wall-mounted dispensers minimizing floor-space consumption. The UK implements EU F-Gas Regulation requirements through domestic enforcement mechanisms. Scotland's whisky-tourism operators experiment with cross-beverage dispensing platforms adapted from wine-system architectures.
Commercial Wine Dispenser Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled diagnostics and subscription service models. The vendor base clusters around three strategic archetypes: thermal engineering specialists leveraging in-house refrigeration expertise, preservation-technology firms differentiating through gas-injection systems, and service-network operators anchoring regional installation and maintenance capabilities. Competitive moves concentrate on M&A for refrigerant compliance capabilities and strategic partnerships for POS integration APIs.
Within the thermal-specialist tier, Napa Technology and Enomatic exemplify divergent positioning approaches. Berg Company anchors North American service density through region-specific installation networks. The Godrej Group represents diversified industrial conglomerate entry from adjacent refrigeration markets. WineEmotion and Vinotemp occupy positions linking Italian manufacturing heritage with export-market hospitality specification.
| Leading Market Players |
|---|
| Napa Technology |
| Enomatic |
| Rosseto Serving Solutions |
| Berg Company |
| The Godrej Group |
| Lancer Beer Systems |
| WineEmotion |
| Vinotemp |
| Cornelius |
| Others |
Value Chain & Pricing Dynamics
Thermal engineering talent concentration in Bavaria and Northern Italy widens pricing-tier spreads, as labor-cost differentials between premium in-house refrigeration design and outsourced assembly separate subscription-service bundling from capital-equipment transactions.
Pricing Analysis
Input-cost pass-through from copper and aluminum commodity swings compresses margin buffers in mid-tier compressor manufacturing, forcing price adjustments across wall-mounted and floor-standing categories. Pricing stratifies across premium, standard, and economy tiers based on argon-preservation certification grade and after-sales service bundling depth. Cost compression in standard-tier units is intensifying because single-source electronics concentration limits supplier switching. Independent restaurant operators in secondary US metros exhibit highest price sensitivity, while Michelin-starred venues in California and New York demonstrate lowest sensitivity due to waste-reduction ROI justification.
Supply Chain Analysis
Warehouse-distribution networks for commercial wine dispensers operate through regional foodservice equipment hubs in California, Illinois, and New York before final-mile deployment to tasting rooms and urban wine bars. Manufacturing draws from China for control boards and sensors, Italy for precision thermal components, and Germany for compressor engineering. Single-source vulnerability in Asian electronics nodes creates disruption exposure for automated pouring system production. Distribution runs through manufacturer-direct specification teams for complex installations and regional distributor networks for standardized countertop replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial wine dispenser market functions as a regulatory compounder where EPA SNAP refrigerant phase-downs and EU F-Gas mandates force recurring equipment replacement cycles that sustain demand independent of hospitality expansion.
For Market Incumbents: Cement service-network density in California's Napa Valley corridor and Manhattan's high-lease-rate wine bar clusters to lock out emerging IoT-enabled competitors. Deepen backward integration into argon-preservation system manufacturing to defend margin position against commodity-driven compressor cost volatility. Prioritize API development for POS integration to reduce legacy system friction that slows automated pouring adoption. For New Entrants and Emerging Players: Regional foodservice equipment distributors represent the most accessible channel partnership for penetrating mid-tier restaurant operators outside premium coastal metros. Target hotel minibar retrofit segments where discrete tabletop specifications favor new engineering approaches over incumbent thermal legacy. Pursue subscription service models with per-glass pricing to transfer oxidation risk and bypass capital-budget constraints at independent venues. For Investors and Strategic Acquirers: Industrial refrigeration conglomerates with adjacent commercial foodservice portfolios are the most active acquirer in this space, seeking thermal engineering capabilities and regional service infrastructure. Acquisition candidates with proven natural refrigerant architectures and California Title 24 compliance pathways offer strongest long-term viability as regulatory timelines compress. Monitor EPA SNAP and EU F-Gas harmonization progress as the critical inflection signal for cross-border inventory efficiency and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Transition | Propane and CO2 system development secures EU F-Gas compliance ahead of hydrofluorocarbon phase-down deadlines. |
| IoT Diagnostics Platform | Cloud-connected predictive maintenance creates recurring revenue streams through service-contract bundling. |
| POS Integration Partnership | API development with hospitality software vendors removes friction from automated pouring adoption. |
| Regional Service Network Expansion | Field engineering density in California and New York metros accelerates specification capture for complex installations. |
| Subscription Service Model | Per-glass pricing transfers oxidation risk and converts capital expenditure to operational expense for seasonal operators. |
Study Parameters
Coverage spans North America and Europe, with primary inputs from each region combining structured interviews with thermal engineering directors, hospitality procurement managers, foodservice equipment distributors, and regulatory compliance officers with secondary validation from EPA SNAP filings, EU F-Gas regulatory databases, California Title 24 efficiency standards, and hospitality industry trade publications. Bottom-up triangulation across dispenser unit shipments and top-down reconciliation against hospitality capital expenditure surveys ensures cross-verified outputs.
Granularity-level modeling disaggregates volume and value across product type, end user, technology tier, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-specific growth trajectories calibrated against refrigerant compliance timelines and energy rebate program schedules. Forecast inputs incorporate labor cost indices for North American hospitality staffing and copper-aluminum commodity price bands for compressor manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA-EU regulatory harmonization delays and natural refrigerant field reliability data. Forecasts reflect documented assumptions around Title 24 rebate continuity and F-Gas phase-down adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market